AB 2366: Long-term care insurance.
- Session Year: 2015-2016
- House: Assembly
- Latest Version Date: 2016-09-24
Existing law provides for the regulation of long-term care insurance, as defined, and requires the Insurance Commissioner to review and approve individual and group policies, certificates, riders, and outlines of coverage. Existing law requires every long-term care policy to contain a provision that, in the event the insurer develops new benefits or benefit eligibility or new policies with new benefits or benefit eligibility not included in the previously issued policy, the insurer shall grant specified current policyholders certain rights, namely notifying the policyholders of the new benefits or benefit eligibility or new policy within 12 months and offering the new benefits or benefit eligibility to those policyholders, as specified. The insurer is required to file the notice to current policyholders with the Department of Insurance at the same time as the new policy or rider.
This bill would require the insurer to notify the policyholder of the availability of the new benefits or benefit eligibility or the new policy within 12 months of the date that the new policy series is made available for sale in this state. The bill would limit new benefits to including coverage for new long-term care services or providers that are material in nature, as specified.
Existing law provides for the regulation of long-term care insurance, as defined, and requires the Insurance Commissioner to review and approve individual and group policies, certificates, riders, and outlines of coverage. Existing law requires every long-term care policy to contain a provision that, in the event the insurer develops new benefits or benefit eligibility or new policies with new benefits or benefit eligibility not included in the previously issued policy, the insurer shall grant specified current policyholders certain rights, namely notifying the policyholders of the new benefits or benefit eligibility or new policy within 12 months and offering the new benefits or benefit eligibility to those policyholders, as specified. The insurer is required to file the notice to current policyholders with the Department of Insurance at the same time as the new policy or rider.
This bill would require the insurer to notify the policyholder of the availability of the new benefits or benefit eligibility or the new policy within 12 months of the date that the new policy series is made available for sale in this state. The bill would limit new benefits to including coverage for new long-term care services or providers that are material in nature, as specified.
Existing law provides for the regulation of long-term care insurance, as defined, and requires the Insurance Commissioner to review and approve individual and group policies, certificates, riders, and outlines of coverage. Existing law requires every long-term care policy to contain a provision that, in the event the insurer develops new benefits or benefit eligibility or new policies with new benefits or benefit eligibility not included in the previously issued policy, the insurer shall grant specified current policyholders certain rights, namely notifying the policyholders of the new benefits or benefit eligibility or new policy within 12 months and offering the new benefits or benefit eligibility to those policyholders, as specified. The insurer is required to file the notice to current policyholders with the Department of Insurance at the same time as the new policy or rider.
This bill would require the insurer to notify the policyholder of the availability of the new benefits or benefit eligibility or the new policy within 12 months of the date that the new policy series is made available for sale in this state. The bill would limit new benefits or benefit eligibility to including coverage for new long-term care services or providers that are material in nature, as specified.
Existing law provides for the regulation of long-term care insurance, as defined, and requires the Insurance Commissioner to review and approve individual and group policies, certificates, riders, and outlines of coverage. Existing law requires every long-term care policy to contain a provision that, in the event the insurer develops new benefits or benefit eligibility or new policies with new benefits or benefit eligibility not included in the previously issued policy, the insurer shall grant specified current policyholders certain rights, namely notifying the policyholders of the new benefits or benefit eligibility or new policy within 12 months and offering the new benefits or benefit eligibility to those policyholders, as specified. The insurer is required to file the notice to current policyholders with the Department of Insurance at the same time as the new policy or rider.
This bill would exempt life insurance-based combination policies that include long-term care coverage provisions from the above-described requirements. require the insurer to notify the policyholder of the availability of the new benefits or benefit eligibility or the new policy within 12 months of the date that the new policy series is made available for sale in this state. The bill would limit new benefits or benefit eligibility to including coverage for new long-term care services or providers that are material in nature, as specified.
Existing law provides for the regulation of long-term care insurance, as defined, and requires the Insurance Commissioner to review and approve individual and group policies, certificates, riders, and outlines of coverage. Existing law requires every long-term care policy to contain a provision that, in the event the insurer develops new benefits or benefit eligibility or new policies with new benefits or benefit eligibility not included in the previously issued policy, the insurer shall grant specified current policyholders certain rights, namely notifying the policyholders of the new benefits or benefit eligibility or new policy within 12 months and offering the new benefits or benefit eligibility to those policyholders, as specified. The insurer is required to file the notice to current policyholders with the Department of Insurance at the same time as the new policy or rider.
This bill would exempt life insurance-based combination policies that include long-term care coverage provisions from the above-described requirements.
This bill would make technical, nonsubstantive changes to that provision.
Existing law provides for the regulation of long-term care insurance, as defined, and requires the Insurance Commissioner to review and approve individual and group policies, certificates, riders, and outlines of coverage.
This bill would make technical, nonsubstantive changes to that provision.
(a)Each policy shall contain a provision that, if the insurer develops new benefits or benefit eligibility or new policies with new benefits or benefit eligibility not included in the previously issued policy, the insurer shall grant current holders of its policies who are not in benefit or within the elimination period all of the following rights:
(1)The insurer shall notify the policyholder of the availability of the new benefits or benefit eligibility or new policy within 12 months of the date that the new policy series is made available for sale in this state. The insurer shall file the notice with the department at the same time as the new policy or rider.
(2)The insurer shall offer the policyholder new benefits or benefit eligibility in one of the following ways:
(A)By adding a rider to the existing policy and paying a separate premium for the new benefits or benefit eligibility based on the insureds attained age. The premium for the existing policy shall remain unchanged based on the insureds age at issuance.
(B)By replacing the existing policy or certificate in accordance with Section 10234.87.
(C)By replacing the existing policy or certificate with a new policy or certificate in which case consideration for past insured status shall be recognized by setting the premium for the replacement policy or certificate at the issue age of the policy or certificate being replaced.
(b)The insured may be required to undergo new underwriting, but the underwriting can be no more restrictive than if the policyholder or certificate holder were applying for a new policy or certificate.
(c)The insurer of a group policy as defined under subdivisions (a) to (c), inclusive, of Section 10231.6 shall offer the group policyholder the opportunity to have coverage for the new benefits and provisions extended to existing certificate holders, but the insurer is relieved of the obligations imposed by this section if the holder of the group policy declines the issuers offer.
(d)For purposes of this section, new benefits means coverage for new long-term care services or providers that are material in nature. New benefits that are material in nature does not include changes to policy structure, benefits, or provisions that are minor in nature. Changes that are minor in nature include, but are not limited to, changes in elimination periods, benefit periods, and benefit amounts.
(a)Each policy shall contain a provision that, if the insurer develops new benefits or benefit eligibility or new policies with new benefits or benefit eligibility not included in the previously issued policy, the insurer shall grant current holders of its policies who are not in benefit or within the elimination period all of the following rights:
(1)The insurer shall notify the policyholder of the availability of the new benefits or benefit eligibility or new policy within 12 months of the date that the new policy series is made available for sale in this state. The insurer shall file the notice with the department at the same time as the new policy or rider.
(2)The insurer shall offer the policyholder new benefits or benefit eligibility in one of the following ways:
(A)By adding a rider to the existing policy and paying a separate premium for the new benefits or benefit eligibility based on the insureds attained age. The premium for the existing policy shall remain unchanged based on the insureds age at issuance.
(B)By replacing the existing policy or certificate in accordance with Section 10234.87.
(C)By replacing the existing policy or certificate with a new policy or certificate in which case consideration for past insured status shall be recognized by setting the premium for the replacement policy or certificate at the issue age of the policy or certificate being replaced.
(b)The insured may be required to undergo new underwriting, but the underwriting can be no more restrictive than if the policyholder or certificate holder were applying for a new policy or certificate.
(c)The insurer of a group policy as defined under subdivisions (a) to (c), inclusive, of Section 10231.6 shall offer the group policyholder the opportunity to have coverage for the new benefits and provisions extended to existing certificate holders, but the insurer is relieved of the obligations imposed by this section if the holder of the group policy declines the issuers offer.
(d)For purposes of this section, new benefits means coverage for new long-term care services or providers that are material in nature. New benefits that are material in nature does not include changes to policy structure, benefits, or provisions that are minor in nature. Changes that are minor in nature include, but are not limited to, changes in elimination periods, benefit periods, and benefit amounts.
(a)Each policy shall contain a provision that, if the insurer develops new benefits or benefit eligibility or new policies with new benefits or benefit eligibility not included in the previously issued policy, the insurer shall grant current holders of its policies who are not in benefit or within the elimination period all of the following rights:
(1)The insurer shall notify the policyholder of the availability of the new benefits or benefit eligibility or new policy within 12 months of the date that the new policy series is made available for sale in this state. The insurer shall file the notice with the department at the same time as the new policy or rider.
(2)The insurer shall offer the policyholder new benefits or benefit eligibility in one of the following ways:
(A)By adding a rider to the existing policy and paying a separate premium for the new benefits or benefit eligibility based on the insureds attained age. The premium for the existing policy shall remain unchanged based on the insureds age at issuance.
(B)By replacing the existing policy or certificate in accordance with Section 10234.87.
(C)By replacing the existing policy or certificate with a new policy or certificate in which case consideration for past insured status shall be recognized by setting the premium for the replacement policy or certificate at the issue age of the policy or certificate being replaced.
(b)The insured may be required to undergo new underwriting, but the underwriting can be no more restrictive than if the policyholder or certificate holder were applying for a new policy or certificate.
(c)The insurer of a group policy as defined under subdivisions (a) to (c), inclusive, of Section 10231.6 shall offer the group policyholder the opportunity to have coverage for the new benefits and provisions extended to existing certificate holders, but the insurer is relieved of the obligations imposed by this section if the holder of the group policy declines the issuers offer.
(d)For purposes of this section, benefits or benefit eligibility shall include new benefits means coverage for new long-term care services or providers that are material in nature and shall nature. New benefits that are material in nature does not include changes to policy structure, benefits, or provisions that are minor in nature. Changes that are minor in nature include, but are not limited to, changes in elimination periods, benefit periods, and benefit amounts.
(e)This section does not apply to life insurance policies or riders containing accelerated long-term care benefits.
(a)Each policy shall contain a provision that, if the insurer develops new benefits or benefit eligibility or new policies with new benefits or benefit eligibility not included in the previously issued policy, the insurer shall grant current holders of its policies who are not in benefit or within the elimination period all of the following rights:
(1)The insurer shall notify the policyholder of the availability of the new benefits or benefit eligibility or new policy within 12 months. months of the date that the new policy series is made available for sale in this state. The insurer shall file the notice with the department at the same time as the new policy or rider.
(2)The insurer shall offer the policyholder new benefits or benefit eligibility in one of the following ways:
(A)By adding a rider to the existing policy and paying a separate premium for the new benefits or benefit eligibility based on the insureds attained age. The premium for the existing policy shall remain unchanged based on the insureds age at issuance.
(B)By replacing the existing policy or certificate in accordance with Section 10234.87.
(C)By replacing the existing policy or certificate with a new policy or certificate in which case consideration for past insured status shall be recognized by setting the premium for the replacement policy or certificate at the issue age of the policy or certificate being replaced.
(b)The insured may be required to undergo new underwriting, but the underwriting can be no more restrictive than if the policyholder or certificate holder were applying for a new policy or certificate.
(c)The insurer of a group policy as defined under subdivisions (a) to (c), inclusive, of Section 10231.6 shall offer the group policyholder the opportunity to have coverage for the new benefits and provisions extended to existing certificate holders, but the insurer is relieved of the obligations imposed by this section if the holder of the group policy declines the issuers offer.
(d)The provision described in subdivision (a) shall not be required for life insurance-based combination policies that include long-term care coverage provisions.
(d)For purposes of this section, benefits or benefit eligibility shall include coverage for new long-term care services or providers that are material in nature and shall not include changes to policy structure, benefits, or provisions that are minor in nature. Changes that are minor in nature include, but are not limited to, changes in elimination periods, benefit periods, and benefit amounts.
(e)This section does not apply to life insurance policies or riders containing accelerated long-term care benefits.
(a)Every Each policy shall contain a provision that, in the event if the insurer develops new benefits or benefit eligibility or new policies with new benefits or benefit eligibility not included in the previously issued policy, the insurer will shall grant current holders of its policies who are not in benefit or within the elimination period all of the following rights:
(1)The policyholder will be notified insurer shall notify the policyholder of the availability of the new benefits or benefit eligibility or new policy within 12 months. The insurers notice shall be filed insurer shall file the notice with the department at the same time as the new policy or rider.
(2)The insurer shall offer the policyholder new benefits or benefit eligibility in one of the following ways:
(A)By adding a rider to the existing policy and paying a separate premium for the new benefits or benefit eligibility based on the insureds attained age. The premium for the existing policy will shall remain unchanged based on the insureds age at issuance.
(B)By replacing the existing policy or certificate in accordance with Section 10234.87.
(C)By replacing the existing policy or certificate with a new policy or certificate in which case consideration for past insured status shall be recognized by setting the premium for the replacement policy or certificate at the issue age of the policy or certificate being replaced.
(b)The insured may be required to undergo new underwriting, but the underwriting can be no more restrictive than if the policyholder or certificate holder were applying for a new policy or certificate.
(c)The insurer of a group policy as defined under subdivisions (a) to (c), inclusive, of Section 10231.6 must shall offer the group policyholder the opportunity to have the new benefits and provisions extended to existing certificate holders, but the insurer is relieved of the obligations imposed by this section if the holder of the group policy declines the issuers offer.
(d)This section shall become operative on June 30, 2003.
(d)The provision described in subdivision (a) shall not be required for life insurance-based combination policies that include long-term care coverage provisions.
SECTION 1.Section 10231.2 of the Insurance Code is amended to read:10231.2.(a)Long-term care insurance includes any insurance policy, certificate, or rider advertised, marketed, offered, solicited, or designed to provide coverage for diagnostic, preventive, therapeutic, rehabilitative, maintenance, or personal care services that are provided in a setting other than an acute care unit of a hospital. Long-term care insurance includes all products containing any of the following benefit types: coverage for institutional care including care in a nursing home, convalescent facility, extended care facility, custodial care facility, skilled nursing facility, or personal care home; home care coverage including home health care, personal care, homemaker services, hospice, or respite care; or community-based coverage including adult day care, hospice, or respite care. Long-term care insurance includes disability based long-term care policies but does not include insurance designed primarily to provide Medicare supplement or major medical expense coverage.
(b)Long-term care policies, certificates, and riders shall be regulated under this chapter. The commissioner shall review and approve individual and group policies, certificates, riders, and outlines of coverage. Other applicable laws and regulations shall also apply to long-term care insurance insofar as they do not conflict with the provisions in this chapter. Long-term care benefits designed to provide coverage of one year or more that are contained in or amended to Medicare supplement or other disability policies and certificates shall be regulated under this chapter.
(a)Long-term care insurance includes any insurance policy, certificate, or rider advertised, marketed, offered, solicited, or designed to provide coverage for diagnostic, preventive, therapeutic, rehabilitative, maintenance, or personal care services that are provided in a setting other than an acute care unit of a hospital. Long-term care insurance includes all products containing any of the following benefit types: coverage for institutional care including care in a nursing home, convalescent facility, extended care facility, custodial care facility, skilled nursing facility, or personal care home; home care coverage including home health care, personal care, homemaker services, hospice, or respite care; or community-based coverage including adult day care, hospice, or respite care. Long-term care insurance includes disability based long-term care policies but does not include insurance designed primarily to provide Medicare supplement or major medical expense coverage.
Long-term
(b)Long-term care policies, certificates, and riders shall be regulated under this chapter. The commissioner shall review and approve individual and group policies, certificates, riders, and outlines of coverage. Other applicable laws and regulations shall also apply to long-term care insurance insofar as they do not conflict with the provisions in this chapter. Long-term care benefits designed to provide coverage of 12 months one year or more that are contained in or amended to Medicare supplement or other disability policies and certificates shall be regulated under this chapter.
|
Date
|
Status
|
|---|---|
| May 19, 2016 | Referred to Com. on INS. |
| Sep 9, 2016 | Enrolled and presented to the Governor at 2:30 p.m. |
| Aug 30, 2016 | Senate amendments concurred in. To Engrossing and Enrolling. (Ayes 80. Noes 0. Page 6460.). |
| Aug 30, 2016 | Senate amendments concurred in. To Engrossing and Enrolling. |
| Aug 26, 2016 | In Assembly. Concurrence in Senate amendments pending. May be considered on or after August 28 pursuant to Assembly Rule 77. |
| Aug 25, 2016 | Read third time. Passed. Ordered to the Assembly. (Ayes 37. Noes 0. Page 5425.). |
| Aug 25, 2016 | Read third time. Passed. Ordered to the Assembly. |
| Aug 22, 2016 | Read second time. Ordered to third reading. |
| Aug 19, 2016 | Read third time and amended. Ordered to second reading. |
| Aug 2, 2016 | Read second time. Ordered to third reading. |
| Aug 1, 2016 | From committee: Be placed on second reading file pursuant to Senate Rule 28.8. |
| Jun 23, 2016 | From committee: Do pass and re-refer to Com. on APPR. (Ayes 8. Noes 0.) (June 22). Re-referred to Com. on APPR. |
| Jun 13, 2016 | From committee chair, with author's amendments: Amend, and re-refer to committee. Read second time, amended, and re-referred to Com. on INS. |
| Feb 18, 2016 | Read first time. To print. |
| May 12, 2016 | Read third time. Passed. Ordered to the Senate. (Ayes 78. Noes 0.) |
| May 12, 2016 | Read third time. Passed. Ordered to the Senate. (Ayes 78. Noes 0. Page 4788.) |
| May 12, 2016 | Read third time. Passed. Ordered to the Senate. |
| May 12, 2016 | In Senate. Read first time. To Com. on RLS. for assignment. |
| May 5, 2016 | Read second time. Ordered to Consent Calendar. |
| May 4, 2016 | From committee: Do pass. To Consent Calendar. (Ayes 20. Noes 0.) (May 4). |
| Apr 20, 2016 | From committee: Do pass and re-refer to Com. on APPR. (Ayes 6. Noes 0.) (April 19). Re-referred to Com. on APPR. |
| Apr 6, 2016 | From committee: Do pass and re-refer to Com. on AGING & L.T.C. (Ayes 13. Noes 0.) (April 6). Re-referred to Com. on AGING & L.T.C. |
| Mar 17, 2016 | Re-referred to Com. on INS. |
| Mar 16, 2016 | From committee chair, with author's amendments: Amend, and re-refer to Com. on INS. Read second time and amended. |
| Mar 14, 2016 | Referred to Coms. on INS. and AGING & L.T.C. |
| Feb 19, 2016 | From printer. May be heard in committee March 20. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Aug 30, 2016 | AB 2366 DABABNEH Concurrence in Senate Amendments | Assembly Floor |
Passed |
|
| Aug 25, 2016 | Assembly 3rd Reading AB2366 Dababneh By Gaines | Senate Floor |
Passed |
|
| Jun 22, 2016 | Do pass, but first be re-referred to the Committee on [Appropriations] | Senate Standing Committee on Insurance |
Passed |
|
| May 12, 2016 | AB 2366 DABABNEH Consent Calendar Second Day Regular Session | Assembly Floor |
Passed |
|
| May 4, 2016 | Do pass. To Consent Calendar. | Assembly Standing Committee on Appropriations |
Passed |
|
| Apr 19, 2016 | Do pass and be re-referred to the Committee on [Appropriations] | Assembly Standing Committee on Aging and Long-Term Care |
Passed |
|
| Apr 6, 2016 | Do pass and be re-referred to the Committee on [Aging and Long-Term Care] | Assembly Standing Committee on Insurance |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| American Council Of Life Insurers | ** Support | Aug 25, 2016 |
| Association Of California Life & Health Insurance Companies | * Support | Jun 22, 2016 |
| California Advocates for Nursing Home Reform | ** Against | Aug 25, 2016 |
| California Department of Insurance | ** Against | Aug 25, 2016 |
| National Association Of Insurance And Financial Advisors - California | ** Support | Aug 25, 2016 |
CONCURRENCE IN SENATE AMENDMENTS
CSA1 Bill Id:AB 2366
Author:(Dababneh)
As Amended Ver:August 19, 2016
Majority vote
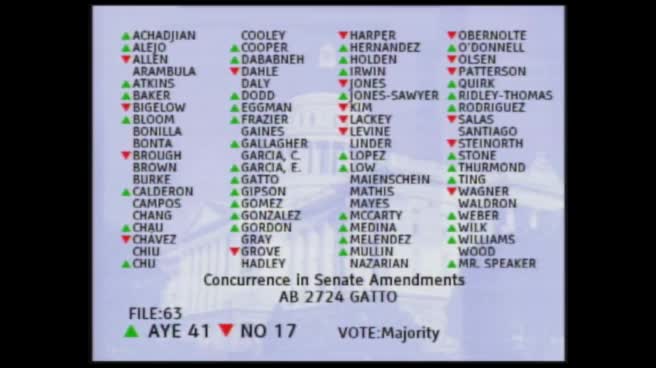
ASSEMBLY: | 78-0 | (May 12, 2016) | SENATE: | 37-0 | (August 25, 2016) |
Original Committee Reference: INS.
SUMMARY: Exempts insurers that offer a policy that combines both life and long-term care (LTC) coverages from the requirement to offer the new policy to their existing long-term care policy holders and clarifies the requirements for when LTC policy holders must be offered a new policy.
The Senate amendments clarify that an insurer must offer existing LTC policyholders any new policy that adds coverage for new LTC services or providers.
EXISTING LAW:
- Requires long-term care insurance policies to provide the policy holder with the right to be:
- Notified of any new long-term care benefit or benefit eligibility rule offered by the insurer, and
- Offered the new benefit or benefit eligibility rule by the insurer as either a replacement policy or a rider on the existing policy.
FISCAL EFFECT: According to the Assembly Appropriations Committee, the bill would have negligible fiscal impact on the Department of Insurance.
COMMENTS:
- Purpose. According to the author, the requirement to offer new LTC products to existing policyholders hinders the ability of companies to make new products available for consumers, creates a compliance debacle for new hybrid products, and can be extremely confusing or misleading to existing policyholders. The author introduced the bill to offer a simple solution to ensure that insurance consumers are offered the latest innovative insurance products, while protecting existing policyholders from being forced to review and contemplate a potentially inappropriate replacement product. In fact, a number of existing Insurance Code sections require significant protections for consumers against potential unnecessary LTC replacement sales. This modest change in the law will assist in the development of new innovative LTC products, and protect many existing policyholders from being needlessly confused by an updated offer every time a new LTC product is developed. All products an insurer offers are always available for review online, or by calling an insurance agent or representative.
- Troubled Product. Long-term care insurance is a product with a troubled history that has spawned a rigorous regulatory regime. Long-term care policies are subject to myriad regulatory controls including prior approval requirements for policies and advertisements, rate regulation, mandatory benefits, and detailed requirements governing the sale of LTC products to name a few. These elaborate controls have arisen from problems that prior LTC products have had in both product design (what services are covered and in what quantity) and pricing. Many early products suffered from the dual sins of paying for a large amount of a fairly narrow range of services (mostly institutional care) with relatively low premiums that resulted in many policyholders owning policies that didn't cover a lot of the services they needed (LTC services are increasingly provided at home and in non-institutional settings) and ever increasing premiums that are unaffordable for retirees with fixed incomes.
LTC insurance is an inherently difficult product for both consumers and insurers. It requires both the consumer and the insurer to estimate what LTC services will be needed, how long they will be needed, and when they will be needed. This is inherently difficult as it requires the consumer to answer these questions based on what their physical and financial condition will be 10, 20, or 30 years from now. That inherent problem is compounded by the rapid development of medical and other technologies that are changing the way we age and die in dramatic ways. Even if the "what" of LTC services doesn't change over that time span, we can be confident that the "how" and the cost of LTC services will be very different in 20 years.
- Combination Products. For the reasons noted above, and others, LTC insurance has been a difficult product to sell. Somewhere between 10 and 12% of adults have an LTC policy of some kind. Mostly these policies have been purchased by more affluent women who face the reality that they will need care and likely not have a spouse or partner to provide it (women have longer average life spans than men) and want to preserve some assets to pass on to their heirs. Insurers have created products that combine life insurance and LTC insurance to try and make the product appealing to a broader range of consumers. These products provide a death benefit during the policyholder's working years and the benefit converts to an LTC benefit later in life. These new products are new LTC products and therefore have triggered the requirement that they be offered to existing LTC insurance policyholders.
Insurers indicate that this is problematic because the requirement to offer new products to existing policyholders was enacted with standalone LTC insurance products in mind. Combination products (also referred to as hybrid products) have a financial structure particular to the specific type of life insurance product upon which it is based (whole life, universal life, variable life, etc.) and within each type there are different methods of allocating premiums and earnings. The diversity of products in this new market may well be at odds with the underlying requirement to offer policyholders new products as they become available.
Analysis Prepared by: Paul Riches / INS. / (916) 319-2086: FN: 0004818
Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | AB |
THIRD READING
Bill No: AB 2366
:
SENATE INSURANCE COMMITTEE: 8-0, 6/22/16
AYES: Roth, Gaines, Berryhill, Glazer, Hall, Hernandez, Mitchell, Wieckowski
NO VOTE RECORDED: Liu
SENATE APPROPRIATIONS COMMITTEE: Senate Rule 28.8
ASSEMBLY FLOOR: 78-0, 5/12/16 (Consent) - See last page for vote
SOURCE: Association of California Life and Health Insurance Companies
DIGEST: This bill exempts new benefits that are not material from requirement that long-term care insurance (LTCI) carrier offer new benefits to holders of existing policies.
Senate Floor Amendments of 8/19/16 (1) eliminate a blanket exception for the special life insurance policies and (2) limit the language describing what is not considered “material” to only new benefits.
Existing law:
- Provides for the regulation of LTCI and life insurance by the California Department of Insurance (CDI) and prescribes various requirements and conditions governing those products.
- Requires LTCI carriers to offer new policies, benefits, or benefit eligibility criteria to existing policyholders as either a replacement policy or a rider on the existing policy (“mandatory offer”).
This bill:
- Clarifies that the mandatory offer must be made within 12 months from when the new policy series is made available in this state.
- Limits the mandatory offer to only those new benefits that are material in nature and exempts benefits that are “minor in nature” including changes to elimination periods, benefit periods, and benefit amounts.
Background
LTCI policies are sold with the expectation that they will not be needed until decades later. However, the rapid evolution of care options makes it difficult for insurers and consumers to predict what services will be offered and available that far in the future. For example, many early products only covered nursing home care and those policies did not cover home care and assisted living facilities when those services became available. To address that problem, in part, insurers must make a mandatory offer of new benefits to existing policyholders as a replacement policy or rider. This provides the policyholder an opportunity to update the policy. However, concerns have been raised that consumers may be confused when offered an “upgrade” that involves insignificant or inappropriate benefits given the coverage already purchased. This bill exempts from the mandatory offer new benefits that are not material or are minor in nature and deems changes to elimination periods, benefit periods, and benefit amounts to be minor in nature.
Recent amendments removed opposition by the Department of Insurance.
FISCAL EFFECT: Appropriation: Fiscal Com.: Local:
Association of California Life and Health Insurance Companies (source)
American Council of Life Insurers
National Association of Insurance and Financial Advisors – California
OPPOSITION: (Verified 8/22/16)
California Advocates for Nursing Home Reform
ARGUMENTS IN SUPPORT: The Association of California Life and Health Insurance Companies explains that this bill offers a simple solution to help ensure that insurance consumers are offered the latest innovative insurance products, see that existing policyholders only get offered updates that make sense for the products they have, and simply protect consumers from being forced to review options that might not be in their best interest.
ARGUMENTS IN OPPOSITION: California Advocates for Nursing Home Reform argues that changes to elimination and benefit periods and benefit amounts are substantive, not minor in nature.
ASSEMBLY FLOOR: 78-0, 5/12/16
AYES: Achadjian, Alejo, Travis Allen, Arambula, Atkins, Baker, Bigelow, Bloom, Bonilla, Bonta, Brough, Brown, Calderon, Campos, Chang, Chau, Chávez, Chiu, Chu, Cooley, Cooper, Dababneh, Dahle, Daly, Dodd, Eggman, Frazier, Beth Gaines, Gallagher, Cristina Garcia, Eduardo Garcia, Gatto, Gipson, Gomez, Gonzalez, Gordon, Gray, Grove, Hadley, Harper, Roger Hernández, Holden, Irwin, Jones, Kim, Lackey, Levine, Linder, Lopez, Low, Maienschein, Mathis, Mayes, McCarty, Medina, Melendez, Mullin, Nazarian, Obernolte, O'Donnell, Olsen, Patterson, Quirk, Ridley-Thomas, Rodriguez, Salas, Santiago, Steinorth, Mark Stone, Thurmond, Ting, Wagner, Waldron, Weber, Wilk, Williams, Wood, Rendon
NO VOTE RECORDED: Burke, Jones-Sawyer
8/22/16 23:02:26
**** END ****
Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | AB |
THIRD READING
Bill No: AB 2366
:
SENATE INSURANCE COMMITTEE: 8-0, 6/22/16
AYES: Roth, Gaines, Berryhill, Glazer, Hall, Hernandez, Mitchell, Wieckowski
NO VOTE RECORDED: Liu
SENATE APPROPRIATIONS COMMITTEE: Senate Rule 28.8
ASSEMBLY FLOOR: 78-0, 5/12/16 (Consent) - See last page for vote
SOURCE: Association of California Life and Health Insurance Companies
DIGEST: This bill exempts life insurance policies that also provide coverage for long-term care services from a provision that requires insurers to offer new benefits to holders of existing long-term care insurance (LTCI) policies.
Existing law:
- Provides for the regulation of LTCI and life insurance by the California Department of Insurance (CDI) and prescribes various requirements and conditions governing those products.
- Requires LTCI carriers to offer new policies, benefits, or benefit eligibility criteria to existing policyholders as either a replacement policy or a rider on the existing policy (“mandatory offer”).
- Authorizes the Insurance Commissioner to waive the requirement under certain conditions.
This bill:
- Clarifies that the mandatory offer must be made within 12 months from when the new policy series is made available in this state.
- Limits the mandatory offer to only those changes that are material in nature and would exempt “minor” revisions such as changes to elimination periods, benefit periods, and benefit amounts.
- Exempts from the mandatory offer those life insurance policies or riders that contain “accelerated long-term care benefits” i.e. policies that pay for long-term care services out of a life insurance benefit.
Background
LTCI policies are sold with the expectation that they will not be needed until decades later. However, the rapid evolution of care options makes it difficult for insurers and consumers to predict what services will be offered and available that far in the future. For example, many early products only covered nursing home care and those policies did not cover home care and assisted living facilities when those services became available. Now, insurers must make a mandatory offer of new benefits to existing policyholders as a replacement policy or rider. This provides the insured an opportunity to update the policy.
Some life insurance products, often referred to as “hybrid” or “combination” products, pay for long-term care services out of the death benefit when the insured develops a qualifying disability. The mandatory offer applies whether or not the policy is standard LTCI or a hybrid.
Both standard and hybrid life insurance products come in a variety of forms that interact with LTCI benefits differently. Whole life policies offer a fixed death benefit, level premium, and a steadily increasing cash value. Universal life policies allow the policyholder to change the death benefit, change or skip premium payments, and have a less predictable cash value. According to the Association of California Life and Health Insurance Companies (ACLHIC), new LTCI benefits might not integrate or graft well onto an existing life policy. This bill conforms California law to the standards adopted by the National Association of Insurance Commissioners by exempting “minor” changes to covered services or providers for all LTCI policies, as well as all hybrid products.
FISCAL EFFECT: Appropriation: Fiscal Com.: Local:
Association of California Life and Health Insurance Companies (source)
American Council of Life Insurers
National Association of Insurance and Financial Advisors – California
California Department of Insurance
ARGUMENTS IN SUPPORT: ACLHIC argues that existing law impedes the development of innovative products and confuses consumers. ACLHIC suggests that it would not be appropriate to force an insurer that develops a new whole life hybrid product to offer the new LTCI features to consumers with an existing universal life hybrid product. For example, an LTCI feature designed for whole life insurance that funds additional LTCI benefits with dividends paid to the policyholder would be meaningless when attached to a universal life policy that does not pay dividends.
ARGUMENTS IN OPPOSITION: CDI argues that an exemption for LTCI attached to life insurance is not necessary given recent amendments that limit the obligation to offer new benefits that are material only. CDI further emphasizes that this exemption may be more significant since industry representatives suggest that more consumers will obtain LTCI through combination policies than through standalone policies.
ASSEMBLY FLOOR: 78-0, 5/12/16
AYES: Achadjian, Alejo, Travis Allen, Arambula, Atkins, Baker, Bigelow, Bloom, Bonilla, Bonta, Brough, Brown, Calderon, Campos, Chang, Chau, Chávez, Chiu, Chu, Cooley, Cooper, Dababneh, Dahle, Daly, Dodd, Eggman, Frazier, Beth Gaines, Gallagher, Cristina Garcia, Eduardo Garcia, Gatto, Gipson, Gomez, Gonzalez, Gordon, Gray, Grove, Hadley, Harper, Roger Hernández, Holden, Irwin, Jones, Kim, Lackey, Levine, Linder, Lopez, Low, Maienschein, Mathis, Mayes, McCarty, Medina, Melendez, Mullin, Nazarian, Obernolte, O'Donnell, Olsen, Patterson, Quirk, Ridley-Thomas, Rodriguez, Salas, Santiago, Steinorth, Mark Stone, Thurmond, Ting, Wagner, Waldron, Weber, Wilk, Williams, Wood, Rendon
NO VOTE RECORDED: Burke, Jones-Sawyer
8/3/16 19:33:36
**** END ****
SENATE COMMITTEE ON
Senator Richard Roth, Chair
2015 - 2016 Regular
Bill No: Hearing Date: June 22, 2016
Author: | |||
Version: | Amended | ||
Urgency: | Fiscal: | ||
Consultant: | |||
Subject:
SUMMARY
Exempts insurers that offer a policy which combines both life and long-term care coverages from the requirement to offer the new benefits or benefit eligibility criteria to their existing long-term care insurance (LTCI) policy.
DIGEST
Existing law
- Provides for the regulation of LTCI and life insurance by the California Department of Insurance (CDI) and prescribes various requirements and conditions governing those products.
- Requires LTCI carriers to offer new benefit or benefit eligibility criteria to existing policyholders as either a replacement policy or a rider on the existing policy.
- Authorizes the Insurance Commissioner to waive the requirement under certain conditions.
This bill
- Clarifies that the offer must be made within 12 months that the new policy series is made available in this state.
- Limits, for all LTCI policies, the requirement to offer new benefits to only those changes that are material in nature, but not to “minor” changes such as changes to elimination periods, benefit periods, and benefit amounts.
- Exempts all life insurance policies or riders that contain accelerated LTCI benefits.
COMMENTS
- Purpose of the bill According to the author, existing law requires insurers offering new LTCI policies to offer the “new” coverage to their existing LTCI policyholders whenever a new product is developed and approved for sale in the state. The offer statute was established when individual “standalone” LTCI policies were the standard, but is now being applied to “hybrid” products for policyholders where it often does not make sense. Hybrid products typically pay for LTCI expenses by accelerating the death benefit of a life insurance policy or annuity contract, while standalone LTCI products are based on premiums paid specifically for LTCI benefits. The offer requirement hinders the ability of companies to make new products available for consumers, creates a compliance debacle for new hybrid products, and can be extremely confusing or misleading to existing policyholders.
The author further states that this bill represents a modest change in the law that will assist in the development of new innovative LTCI products, as wells as protect many existing policyholders from being needlessly confused by an updated offer every time a new LTCI product is developed.
- Background LTCI is a product with a troubled history that has spawned a rigorous regulatory regime. LTCI policies are subject to a myriad of regulatory controls including prior approval requirements for policies and advertisements, rate regulation, and mandated benefits. These elaborate controls have arisen from problems that prior LTCI products have had in both product design (what services are covered and in what quantity) and pricing. Many early products only covered a narrow range of services (mostly institutional care) and did not cover needed services (LTCI services are increasingly provided at home and in non-institutional settings). Additionally, these policies were severely underpriced leading to drastically increasing premiums that have grown are unaffordable for retirees with fixed incomes. Consumers are purchasing fewer policies and carriers are leaving the market. In this year alone, two carriers have suspended sales of individual products, leaving 10 carriers actively selling individual LTCI in California.
Both LTCI consumers and insurers must anticipate service needs and options decades before claim would likely be filed. Rapid development of medical and other technologies that are changing the way we age and die in dramatic ways make needs even less predictable. Even if the "what" of services doesn't change over that time span, the "how" and the cost of LTC services will likely be very different in 20 years.
Insurers have combined life insurance and LTCI to make the product appealing to a broader range of consumers. These products offer a sort-of “two-for-one” that provides some LTCI coverage and a death benefit. Although not cheaper than an LTCI policy, they are likely less expensive than purchasing two separate policies. These new products are relatively new and have increased in popularity as concerns have grown over premium increases, regulatory challenges, and hostile markets, for LTCI.
These policies “accelerate” the death benefit when the insured develops a qualifying disability. Use of the LTCI benefit reduces the death benefit. These policies are sometimes referred to as “hybrid” products and are offered as a single package or the LTCI benefit may be offered as a rider. These contracts otherwise behave like, and are subject to most of the same Insurance Code provisions as standard LTCI policies, except they use an underlying life insurance policy to fund the benefit.
Life Insurance. In addition to a variety of LTCI benefit options, life insurance comes in a variety of forms. Whole life insurance usually remains in effect over the life of the insured. Premium payments remain level, but early payments exceed the actual cost of insurance. The extra premium builds a reserve (cash value) which helps pay for the policy in later years as the cost of protection rises.
Universal life (UL) insurance offers a flexible alternative because it allows the policyholder to change or skip premium payments or change the death benefit more easily. The policy, premium, death benefit and cash value are treated separately. Cash values are accumulated by crediting premium payments and interest to a fund from which deductions are made for the expenses and cost of insurance. Interest rates are linked to an external index such as Treasury bills. Because the cash value element of this type of policy is interest rate sensitive, predictions of future costs are highly dependent upon the accuracy of interest rate projections. Recently, some insurers have dramatically increased premiums as a result of pervasive low interest rates.
Variable life insurance anchors the value of the death benefit based on the performance of the investments underlying the policy. Variable universal life insurance combines the flexibility of universal life insurance with the investment account features of variable life insurance.
Hybrid products may have a financial structure particular to the specific type of life insurance product upon which it is based (whole life, universal life, variable life, etc.) and within each type there are different methods of allocating premiums and earnings. The LTCI benefits may be highly integrated with the underlying policy or added on, in other words the LTCI may be “built-in at the factory” or “bolted on.”
Existing law requires LTCI carriers to offer new benefits and benefit eligibility criteria to existing policyholders. This gives the policyholders an opportunity to update their policy. However, because the new LTCI benefit might not match or graft well onto the underlying life policy, forcing new benefits to a mismatched life policy may produce detrimental or nonsensical results.
Replacement Policies. Concerns have been raised that offering consumers of new LTCI benefits may invite them to purchase new benefits that may not be appropriate. Consumer protections are in place and agents and brokers must go through a special process for “replacement” policies, but these replacements are not subject to all consumer protections applicable to standard LTCI policies.
The NAIC LTCI Model Regulation. The National Association of Insurance Commissioner adopts model laws and regulations and establishes national standards. This bill would more closely conform California law to the NAIC’s LTCI model regulation.
- Support The sponsors, Association of California Life and Health Insurance Companies and the American Council for Life Insurers support this bill because they argue existing law impedes the development of innovative products and may confuse consumers. They suggest that it would not be appropriate to force an insurer that develops a new whole life—LTCI product to offer the new LTCI features to consumers with universal life insurance. As a specific example, an LTCI feature designed for whole life insurance that funds additional LTCI benefits with dividends paid to the policyholder would be meaningless when attached to a universal life policy that does not pay dividends.
- Concerns California Health Advocates (CHA) has not taken a formal position on the bill, but expresses concerns about exempting hybrid policies. CHA writes that the insurance sold to cover long-term care costs has changed dramatically over the last few decades. The baby boom generation has changed every institution it has passed through – from schools to employment. LTCI policies will inevitably change as well. Given that there has been a shift from traditional LTCI to combination products, CHA believes that the offer of new benefits or benefit eligibility is a necessary consumer protection.
- Questions
- How frequently do consumers elect to purchase the new benefits when offered for all types of LTCI coverage?
- How many hybrid products have been approved that trigger the obligation to offer the new benefit to existing policyholders?
- Prior and Related Legislation
SB 1091 (Liu) would define and establish standards for alternate plans of care that permit an LTCI insurer, insured, and the insureds medical provider to agree that the policy will provide care that is not covered under existing policy terms.
SB 1348 (Liu) would require the Partnership for Long-Term Care to provide additional and more affordable LTCI policy options and would establish a task force to consider more affordable policy design options.
POSITIONS
Support
Association of California Life and Health Insurance Companies (sponsor)
American Council of Life Insurers
National Association of Insurance and Financial Advisors – California
Oppose
None received
-- END --
Date of Hearing: May 4, 2016
ASSEMBLY COMMITTEE ON APPROPRIATIONS
Lorena Gonzalez, Chair
ABPCA Bill Id:AB 2366
Author:(Dababneh) – As Amended Ver:March 16, 2016
Policy Committee: | Insurance | Vote: | 13 - 0 |
Aging and Long Term Care | 6 - 0 |
Urgency: No State Mandated Local Program: No Reimbursable: No
SUMMARY:
This bill exempts insurers that offer a policy which combines both life and long-term care (LTC) coverages from the requirement to offer the new policy to their existing long-term care policy holders.
FISCAL EFFECT:
Costs to the California Department of Insurance are negligible.
COMMENTS:
- Purpose. According to the author, the requirement to offer new LTC products to existing policyholders hinders the ability of companies to make new products available for consumers, which creates a compliance debacle for new hybrid products, and can be extremely confusing or misleading to existing policyholders. This bill exempts insurers from the requirement to offer new LTC products to their existing policyholders when the products are a combination of LTC and another insurance product, such as life insurance. This bill is sponsored by the Association of California Life and Health Insurance Companies and has no opposition.
- Background. LTC insurance is an inherently difficult product for both consumers and insurers. It requires both the consumer and the insurer to estimate what LTC services will be needed, how long they will be needed, and when they will be needed, which requires projections decades into the future.
Because the LTC insurance product can tend to be volatile due to such uncertainty, strict requirements are in place for sellers of LTC policies. One such provision of existing law, which this bill addresses, requires LTC insurance sellers to provide the policy holder with the right to be notified of any new LTC benefit or benefit eligibility rule offered by the insurer, and be offered these same terms. This prevents a situation where a consumer is locked in to a higher rate for their LTC policy, when the insurer is offering new clients a lower rate or more favorable terms.
Uncertainty, a long time horizon, and relatively high cost have limited the popularity of LTC policies. To make the LTC insurance product appealing to a broader range of consumers, insurers have created products that combine life insurance and LTC insurance. These products provide a death benefit during the policyholder's working years and the benefit converts to an LTC benefit later in life. Since these new products are technically new LTC products, their creation and marketing have triggered the requirement that they be offered to existing LTC insurance policyholders. Insurers believe the requirement to offer new LTC policies to existing consumers was created to allow them to benefit from more favorable terms for their LTC product, but that applying the requirement to offer combination products to their existing LTC insurance policyholder sows confusion and is unnecessary. This bill will remove the requirement to offer—essentially, market— a combined life/LTC insurance product to their existing LTC policyholders, for many of whom the combined product may not be desirable.
Analysis Prepared by: Lisa Murawski / APPR. / (916) 319-2081
Date of Hearing: April 19, 2016
ASSEMBLY COMMITTEE ON AGING AND LONG-TERM CARE
Cheryl Brown, Chair
ABPCA Bill Id:AB 2366 (
Author:Dababneh) – As Amended Ver:March 16, 2016
SUBJECT: Long-term care insurance.
SUMMARY: Exempts insurers that offer a policy which combines both life and long-term care (LTC) coverage from the requirement to offer the new policy to their existing long-term care policy holders. Specifically, this bill:
- Maintains the requirement that insurers must notify its existing insureds of the right to be notified of new benefits or benefit eligibility.
- Maintains the requirement that insurers must provide the notice above within 12 months.
- Maintains the requirement that the insurer must continue to file notice with the Department of Insurance.
4) Exempts the insurer from providing this notice for life insurance-based combination policies that include long-term care coverage provisions.
EXISTING LAW:
- Requires long-term care insurance policies to provide the policy holder with the right to be notified of any new long-term care benefit or benefit eligibility rule offered by the insurer.
- Requires the insurer to offer the new benefit or benefit eligibility rule by the insurer as either a replacement policy or a rider on the existing policy.
- Provides for the regulation of LTC insurance by the Insurance Commissioner and prescribes various requirements and conditions governing the delivery of individual or group long-term care insurance in the state.
- Establishes the California Partnership for Long-Term Care Program to link private long-term care insurance and health care service plan contracts that cover long-term care with the In-Home Supportive Services program and Medi-Cal and to provide Medi-Cal benefits to certain individuals who have income and resources above the eligibility levels for receipt of medical assistance, but who have purchased certified private long-term care insurance policies and subsequently exhausted the benefits of these private policies.
FISCAL EFFECT: Unknown
COMMENTS:
Long-Term Care Services and Supports:
By 2030, nearly 20 % of California’s population will be 65 years or older. The vast majority of these seniors will one day need some type of long-term care services and supports, meaning a high level of help with nonmedical basic daily activities, like walking, eating, and bathing. For older adults and their families, providing this level of support can take a sizable toll on both quality of life and personal finances, given the lack of affordable, accessible financing solutions.
Preference for Home-Based Care:
The AARP Public Policy Institute has conducted numerous focus groups and surveys of people age 50 and over to ascertain their views about various issues with which they will grapple as they age. Nearly 90 % of people over age 65 want to stay in their home for as long as possible, and 80 % believe their current residence is where they will always live.
When asked to think specifically about their own personal situation as they get older, a slight majority of Americans 40 years or older are a great deal or quite a bit concerned about losing their independence (52%) and losing their memories or other mental abilities (51%). Forty-four percent are at least quite a bit concerned about being able to pay for the care or help they might need as they age, having to move to a nursing home (42%), being a burden on their family (41%), leaving debts to their family (32%), and being alone without family or friends around them (33%).
While a large share of Californians age 40 and older recognize the future need, many also state they have done little or no planning for their care needs and lack knowledge and confidence on the financial aspects of long-term care. Among California adults age 40 and over, only 27% are confident they have the financial resources to pay for long-term care. This is significantly lower than the rest of the country. In addition, nearly 3 in 10 mistakenly believe Medicare covers ongoing care in the home by a licensed home health care aid; a full one-third of individuals 40 and over do not know what Medicare provides for home-based care. What the survey does show without question is that the vast majority of older adults want to remain in their homes and communities as they age.
Several substantial and collaborative policy efforts are underway to explore innovative strategies to solving the Rubik’s cube puzzle of how to finance long term services and support. These efforts seek to provide information to help policymakers and stakeholders create a viable set of policy solutions that will meet the needs of individuals, families, state and federal governments, and society at large.
In February 2016, three organizations – the Bipartisan Policy Center (BPC), LeadingAge, and the Long-Term Care Financing Collaborative (the Collaborative) released information regarding how to approach better providing LTC services and supports. First, increasing insurance-based coverage would require multiple solutions, utilizing the strengths of both the private and public sectors. The private insurance marketplace needs to identify lower priced policies insuring against the risk of needing a high level of LTSS over a relatively short period of time. Next, it should include a public component of a catastrophic insurance program where all Americans would be covered. And finally, Medicaid should be strengthened as the safety net program, which would have an important but smaller role in a refashioned, insurance-based LTC financing system.
The federal Patient Protection and Affordable Care Act established the Community Living Assistance Services and Supports program (CLASS). The CLASS program was intended to be a national, voluntary insurance program designed to cover long-term care services and support. However, the federal government has since determined that the national program established under the CLASS Act would not be viable.
Long-term care (LTC) insurance is a product with a troubled history that has resulted in a rigorous regulatory regime. Long-term care policies are subject to regulatory controls including prior approval requirements for policies and advertisements, rate regulation, mandatory benefits, and detailed requirements governing the sale of LTC products to name a few. These stringent controls resulted from controversies involving prior LTC products in both product design (what services are covered and in what quantity) and pricing. Many early products were quite expensive for the narrow range of services and an emphasis on mostly institutional care that resulted in many policyholders owning policies that didn't cover the services they needed. LTC services are increasingly provided at home and in non-institutional, lesser restrictive settings and at the same time ever-increasing premiums that are unaffordable for the elderly with fixed incomes.
In addition, LTC insurance coverage is inherently difficult for both the consumer and the insurer to estimate what LTC services will be needed, how long they will be needed, and when they will be needed. The typical insurance coverage framework pressures the consumer to provide answers based on what their physical and financial condition will be 10, 20, or 30 years from now. It is tremendously difficult to anticipate what an individual might need over the last decades of one’s life. What is becoming clearer is that the vast majority of older adults want to remain in their homes and communities as they age.
Author’s Statement: According to the author, “Americans are increasingly concerned about how to pay for long-term care costs, if the need arises. At the same time, some consumers are hesitant to purchase and pay premiums on a traditional long-term care policy they may never use. In response to these concerns, some insurance companies began offering a hybrid product, which combines the benefits of a long-term care policy and a life insurance policy. Popular among consumers, premiums for these types of hybrid products reached $1.2 billion in 2014.
“Despite the popularity and evident desire for these types of hybrid products, California customers are unable to access some of these hybrid products because of a provision in California law that requires companies to offer existing long-term care policyholders the ability to upgrade their benefits any time new policies are developed with new long-term care benefits. Since hybrid products are treated as one policy and not separate components, there is confusion when new long-term care policy upgrades are available.
“Current law was intended to ensure that all stand-alone long-term care insurance consumers would continue to be able to compare and contrast their existing coverage against new products. However, hybrid products were not prevalent when the original mandate was passed, and applying it to combination products is not in consumers’ best interest and hinders new products from being offered.
“AB 2366 will exempt hybrid products from this mandatory “offer” requirement. This will give customers more access to hybrid products.”
Arguments in Support: According to the sponsor, the Association of California Life and Health Insurance Companies, “AB 2366 simply exempts hybrid products from the current offer requirement. This solution is not unique. There are other sections in CA law that carve out hybrid products from some of the LTC requirements that are typically put in place for stand-alone LTC policies.” The bill “will help remove a confusing replacement coverage requirement and pave the way for more innovative Long-Term Care products. Existing law requires insurers offering new long-term care (LTC) policies to offer the “new” coverage to their existing LTC policyholders whenever a new product is developed and approved for sale in the state. The offer statute (CIC 10235.52) was established in 2002 at a time when individual standalone LTC policies were more the focus of policymakers. We believe it is inappropriate to apply this requirement to “hybrid” products as it hinders the ability of companies to make new products available for consumers and can also be confusing or misleading to existing policyholders. ACLHIC is sponsoring AB 2366 to offer a simple solution to ensure that insurance consumers are offered the latest innovative insurance products, and protect existing consumers from being forced to review and contemplate a potentially inappropriate replacement product. In fact, a number of existing insurance code sections require significant protections for consumers against potential unnecessary LTC replacement sales. We believe this modest change in the law will assist in the development of new innovative LTC products, and protect many existing policyholders from being needlessly confused by an updated offer every time a new LTC product is developed. All products an insurer offers are always available for review online, or by calling a trusted insurance agent or representative.”
Related Legislation:
SB 1438 (Alquist) of 2012, called for a Long-Term Care Task force convened by the Commissioner of the Department of Insurance. SB 1438 was held in Senate Appropriations Committee.
AB 999 (Yamada), Chapter 627, Statutes of 2012 revised long-term care (LTC) insurance oversight to enhance consumer information and revise rate calculation requirements.
AB 1553 (Yamada) of 2014 prohibited the use of gender as a factor to determine the premium for LTC insurance. AB 1553 was held in the Assembly Insurance Committee.
AB 332 (Calderon) of 2015 established a task force to design a statewide, public long-term care insurance program. AB 332 was vetoed by the Governor.
REGISTERED SUPPORT / OPPOSITION:
Support
Association of California Life and Health Insurance Companies - Sponsor
National Association of Insurance and Financial Advisors – California (NAIFA-California)
Opposition
None on file.
Analysis Prepared by: Gail Gronert / AGING & L.T.C. / (916) 319-3990
Date of Hearing: April 6, 2016
ASSEMBLY COMMITTEE ON INSURANCE
Tom Daly, Chair
ABPCA Bill Id:AB 2366 (
Author:Dababneh) – As Amended Ver:March 16, 2016
SUBJECT: Long-term care insurance
SUMMARY: Exempts insurers that offer a policy which combines both life and long-term care (LTC) coverages from the requirement to offer the new policy to their existing long-term care policy holders.
EXISTING LAW:
1) Requires long-term care insurance policies to provide the policy holder with the right to be:
a) notified of any new long-term care benefit or benefit eligibility rule offered by the insurer, and
b) offered the new benefit or benefit eligibility rule by the insurer as either a replacement policy or a rider on the existing policy.
FISCAL EFFECT: Undetermined
COMMENTS:
- Purpose. According to the author, the requirement to offer new LTC products to existing policyholders hinders the ability of companies to make new products available for consumers, creates a compliance debacle for new hybrid products, and can be extremely confusing or misleading to existing policyholders. The author introduced the bill to offer a simple solution to ensure that insurance consumers are offered the latest innovative insurance products, while protecting existing policyholders from being forced to review and contemplate a potentially inappropriate replacement product. In fact, a number of existing Insurance Code sections require significant protections for consumers against potential unnecessary LTC replacement sales. This modest change in the law will assist in the development of new innovative LTC products, and protect many existing policyholders from being needlessly confused by an updated offer every time a new LTC product is developed. All products an insurer offers are always available for review online, or by calling an insurance agent or representative.
- Troubled Product. Long-term care insurance is a product with a troubled history that has spawned a rigorous regulatory regime. Long-term care policies are subject to myriad regulatory controls including prior approval requirements for policies and advertisements, rate regulation, mandatory benefits, and detailed requirements governing the sale of LTC products to name a few. These elaborate controls have arisen from problems that prior LTC products have had in both product design (what services are covered and in what quantity) and pricing. Many early products suffered from the dual sins of paying for a large amount of a fairly narrow range of services (mostly institutional care) with relatively low premiums that resulted in many policyholders owning policies that didn't cover a lot of the services they needed (LTC services are increasingly provided at home and in non-institutional settings) and ever increasing premiums that are unaffordable for retirees with fixed incomes.
LTC insurance is an inherently difficult product for both consumers and insurers. It requires both the consumer and the insurer to estimate what LTC services will be needed, how long they will be needed, and when they will be needed. This is inherently difficult as it requires the consumer to answer these questions based on what their physical and financial condition will be 10, 20, or 30 years from now. That inherent problem is compounded by the rapid development of medical and other technologies that are changing the way we age and die in dramatic ways. Even if the "what" of LTC services doesn't change over that time span, we can be confident that the "how" and the cost of LTC services will be very different in 20 years.
- Combination Products. For the reasons noted above, and others, LTC insurance has been a difficult product to sell. Somewhere between 10 and 12 percent of adults have an LTC policy of some kind. Mostly these policies have been purchased by more affluent women who face the reality that they will need care and likely not have a spouse or partner to provide it (women have longer average life spans than men) and want to preserve some assets to pass on to their heirs. Insurers have created products that combine life insurance and LTC insurance to try and make the product appealing to a broader range of consumers. These products provide a death benefit during the policyholder's working years and the benefit converts to an LTC benefit later in life. These new products are new LTC products and therefore have triggered the requirement that they be offered to existing LTC insurance policyholders.
Insurers indicate that this is problematic because the requirement to offer new products to existing policyholders was enacted with standalone LTC insurance products in mind. Combination products (also referred to as hybrid products) have a financial structure particular to the specific type of life insurance product upon which it is based (whole life, universal life, variable life, etc.) and within each type there are different methods of allocating premiums and earnings. The diversity of products in this new market may well be at odds with the underlying requirement to offer policyholders new products as they become available.
REGISTERED SUPPORT / OPPOSITION:
Support
Association of California Life and Health Insurance Companies
Opposition
None received
Analysis Prepared by: Paul Riches / INS. / (916) 319-2086
Discussed in Hearing
 1MIN
Assembly Floor
 2MIN
Senate Floor
 2MIN
Senate Floor
 5MIN
Senate Standing Committee on Insurance
Bill Author
Bill Co-Author(s):