AB 565: Group life insurance: required provisions.
- Session Year: 2015-2016
- House: Assembly
- Latest Version Date: 2016-09-22
Existing law provides for the regulation of specified insurance products, including group life insurance, by the Insurance Commissioner. Existing law provides that insurance under a group life insurance policy may be extended to insure the dependents of each insured employee under the group policy, as specified. Existing law defines a dependent for these purposes as including the employees spouse and all children from birth until 26 years of age, or a child 26 years of age or older who is both incapable of self-sustaining employment by reason of intellectual disability or physical handicap and chiefly dependent upon the employee for support and maintenance, as specified.
This bill would clarify that for dependent children over the age of majority the group policyholder would be authorized to elect coverage at age variations up to the limiting age.
Existing law defines a waiver of premium benefit or a waiver of monthly deduction benefit under a life insurance contract as a supplemental benefit that operates to safeguard a life insurance contract against lapse when the insured becomes totally disabled, as defined by the supplemental benefit, and continues until the end of the insureds disability or the period specified by the supplemental benefit, consistent with specified restrictions. Existing law requires, if the insureds total disability begins before the insured attains 60 years of age, the insurer to waive all premiums or monthly deductions due for the period that the insured continues to be totally disabled. Existing law requires, if the insureds total disability begins when the insured is 60 years of age or older, the insurer to waive all premiums or monthly deductions due for the period that the insured continues to be totally disabled up to 65 years of age.
This bill would require an insurer, for an insured who becomes totally disabled before attaining 60 years of age and is covered by a group life insurance policy that includes a supplemental benefit, to waive all premiums or monthly deductions due for the period of total disability up to the time the insured attains 65 years of age. The bill would also permit an insurer to collect premiums or monthly deductions from an insured who becomes totally disabled on or after 60 years of age and is covered by a group life insurance policy that includes a supplemental benefit. The bill would require an insurer offering a renewal for a group life insurance policy issued prior to January 1, 2017, that contains a supplemental benefit to offer the employer a continuation of the in-force supplemental benefit, and would authorize the insurer to concurrently offer the group policyholder the option to change the supplemental benefit to either waive or collect premiums or monthly deductions as described above.
Existing law provides for the regulation of specified insurance products, including group life insurance, by the Insurance Commissioner. Existing law provides that insurance under a group life insurance policy may be extended to insure the dependents of each insured employee under the group policy, as specified. Existing law defines a dependent for these purposes as including the employees spouse and all children from birth until 26 years of age, or a child 26 years of age or older who is both incapable of self-sustaining employment by reason of intellectual disability or physical handicap and chiefly dependent upon the employee for support and maintenance, as specified.
This bill would clarify that for dependent children over the age of majority the group policyholder would be authorized to elect coverage at age variations up to the limiting age.
Existing law defines a waiver of premium benefit or a waiver of monthly deduction benefit under a life insurance contract as a supplemental benefit that operates to safeguard a life insurance contract against lapse when the insured becomes totally disabled, as defined by the supplemental benefit, and continues until the end of the insureds disability or the period specified by the supplemental benefit, consistent with specified restrictions. Existing law requires, if the insureds total disability begins before the insured attains 60 years of age, the insurer to waive all premiums or monthly deductions due for the period that the insured continues to be totally disabled. Existing law requires, if the insureds total disability begins when the insured is 60 years of age or older, the insurer to waive all premiums or monthly deductions due for the period that the insured continues to be totally disabled up to 65 years of age.
This bill would require an insurer, for an insured who becomes totally disabled before attaining 60 years of age and is covered by a group life insurance policy that includes a supplemental benefit, to waive all premiums or monthly deductions due for the period of total disability up to the time the insured attains 65 years of age. The bill would also permit an insurer to collect premiums or monthly deductions from an insured who becomes totally disabled on or after 60 years of age and is covered by a group life insurance policy that includes a supplemental benefit. The bill would require an insurer offering a renewal for a group life insurance policy issued prior to January 1, 2017, that contains a supplemental benefit to offer the employer a continuation of the in-force supplemental benefit, and would authorize the insurer to concurrently offer the group policyholder the option to change the supplemental benefit to either waive or collect premiums or monthly deductions as described above.
Existing law provides for the regulation of specified insurance products, including group life and disability insurance, by the Insurance Commissioner. Existing law provides that insurance under a group life insurance policy may be extended to insure the dependents of each insured employee under the group policy, as specified. Existing law defines a dependent for these purposes as including the employees spouse and all children from birth until 26 years of age, or a child 26 years of age or older who is both incapable of self-sustaining employment by reason of intellectual disability or physical handicap and chiefly dependent upon the employee for support and maintenance, as specified.
This bill would clarify that the group policyholder would be authorized to elect coverage for dependent children under a group life insurance policy based on factors, including marital status, student status, residency, or support requirements, and, for dependent children over the age of majority, majority the group policyholder would be authorized to elect coverage at age variations up to the limiting age.
Existing law requires a group disability master insurance policy to include a provision that the insurer will issue to the policyholder for delivery to an individual insured under the policy an individual certificate that sets forth a statement as to the insurance protection to which he or she is entitled and to whom it is payable.
This bill would provide that instead the insurer may include in the master insurance policy a provision that the insurer will issue the certificate directly to the insured individual. This bill would make other technical, nonsubstantive changes.
Existing law defines a waiver of premium benefit or a waiver of monthly deduction benefit under a life insurance contract as a supplemental benefit that operates to safeguard a life insurance contract against lapse when the insured becomes totally disabled, as defined by the supplemental benefit, and continues until the end of the insureds disability or the period specified by the supplemental benefit, consistent with specified restrictions. Existing law requires, if the insureds total disability begins before the insured attains 60 years of age, the insurer to waive all premiums or monthly deductions due for the period that the insured continues to be totally disabled. Existing law requires, if the insureds total disability begins when the insured is 60 years of age or older, the insurer to waive all premiums or monthly deductions due for the period that the insured continues to be totally disabled up to 65 years of age.
This bill would require an insurer, for an insured who becomes totally disabled before attaining 60 years of age and is covered by a group life insurance policy that includes a supplemental benefit, to waive all premiums or monthly deductions due for the period of total disability up to the time the insured attains 65 years of age. The bill would also permit an insurer, for insurer to collect premiums or monthly deductions from an insured who becomes totally disabled on or after 60 years of age and is covered by a group life insurance policy that includes a supplemental benefit, to collect premiums as long as the insurer offers the group policyholder the option of having the insurer waive premiums up to 65 years of age. benefit. The bill would require an insurer offering a renewal for a group life insurance policy issued prior to January 1, 2017, that contains a supplemental benefit to offer the employer a continuation of the in-force supplemental benefit, and would authorize the insurer to concurrently offer the group policyholder the option to change the supplemental benefit to either waive or collect premiums or monthly deductions as described above.
Existing law provides for the regulation of specified insurance products, including group life and disability insurance, by the Insurance Commissioner. Existing law requires provides that insurance under a group life insurance policy may be extended to insure the dependents of each insured employee under the group policy, as specified. Existing law defines a dependent for these purposes as including the employees spouse and all children from birth until 26 years of age, or a child 26 years of age or older who is both incapable of self-sustaining employment by reason of intellectual disability or physical handicap and chiefly dependent upon the employee for support and maintenance, as specified.
This bill would clarify that the group policyholder would be authorized to elect coverage for dependent children under a group life insurance policy based on factors, including marital status, student status, residency, or support requirements, and, for dependent children over the age of majority, the group policyholder would be authorized to elect coverage at age variations up to the limiting age.
Existing law requires a group disability master insurance policy to include a provision that the insurer will issue to the policyholder for delivery to an individual insured under the policy an individual certificate that sets forth a statement as to the insurance protection to which he or she is entitled and to whom it is payable.
This bill would provide that instead the insurer may include in the master insurance policy a provision that the insurer will issue the certificate directly to the insured individual. This bill would make other technical, nonsubstantive changes.
Existing law defines a waiver of premium benefit or a waiver of monthly deduction benefit under a life insurance contract as a supplemental benefit that operates to safeguard a life insurance contract against lapse when the insured becomes totally disabled, as defined by the supplemental benefit, and continues until the end of the insureds disability or the period specified by the supplemental benefit, consistent with specified restrictions. Existing law requires, if the insureds total disability begins before the insured attains 60 years of age, the insurer to waive all premiums or monthly deductions due for the period that the insured continues to be totally disabled. Existing law requires, if the insureds total disability begins when the insured is 60 years of age or older, the insurer to waive all premiums or monthly deductions due for the period that the insured continues to be totally disabled up to 65 years of age.
This bill would require an insurer, for an insured who becomes totally disabled before attaining 60 years of age and is covered by a group life insurance policy that includes a supplemental benefit, to waive all premiums or monthly deductions due for the period of total disability up to the time the insured attains 65 years of age. The bill would also permit an insurer, for an insured who becomes totally disabled on or after 60 years of age and is covered by a group life insurance policy that includes a supplemental benefit, to collect premiums as long as the insurer offers the group policyholder the option of having the insurer waive premiums up to 65 years of age.
Existing law provides for the regulation of specified insurance products, including group disability insurance, by the Insurance Commissioner. Existing law requires a group disability master insurance policy to include a provision that the insurer will issue to the policyholder for delivery to an individual insured under the policy an individual certificate that sets forth a statement as to the insurance protection to which he or she is entitled and to whom it is payable.
This bill would provide that instead the insurer may include in the master insurance policy a provision that the insurer will issue the certificate directly to the insured individual. This bill would make other technical, nonsubstantive changes.
Existing law provides for the regulation of insurers and specified insurance products, including life insurance, disability insurance, and long-term care insurance, by the Insurance Commissioner. Existing law directs the Insurance Commissioner to enforce the execution of laws regulating the business of insurance.
This bill would require the commissioner to commission an independent study to examine the extent to which the uniform standards set forth in the Interstate Insurance Product Regulation Compact provide consumer protections that are equivalent to those established under state law for annuity, life insurance, disability income, and long-term care insurance products, and would prohibit the use of General Fund or Insurance Fund moneys for this purpose. The bill would require the commissioner to submit the report to the chairpersons of the Assembly and Senate Committees on Insurance no later than January 1, 2017.
Existing law provides for the regulation of insurers and specified insurance products, including life insurance, disability insurance, and long-term care insurance, by the Insurance Commissioner. Existing law directs the Insurance Commissioner to enforce the execution of laws regulating the business of insurance.
This bill would require the commissioner to commission an independent study to examine the extent to which the uniform standards set forth in the Interstate Insurance Product Regulation Compact provide consumer protections that are equivalent to those established under state law for annuity, life insurance, disability income, and long-term care insurance products, and would prohibit the use of General Fund or Insurance Fund moneys for this purpose. The bill would require the commissioner to submit the report to the chairpersons of the Assembly and Senate Committees on Insurance no later than January 1, 2017.
Existing law authorizes the Insurance Commissioner to promulgate, from time to time as conditions warrant, after notice and hearing, reasonable rules and regulations, and amendments and additions to those rules and regulations, as are necessary or advisable in order to establish and maintain a procedure for the filing and approval of specified documents prior to their issuance, delivery, or use in this state.
This bill would make technical, nonsubstantive changes to this provision.
Existing law authorizes the Insurance Commissioner to promulgate, from time to time as conditions warrant, after notice and hearing, reasonable rules and regulations, and amendments and additions to those rules and regulations, as are necessary or advisable in order to establish and maintain a procedure for the filing and approval of specified documents prior to their issuance, delivery, or use in this state.
This bill would make technical, nonsubstantive changes to this provision.
(a)Insurance under a group life insurance policy issued pursuant to Sections 10202, 10202.8, 10203, 10203.1, and 10203.7 may be extended to insure the dependents, or any class or classes thereof, of each insured employee who so elects, in amounts in accordance with some plan that precludes individual selection and that shall not be in excess of 100 percent of the insurance on the life of the insured employee. For dependent children over the age of majority, the group policyholder may elect coverage at age variations up to the limiting age.
(b)Dependent includes the members spouse or a minor child, as well as a child older than the age of majority up to a maximum of 26 years of age, or any child over the age of majority who is both incapable of self-sustaining employment by reason of an intellectual disability or physical handicap and chiefly dependent upon the employee for support and maintenance if proof of the incapacity and dependency is furnished to the insurer by the employee within 31 days of the childs attainment of the limiting age and subsequently as may be required by the insurer, but not more frequently than annually after the two-year period following the childs attainment of the limiting age.
(c)The premiums for the insurance on the dependents may be paid by the employer, the employee, or the employer and the employee jointly.
SEC. 2.Section 10271.1 of the Insurance Code is amended to read:10271.1.(a)(1)Supplemental benefits that operate to safeguard life insurance contracts against lapse are defined as a waiver of premium benefit or a waiver of monthly deduction benefit, as applicable, in which the insurer waives the premium or monthly deduction for a life insurance contract when the insured becomes totally disabled, as defined by the supplemental benefit, and where the waiver continues until the end of the insureds disability, or for the period specified by the supplemental benefit, consistent with paragraph (5).
(2)For purposes of this subdivision, total disability shall not be less favorable to the insured than the following:
(A)During the first 24 months of total disability, the insured is unable to perform with reasonable continuity the substantial and material duties of his or her job due to sickness or bodily injury.
(B)After the first 24 months of total disability, the insured, due to sickness or bodily injury, is unable to engage with reasonable continuity in any other job in which he or she could reasonably be expected to perform satisfactorily in light of his or her age, education, training, experience, station in life, or physical and mental capacity.
(3)The definition of total disability may also include presumptive total disability, such as the insureds total and permanent loss of sight of both eyes, hearing of both ears, speech, the use of both hands, both feet, or one hand and one foot.
(4)The insurer may require total disability to continue for an uninterrupted period of time specified by the supplemental benefit, or the insurer may allow separate periods of disability to be combined.
(5)The waiver of premium or monthly deduction benefit shall continue for the period specified by the supplemental benefit, but shall not be less favorable to the insured than the following:
(A)If the insureds total disability begins before the insured attains 60 years of age, the insurer shall waive all premiums or monthly deductions due for the period that the insured continues to be totally disabled, except as follows:
(i)For group life insurance policies, if the insureds total disability begins before the insured attains 60 years of age, the insurer shall waive all premiums or monthly deductions due for the period of total disability up to 65 years of age. Nothing in this subdivision shall preclude the insurer from extending a supplemental benefit for longer periods.
(ii)When a renewal is offered for a group life insurance policy that was issued prior to January 1, 2017, and contains a supplemental benefit described in this subparagraph, the insurer shall offer to renew the policy with a continuation of the in-force supplemental benefit, and may concurrently offer the group policyholder the option to change the supplemental benefit as described in clause (i).
(B)If the insureds total disability begins after the age specified in subparagraph (A), the insurer shall waive all premiums or monthly deductions due for the period that the insured continues to be totally disabled up to 65 years of age, except as follows:
(i)For group life insurance policies, if the insureds total disability begins on or after the date the insured attains 60 years of age, the insurer is not required to waive premiums or monthly deductions. Nothing in this subdivision shall preclude the insurer from extending a supplemental benefit for longer periods.
(ii)When a renewal is offered for a group life insurance policy that was issued prior to January 1, 2017, and contains a supplemental benefit described in this subparagraph, the insurer shall offer to renew the policy with a continuation of the in-force supplemental benefit, and may concurrently offer the group policyholder the option to change the supplemental benefit as described in clause (i).
(6)In addition to the permissible exclusions listed in subdivision (g) of Section 10271, the insurer may exclude a total disability occurring after the policy anniversary or supplemental contract anniversary, as applicable and as defined by the supplemental benefit, on which the insured attains a specified age of no less than 65 years.
(b)Special surrender benefit is defined as a waiver of surrender charge benefit wherein the insurer waives the surrender charge usually charged for a withdrawal of funds from the cash value of a life insurance contract or the account value of an annuity contract if the owner, insured, or annuitant, as applicable, meets any of the following criteria:
(1)Develops any medical condition where the owners, insureds, or annuitants life expectancy is expected to be less than or equal to a limited period of time that shall not be restricted to a period of less than 12 months or greater than 24 months.
(2)Is receiving, as prescribed by a physician, registered nurse, or licensed social worker, home care or community-based services, as defined in subdivision (a) of Section 10232.9, or is confined in a skilled nursing facility, convalescent nursing home, or extended care facility, which shall not be defined more restrictively than as in the Medicare program, or is confined in a residential care facility or residential care facility for the elderly, as defined in the Health and Safety Code. Out-of-state providers of services shall be defined as comparable in licensure and staffing requirements to California providers.
(3)Has any medical condition that would, in the absence of treatment, result in death within a limited period of time, as defined by the supplemental benefit, but that shall not be restricted to a period of less than six months.
(4)Is totally disabled, as follows:
(A)During the first 24 months of total disability, the owner, insured, or annuitant, as applicable, is unable to perform with reasonable continuity the substantial and material duties of his or her job due to sickness or bodily injury.
(B)After the first 24 months of total disability, the owner, insured, or annuitant, as applicable, due to sickness or bodily injury, is unable to engage with reasonable continuity in any other job in which he or she could reasonably be expected to perform satisfactorily in light of his or her age, education, training, experience, station in life, or physical and mental capacity.
(C)The definition of total disability may also include presumptive total disability, such as the insureds total and permanent loss of sight of both eyes, hearing of both ears, speech, the use of both hands, both feet, or one hand and one foot.
(D)The insurer may require the total disability to continue for an uninterrupted period of time specified by the supplemental benefit, or the insurer may allow separate periods of disability to be combined.
(5)Has a chronic illness as defined pursuant to either subparagraph (A) or (B):
(A)Either of the following:
(i)Impairment in performing two out of seven activities of daily living, as set forth in subdivisions (a) and (g) of Section 10232.8, meaning the insured needs human assistance, or needs continual substantial supervision.
(ii)The insured has an impairment of cognitive ability, meaning a deterioration or loss of intellectual capacity due to mental illness or disease, including Alzheimers disease or related illnesses, that requires continual supervision to protect oneself or others.
(B)Either of the following:
(i)Impairment in performing two out of six activities of daily living as described in subdivisions (b), (d), (e), and (f) of Section 10232.8 due to a loss of functional capacity to perform the activity.
(ii)Impairment of cognitive ability, meaning the insured needs substantial supervision due to severe cognitive impairment, as described in subdivisions (b), (d), and (e) of Section 10232.8.
(6)Has become involuntarily or voluntarily unemployed.
(c)The term supplemental benefit means a rider to or provision in a life insurance policy, certificate, or annuity contract that provides a benefit as set forth in subdivision (a) of Section 10271.
(a)Insurance under a group life insurance policy issued pursuant to Sections 10202, 10202.8, 10203, 10203.1, and 10203.7 may be extended to insure the dependents, or any class or classes thereof, of each insured employee who so elects, in amounts in accordance with some plan that precludes individual selection and that shall not be in excess of 100 percent of the insurance on the life of the insured employee. For dependent children over the age of majority, the group policyholder may elect coverage at age variations up to the limiting age.
(b)Dependent includes the members spouse or a minor child, as well as a child older than the age of majority up to a maximum of 26 years of age, or any child over the age of majority who is both incapable of self-sustaining employment by reason of an intellectual disability or physical handicap and chiefly dependent upon the employee for support and maintenance if proof of the incapacity and dependency is furnished to the insurer by the employee within 31 days of the childs attainment of the limiting age and subsequently as may be required by the insurer, but not more frequently than annually after the two-year period following the childs attainment of the limiting age.
(c)The premiums for the insurance on the dependents may be paid by the employer, the employee, or the employer and the employee jointly.
SEC. 2.Section 10271.1 of the Insurance Code is amended to read:10271.1.(a)(1)Supplemental benefits that operate to safeguard life insurance contracts against lapse are defined as a waiver of premium benefit or a waiver of monthly deduction benefit, as applicable, in which the insurer waives the premium or monthly deduction for a life insurance contract when the insured becomes totally disabled, as defined by the supplemental benefit, and where the waiver continues until the end of the insureds disability, or for the period specified by the supplemental benefit, consistent with paragraph (5).
(2)For purposes of this subdivision, total disability shall not be less favorable to the insured than the following:
(A)During the first 24 months of total disability, the insured is unable to perform with reasonable continuity the substantial and material duties of his or her job due to sickness or bodily injury.
(B)After the first 24 months of total disability, the insured, due to sickness or bodily injury, is unable to engage with reasonable continuity in any other job in which he or she could reasonably be expected to perform satisfactorily in light of his or her age, education, training, experience, station in life, or physical and mental capacity.
(3)The definition of total disability may also include presumptive total disability, such as the insureds total and permanent loss of sight of both eyes, hearing of both ears, speech, the use of both hands, both feet, or one hand and one foot.
(4)The insurer may require total disability to continue for an uninterrupted period of time specified by the supplemental benefit, or the insurer may allow separate periods of disability to be combined.
(5)The waiver of premium or monthly deduction benefit shall continue for the period specified by the supplemental benefit, but shall not be less favorable to the insured than the following:
(A)If the insureds total disability begins before the insured attains 60 years of age, the insurer shall waive all premiums or monthly deductions due for the period that the insured continues to be totally disabled, except as follows:
(i)For group life insurance policies, if the insureds total disability begins before the insured attains 60 years of age, the insurer shall waive all premiums or monthly deductions due for the period of total disability up to 65 years of age. Nothing in this subdivision shall preclude the insurer from extending a supplemental benefit for longer periods.
(ii)When a renewal is offered for a group life insurance policy that was issued prior to January 1, 2017, and contains a supplemental benefit described in this subparagraph, the insurer shall offer to renew the policy with a continuation of the in-force supplemental benefit, and may concurrently offer the group policyholder the option to change the supplemental benefit as described in clause (i).
(B)If the insureds total disability begins after the age specified in subparagraph (A), the insurer shall waive all premiums or monthly deductions due for the period that the insured continues to be totally disabled up to 65 years of age, except as follows:
(i)For group life insurance policies, if the insureds total disability begins on or after the date the insured attains 60 years of age, the insurer is not required to waive premiums or monthly deductions. Nothing in this subdivision shall preclude the insurer from extending a supplemental benefit for longer periods.
(ii)When a renewal is offered for a group life insurance policy that was issued prior to January 1, 2017, and contains a supplemental benefit described in this subparagraph, the insurer shall offer to renew the policy with a continuation of the in-force supplemental benefit, and may concurrently offer the group policyholder the option to change the supplemental benefit as described in clause (i).
(6)In addition to the permissible exclusions listed in subdivision (g) of Section 10271, the insurer may exclude a total disability occurring after the policy anniversary or supplemental contract anniversary, as applicable and as defined by the supplemental benefit, on which the insured attains a specified age of no less than 65 years.
(b)Special surrender benefit is defined as a waiver of surrender charge benefit wherein the insurer waives the surrender charge usually charged for a withdrawal of funds from the cash value of a life insurance contract or the account value of an annuity contract if the owner, insured, or annuitant, as applicable, meets any of the following criteria:
(1)Develops any medical condition where the owners, insureds, or annuitants life expectancy is expected to be less than or equal to a limited period of time that shall not be restricted to a period of less than 12 months or greater than 24 months.
(2)Is receiving, as prescribed by a physician, registered nurse, or licensed social worker, home care or community-based services, as defined in subdivision (a) of Section 10232.9, or is confined in a skilled nursing facility, convalescent nursing home, or extended care facility, which shall not be defined more restrictively than as in the Medicare program, or is confined in a residential care facility or residential care facility for the elderly, as defined in the Health and Safety Code. Out-of-state providers of services shall be defined as comparable in licensure and staffing requirements to California providers.
(3)Has any medical condition that would, in the absence of treatment, result in death within a limited period of time, as defined by the supplemental benefit, but that shall not be restricted to a period of less than six months.
(4)Is totally disabled, as follows:
(A)During the first 24 months of total disability, the owner, insured, or annuitant, as applicable, is unable to perform with reasonable continuity the substantial and material duties of his or her job due to sickness or bodily injury.
(B)After the first 24 months of total disability, the owner, insured, or annuitant, as applicable, due to sickness or bodily injury, is unable to engage with reasonable continuity in any other job in which he or she could reasonably be expected to perform satisfactorily in light of his or her age, education, training, experience, station in life, or physical and mental capacity.
(C)The definition of total disability may also include presumptive total disability, such as the insureds total and permanent loss of sight of both eyes, hearing of both ears, speech, the use of both hands, both feet, or one hand and one foot.
(D)The insurer may require the total disability to continue for an uninterrupted period of time specified by the supplemental benefit, or the insurer may allow separate periods of disability to be combined.
(5)Has a chronic illness as defined pursuant to either subparagraph (A) or (B):
(A)Either of the following:
(i)Impairment in performing two out of seven activities of daily living, as set forth in subdivisions (a) and (g) of Section 10232.8, meaning the insured needs human assistance, or needs continual substantial supervision.
(ii)The insured has an impairment of cognitive ability, meaning a deterioration or loss of intellectual capacity due to mental illness or disease, including Alzheimers disease or related illnesses, that requires continual supervision to protect oneself or others.
(B)Either of the following:
(i)Impairment in performing two out of six activities of daily living as described in subdivisions (b), (d), (e), and (f) of Section 10232.8 due to a loss of functional capacity to perform the activity.
(ii)Impairment of cognitive ability, meaning the insured needs substantial supervision due to severe cognitive impairment, as described in subdivisions (b), (d), and (e) of Section 10232.8.
(6)Has become involuntarily or voluntarily unemployed.
(c)The term supplemental benefit means a rider to or provision in a life insurance policy, certificate, or annuity contract that provides a benefit as set forth in subdivision (a) of Section 10271.
(a)Insurance under a group life insurance policy issued pursuant to Sections 10202, 10202.8, 10203, 10203.1, and 10203.7 may be extended to insure the dependents, or any class or classes thereof, of each insured employee who so elects, in amounts in accordance with some plan that precludes individual selection and that shall not be in excess of 100 percent of the insurance on the life of the insured employee. The group policyholder may elect coverage for dependent children based on factors, including marital status, student status, residency, or support requirements, and, for For dependent children over the age of majority, the group policyholder may elect coverage at age variations up to the limiting age.
(b)Dependent includes the members spouse or a minor child, as well as a child older than the age of majority up to a maximum of 26 years of age, or an older child any child over the age of majority who is both incapable of self-sustaining employment by reason of an intellectual disability or physical handicap and chiefly dependent upon the employee for support and maintenance if proof of the incapacity and dependency is furnished to the insurer by the employee within 31 days of the childs attainment of the limiting age and subsequently as may be required by the insurer, but not more frequently than annually after the two-year period following the childs attainment of the limiting age.
(c)The premiums for the insurance on the dependents may be paid by the employer, the employee, or the employer and the employee jointly.
SEC. 2.Section 10270.6 of the Insurance Code is amended to read:10270.6.Every group disability master policy shall contain the following provisions:
(a)A provision that the policy, the application of the policyholder, and the individual applications, if any, of the individuals insured shall constitute the entire contract between the parties, and that all statements made by the policyholder, or by the individuals insured shall, in the absence of fraud, be deemed representations and not warranties, and that no such statement shall be used in defense to a claim under the policy, unless it is contained in a written application.
(b)A provision that the insurer will issue to the policyholder for delivery to the individuals insured under that policy, or a provision that the insurer will issue directly to the insured, an individual certificate setting forth a statement as to the insurance protection to which he or she is entitled and to whom payable.
(c)A provision that to the group or class thereof originally insured shall be added from time to time all new employees, members or pupils of the policyholder eligible to and applying for insurance in that group or class.
(d)A statement that the policy is not in lieu of and does not affect any requirement for coverage by workmens compensation insurance.
SEC. 3.SEC. 2.Section 10271.1 of the Insurance Code is amended to read:10271.1.(a)(1)Supplemental benefits that operate to safeguard life insurance contracts against lapse are defined as a waiver of premium benefit or a waiver of monthly deduction benefit, as applicable, in which the insurer waives the premium or monthly deduction for a life insurance contract when the insured becomes totally disabled, as defined by the supplemental benefit, and where the waiver continues until the end of the insureds disability, or for the period specified by the supplemental benefit, consistent with paragraph (5).
(2)For purposes of this subdivision, total disability shall not be less favorable to the insured than the following:
(A)During the first 24 months of total disability, the insured is unable to perform with reasonable continuity the substantial and material duties of his or her job due to sickness or bodily injury.
(B)After the first 24 months of total disability, the insured, due to sickness or bodily injury, is unable to engage with reasonable continuity in any other job in which he or she could reasonably be expected to perform satisfactorily in light of his or her age, education, training, experience, station in life, or physical and mental capacity.
(3)The definition of total disability may also include presumptive total disability, such as the insureds total and permanent loss of sight of both eyes, hearing of both ears, speech, the use of both hands, both feet, or one hand and one foot.
(4)The insurer may require total disability to continue for an uninterrupted period of time specified by the supplemental benefit, or the insurer may allow separate periods of disability to be combined.
(5)The waiver of premium or monthly deduction benefit shall continue for the period specified by the supplemental benefit, but shall not be less favorable to the insured than the following:
(A)If the insureds total disability begins before the insured attains 60 years of age, the insurer shall waive all premiums or monthly deductions due for the period that the insured continues to be totally disabled, except in the case of coverage under as follows:
(i)For group life insurance policies where, policies, if the insureds total disability begins before the insured attains 60 years of age, the insurer shall waive all premiums or monthly deductions due for the period of total disability up to 65 years of age. Nothing in this subdivision shall preclude the insurer from extending a supplemental benefit for longer periods.
(ii)When a renewal is offered for a group life insurance policy that was issued prior to January 1, 2017, and contains a supplemental benefit described in this subparagraph, the insurer shall offer to renew the policy with a continuation of the in-force supplemental benefit, and may concurrently offer the group policyholder the option to change the supplemental benefit as described in clause (i).
(B)If the insureds total disability begins after the age specified in subparagraph (A), the insurer shall waive all premiums or monthly deductions due for the period that the insured continues to be totally disabled up to 65 years of age, except in the case of coverage under as follows:
(i)For group life insurance policies where, subject to the insurer offering the group policyholder the option to have the insurer waive premiums up to 65 years of age, premiums are not required to be waived for a disability that begins on or after the date the insured attains 60 years of age. policies, if the insureds total disability begins on or after the date the insured attains 60 years of age, the insurer is not required to waive premiums or monthly deductions. Nothing in this subdivision shall preclude the insurer from extending a supplemental benefit for longer periods.
(ii)When a renewal is offered for a group life insurance policy that was issued prior to January 1, 2017, and contains a supplemental benefit described in this subparagraph, the insurer shall offer to renew the policy with a continuation of the in-force supplemental benefit, and may concurrently offer the group policyholder the option to change the supplemental benefit as described in clause (i).
(6)In addition to the permissible exclusions listed in subdivision (g) of Section 10271, the insurer may exclude a total disability occurring after the policy anniversary or supplemental contract anniversary, as applicable and as defined by the supplemental benefit, on which the insured attains a specified age of no less than 65 years.
(b)Special surrender benefit is defined as a waiver of surrender charge benefit wherein the insurer waives the surrender charge usually charged for a withdrawal of funds from the cash value of a life insurance contract or the account value of an annuity contract if the owner, insured, or annuitant, as applicable, meets any of the following criteria:
(1)Develops any medical condition where the owners, insureds, or annuitants life expectancy is expected to be less than or equal to a limited period of time that shall not be restricted to a period of less than 12 months or greater than 24 months.
(2)Is receiving, as prescribed by a physician, registered nurse, or licensed social worker, home care or community-based services, as defined in subdivision (a) of Section 10232.9, or is confined in a skilled nursing facility, convalescent nursing home, or extended care facility, which shall not be defined more restrictively than as in the Medicare program, or is confined in a residential care facility or residential care facility for the elderly, as defined in the Health and Safety Code. Out-of-state providers of services shall be defined as comparable in licensure and staffing requirements to California providers.
(3)Has any medical condition that would, in the absence of treatment, result in death within a limited period of time, as defined by the supplemental benefit, but that shall not be restricted to a period of less than six months.
(4)Is totally disabled, as follows:
(A)During the first 24 months of total disability, the owner, insured, or annuitant, as applicable, is unable to perform with reasonable continuity the substantial and material duties of his or her job due to sickness or bodily injury.
(B)After the first 24 months of total disability, the owner, insured, or annuitant, as applicable, due to sickness or bodily injury, is unable to engage with reasonable continuity in any other job in which he or she could reasonably be expected to perform satisfactorily in light of his or her age, education, training, experience, station in life, or physical and mental capacity.
(C)The definition of total disability may also include presumptive total disability, such as the insureds total and permanent loss of sight of both eyes, hearing of both ears, speech, the use of both hands, both feet, or one hand and one foot.
(D)The insurer may require the total disability to continue for an uninterrupted period of time specified by the supplemental benefit, or the insurer may allow separate periods of disability to be combined.
(5)Has a chronic illness as defined pursuant to either subparagraph (A) or (B):
(A)Either of the following:
(i)Impairment in performing two out of seven activities of daily living, as set forth in subdivisions (a) and (g) of Section 10232.8, meaning the insured needs human assistance, or needs continual substantial supervision.
(ii)The insured has an impairment of cognitive ability, meaning a deterioration or loss of intellectual capacity due to mental illness or disease, including Alzheimers disease or related illnesses, that requires continual supervision to protect oneself or others.
(B)Either of the following:
(i)Impairment in performing two out of six activities of daily living as described in subdivisions (b), (d), (e), and (f) of Section 10232.8 due to a loss of functional capacity to perform the activity.
(ii)Impairment of cognitive ability, meaning the insured needs substantial supervision due to severe cognitive impairment, as described in subdivisions (b), (d), and (e) of Section 10232.8.
(6)Has become involuntarily or voluntarily unemployed.
(c)The term supplemental benefit means a rider to or provision in a life insurance policy, certificate, or annuity contract that provides a benefit as set forth in subdivision (a) of Section 10271.
(a)Insurance under a group life insurance policy issued pursuant to Sections 10202, 10202.8, 10203, 10203.1, and 10203.7 may be extended to insure the dependents, or any class or classes thereof, of each insured employee who so elects, in amounts in accordance with some plan that precludes individual selection and that shall not be in excess of 100 percent of the insurance on the life of the insured employee. The group policyholder may elect coverage for dependent children based on factors, including marital status, student status, residency, or support requirements, and, for dependent children over the age of majority, the group policyholder may elect coverage at age variations up to the limiting age.
(b)Dependent includes the members spouse and all children from birth until 26 years of age, or a child 26 years of age or a minor child, as well as a child older than the age of majority up to a maximum of 26 years of age, or an older child who is both incapable of self-sustaining employment by reason of an intellectual disability or physical handicap and chiefly dependent upon the employee for support and maintenance if proof of the incapacity and dependency is furnished to the insurer by the employee within 31 days of the childs attainment of the limiting age and subsequently as may be required by the insurer, but not more frequently than annually after the two-year period following the childs attainment of the limiting age.
(c)The premiums for the insurance on the dependents may be paid by the employer, the employee, or the employer and the employee jointly.
SECTION 1.SEC. 2.Section 10270.6 of the Insurance Code is amended to read:10270.6.Every group disability master policy shall contain the following provisions:
(a)A provision that the policy, the application of the policyholder, and the individual applications, if any, of the individuals insured shall constitute the entire contract between the parties, and that all statements made by the policyholder, or by the individuals insured shall, in the absence of fraud, be deemed representations and not warranties, and that no such statement shall be used in defense to a claim under the policy, unless it is contained in a written application.
(b)A provision that the insurer will issue to the policyholder for delivery to the individuals insured under that policy, or a provision that the insurer will issue directly to the insured, an individual certificate setting forth a statement as to the insurance protection to which he or she is entitled and to whom payable.
(c)A provision that to the group or class thereof originally insured shall be added from time to time all new employees, members or pupils of the policyholder eligible to and applying for insurance in that group or class.
(d)A statement that the policy is not in lieu of and does not affect any requirement for coverage by workmens compensation insurance.
SEC. 3.Section 10271.1 of the Insurance Code is amended to read:10271.1.(a)(1)Supplemental benefits that operate to safeguard life insurance contracts against lapse are defined as a waiver of premium benefit or a waiver of monthly deduction benefit, as applicable, in which the insurer waives the premium or monthly deduction for a life insurance contract when the insured becomes totally disabled, as defined by the supplemental benefit, and where the waiver continues until the end of the insureds disability, or for the period specified by the supplemental benefit, consistent with paragraph (5).
(2)For purposes of this subdivision, total disability shall not be less favorable to the insured than the following:
(A)During the first 24 months of total disability, the insured is unable to perform with reasonable continuity the substantial and material duties of his or her job due to sickness or bodily injury.
(B)After the first 24 months of total disability, the insured, due to sickness or bodily injury, is unable to engage with reasonable continuity in any other job in which he or she could reasonably be expected to perform satisfactorily in light of his or her age, education, training, experience, station in life, or physical and mental capacity.
(3)The definition of total disability may also include presumptive total disability, such as the insureds total and permanent loss of sight of both eyes, hearing of both ears, speech, the use of both hands, both feet, or one hand and one foot.
(4)The insurer may require total disability to continue for an uninterrupted period of time specified by the supplemental benefit, or the insurer may allow separate periods of disability to be combined.
(5)The waiver of premium or monthly deduction benefit shall continue for the period specified by the supplemental benefit, but shall not be less favorable to the insured than the following:
(A)If the insureds total disability begins before the insured attains 60 years of age, the insurer shall waive all premiums or monthly deductions due for the period that the insured continues to be totally disabled. disabled, except in the case of coverage under group life insurance policies where, if the insureds total disability begins before the insured attains 60 years of age, the insurer shall waive all premiums or monthly deductions due for the period of total disability up to 65 years of age. Nothing in this subdivision shall preclude the insurer from extending a supplemental benefit for longer periods.
(B)If the insureds total disability begins after the age specified in subparagraph (A), the insurer shall waive all premiums or monthly deductions due for the period that the insured continues to be totally disabled up to 65 years of age. age, except in the case of coverage under group life insurance policies where, subject to the insurer offering the group policyholder the option to have the insurer waive premiums up to 65 years of age, premiums are not required to be waived for a disability that begins on or after the date the insured attains 60 years of age. Nothing in this subdivision shall preclude the insurer from extending a supplemental benefit for longer periods.
(6)In addition to the permissible exclusions listed in subdivision (g) of Section 10271, the insurer may exclude a total disability occurring after the policy anniversary or supplemental contract anniversary, as applicable and as defined by the supplemental benefit, on which the insured attains a specified age of no less than 65 years.
(b)Special surrender benefit is defined as a waiver of surrender charge benefit wherein the insurer waives the surrender charge usually charged for a withdrawal of funds from the cash value of a life insurance contract or the account value of an annuity contract if the owner, insured, or annuitant, as applicable, meets any of the following criteria:
(1)Develops any medical condition where the owners, insureds, or annuitants life expectancy is expected to be less than or equal to a limited period of time that shall not be restricted to a period of less than 12 months or greater than 24 months.
(2)Is receiving, as prescribed by a physician, registered nurse, or licensed social worker, home care or community-based services, as defined in subdivision (a) of Section 10232.9, or is confined in a skilled nursing facility, convalescent nursing home, or extended care facility, which shall not be defined more restrictively than as in the Medicare program, or is confined in a residential care facility or residential care facility for the elderly, as defined in the Health and Safety Code. Out-of-state providers of services shall be defined as comparable in licensure and staffing requirements to California providers.
(3)Has any medical condition that would, in the absence of treatment, result in death within a limited period of time, as defined by the supplemental benefit, but that shall not be restricted to a period of less than six months.
(4)Is totally disabled, as follows:
(A)During the first 24 months of total disability, the owner, insured, or annuitant, as applicable, is unable to perform with reasonable continuity the substantial and material duties of his or her job due to sickness or bodily injury.
(B)After the first 24 months of total disability, the owner, insured, or annuitant, as applicable, due to sickness or bodily injury, is unable to engage with reasonable continuity in any other job in which he or she could reasonably be expected to perform satisfactorily in light of his or her age, education, training, experience, station in life, or physical and mental capacity.
(C)The definition of total disability may also include presumptive total disability, such as the insureds total and permanent loss of sight of both eyes, hearing of both ears, speech, the use of both hands, both feet, or one hand and one foot.
(D)The insurer may require the total disability to continue for an uninterrupted period of time specified by the supplemental benefit, or the insurer may allow separate periods of disability to be combined.
(5)Has a chronic illness as defined pursuant to either subparagraph (A) or (B):
(A)Either of the following:
(i)Impairment in performing two out of seven activities of daily living, as set forth in subdivisions (a) and (g) of Section 10232.8, meaning the insured needs human assistance, or needs continual substantial supervision.
(ii)The insured has an impairment of cognitive ability, meaning a deterioration or loss of intellectual capacity due to mental illness or disease, including Alzheimers disease or related illnesses, that requires continual supervision to protect oneself or others.
(B)Either of the following:
(i)Impairment in performing two out of six activities of daily living as described in subdivisions (b), (d), (e), and (f) of Section 10232.8 due to a loss of functional capacity to perform the activity.
(ii)Impairment of cognitive ability, meaning the insured needs substantial supervision due to severe cognitive impairment, as described in subdivisions (b), (d), and (e) of Section 10232.8.
(6)Has become involuntarily or voluntarily unemployed.
(c)The term supplemental benefit means a rider to or provision in a life insurance policy, certificate, or annuity contract that provides a benefit as set forth in subdivision (a) of Section 10271.
Every group disability master policy shall contain the following provisions:
(a)A provision that the policy, the application of the policyholder policyholder, and the individual applications, if any, of the individuals insured shall constitute the entire contract between the parties, and that all statements made by the policyholder, or by the individuals insured shall, in the absence of fraud, be deemed representations and not warranties, and that no such statement shall be used in defense to a claim under the policy, unless it is contained in a written application; application.
(b)A provision that the insurer will issue to the policyholder for delivery to the individuals insured under such that policy, or a provision that the insurer will issue directly to the insured, an individual certificate setting forth a statement as to the insurance protection to which he or she is entitled and to whom payable; payable.
(c)A provision that to the group or class thereof originally insured shall be added from time to time all new employees, members or pupils of the policyholder eligible to and applying for insurance in such that group or class; class.
(d)A statement that such the policy is not in lieu of and does not affect any requirement for coverage by workmens compensation insurance.
SECTION 1.Section 10191.5 is added to the Insurance Code, to read:10191.5.(a)(1)The commissioner shall commission an independent study to examine the extent to which the uniform standards set forth in the Interstate Insurance Product Regulation Compact developed by the Interstate Insurance Product Regulation Commission provide consumer protections that are equivalent to those established under state law for annuity, life insurance, disability income, and long-term care insurance products.
(2)The report shall, to the extent feasible, also highlight the substantive differences between the uniform standards set forth in the Interstate Insurance Product Regulation Compact and the statutory requirements under state law for annuity, life insurance, disability income, and long-term care insurance products.
(b)(1)The commissioner shall submit the report to the chairpersons of the Assembly and Senate Committees on Insurance no later than January 1, 2017. The report shall be made in compliance with Section 9795 of the Government Code.
(2)The commissioner shall have the right to review and approve the final report prior to its submission to the Legislature.
(c)This section shall be implemented only to the extent that solicited nonpublic funds are received and made available for the commission of the independent study. No General Fund or Insurance Fund moneys shall be used to implement this section.
(d)This section shall remain in effect only until January 1, 2021, and as of that date is repealed, unless a later enacted statute, that is enacted before January 1, 2021, deletes or extends that date.
(a)(1)The commissioner shall commission an independent study to examine the extent to which the uniform standards set forth in the Interstate Insurance Product Regulation Compact developed by the Interstate Insurance Product Regulation Commission provide consumer protections that are equivalent to those established under state law for annuity, life insurance, disability income, and long-term care insurance products.
(2)The report shall, to the extent feasible, also highlight the substantive differences between the uniform standards set forth in the Interstate Insurance Product Regulation Compact and the statutory requirements under state law for annuity, life insurance, disability income, and long-term care insurance products.
(b)(1)The commissioner shall submit the report to the chairpersons of the Assembly and Senate Committees on Insurance no later than January 1, 2017. The report shall be made in compliance with Section 9795 of the Government Code.
(2)The commissioner shall have the right to review and approve the final report prior to its submission to the Legislature.
(c)This section shall be implemented only to the extent that solicited nonpublic funds are received and made available for the commission of the independent study. No General Fund or Insurance Fund moneys shall be used to implement this section.
(d)This section shall remain in effect only until January 1, 2021, and as of that date is repealed, unless a later enacted statute, that is enacted before January 1, 2021, deletes or extends that date.
SECTION 1.Section 10191 of the Insurance Code is amended to read:10191.(a)The commissioner may, from time to time as conditions warrant, after notice and hearing, promulgate reasonable rules and regulations, and amendments and additions to those rules and regulations, as are necessary or advisable, to establish and maintain a procedure for the filing and approval of documents, as defined in this section, prior to their issuance, delivery, or use in this state, in lieu of the requirements of submission, filing, or approval for the documents presently provided in Section 10205, 10205.5, 10205.6, 10225, 10270, 10270.1, 10270.57, 10270.9, 10270.91, 10270.92, 10270.93, 10290, 10292, 11066, 11069, or 11658. For purposes of this section, document includes, but is not limited to, every form of contract, insurance policy, application, rider, endorsement, amendment, insert policy page, certificate, or other evidence or notice of insurance, fill-in material, schedules of rates and classifications of risks, and any modification to any document, which is subject to the requirements of any of the sections described in this subdivision.
(b)Any rule or regulation shall be promulgated in accordance with the procedure provided in Chapter 3.5 (commencing with Section 11340) of Part 1 of Division 3 of Title 2 of the Government Code.
(c)In promulgating any rule or regulation, the commissioner may give consideration to the following circumstances:
(1)Whether all documents, the submission, filing, or approval of which is governed by any of the sections described in subdivision (a), or only a portion of those documents described in the rule or regulation, shall be subject to the rule or regulation.
(2)Whether certain documents or portions of those documents should be regulated in respect of submission, filing, or approval in a fashion differing from similar requirements applicable to other documents.
(3)Whether varying procedures may be made applicable among admitted insurers in respect of the submission, filing or approval predicated, in whole or in part, upon the following factors: (A) the age and size of the submitting insurer, (B) the period of its licensing in this state for the class or classes of insurance represented by the documents, (C) the nature and number of prior submissions of similar documents and the disposition of those prior submissions by the commissioner, (D) and similar criteria that is relevant to a determination that the submitting insurer has demonstrated compliance with all applicable statutes, rules, and regulations relating to documents comprising prior submissions.
(d)In promulgating any rules and regulations, the commissioner shall, so far as practical, describe or define certain provisions: (1) that the commissioner will authorize without review when accompanied by a certification prescribed by him or her by rule, and (2) that the commissioner will under no circumstances approve.
(e)The commissioner shall establish a period of time, not shorter than one year, during which any change in the provisions that pursuant to subdivision (d), he or she has provided he or she will under no circumstances approve, will not apply to policies filed prior to the effective date of the change.
(f)Except as otherwise provided in this section, any document approved by the commissioner pursuant to rules and regulations authorized by this section may have its approval withdrawn in accordance with subdivision (d) of Section 10291.5 or Section 12957, whichever is applicable.
(a)The commissioner may, from time to time as conditions warrant, after notice and hearing, promulgate such reasonable rules and regulations, and amendments and additions thereto, to those rules and regulations, as are necessary or advisable, to establish and maintain a procedure for the filing and approval of documents, as defined in this section, prior to their issuance, delivery, or use in this state, in lieu of the requirements of submission, filing, or approval for the documents presently provided in Section 10205, 10205.5, 10205.6, 10225, 10270, 10270.1, 10270.57, 10270.9, 10270.91, 10270.92, 10270.93, 10290, 10292, 11066, 11069, 11513, 11513.1, 11513.2, 11515, or 11658. For purposes of this section, document includes, but is not limited to, every form of contract, insurance policy, application, rider, endorsement, amendment, insert policy page, certificate, or other evidence or notice of insurance, fill-in material, schedules of rates and classifications of risks, and any modification to any document, which is subject to the requirements of any of the enumerated sections. sections described in this subdivision.
(b)Any such rule or regulation shall be promulgated in accordance with the procedure provided in Chapter 3.5 (commencing with Section 11340) of Part 1 of Division 3 of Title 2 of the Government Code.
(c)In promulgating any such rule or regulation, the commissioner may give consideration to the following circumstances:
(1)Whether all such documents, the submission, filing, or approval of which is governed by any of the foregoing enumerated sections, sections described in subdivision (a), or only a portion thereof of those documents described in the rule or regulation, shall be subject thereto. to the rule or regulation.
(2)Whether certain documents or portions thereof of those documents should be regulated in respect of submission, filing, or approval in a fashion differing from similar requirements applicable to other documents.
(3)Whether varying procedures may be made applicable among admitted insurers in respect of the submission, filing or approval predicated, in whole or in part, upon such the following factors as: (A) the age and size of the submitting insurer, (B) the period of its licensing in this state for the class or classes of insurance represented by the documents, (C) the nature and number of prior submissions of similar documents and the disposition thereof of those prior submissions by the commissioner, (D) and similar criteria which that is relevant to a determination that the submitting insurer has demonstrated compliance with all applicable statutes, rules, and regulations relating to documents comprising prior submissions.
(d)In promulgating any such rules and regulations, the commissioner shall, so far as practical, describe or define certain provisions: (1) which that the commissioner will authorize without review when accompanied by a certification prescribed by him or her by rule, and (2) which that the commissioner will under no circumstances approve.
(e)The commissioner shall establish a period of time, not shorter than one year, during which any change in the provisions which that pursuant to subdivision (d), he or she has provided he or she will under no circumstances approve, will not apply to policies filed prior to the effective date of the change.
(f)Except as otherwise provided in this section section, any document approved by the commissioner pursuant to rules and regulations authorized by this section may have its approval withdrawn in accordance with subdivision (d) of Section 10291.5 or Section 12957, whichever is applicable.
|
Date
|
Status
|
|---|---|
| May 28, 2015 | Referred to Com. on INS. |
| Aug 30, 2016 | Enrolled and presented to the Governor at 4 p.m. |
| Aug 23, 2016 | Senate amendments concurred in. To Engrossing and Enrolling. (Ayes 80. Noes 0. Page 6106.). |
| Aug 23, 2016 | Senate amendments concurred in. To Engrossing and Enrolling. |
| Aug 16, 2016 | Read third time. Passed. Ordered to the Assembly. (Ayes 39. Noes 0.). |
| Aug 16, 2016 | Read third time. Passed. Ordered to the Assembly. (Ayes 39. Noes 0. Page 5009.). |
| Aug 16, 2016 | Read third time. Passed. Ordered to the Assembly. |
| Aug 16, 2016 | In Assembly. Concurrence in Senate amendments pending. May be considered on or after August 18 pursuant to Assembly Rule 77. |
| Jun 29, 2016 | Read second time and amended. Ordered to third reading. |
| Jun 28, 2016 | From committee: Amend, and do pass as amended. (Ayes 8. Noes 0.) (June 22). |
| Jun 6, 2016 | In committee: Hearing postponed by committee. |
| Mar 10, 2016 | From committee chair, with author's amendments: Amend, and re-refer to committee. Read second time, amended, and re-referred to Com. on INS. |
| Jun 30, 2015 | In committee: Set, first hearing. Hearing canceled at the request of author. |
| Feb 24, 2015 | Read first time. To print. |
| May 14, 2015 | Read third time. Passed. Ordered to the Senate. (Ayes 78. Noes 0. Page 1452.) |
| May 14, 2015 | Read third time. Passed. Ordered to the Senate. |
| May 14, 2015 | In Senate. Read first time. To Com. on RLS. for assignment. |
| May 7, 2015 | Read second time. Ordered to Consent Calendar. |
| May 6, 2015 | From committee: Do pass. To Consent Calendar. (Ayes 13. Noes 0.) (May 6). |
| Apr 29, 2015 | Re-referred to Com. on INS. |
| Apr 28, 2015 | From committee chair, with author's amendments: Amend, and re-refer to Com. on INS. Read second time and amended. |
| Apr 6, 2015 | Re-referred to Com. on INS. |
| Mar 26, 2015 | Referred to Com. on INS. |
| Mar 26, 2015 | From committee chair, with author's amendments: Amend, and re-refer to Com. on INS. Read second time and amended. |
| Feb 25, 2015 | From printer. May be heard in committee March 27. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Aug 23, 2016 | AB 565 COOLEY Concurrence in Senate Amendments | Assembly Floor |
Passed |
|
| Aug 16, 2016 | Assembly 3rd Reading AB565 Cooley By Roth | Senate Floor |
Passed |
|
| Jun 22, 2016 | Do pass as amended | Senate Standing Committee on Insurance |
Passed |
|
| May 14, 2015 | AB 565 COOLEY Consent Calendar Second Day Regular Session | Assembly Floor |
Passed |
|
| May 6, 2015 | Do pass. To Consent Calendar. | Assembly Standing Committee on Insurance |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| American Council Of Life Insurers | ** Support | Aug 16, 2016 |
| California Department of Insurance | ** Against | Aug 16, 2016 |
CONCURRENCE IN SENATE AMENDMENTS
CSA1 Bill Id:AB 565
Author:(Cooley)
As Amended Ver:June 29, 2016
Majority vote
ASSEMBLY: | 78-0 | (May 14, 2015) | SENATE: | 39-0 | (August 16, 2016) |
Original Committee Reference: INS.
SUMMARY: The bill revises the standards for group life insurance related to dependent coverage and waiver of premium benefits. Specifically, this bill:
- Revises the definition of "dependent" for the purpose of issuing dependent coverage, to clarify that coverage for dependents over 18 is optional at any age up to 26.
- Authorizes an insurer offering a waiver of premium benefit in a group master policy to waive all premiums due for the period of total disability until the insured attains 65 years of age if the insured develops a total disability before age 60.
- Authorizes an insurer offering a waiver of premium benefit in a group master policy to offer a policy that excludes disabilities developed once the insured reaches age 60 or older.
- Requires an insurer to offer to renew a policy that continues an in-force waiver of premium benefit for group policies issued prior to January 1, 2017 (this ensures that the policyholders have the option to keep the more generous benefits if the policy provides those benefits at the time of renewal).
The Senate amendments delete the provision governing the mailing of notice to group life insurance certificate holders passed by the Assembly, and add the current contents of the bill.
EXISTING LAW:
- Establishes standards for life and disability insurance, and subjects life and disability insurers to regulation by Department of Insurance (DOI).
- Authorizes life insurers to issue a master group life insurance policy to employers, unions, credit unions and other qualified associations, so that individual members of the group may obtain coverage through that master policy.
- Permits insurers to cover dependents of an insured employee.
- Defines "dependent" to include the insured's spouse, all children from birth until 26 years of age, or a child 26 years of age or older that suffers from a qualifying disability and is incapable of self-sustaining employment.
- Authorizes insurers to include a benefit that waives premium charges on life insurance policies when the insured suffers a total disability ("waiver of premium benefit").
- Requires an insurer offering a waiver of premium benefit to waive all premiums due for the entire period of total disability if the insured develops a total disability before age 60.
- Requires an insurer offering a waiver of premium benefit to waive all premiums until the insured reaches age 65 if the insured develops a total disability after attaining age 60.
FISCAL EFFECT: None
COMMENTS:
- Purpose. This bill more closely aligns California law to national standards for group life insurance policies by permitting the insurer to limit the waiver of premium benefit period to a retirement proxy age no younger than age 65 and to exclude disabilities that develop after age 60. However, insurers must give policyholders the option to keep the more generous benefits at renewal. The bill also clarifies that the owner of a group life insurance policy may choose whether to offer coverage for adult dependents with a maximum age of 26.
- Background. Group life insurance policies provide term life coverage to group members (commonly a benefit provided to employees by their employer or by associations as a benefit to their members) under a master policy owned by the employer or association. Individual members can then opt to purchase the coverage during a defined enrollment period (typically within a number of months of being hired or joining the association). Employers offering group life coverage as a benefit commonly pay for $50,000 of coverage for all employees and the individual employees can opt to pay for a higher benefit amount individually. These policies are typically less expensive than individual life insurance policies and members can obtain coverage without medical underwriting. The master policyholder (employer or association) selects a standard set of benefits offered to all group members. Coverage typically ends when the member leaves the group or the employment ends, although employees may convert their group policy to a permanent, individual policy at that time.
- Dependents. Some group life insurance policies allow group members to purchase coverage on their dependents (spouses and children up to the age of 26 generally). This bill clarifies that the employer or association may choose to limit dependent coverage to any age between 18 and 26.
- Waiver of Premium. Life insurers may offer a "waiver of premium" benefit that prevents a policy from lapsing during periods when the insured can no longer work by waiving the premium otherwise required to maintain the policy. This benefit will pay premium until either the disability ends or the insured attains a specific age. Prior legislation, SB 1449 (Calderon), Chapter 567, Statutes of 2012, established specific standards for minimum waiver periods based on whether the insured develops a disability before or after reaching the age of 60. SB 1449 was based on national standards designed for individual life insurance policies. The standards were revised for group policies in 2013 and the insurance industry began raising concerns that California law was misaligned with these standards resulting in increased premium charges for group coverage. AB 2578 (Dababneh), Chapter 360, Statutes of 2014, made some adjustments to California's law, but did not fully address those factors driving premium increases. This bill is designed to correct the remaining misalignment and prevent further cost increases for group life insurance.
Analysis Prepared by: Paul Riches / INS. / (916) 319-2086 FN: 0004373
Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | AB |
THIRD READING
Bill No: AB 565
: 6/29/16
SENATE INSURANCE COMMITTEE: 8-0, 6/22/16
AYES: Roth, Gaines, Berryhill, Glazer, Hall, Hernandez, Mitchell, Wieckowski
NO VOTE RECORDED: Liu
ASSEMBLY FLOOR: Not relevant
SOURCE: Association of California Life and Health Insurance Companies
DIGEST: This bill revises the standards for group life insurance related to dependent coverage and waiver of premium benefits.
Existing law:
- Establishes standards for life and disability insurance and subjects life and disability insurers to regulation by California Department of Insurance (CDI).
- Authorizes life insurers to issue a master group life insurance policy to employers, unions, credit unions and other qualified associations, so that individual members of the group may obtain coverage through that master policy.
- Permits insurers to cover dependents of an insured employee.
- Defines “dependent” to include the insured’s spouse, all children from birth until 26 years of age, or a child 26 years of age or older that suffers from a qualifying disability and is incapable of self-sustaining employment.
- Authorizes insurers to include a benefit that waives premium charges on life insurance policies when the insured suffers a total disability (“waiver of premium benefit”).
- Requires an insurer, offering a waiver of premium benefit, to waive all premiums due for the entire period of total disability if the insured develops a total disability before age 60.
- Requires an insurer, offering a waiver of premium benefit, to waive all premiums until the insured reaches age 65 if the insured develops a total disability after attaining age 60.
This bill:
- Revises the definition of “dependent” for the purpose of issuing dependent coverage, to include children up to the age of 26.
- Authorizes an insurer offering a waiver of premium benefit in a group master policy to waive all premiums due for the period of total disability until the insured attains 65 years of age if the insured develops a total disability before age 60.
- Authorizes an insurer offering a waiver of premium benefit in a group master policy to offer a policy that excludes disabilities developed once the insured reaches age 60 or older.
- Requires an insurer to offer to renew a policy that continues an in-force waiver of premium benefit for group policies issued prior to January 1, 2017 (this ensures that the policyholders the option to keep the more generous benefits if the policy provides those benefits at the time of renewal).
Group life insurance policies provide coverage to group members under a master policy usually issued to an employer or association. These policies are less expensive than individual counterparts. Premiums for group policies are tied to the claims experience of the group and higher utilization may result in an increase in premium for the entire group. The master policyholder selects a standard set of benefits and some policyholders, such as employers, may pay the premium. Coverage typically ends when the member leaves the group or the employment ends, although employees may convert a group certificate to a permanent, individual policy at that time. According to the sponsor, most group insurance is renewed on an annual term basis and offered to active employees. This bill addresses special types of benefits that attach to group life insurance policies.
Dependent life insurance covers a member’s spouse or qualified child and pays the benefit to the member when a covered dependent dies. In 2011, SB 220 (Price, Chapter 126, Statutes of 2011) authorized insurers to cover children “from birth until 26 years of age.” This bill clarifies that an insurer may permit a policyholder to choose a maximum age limit at or between 18 and 26. The changes made by SB 220 also created some confusion as to whether coverage may be limited based on factors related to dependency including marital status, student status, residency, or whether the group member is supporting the child. On that point, this bill is intended to return the law to what it was prior to SB 220 so that an insurer may limit dependent coverage on actuarially justified factors or factors that truly relate to whether a child is a “dependent.”
Life insurers may waive premium during periods when the insured can no longer work so that coverage remains in force until the end of the disability or the insured reaches an age specified by the policy. SB 1449 (Calderon, 2012, Chapter 567, Statutes of 2012) established specific standards for these benefits including minimum waiver periods based on whether the insured develops a disability before or after reaching the age of 60. SB 1449 was based on standards developed by the Interstate Insurance Product Regulation Commission (IIPRC) designed for individual life insurance policies that had no connection to retirement or termination of employment. (The IIPRC establishes a uniform set of standards and a single policy approval process for its 44 participating states.) In 2013, the IIPRC adopted standards specific to group policies, and members of the insurance industry began raising concerns that California’s standards were misaligned with group coverage typically offered to employers and would significantly increase premium. The following year, AB 2578 (Dababneh, Chapter 360, Statutes of 2014) made minor adjustments to California’s standards, but did not fully address concerns related to cost. AB 565 more closely aligns California law to the IIPRC standards applicable to group policies by permitting the insurer to limit the waiver of premium benefit period to a retirement proxy age no younger than age 65 and to exclude disabilities that develop after age 60. However, insurers must give policyholders the option to keep the more generous benefits at renewal.
FISCAL EFFECT: Appropriation: Fiscal Com.: Local:
Association of California Life and Health Insurance Companies (source)
American Council of Life Insurers
OPPOSITION: (Verified 7/25/16)
None received
ARGUMENTS IN SUPPORT: ACLHIC points out that unlike the federal Affordable Care Act that provides coverage that benefits dependent children, dependent life insurance coverage pays the benefit the parent/group member. A requirement that forces coverage for all children under age 26 unduly restricts options for employers and affinity groups.
ACLHIC also argues that group life insurance is usually provided during an insured’s span of employment with the group policyholder or with a known set of limitations as part of affinity group coverage. Treating group coverage like individual coverage could lead employers and groups to forego the waiver of premium benefit due to the added expense. As a result, employees would be deprived of the ability to have their premium paid while disabled, at a time they most need financial help.
7/25/16 11:29:54
**** END ****
Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | AB |
THIRD READING
Bill No: AB 565
: 6/29/16
SENATE INSURANCE COMMITTEE: 8-0, 6/22/16
AYES: Roth, Gaines, Berryhill, Glazer, Hall, Hernandez, Mitchell, Wieckowski
NO VOTE RECORDED: Liu
ASSEMBLY FLOOR: Not relevant
SOURCE: Association of California Life and Health Insurance Companies
DIGEST: This bill revises the standards for group life insurance related to dependent coverage and waiver of premium benefits.
Existing law:
- Establishes standards for life and disability insurance and subjects life and disability insurers to regulation by California Department of Insurance (CDI).
- Authorizes life insurers to issue a master group life insurance policy to employers, unions, credit unions and other qualified associations, so that individual members of the group may obtain coverage through that master policy.
- Permits insurers to cover dependents of an insured employee.
- Defines “dependent” to include the insured’s spouse, all children from birth until 26 years of age, or a child 26 years of age or older that suffers from a qualifying disability and is incapable of self-sustaining employment.
- Authorizes insurers to include a benefit that waives premium charges on life insurance policies when the insured suffers a total disability (“waiver of premium benefit”).
- Requires an insurer, offering a waiver of premium benefit, to waive all premiums due for the entire period of total disability if the insured develops a total disability before age 60.
- Requires an insurer, offering a waiver of premium benefit, to waive all premiums until the insured reaches age 65 if the insured develops a total disability after attaining age 60.
This bill:
- Revises the definition of “dependent” for the purpose of issuing dependent coverage, to include children up to the age of 26.
- Authorizes an insurer offering a waiver of premium benefit in a group master policy to waive all premiums due for the period of total disability until the insured attains 65 years of age if the insured develops a total disability before age 60.
- Authorizes an insurer offering a waiver of premium benefit in a group master policy to offer a policy that excludes disabilities developed once the insured reaches age 60 or older.
- Requires an insurer to offer to renew a policy that continues an in-force waiver of premium benefit for group policies issued prior to January 1, 2017 (this ensures that the policyholders the option to keep the more generous benefits if the policy provides those benefits at the time of renewal).
Group life insurance policies provide coverage to group members under a master policy usually issued to an employer or association. These policies are less expensive than individual counterparts. Premiums for group policies are tied to the claims experience of the group and higher utilization may result in an increase in premium for the entire group. The master policyholder selects a standard set of benefits and some policyholders, such as employers, may pay the premium. Coverage typically ends when the member leaves the group or the employment ends, although employees may convert a group certificate to a permanent, individual policy at that time. According to the sponsor, most group insurance is renewed on an annual term basis and offered to active employees. This bill addresses special types of benefits that attach to group life insurance policies.
Dependent life insurance covers a member’s spouse or qualified child and pays the benefit to the member when a covered dependent dies. In 2011, SB 220 (Price, Chapter 126, Statutes of 2011) authorized insurers to cover children “from birth until 26 years of age.” This bill clarifies that an insurer may permit a policyholder to choose a maximum age limit at or between 18 and 26. The changes made by SB 220 also created some confusion as to whether coverage may be limited based on factors related to dependency including marital status, student status, residency, or whether the group member is supporting the child. On that point, this bill is intended to return the law to what it was prior to SB 220 so that an insurer may limit dependent coverage on actuarially justified factors or factors that truly relate to whether a child is a “dependent.”
Life insurers may waive premium during periods when the insured can no longer work so that coverage remains in force until the end of the disability or the insured reaches an age specified by the policy. SB 1449 (Calderon, 2012, Chapter 567, Statutes of 2012) established specific standards for these benefits including minimum waiver periods based on whether the insured develops a disability before or after reaching the age of 60. SB 1449 was based on standards developed by the Interstate Insurance Product Regulation Commission (IIPRC) designed for individual life insurance policies that had no connection to retirement or termination of employment. (The IIPRC establishes a uniform set of standards and a single policy approval process for its 44 participating states.) In 2013, the IIPRC adopted standards specific to group policies, and members of the insurance industry began raising concerns that California’s standards were misaligned with group coverage typically offered to employers and would significantly increase premium. The following year, AB 2578 (Dababneh, Chapter 360, Statutes of 2014) made minor adjustments to California’s standards, but did not fully address concerns related to cost. AB 565 more closely aligns California law to the IIPRC standards applicable to group policies by permitting the insurer to limit the waiver of premium benefit period to a retirement proxy age no younger than age 65 and to exclude disabilities that develop after age 60. However, insurers must give policyholders the option to keep the more generous benefits at renewal.
FISCAL EFFECT: Appropriation: Fiscal Com.: Local:
Association of California Life and Health Insurance Companies (source)
American Council of Life Insurers
OPPOSITION: (Verified 6/29/16)
California Department of Insurance
ARGUMENTS IN SUPPORT: ACLHIC points out that unlike the federal Affordable Care Act that provides coverage that benefits dependent children, dependent life insurance coverage pays the benefit the parent/group member. A requirement that forces coverage for all children under age 26 unduly restricts options for employers and affinity groups.
ACLHIC also argues that group life insurance is usually provided during an insured’s span of employment with the group policyholder or with a known set of limitations as part of affinity group coverage. Treating group coverage like individual coverage could lead employers and groups to forego the waiver of premium benefit due to the added expense. As a result, employees would be deprived of the ability to have their premium paid while disabled, at a time they most need financial help.
ARGUMENTS IN OPPOSITION: CDI raised a concern regarding the March 10, 2016 version of the bill that policyholders currently holding the more generous benefits will be forced to take less generous benefits authorized by this bill. Amendments adopted on June 29, 2016, addressed that and other concerns and CDI will reconsider its position once it reviews the current version of the bill.
6/29/16 15:56:23
**** END ****
SENATE COMMITTEE ON INSURANCE
Senator Richard Roth, Chair
2015 - 2016 Regular
Bill No: AB 565 Hearing Date: June 22, 2016
Author: | Cooley | ||
Version: | March 10, 2016 Amended | ||
Urgency: | No | Fiscal: | No |
Consultant: | Hugh Slayden | ||
Subject: Group life and disability insurance: required provisions
SUMMARY
Revises the standards for group life insurance related to waiver of premium benefits and dependent coverage.
DIGEST
Existing law
- Establishes standards for life and disability insurance and subjects life and disability insurers to regulation by the California Department of Insurance (CDI).
- Authorizes life insurers to issue a master group life insurance policy to employers, unions, credit unions and other qualified associations, so that individual members of the group may obtain coverage through that master policy.
- Requires that every master policy include a provision that the insurer shall issue to the policyholder an individual certificate for distribution to the insured employee or group member that describes the insurance coverage.
- Permits an insurer to cover dependents of an insured employee, under specified conditions, so that the employee receives a death benefit on death of the dependent.
- Defines dependents to include the insured’s spouse, all children from birth until 26 years of age, or a child 26 years of age or older that suffers from a qualifying disability and is incapable of self-sustaining employment.
- Authorizes insurers to include a benefit that waives premium charges on life insurance policies when the insured suffers a total disability.
- Defines “total disability” as, during the first 24 months, the inability to perform the duties of the insured’s current job due to sickness or bodily injury and, after the first 24 months, the inability to perform the duties of any suitable job due to sickness or bodily injury.
- Requires an insurer, under waiver of premium benefit under a group policy, to waive all premiums due for the entire period of total disability if the insured develops a total disability before age 60.
- Requires an insurer, under waiver of premium benefit under a group policy, to waive all premiums until the insured reaches age 65 if the insured develops a totally disability after attaining age 60.
This bill
- Permits an insurer to issue an individual certificate directly to the group member.
- Revises the definition of “dependent” for the purpose of issuing dependent coverage, to include children up to the age of 26.
- Authorizes the insurer to permit the policyholder to elect coverage for dependent children based on factors such as marital status, student status, residency, or support requirements and, for dependent children over the age of majority, the group policyholder may elect coverage at age variations up to the limiting age.
- Requires an insurer, under waiver of premium benefit under a group policy, to waive all premiums due for the period of total disability until the insured attains 65 years of age if the insured develops a total disability before age 60.
- Authorizes an insurer, under waiver of premium benefit, to offer a policy that excludes disabilities developed once the insured reaches age 60 or older, but if the insurer offers that policy, it must also offer a policy that waives premiums until the age of 65.
COMMENTS
- Purpose of the bill According to the author, AB 565 clarifies that group life insurance policies are allowed, but not required, to provide coverage for the dependents of employees up to age 26. It also clarifies that a group life waiver of premium benefit is not required to be offered after age 60 and may end at separation from the group or at age 65 – a change that will align California group life provisions with national standards.
- Background Group life insurance policies provide coverage to group members under a master policy. Each insured receives a certificate evidencing coverage. Group coverage is usually purchased through an employer, but may be purchased through other authorized associations. These policies are less expensive than individual counterparts and a medical exam is not usually required.
Group policies provide a standard set of benefits chosen by the master policyholder. For example, an employer may select the benefits and pay some or all of premium. Premiums for group policies are tied to the claims experience of the group; claims costs will result in increases in premium for the entire group. Coverage typically ends when the member leaves the group, such as when an employee changes jobs or retires. Employees have the right to convert the certificate to a permanent, individual policy when the employment relationship ends. However, the individual must choose from an individual policy offered by that insurer and pay the premium.
According to the Association of California Life and Health Insurance Companies (ACLHIC), most group insurance is renewed on an annual term basis and offered to active employees. Individual policies are usually for longer terms or permanent (do not expire and the contract conditions remain fixed) and do not depend on employment or association.
Dependent Coverage. Dependent life insurance covers a member’s spouse or qualified child and pays the benefit to the member when a covered dependent dies. In 2011, SB 220 (Price), Chapter 126, Statutes of 2011, authorized insurers to cover children “from birth until 26 years of age.” However, stakeholders disagree as to whether insurer must cover all children up to age 26, or whether an insurer may cover children up to a selected maximum age that is no greater than age 26. This bill would clarify that an insurer may offer a policyholder the option to choose a maximum age limit at or between 18 and 26. It also expressly provides that coverage may be limited based on factors related to dependency including marital status, student status, residency, or whether the group member is supporting the child.
Waiver of Premium. Insurance coverage designed to replace lost income due to total disability often terminates at age 65. These policies are a form of disability (not life) insurance and subject to a different set of standards. Life insurers may waive premium during periods when the insured can no longer work so that coverage remains in force until the end of the disability or the insured reaches an age specified by the policy. This feature does not replace income or provide a cash benefit.
Prior to 2013, CDI applied disability insurance standards to life insurance policies that waive premium for disability. The application of dual standards presented a significant obstacle for insurers to introduce premium waivers into the California market. SB 1449 (Calderon, 2012), Chapter 567, Statutes of 2012, established specific standards for waivers of premium including minimum waiver periods based on whether the insured develops a disability before or after reaching the age of 60. SB 1449 was based on standards developed by the Interstate Insurance Product Regulation Commission (IIPRC) designed for individual life insurance policies that had no connection to retirement or termination of employment. (The IIPRC establishes a uniform set of standards and a single policy approval process for its 44 participating states; the approved product may be sold in all member states.)
In 2013, after the enactment of SB 1449, the IIPRC adopted standards specific to group policies that permit the insurer to require that the disability begin before age 60 and that permit the insurer to terminate the waiver at set age not less than age 65. At the same time, industry stakeholders began raising concerns that standards established by SB 1449 made these policies unaffordable. In response, the Legislature enacted AB 2578 (Dababneh), Chapter 360, Statutes of 2014, permitting insurers to limit the waiver to the period of disability.
AB 565 continues the approach taken by AB 2578 and more closely aligns California law to the IIPRC standards applicable to group policies. Similar to disability income insurance, this bill permits insurers to terminate the waiver of premium benefit at a proxy retirement age (65 years or older) when the insured develops a disability before age 60. It also permits the insurer to limit the waiver of premium benefit to disabilities developed before the age of 60, even if the insured remains a member of the group.
- Support ACLHIC points out that unlike the federal Affordable Care Act that provides coverage that benefits dependent children, dependent life insurance coverage pays the benefit the parent/group member. An interpretation of existing law that requires coverage for all children under age 26 unduly restricts options for employers and affinity groups.
ACLHIC also argues that group life insurance is usually provided during an insured’s span of employment with the group policyholder or with a known set of limitations as part of affinity group coverage. Treating group coverage like individual coverage could lead employers and groups to forego the waiver of premium benefit due to the added expense. As a result, employees would be deprived of the ability to have their premium paid while disabled, at a time they most need financial help.
- Opposition CDI has raised concerns that subclassifications of dependent coverage might not be actuarially justified. CDI also questions the assertion that the existing standards are not cost-effective. Additionally, CDI expresses concerns that policyholders currently holding the more generous benefits required under existing law will be forced to take the less generous benefits authorized by this bill.
- Suggested Amendments
Amendments to Section 10270.6 that authorize the group insurer to deliver certificates directly to group members are the result of a drafting error.
The author has agreed to take amendments that address concerns raised by CDI in its letter of opposition. The amendments would do the following:
- Remove language that explicitly authorizes the group policyholder to select groups of children based on specified factors, such as marital status, student status, residency, or support requirements. Stakeholders agree that such factors may be relevant to determining in whether children of the insured are actually dependent on the insured. However, SB 220 unintentionally required insurers to cover all children up to age 26 and severely restricted a master policyholder’s ability to limit coverage to what they view as actual dependents. These amendments are intended to return the law, in that regard, to what it was prior to SB 220, and continue the prior practice of evaluating the validity of factors on a case-by-case basis according to their actuarial relevancy to actual dependency, insurable interest, and impact on mortality.
- Require insurers to offer a master policyholder the option to renew the more generous waiver of premium period. This bill would allow insurers to offer less generous periods of waived premium when an insured develops a qualifying disability. CDI expressed concerns that existing master policyholders may be forced to give up these benefits under the new standards. These amendments are intended to give the master policyholder the option to continue the more generous benefits on subsequent renewals. Although, the insurer would not be required to offer the more generous benefit on renewal in later years if the policyholder chooses the less generous option, representatives of the insurance industry explain that an insurer would likely accommodate a request by the policyholder to add the more generous benefit (but at a higher premium).
POSITIONS
Support
Association of California Life and Health Insurance Companies (sponsor)
American Council of Life Insurers
Oppose
California Department of Insurance
-- END --
AB 565
Page 1
Date of Hearing: May 6, 2015
ASSEMBLY COMMITTEE ON INSURANCE
Tom Daly, Chair
AB 565
(Cooley) – As Amended April 28, 2015
SUBJECT: Group Disability Insurance
SUMMARY: Permits an insurer to send a certificate of insurance directly to an individual insured who is insured by a group disability policy.
EXISTING LAW:
Specifies that group disability insurance contracts contain a provision requiring insurers issuing an insurance certificate for an individual insured in a group disability policy to provide the certificate to the policyholder, who will then forward it to the individual insured.
FISCAL EFFECT: Undetermined
COMMENTS:
Purpose. This bill will provide insurers with greater flexibility when serving customers who are covered under a group disability insurance policy. Current law requires insurers offering group disability policies to route the certificate of insurance for an individual member of the group through the policyholder (generally the employer) who then is responsible for delivering it to the individual insured. This bill will give employers and insurers the option to allow the insurer to deliver the certificate of insurance directly to the insured and reduce the administrative burden on employers who choose to offer group disability insurance to their employees.
Disability Income Insurance. Disability income (DI) insurance is an insurance product that provides individuals with a cash benefit if they become disabled and are unable to work. DI insurance can be purchased to cover either short or long term disability. Many employers offer a "group" DI policy as an optional employee benefit. DI insurance is a niche product as there are a number of public DI programs available to California workers, including workers compensation temporary disability benefits, the State Disability Insurance program administered by the Employment Development Department, and the permanent disability benefits offered through Social Security.
REGISTERED SUPPORT / OPPOSITION:
Support
Association of California Life and Health Insurance Companies
Opposition
None received
Analysis Prepared by: Paul Riches / INS. / (916) 319-2086
Discussed in Hearing
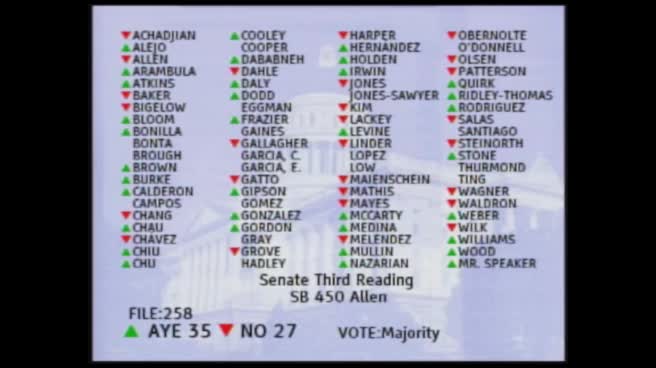 51SEC
Assembly Floor
 1MIN
Senate Floor
 11MIN
Senate Standing Committee on Insurance
Bill Author
Bill Co-Author(s):