AB 2350: Unclaimed property.
- Session Year: 2017-2018
- House: Assembly
- Latest Version Date: 2018-09-14
(1)Existing law provides for the escheat of property to the state. Existing law requires all property that escheats to the state to be deposited into the Abandoned Property Account in the Unclaimed Property Fund, which is continuously appropriated for specified purposes. Existing law establishes procedures for submitting a claim for property that has escheated.
This bill would create in the Special Deposit Fund the Unclaimed Property Offset Account as a continuously appropriated fund for the payment of moneys to a state or local governmental entity to offset the moneys owed by a person claiming to be the owner of unclaimed property that has escheated to the state.
(2)Existing law requires funds in Interest on Lawyers Trust Accounts (IOLTA) that escheat to the state to be deposited into the Abandoned IOLTA Property Account, which is within the Unclaimed Property Fund. Existing law establishes the IOLTA Claims Reserve Subaccount within the account and requires that 25% of IOLTA escheated funds be deposited into the subaccount to be used by the Controller, upon appropriation by the Legislature, for the purposes of paying refunds, claims, and costs associated with escheated IOLTA funds.
This bill would make the IOLTA Claims Reserve Subaccount a continuously appropriated fund and remove the authorization for the subaccount to be used for general costs associated with escheated IOLTA funds.
(1)Existing law provides for the escheat of property to the state. Existing law requires all property that escheats to the state to be deposited into the Abandoned Property Account in the Unclaimed Property Fund, which is continuously appropriated for specified purposes. Existing law establishes procedures for submitting a claim for property that has escheated.
This bill would create in the Special Deposit Fund the Unclaimed Property Offset Account as a continuously appropriated fund for the payment of moneys to a state or local governmental entity to offset the moneys owed by a person claiming to be the owner of unclaimed property that has escheated to the state.
(2)Existing law requires funds in Interest on Lawyers Trust Accounts (IOLTA) that escheat to the state to be deposited into the Abandoned IOLTA Property Account, which is within the Unclaimed Property Fund. Existing law establishes the IOLTA Claims Reserve Subaccount within the account and requires that 25% of IOLTA escheated funds be deposited into the subaccount to be used by the Controller, upon appropriation by the Legislature, for the purposes of paying refunds, claims, and costs associated with escheated IOLTA funds.
This bill would make the IOLTA Claims Reserve Subaccount a continuously appropriated fund and remove the authorization for the subaccount to be used for general costs associated with escheated IOLTA funds.
(1)Existing law provides for the escheat of property to the state. Existing law requires all property that escheats to the state to be deposited into the Abandoned Property Account in the Unclaimed Property Fund, which is continuously appropriated for specified purposes. Existing law establishes procedures for submitting a claim for property that has escheated.
This bill would create in the Special Deposit Fund the Unclaimed Property Offset Account as a continuously appropriated fund for the payment of moneys to a state or local governmental entity to offset the moneys owed by a person claiming to be the owner of unclaimed property that has escheated to the state.
(2)Existing law requires funds in Interest on Lawyers Trust Accounts (IOLTA) that escheat to the state to be deposited into the Abandoned IOLTA Property Account, which is within the Unclaimed Property Fund. Existing law establishes the IOLTA Claims Reserve Subaccount within the account and requires that 25% of IOLTA escheated funds be deposited into the subaccount to be used by the Controller, upon appropriation by the Legislature, for the purposes of paying refunds, claims, and costs associated with escheated IOLTA funds.
This bill would make the IOLTA Claims Reserve Subaccount a continuously appropriated fund. fund and remove the authorization for the subaccount to be used for general costs associated with escheated IOLTA funds.
(1)Existing law provides for the escheat of property to the state. Existing law requires all property that escheats to the state to be deposited into the Abandoned Property Account in the Unclaimed Property Fund, which is continuously appropriated for specified purposes. Existing law establishes procedures for submitting a claim for property that has escheated.
This bill would create in the Special Deposit Fund the Unclaimed Property Offset Account as a continuously appropriated fund for the payment of moneys to a state or local governmental entity to offset the moneys owed by a person claiming to be the owner of unclaimed property that has escheated to the state.
(2)Existing law requires funds in Interest on Lawyers Trust Accounts (IOLTA) that escheat to the state to be deposited into the Abandoned IOLTA Property Account, which is within the Unclaimed Property Fund. Existing law establishes the IOLTA Claims Reserve Subaccount within the account and requires that 25% of IOLTA escheated funds be deposited into the subaccount to be used by the Controller, upon appropriation by the Legislature, for the purposes of paying refunds, claims, and costs associated with escheated IOLTA funds.
This bill would make the IOLTA Claims Reserve Subaccount a continuously appropriated fund.
(a)Notwithstanding any law, including, but not limited to, Section 1564, all money received under this chapter from funds held in an Interest on Lawyers Trust Account (IOLTA) that escheat to the state shall be administered as set forth in this section. The money shall be deposited into the Abandoned IOLTA Property Account, which is hereby established within the Unclaimed Property Fund.
(b)Twenty-five percent of the money in the Abandoned IOLTA Property Account shall be deposited into the IOLTA Claims Reserve Subaccount, which is hereby established within the Abandoned IOLTA Property Account. Notwithstanding Section 13340 of the Government Code, funds in the subaccount are continuously appropriated to the Controller for the payment of all refunds and claims pursuant to this chapter related to escheated IOLTA funds.
(c)The balance of the funds in the Abandoned IOLTA Property Account, excluding funds in the subaccount, shall be transferred on an annual basis to the Public Interest Attorney Loan Repayment Account established pursuant to Section 6032.5 of the Business and Professions Code. Before making this transfer, the Controller shall record the name and last known address of each person appearing from the holders report to be entitled to the escheated property. The record shall be available for public inspection at all reasonable business hours.
SEC. 2.Section 16378 is added to the Government Code, to read:16378.(a)There is established in the Special Deposit Fund in the State Treasury the Unclaimed Property Offset Account. Notwithstanding Section 13340, moneys in the account are continuously appropriated pursuant to Section 16372 for both of the following purposes:
(1)The payment of moneys to a state agency, local agency, city, county, community college district, special district, or court, or any other state or local governmental entity, to offset the moneys owed by a person claiming to be the owner of unclaimed property that has escheated to the state under Title 10 (commencing with Section 1300) of Part 3 of the Code of Civil Procedure.
(2)The payment of moneys to owners of unclaimed property that has escheated to the state after offsetting moneys paid pursuant to paragraph (1).
(b)The Controller may transfer to the Unclaimed Property Offset Account moneys held by the Controller from property that has escheated to the state under Title 10 (commencing with Section 1300) of Part 3 of the Code of Civil Procedure if the Controller has reason to believe the owner of the property has a debt to a state or local governmental entity.
(a)Notwithstanding any law, including, but not limited to, Section 1564, all money received under this chapter from funds held in an Interest on Lawyers Trust Account (IOLTA) that escheat to the state shall be administered as set forth in this section. The money shall be deposited into the Abandoned IOLTA Property Account, which is hereby established within the Unclaimed Property Fund.
(b)Twenty-five percent of the money in the Abandoned IOLTA Property Account shall be deposited into the IOLTA Claims Reserve Subaccount, which is hereby established within the Abandoned IOLTA Property Account. Notwithstanding Section 13340 of the Government Code, funds in the subaccount are continuously appropriated to the Controller for the payment of all refunds and claims pursuant to this chapter related to escheated IOLTA funds.
(c)The balance of the funds in the Abandoned IOLTA Property Account, excluding funds in the subaccount, shall be transferred on an annual basis to the Public Interest Attorney Loan Repayment Account established pursuant to Section 6032.5 of the Business and Professions Code. Before making this transfer, the Controller shall record the name and last known address of each person appearing from the holders report to be entitled to the escheated property. The record shall be available for public inspection at all reasonable business hours.
SEC. 2.Section 16378 is added to the Government Code, to read:16378.(a)There is established in the Special Deposit Fund in the State Treasury the Unclaimed Property Offset Account. Notwithstanding Section 13340, moneys in the account are continuously appropriated pursuant to Section 16372 for both of the following purposes:
(1)The payment of moneys to a state agency, local agency, city, county, community college district, special district, or court, or any other state or local governmental entity, to offset the moneys owed by a person claiming to be the owner of unclaimed property that has escheated to the state under Title 10 (commencing with Section 1300) of Part 3 of the Code of Civil Procedure.
(2)The payment of moneys to owners of unclaimed property that has escheated to the state after offsetting moneys paid pursuant to paragraph (1).
(b)The Controller may transfer to the Unclaimed Property Offset Account moneys held by the Controller from property that has escheated to the state under Title 10 (commencing with Section 1300) of Part 3 of the Code of Civil Procedure if the Controller has reason to believe the owner of the property has a debt to a state or local governmental entity.
(a)Notwithstanding any law, including, but not limited to, Section 1564, all money received under this chapter from funds held in an Interest on Lawyers Trust Account (IOLTA) that escheat to the state shall be administered as set forth in this section. The money shall be deposited into the Abandoned IOLTA Property Account, which is hereby established within the Unclaimed Property Fund.
(b)Twenty-five percent of the money in the Abandoned IOLTA Property Account shall be deposited into the IOLTA Claims Reserve Subaccount, which is hereby established within the Abandoned IOLTA Property Account. Notwithstanding Section 13340 of the Government Code, funds in the subaccount are continuously appropriated to the Controller for the payment of all refunds, claims, and costs refunds and claims pursuant to this chapter related to escheated IOLTA funds.
(c)The balance of the funds in the Abandoned IOLTA Property Account, excluding funds in the subaccount, shall be transferred on an annual basis to the Public Interest Attorney Loan Repayment Account established pursuant to Section 6032.5 of the Business and Professions Code. Before making this transfer, the Controller shall record the name and last known address of each person appearing from the holders report to be entitled to the escheated property. The record shall be available for public inspection at all reasonable business hours.
SEC. 2.Section 16378 is added to the Government Code, to read:16378.(a)There is established in the Special Deposit Fund in the State Treasury the Unclaimed Property Offset Account. Notwithstanding Section 13340, moneys in the account are continuously appropriated pursuant to Section 16372 for both of the following purposes:
(1)The payment of moneys to a state agency, local agency, city, county, community college district, special district, or court, or any other state or local governmental entity, to offset the moneys owed by a person claiming to be the owner of unclaimed property that has escheated to the state under Title 10 (commencing with Section 1300) of Part 3 of the Code of Civil Procedure.
(2)The payment of moneys to owners of unclaimed property that has escheated to the state after offsetting moneys paid pursuant to paragraph (1).
(b)The Controller may transfer to the Unclaimed Property Offset Account moneys held by the Controller from property that has escheated to the state under Title 10 (commencing with Section 1300) of Part 3 of the Code of Civil Procedure if the Controller has reason to believe the owner of the property has a debt to a state or local governmental entity.
(a)Notwithstanding any law, including, but not limited to, Section 1564, all money received under this chapter from funds held in an Interest on Lawyers Trust Account (IOLTA) that escheat to the state shall be administered as set forth in this section. The money shall be deposited into the Abandoned IOLTA Property Account, which is hereby established within the Unclaimed Property Fund.
(b)Twenty-five percent of the money in the Abandoned IOLTA Property Account shall be deposited into the IOLTA Claims Reserve Subaccount, which is hereby established within the Abandoned IOLTA Property Account. Funds Notwithstanding Section 13340 of the Government Code, funds in the subaccount shall, upon appropriation by the Legislature, be available are continuously appropriated to the Controller for the payment of all refunds, claims, and costs pursuant to this chapter related to escheated IOLTA funds.
(c)The balance of the funds in the Abandoned IOLTA Property Account, excluding funds in the subaccount, shall be transferred on an annual basis to the Public Interest Attorney Loan Repayment Account established pursuant to Section 6032.5 of the Business and Professions Code. Before making this transfer, the Controller shall record the name and last known address of each person appearing from the holders report to be entitled to the escheated property. The record shall be available for public inspection at all reasonable business hours.
SEC. 2.Section 16378 is added to the Government Code, to read:16378.(a)There is established in the Special Deposit Fund in the State Treasury the Unclaimed Property Offset Account. Notwithstanding Section 13340, moneys in the account are continuously appropriated pursuant to Section 16372 for both of the following purposes:
(1)The payment of moneys to a state agency, local agency, city, county, community college district, special district, or court, or any other state or local governmental entity, to offset the moneys owed by a person claiming to be the owner of unclaimed property that has escheated to the state under Title 10 (commencing with Section 1300) of Part 3 of the Code of Civil Procedure.
(2)The payment of moneys to owners of unclaimed property that has escheated to the state after offsetting moneys paid pursuant to paragraph (1).
(b)The Controller may transfer to the Unclaimed Property Offset Account moneys held by the Controller from property that has escheated to the state under Title 10 (commencing with Section 1300) of Part 3 of the Code of Civil Procedure if the Controller has reason to believe the owner of the property has a debt to a state or local governmental entity.
|
Date
|
Status
|
|---|---|
| Sep 14, 2018 | Chaptered by Secretary of State - Chapter 390, Statutes of 2018. |
| Sep 14, 2018 | Approved by the Governor. |
| Sep 5, 2018 | Enrolled and presented to the Governor at 3 p.m. |
| Aug 27, 2018 | Senate amendments concurred in. To Engrossing and Enrolling. |
| Aug 23, 2018 | In Assembly. Concurrence in Senate amendments pending. May be considered on or after August 25 pursuant to Assembly Rule 77. |
| Aug 23, 2018 | Read third time. Passed. Ordered to the Assembly. |
| Aug 20, 2018 | Read second time. Ordered to third reading. |
| Aug 17, 2018 | From committee: Amend, and do pass as amended. (Ayes 7. Noes 0.) (August 16). |
| Aug 6, 2018 | In committee: Referred to APPR. suspense file. |
| Jun 20, 2018 | From committee: Do pass and re-refer to Com. on APPR. with recommendation: To Consent Calendar. (Ayes 7. Noes 0.) (June 19). Re-referred to Com. on APPR. |
| Jun 7, 2018 | Referred to Com. on JUD. |
| May 30, 2018 | In Senate. Read first time. To Com. on RLS. for assignment. |
| May 29, 2018 | Read third time. Passed. Ordered to the Senate. |
| May 25, 2018 | Read second time. Ordered to third reading. |
| Apr 4, 2018 | In committee: Set, first hearing. Referred to suspense file. |
| Mar 20, 2018 | From committee: Do pass and re-refer to Com. on APPR. with recommendation: To Consent Calendar. (Ayes 10. Noes 0.) (March 20). Re-referred to Com. on APPR. |
| Mar 1, 2018 | Referred to Com. on JUD. |
| Feb 14, 2018 | From printer. May be heard in committee March 16. |
| Feb 13, 2018 | Read first time. To print. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Aug 27, 2018 | AB 2350 OBERNOLTE Concurrence in Senate Amendments | Assembly Floor |
Passed |
|
| Aug 23, 2018 | Assembly 3rd Reading AB2350 Obernolte By Hertzberg | Senate Floor |
Passed |
|
| Aug 16, 2018 | Do pass as amended | Senate Standing Committee on Appropriations |
Passed |
|
| Aug 6, 2018 | Placed on suspense file | Senate Standing Committee on Appropriations |
Passed |
|
| Jun 19, 2018 | Do pass, but first be re-referred to the Committee on [Appropriations] with the recommendation: To Consent Calendar | Senate Standing Committee on Judiciary |
Passed |
|
| May 29, 2018 | AB 2350 OBERNOLTE Assembly Third Reading | Assembly Floor |
Passed |
|
| May 25, 2018 | Do pass. | Assembly Standing Committee on Appropriations |
Passed |
|
| Mar 20, 2018 | Do pass and be re-referred to the Committee on [Appropriations] with recommendation: To Consent Calendar | Assembly Standing Committee on Judiciary |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| State Controller Betty Yee | ** Support | Aug 19, 2018 |
| State Controller's Office | ** Support | Mar 16, 2018 |
CONCURRENCE IN SENATE AMENDMENTS
CSA1 Bill Id:AB 2350
Author:(Obernolte)
As Amended Ver:August 17, 2018
2/3 vote
ASSEMBLY: | 78-0 | (May 29, 2018) | SENATE: | 39-0 | (August 23, 2018) |
Original Committee Reference: JUD.
SUMMARY: Gives the State Controller continuous appropriation authority to make payments from the Interest on Lawyers' Trust Accounts (IOLTA) Claims Reserve Subaccount, and codifies the Controller's use of the Franchise Tax Board Offset Account. Specifically, this bill:
- Provides that, notwithstanding other law, funds in the IOLTA Claims Reserve Subaccount are continuously appropriated to the Controller (instead of upon appropriation by the Legislature) for the payment of all refunds and claims related to escheated IOLTA funds, as specified.
- Establishes the Unclaimed Property Offset Account in the Special Deposit Fund in the State Treasury, and provide that moneys in the account are continuously appropriated, for both of the following purposes:
- The payment of moneys to a state or local governmental entity, to offset the moneys owed by a person claiming to be the owner of unclaimed property that has escheated to the state under the Code of Civil Procedure, Title 10 (commencing with Section 1300).
- The payment of moneys to owners of unclaimed property that has escheated to the state after offsetting moneys paid pursuant to 2a), above.
- Permits the Controller to transfer to the Unclaimed Property Offset Account moneys held by the Controller from property that has escheated to the state, as provided, if the Controller has reason to believe the owner of the property has a debt to a state or local governmental entity.
The Senate amendments remove authorization for the IOLTA Claims Reserve Subaccount to be used for general costs associated with escheated IOLTA funds.
FISCAL EFFECT: According to the Senate Appropriations Committee:
- Unknown, potentially-significant redirection of moneys from the Unclaimed Property Fund and the General Fund to UPOA and ultimately to various state and local funds for outstanding debt owed to state and local governmental entities by allowing the State Controller to transfer moneys owed by persons who claim properties escheated to the state but who would not have paid the outstanding balances to the state and local entities.
Recovery of funds for outstanding debt owed to state entities could, in turn, lead to a reduction in General Fund expenditure of an unknown amount to the extent that the offsetting money is deposited into a state fund that is supplemented by the General Fund.
- Negligible administrative costs to the State Controller's Office.
COMMENTS: This non-controversial bill, sponsored by SCO, seeks to implement two separate changes to accounting procedures used by the SCO to manage escheated funds under the unclaimed property program. According to the author, the bill is needed to give the SCO continuous appropriation authority to make payments from the Interest on Lawyers' Trust Account (IOLTA), consistent with the authority to administer the rest of the Abandoned Property Fund, and to codify the Unclaimed Property Offset Account, which is a Special Deposit Fund (SDF) that has been temporarily authorized by the Department of Finance to collect debts owed to governmental entities by individuals receiving their unclaimed property.
Background on SB 134-- IOLTA Claims Reserve Subaccount. In order to address the high cost of a legal education and to encourage law students and new attorneys to pursue careers in public service, the Legislature enacted SB 134 (Hertzberg), Chapter. 488, Statutes of 2015, to require unclaimed funds in Interest on Lawyers' Trust Accounts (IOLTA accounts), rather than escheating to the state, to be deposited into the newly created Public Interest Attorney Loan Repayment Account in the State Treasury for the purposes of providing, upon appropriation by the Legislature, additional funding for the Public Interest Attorney Loan Repayment Program.
Existing state law requires attorneys to place their clients' funds (advances for attorney expenses, etc.) in a special IOLTA account on which interest is paid to the California State Bar in order to fund indigent legal services. Existing state law (the Unclaimed Property Law, or UPL) also provides that if there is no activity for a specified time (generally three years) on an account held by a bank or financial institution, the property in the account escheats to the state and the bank or financial institution (or "holder") is required to relinquish any unclaimed property in the account to the Controller's office. The Controller deposits all unclaimed funds, including funds from abandoned IOLTA accounts, into the Abandoned Property Account in the Unclaimed Property Fund, which is continuously appropriated by the state, as needed by the state's General Fund. However, the owner of the escheated funds, or even the owner's heirs, can always make a claim for the funds. When a claim is approved by the Controller, the state issues a check (without paying any interest on the funds) to the claimant.
The new law enacted by SB 134 effectively creates an exception to the Unclaimed Property Law for IOLTA funds that escheat to the state. Instead of being deposited in the Abandoned Property Account for use by the state's General Fund until and unless the owners file claims for their return, abandoned IOLTA funds are deposited into the Public Interest Attorney Loan Repayment Account in the State Treasury for the purpose of providing, upon appropriation by the Legislature, additional funding for the Public Interest Attorney Loan Repayment Program and administering the program.
Codifying continuous appropriation authority for the IOLTA Claims Reserve Subaccount. As enacted by SB 134, Code of Civil Procedure Section 1564.5 requires twenty-five percent (25%) of the money in the Abandoned IOLTA Property Account to be deposited into the IOLTA Claims Reserve Subaccount. The law also provides that funds in the Subaccount shall, upon appropriation by the Legislature, be available to the Controller for the payment of all refunds and claims related to escheated IOLTA funds, but as recently amended, not for general costs associated with escheated IOLTA funds.
The Abandoned IOLTA Property Account has continuous appropriation authorization from the Legislature. However, this authority does not apply to funds in the IOLTA Claim Reserve Subaccount. For the Controller to issue loan repayments from this subaccount, the Legislature must provide an appropriation. The author notes that this is inconsistent with the authority that applies to the rest of the Abandoned IOLTA Property Account, within which this subaccount resides. Accordingly, this bill seeks to provide the Controller with continuous appropriation authority to make loan repayments from the IOLTA Claim Reserve Subaccount, removing the administrative burden of waiting for an appropriation to administer the program.
Codifying permanent authority for the Unclaimed Property Offset Account. According to the State Controller, its Unclaimed Property Division began participating in the Franchise Tax Board's intercept program in September 2009. This program intercepts claim payments set to be mailed to people who owe money to the state of California, a county, a city or a special district. The Department of Finance granted the Controller the authority to establish an Unclaimed Property Offset account in the Special Deposit Fund to account for this FTB offset activity to pay the debt owed, and then send the claimant the balance of their unclaimed property. The offset program is currently, however, a temporarily authorized account. The author contends that to continue the intercept program, the account should be made permanent in statute.
According to the Controller's office, this offset program is similar to the Special Deposit Fund used by the Department of Child Support Services for child and spousal support intercept, as codified in Government Code Section 16377. The Child Support Intercept account is for the payment of child and spousal support obligations, and consists of all funds obtained by the state pursuant to child and spousal support intercept programs. In order to facilitate its permanent use, this bill would codify establishment of the Unclaimed Property Offset Account in the Special Deposit Fund, and provide that moneys in the account are continuously appropriated for the purpose of offsetting payment of funds to owners of unclaimed property that has escheated to the state, as specified.
Analysis Prepared by: Anthony Lew / JUD. / (916) 319-2334 FN: 0004465 FN:
Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | AB |
THIRD READING
Bill No: AB 2350
:
SENATE JUDICIARY COMMITTEE: 7-0, 6/19/18
AYES: Jackson, Moorlach, Anderson, Hertzberg, Monning, Stern, Wieckowski
SENATE APPROPRIATIONS COMMITTEE: 7-0, 8/16/18
AYES: Portantino, Bates, Beall, Bradford, Hill, Nielsen, Wiener
ASSEMBLY FLOOR: 78-0, 5/29/18 - See last page for vote
SOURCE: State Controller Betty T. Yee
DIGEST:
This bill enacts provisions designed to facilitate the way that the State Controller handles two unique types of unclaimed property. First, this bill enables the State Controller to pay refunds and claims out of the account holding money left abandoned in legal trust accounts without the need for a specific Legislative appropriation for that purpose. Second, this bill provides statutory authority for an existing account that the State Controller currently uses to manage unclaimed funds that the State Controller has reason to believe may be owed, in whole or in part, to state of local government agencies.
Existing law:
- Requires an attorney or law firm that receives or disburses trust funds to establish an interest bearing demand trust account, known as an IOLTA account, and to deposit in the account all client deposits that are nominal in amount or are on deposit or invested for a short period of time. (Bus. & Prof. Code Sec. 6211(a).)
- Establishes the Public Interest Attorney Loan Repayment Program for licensed attorneys who practice or agree to practice in public interest areas of law in this state and provides that participants are eligible for a maximum of $11,000 in loan assistance over four years. (Ed. Code Secs. 69741 and 69741.5.)
- Establishes the Public Interest Attorney Loan Repayment Account within the State Treasury, and requires funds from an IOLTA account that escheat to the state and that are deposited into this Account to be used, upon appropriation by the Legislature, by the Student Aid Commission for the purpose of providing increased funding for the Public Interest Attorney Loan Repayment Program, as provided. (Bus. & Prof. Code Sec. 6032.5.)
- Establishes the Abandoned IOLTA Property Account within the Unclaimed Property Fund, and provides that notwithstanding any law, any property held in an IOLTA account that escheats to the state shall be deposited into the Abandoned IOLTA Property Account. (Code Civ. Proc. Sec. 1564.5(a).)
- Requires 25 percent of the money in the Abandoned IOLTA Property Account to be deposited into the IOLTA Claims Reserve Subaccount, within the Abandoned IOLTA Property Account and that funds in this subaccount shall, upon appropriation by the Legislature, be available to the Controller for the payment of all refunds, claims, and costs related to escheated IOLTA funds. (Code Civ. Proc. Sec. 1564.5(b).)
- Requires the balance of the funds in the Abandoned IOLTA Property Account, excluding funds in the subaccount, to be transferred on an annual basis to the Public Interest Attorney Loan Repayment Account and requires the Controller, before making such a transfer, to record the name and last known address of each person appearing from the holders’ report to be entitled to the escheated property, and to make the record available for public inspection at all reasonable business hours. (Code Civ. Proc. Sec. 1564.5(c).)
- Provides, in the Unclaimed Property Law (UPL), for the escheat of property to the state and requires all property that escheats to the state to be deposited into the Abandoned Property Account in the Unclaimed Property Fund, which is continuously appropriated for specified purposes, and establishes procedures for submitting a claim for property that has escheated. (Code Civ. Proc. Sec. 1500 et seq.)
- Provides that moneys in any fund that, by any statute other than a Budget Act, are continuously appropriated without regard to fiscal years may be encumbered unless the Legislature, by statute, specifies that the moneys in the fund are appropriated for encumbrance. (Gov. Code Sec. 13340.)
This bill:
- Provides that, notwithstanding other law, funds in the IOLTA Claims Reserve Subaccount are continuously appropriated to the Controller (instead of upon appropriation by the Legislature) for the payment of all refunds and claims related to escheated IOLTA funds, as specified.
- Establishes the Unclaimed Property Offset Account within the Special Deposit Fund of the State Treasury, and provide that any funds in the account are continuously appropriated, for both of the following purposes:
- payments to a state or local governmental entity, to offset the debts owed by a person claiming to be the owner of unclaimed property that has escheated to the state; and
- payments of any balance remaining to owners of unclaimed property that has escheated to the state after offsets for money paid to a state or local government entity to satisfy the unclaimed property owner’s debt with that entity.
- Permits the Controller to transfer to the Unclaimed Property Offset Account moneys held by the Controller from property that has escheated to the state, as provided, if the Controller has reason to believe the owner of the property has a debt to a state or local governmental entity.
Background
Among the State Controller’s functions is the duty to safeguard lost and forgotten property – things like bank accounts, uncashed checks, insurance benefits, wages, stocks, bonds, and safe deposit box contents – that have been turned over to the state until that property is either claimed by the rightful owners or it permanently escheats to the state.
To track all of this property, the State Controller maintains a variety of distinct accounts. The existence of these accounts and how the State Controller must handle the contents of them is governed by statute. This bill makes two alterations to those statutes.
The first change relates to handling of funds left abandoned in Interest on Legal Trust Accounts (IOLTAs). An IOLTA is a specialized type of pooled deposit account that lawyers must use when holding money for clients in small enough quantities, or for so short a time, that the money would not generate interest on its own. Under existing law, when funds are abandoned in an IOLTA, the State Controller must deposit them into the Abandoned IOLTA Property Account, a distinct account with the State Controller’s broader Unclaimed Property Fund. (Code Civ. Proc. Sec. 1564.5(a).)
Existing law further directs the State Controller what to do with the content of the Abandoned IOLTA Property Account. Each year, the State Controller must transfer 75 percent of the balance to the Public Interest Attorney Loan Repayment Account. (Code Civ. Proc. Sec. 1564.5(c).) The remaining 25 percent must be held back in a separate IOLTA Claims Reserve Subaccount in case the owners of that property turn up and want it back. (Code Civ. Proc. Sec. 1564.5(b).)
The problem is that when owners do show up to reclaim money from the IOLTA Claims Reserve Subaccount, existing law says that the State Controller can only pay the resulting refund, claim or cost “upon appropriation by the Legislature.” Administratively, therefore, the State Controller has to await that specific legislative appropriation before it can process someone’s request to reclaim money that person left abandoned in an IOLTA. This bill, instead, provides for continuous appropriation of the funds in the IOLTA Claims Reserve Subaccount to the State Controller for the purpose of paying these refunds and claims, thus eliminating the delay and administrative burden association with obtaining specific legislative appropriation.
The second change proposed by this bill relates to how the State Controller handles unclaimed property when the State Controller has reason to believe the owner of the property owes money to a state or local government entity. According to the author, the State Controller has a dedicated account into which it deposits such unclaimed property, known as the Unclaimed Property Offset account. From this account, the State Controller can pay debts owed by the owner of the property to state and local government entities when and if the property is reclaimed. After the debts are paid, any remainder is issued back to the owner of the property.
According to the author, the problem is that the State Controller set up the Unclaimed Property Offset account based on temporary authority given to it by the Department of Finance. This apparently first took place back in 2009 and was done to enable the State Controller to participate in a Franchise Tax Board effort to intercept claim payments being made to people who owe money to the state or a local government entity. This bill provides permanent statutory authority for the existence of the account, thus authorizing and enabling the State Controller’s ongoing participation in the intercept program.
Comments
Background IOLTA accounts and the Public Interest Attorney Loan Repayment Program
As explained by the Assembly Committee on Judiciary in its staff analysis of this bill:
In the course of their legal practice, attorneys are frequently required to hold clients’ funds for various lengths of time. It has long been recognized that attorneys have a professional and fiduciary obligation to avoid commingling their clients’ money with their own. Before 1980, client funds were typically held in non-interest-bearing federally insured checking accounts. Because of federal banking regulations in effect since the Great Depression, banks were prohibited from paying interest on checking accounts. As a result, the value of the use of the clients’ money in such accounts inured to the banking institutions.
In 1980, Congress authorized federally insured banks to pay interest on a limited category of demand deposits referred to as “NOW accounts.” This category includes deposits made by individuals and charitable organizations, but does not include those made by for-profit corporations or partnerships unless the deposits are made pursuant to a program under which charitable organizations have “the exclusive right to the interest.”
In response to the change in federal law, Florida adopted the first IOLTA program in 1981 authorizing the use of NOW accounts for the deposit of client funds, and providing that all of the interest on such accounts be used for charitable purposes. Every state in the nation and the District of Columbia has followed Florida’s lead and adopted an IOLTA program, either through their legislatures or their highest courts. The result is that, whereas before 1980 the banks retained the value of the use of the money deposited in non-interest-bearing client trust accounts, today, because of the adoption of IOLTA programs, that value is transferred to charitable entities providing legal services for the poor.
Due process considerations
This bill would provide statutory authority for the State Controller to place certain unclaimed property into a specially designated account, the Unclaimed Property Offset Account, when the State Controller has “reason to believe” that the owner of the property has a debt to a state or local government agency. The bill also continuously appropriates the funds in the account for use by the State Controller to pay those debts. Left unsaid is what safeguards, if any, are in place to ensure that the debts are genuine and that they are indeed owed by the owner of the unclaimed property. Since the proposed (and evidently existing) program involves depriving people of property, albeit currently unclaimed, due process arguably demands that such safeguards be in place.
According to the Controller’s office:
The FTB administers the offset program under the “Interagency Intercept Collection Program” for other state agencies and many other government entities. The FTB does not determine if or advise on acceptable debt types for collection. It is each agency’s responsibility to do this. Departments are advised to consult with their legal department to determine acceptable debts.
A significant step in the process that addresses due process protection is a preliminary step requiring each participating agency to first submit a “Pre-Intercept Notice” to the debtor that contains specific due process language, refer to sample FTB 2288, Pre-Intercept Notice Instructions. (https://www.ftb.ca.gov/forms/misc/2288.pdf)
The notice must:
- Provide the Government Code Sections that authorize your agency to submit debts for intercept.
- Allow your debtors 30 days to resolve or dispute the debts, before submitting their debts to us.
- Provide your agency’s contact information where the debtor can dispute the liability.
More info is available about this program on FTB’s website at https://www.ftb.ca.gov/individuals/Interagency_Intercept_Collections/index.shtml
As far as timing and reasonable belief, the offset takes place after a claim for property is made and validated with our Unclaimed Property staff.
The only way an unclaimed property payment would be subject to offset is if the reported owner (or their heir) filed a claim on their own volition. If their claim is proved to be valid and they are determined to be the rightful owner through corroborating evidence and documentation submitted, we would then be in a position to believe they are in fact the rightful owner and the property belongs to them. The Unclaimed Property Program has exhaustive claim evaluation procedures in place to make a reasonable determination that property we hold is approved for the correct person. Only after this would an unclaimed property payment be subject to the offset program.
FISCAL EFFECT: Appropriation: Fiscal Com.: Local:
State Controller Betty Yee (source)
OPPOSITION: (Verified 8/17/18)
None received
ARGUMENTS IN SUPPORT: According to the author:
AB 2350 will give the State Controller continuous appropriation authority to make payments from the Interest on Lawyers’ Trust Account (IOLTA), consistent with the authority to administer the rest of the Abandoned Property Fund. AB 2350 also codifies the Controller’s use of a Special Deposit Fund, the Unclaimed Property Offset Account.
ASSEMBLY FLOOR: 78-0, 5/29/18
AYES: Acosta, Aguiar-Curry, Travis Allen, Arambula, Baker, Berman, Bigelow, Bloom, Bonta, Brough, Burke, Caballero, Calderon, Carrillo, Cervantes, Chau, Chávez, Chen, Chiu, Choi, Chu, Cooley, Cooper, Cunningham, Dahle, Daly, Eggman, Flora, Fong, Frazier, Friedman, Gallagher, Cristina Garcia, Eduardo Garcia, Gipson, Gloria, Gonzalez Fletcher, Gray, Grayson, Harper, Holden, Irwin, Jones-Sawyer, Kalra, Kamlager-Dove, Kiley, Lackey, Levine, Limón, Low, Maienschein, Mathis, Mayes, McCarty, Medina, Melendez, Mullin, Muratsuchi, Nazarian, Obernolte, O'Donnell, Patterson, Quirk, Quirk-Silva, Reyes, Rodriguez, Rubio, Salas, Santiago, Steinorth, Mark Stone, Thurmond, Ting, Voepel, Waldron, Weber, Wood, Rendon
8/19/18 14:02:35
**** END ****
SENATE COMMITTEE ON APPROPRIATIONS
Senator Anthony Portantino, Chair
2017 - 2018 Regular Session
AB 2350 (Obernolte) - Unclaimed property
Version: February 13, 2018 | Policy Vote: JUD. 7 - 0 |
Urgency: No | Mandate: No |
Hearing Date: August 16, 2018 | Consultant: Shaun Naidu |
Bill Summary:
AB 2350 would create the Unclaimed Property Offset Account (UPOA) for payment of moneys to a public entity to offset the moneys owed by a person claiming unclaimed property that has escheated to the state. It also would make the UPOA and the Interest on Lawyers’ Trust Account (IOLTA) Claims Reserve Subaccount continuously-appropriated funds.
*********** ANALYSIS ADDENDUM – SUSPENSE FILE ***********
The following information is revised to reflect amendments
adopted by the committee on August 16, 2018
Fiscal Impact:
- Unknown, potentially-significant redirection of moneys from the Unclaimed Property Fund and the General Fund to UPOA and ultimately to various state and local funds for outstanding debt owed to state and local governmental entities by allowing the State Controller to transfer moneys owed by persons who claim properties escheated to the state but who would not have paid the outstanding balances to the state and local entities.
Recovery of funds for outstanding debt owed to state entities could, in turn, lead to a reduction in General Fund expenditure of an unknown amount to the extent that the offsetting money is deposited into a state fund that is supplemented by the General Fund.
- Negligible administrative costs to the State Controller’s Office.
Author Amendments:
Strike the continuous appropriation of costs from the IOLTA Claims Reserve Subaccount.
-- END --
SENATE COMMITTEE ON
Senator Anthony Portantino, Chair
2017 - 2018 Regular Session
AB 2350 (Obernolte) - Unclaimed property
Version: | Policy Vote: |
Urgency: | Mandate: |
Hearing Date: | Consultant: |
This bill meets the criteria for referral to the Suspense File.
Bill Summary:
AB 2350 would create the Unclaimed Property Offset Account (UPOA) for payment of moneys to a public entity to offset the moneys owed by a person claiming unclaimed property that has escheated to the state. It also would make the UPOA and the Interest on Lawyers’ Trust Account (IOLTA) Claims Reserve Subaccount continuously-appropriated funds.
Fiscal Impact:
- Unknown, potentially-significant redirection of moneys from the Unclaimed Property Fund and the General Fund to UPOA and ultimately to various state and local funds for outstanding debt owed to state and local governmental entities by allowing the State Controller to transfer moneys owed by persons who claim properties escheated to the state but who would not have paid the outstanding balances to the state and local entities.
Recovery of funds for outstanding debt owed to state entities could, in turn, lead to a reduction in General Fund expenditure of an unknown amount to the extent that the offsetting money is deposited into a state fund that is supplemented by the General Fund.
- Unknown, potentially-significant expenditure from the IOLTA Claims Reserve Subaccount for unknown State Controller’s Office costs related to escheated IOLTA funds that could exceed $150,000 in any given year depending on the fund balance.
- Negligible administrative costs to the State Controller’s Office.
Background:
As stated in the analysis of this bill by the Assembly Committee on Judiciary:
In the course of their legal practice, attorneys are frequently required to hold clients’ funds for various lengths of time. It has long been recognized that attorneys have a professional and fiduciary obligation to avoid commingling their clients’ money with their own. Before 1980, client funds were typically held in non-interest-bearing federally insured checking accounts. Because of federal banking regulations in effect since the Great Depression, banks were prohibited from paying interest on checking accounts. As a result, the value of the use of the clients’ money in such accounts inured to the banking institutions.
In 1980, Congress authorized federally insured banks to pay interest on a limited category of demand deposits referred to as “NOW accounts.” This category includes deposits made by individuals and charitable organizations, but does not include those made by for-profit corporations or partnerships unless the deposits are made pursuant to a program under which charitable organizations have “the exclusive right to the interest.”
In response to the change in federal law, Florida adopted the first IOLTA program in 1981 authorizing the use of NOW accounts for the deposit of client funds, and providing that all of the interest on such accounts be used for charitable purposes. Every state in the nation and the District of Columbia has followed Florida’s lead and adopted an IOLTA program, either through their legislatures or their highest courts. The result is that, whereas before 1980 the banks retained the value of the use of the money deposited in non-interest-bearing client trust accounts, today, because of the adoption of IOLTA programs, that value is transferred to charitable entities providing legal services for the poor.
Additionally, California’s Unclaimed Property Law requires banks, insurance companies, corporations, and certain other entities to report and submit their customers’ property to the State Controller’s Office when there has been no activity for a period of time, generally three years. Common types of unclaimed property are bank accounts, stocks, bonds, uncashed checks, insurance benefits, wages, and safe deposit box contents. From time to time, the Attorney General is required to bring a civil action in Sacramento County to have the court adjudge that title to unclaimed property has vested in the state and that the property has been actually abandoned or that the owner has died and there is no person entitled to it and effectuate permanent escheatment of the property to the state. When money in the Unclaimed Property Fund becomes permanently escheated to the state, it is transferred to the General Fund.
Proposed Law:
This bill would:
- Create the UPOA in the Special Deposit Fund for the payment of moneys to a state or local governmental entity to offset the moneys owed by a person claiming to be the owner of unclaimed property that has escheated to the state.
- Make the UPOA and IOLTA Claims Reserve Subaccount continuously-appropriated funds.
Related Legislation:
SB 134 (Hertzberg, Ch. 488, Stats. 2015) required unclaimed IOLTA funds, rather than escheating to the state, be deposited into an Abandoned IOLTA Property Account within the Unclaimed Property Fund. SB 134 required 75 percent of the balance of the Abandoned IOLTA Property Account to be transferred each year to the Public Interest Attorney Loan Repayment Account and 25 percent to be held in the IOLTA Claims Reserve Subaccount to be used, upon appropriation by the Legislature, for paying refunds, claims, and costs relating to the return of unclaimed IOLTA funds to their owner.
SB 184 (Committee on Governance and Finance, Ch. 210, Stats. 2013) authorized the State Controller to use unclaimed Franchise Tax Board refunds to satisfy state, county, city, and special district debts with any residual amount to be paid to the rightful owner through the claim process.
SB 906 (Dills, Ch. 917, Stats. 1989) authorized the State Controller to use unclaimed property to satisfy state, county, city, and special district debts with any residual amount to be paid to the rightful owner through the claim process.
Staff Comments:
The State Controller’s Office indicates that $32,841.52 was deposited into the IOLTA Claims Reserve Subaccount for the 2016-17 fiscal year. It is unknown to committee staff how much, on average, is deposited into the subaccount on an annual basis, but the balance of the account could grow rapidly depending on the volume of claims submitted and approved each year. Recently, there have been seventeen claims submitted, thirteen of which have been approved by the office for a total of $9,244.15. The remaining four pending claims total $25,595.39. This bill would allow the State Controller to pay those and future claims without requesting an appropriation from the Legislature.
Additionally, AB 2350 would allow the State Controller to use moneys in the subaccount for costs related to escheated IOLTA funds, such as, for example, staff to administer the program and increase outreach and education of the program to the public. The cost to provide a more robust outreach and education program would be $92,000 for 1.0 permanent position and $160,000 annually for 2.0 permanent positions. The use of these moneys would not be subject to any legislative approval, as this bill would make such types of appropriations by the State Controller continuous for costs and for refund and claim purposes.
-- END --
Senator Hannah-Beth Jackson, Chair
2017-2018 Regular Session
Bill No: AB 2350 (Author:Obernolte)
Version: February 13, 2018
Hearing Date: June 19, 2018
Fiscal: Yes
Urgency: No
Consultant: TSG
SUBJECT
Unclaimed property
DESCRIPTION
This bill would enact provisions designed to facilitate the way that the State Controller handles two unique types of unclaimed property. First, the bill would enable the State Controller to pay refunds, claims, and costs out of the account holding money left abandoned in legal trust accounts without the need for a specific Legislative appropriation for that purpose. Second, the bill would provide statutory authority for an existing account that the State Controller currently uses to manage unclaimed funds that the State Controller has reason to believe may be owed, in whole or in part, to state of local government agencies.
BACKGROUND
Among the State Controller’s functions is the duty to safeguard lost and forgotten property – things like bank accounts, uncashed checks, insurance benefits, wages, stocks, bonds, and safe deposit box contents – that have been turned over to the state until that property is either claimed by the rightful owners or it permanently escheats to the state.
To track all of this property, the State Controller maintains a variety of distinct accounts. The existence of these accounts and how the State Controller must handle the contents of them is governed by statute. This bill would make two alterations to those statutes.
The first change relates to handling of funds left abandoned in Interest on Legal Trust Accounts (IOLTAs). An IOLTA is a specialized type of pooled deposit account that lawyers must use when holding money for clients in small enough quantities, or for so short a time, that the money would not generate interest on its own. Under existing law, when funds are abandoned in an IOLTA, the State Controller must deposit them into the Abandoned IOLTA Property Account, a distinct account with the State Controller’s broader Unclaimed Property Fund. (Code Civ. Proc. Sec. 1564.5(a).)
Existing law further directs the State Controller what to do with the content of the Abandoned IOLTA Property Account. Each year, the State Controller must transfer 75 percent of the balance to the Public Interest Attorney Loan Repayment Account. (Code Civ. Proc. Sec. 1564.5(c).) The remaining 25 percent must be held back in a separate IOLTA Claims Reserve Subaccount in case the owners of that property turn up and want it back. (Code Civ. Proc. Sec. 1564.5(b).)
The problem is that when owners do show up to reclaim money from the IOLTA Claims Reserve Subaccount, existing law says that the State Controller can only pay the resulting refund, claim or cost “upon appropriation by the Legislature.” Administratively, therefore, the State Controller has to await that specific legislative appropriation before it can process someone’s request to reclaim money that person left abandoned in an IOLTA. This bill would, instead, provide for continuous appropriation of the funds in the IOLTA Claims Reserve Subaccount to the State Controller for the purpose of paying these refunds, claims, and costs, thus eliminating the delay and administrative burden association with obtaining specific legislative appropriation.
The second change proposed by this bill relates to how the State Controller handles unclaimed property when the State Controller has reason to believe the owner of the property owes money to a state or local government entity. According to the author, the State Controller has a dedicated account into which it deposits such unclaimed property, known as the Unclaimed Property Offset account. From this account, the State Controller can pay debts owed by the owner of the property to state and local government entities when and if the property is reclaimed. After the debts are paid, any remainder is issued back to the owner of the property.
According to the author, the problem is that the State Controller set up the Unclaimed Property Offset account based on temporary authority given to it by the Department of Finance. This apparently first took place back in 2009 and was done to enable the State Controller to participate in a Franchise Tax Board effort to intercept claim payments being made to people who owe money to the state or a local government entity. This bill would provide permanent statutory authority for the existence of the account, thus authorizing and enabling the State Controller’s ongoing participation in the intercept program.
CHANGES TO EXISTING LAW
Existing law requires an attorney or law firm that receives or disburses trust funds to establish an interest bearing demand trust account, known as an IOLTA account, and to deposit in the account all client deposits that are nominal in amount or are on deposit or invested for a short period of time. (Bus. & Prof. Code Sec. 6211(a).)
Existing law establishes the Public Interest Attorney Loan Repayment Program for licensed attorneys who practice or agree to practice in public interest areas of law in this state and provides that participants are eligible for a maximum of $11,000 in loan assistance over four years. (Ed. Code Secs. 69741 and 69741.5.)
Existing law establishes the Public Interest Attorney Loan Repayment Account within the State Treasury, and requires funds from an IOLTA account that escheat to the state and that are deposited into this Account to be used, upon appropriation by the Legislature, by the Student Aid Commission for the purpose of providing increased funding for the Public Interest Attorney Loan Repayment Program, as provided. (Bus. & Prof. Code Sec. 6032.5.)
Existing law establishes the Abandoned IOLTA Property Account within the Unclaimed Property Fund, and provides that notwithstanding any law, any property held in an IOLTA account that escheats to the state shall be deposited into the Abandoned IOLTA Property Account. (Code Civ. Proc. Sec. 1564.5(a).)
Existing law requires 25 percent of the money in the Abandoned IOLTA Property Account to be deposited into the IOLTA Claims Reserve Subaccount, within the Abandoned IOLTA Property Account and that funds in this subaccount shall, upon appropriation by the Legislature, be available to the Controller for the payment of all refunds, claims, and costs related to escheated IOLTA funds. (Code Civ. Proc. Sec. 1564.5(b).)
Existing law requires the balance of the funds in the Abandoned IOLTA Property Account, excluding funds in the subaccount, to be transferred on an annual basis to the Public Interest Attorney Loan Repayment Account and requires the Controller, before making such a transfer, to record the name and last known address of each person appearing from the holders’ report to be entitled to the escheated property, and to make the record available for public inspection at all reasonable business hours. (Code Civ. Proc. Sec. 1564.5(c).)
Existing law provides, in the Unclaimed Property Law (UPL), for the escheat of property to the state and requires all property that escheats to the state to be deposited into the Abandoned Property Account in the Unclaimed Property Fund, which is continuously appropriated for specified purposes, and establishes procedures for submitting a claim for property that has escheated. (Code Civ. Proc. Sec. 1500 et seq.)
Existing law provides that moneys in any fund that, by any statute other than a Budget Act, are continuously appropriated without regard to fiscal years may be encumbered unless the Legislature, by statute, specifies that the moneys in the fund are appropriated for encumbrance. (Gov. Code Sec. 13340.)
This bill would provide that, notwithstanding other law, funds in the IOLTA Claims Reserve Subaccount are continuously appropriated to the Controller (instead of upon appropriation by the Legislature) for the payment of all refunds, claims, and costs related to escheated IOLTA funds, as specified.
This bill would establish the Unclaimed Property Offset Account within the Special Deposit Fund of the State Treasury, and provide that any funds in the account are continuously appropriated, for both of the following purposes:
- payments to a state or local governmental entity, to offset the debts owed by a person claiming to be the owner of unclaimed property that has escheated to the state; and
- payments of any balance remaining to owners of unclaimed property that has escheated to the state after offsets for money paid to a state or local government entity to satisfy the unclaimed property owner’s debt with that entity.
This bill would permit the Controller to transfer to the Unclaimed Property Offset Account moneys held by the Controller from property that has escheated to the state, as provided, if the Controller has reason to believe the owner of the property has a debt to a state or local governmental entity.
COMMENT
1. Stated need for the bill
According to the author:
AB 2350 will give the State Controller continuous appropriation authority to make payments from the Interest on Lawyers’ Trust Account (IOLTA), consistent with the authority to administer the rest of the Abandoned Property Fund. AB 2350 also codifies the Controller’s use of a Special Deposit Fund, the Unclaimed Property Offset Account.
2. Background IOLTA accounts and the Public Interest Attorney Loan Repayment Program
As explained by the Assembly Committee on Judiciary in its staff analysis of this bill:
In the course of their legal practice, attorneys are frequently required to hold clients’ funds for various lengths of time. It has long been recognized that attorneys have a professional and fiduciary obligation to avoid commingling their clients’ money with their own. Before 1980, client funds were typically held in non-interest-bearing federally insured checking accounts. Because of federal banking regulations in effect since the Great Depression, banks were prohibited from paying interest on checking accounts. As a result, the value of the use of the clients’ money in such accounts inured to the banking institutions.
In 1980, Congress authorized federally insured banks to pay interest on a limited category of demand deposits referred to as “NOW accounts.” This category includes deposits made by individuals and charitable organizations, but does not include those made by for-profit corporations or partnerships unless the deposits are made pursuant to a program under which charitable organizations have “the exclusive right to the interest.”
In response to the change in federal law, Florida adopted the first IOLTA program in 1981 authorizing the use of NOW accounts for the deposit of client funds, and providing that all of the interest on such accounts be used for charitable purposes. Every state in the nation and the District of Columbia has followed Florida’s lead and adopted an IOLTA program, either through their legislatures or their highest courts. The result is that, whereas before 1980 the banks retained the value of the use of the money deposited in non-interest-bearing client trust accounts, today, because of the adoption of IOLTA programs, that value is transferred to charitable entities providing legal services for the poor.
3. Due process considerations
This bill would provide statutory authority for the State Controller to place certain unclaimed property into a specially designated account, the Unclaimed Property Offset Account, when the State Controller has “reason to believe” that the owner of the property has a debt to a state or local government agency. The bill also continuously appropriates the funds in the account for use by the State Controller to pay those debts. Left unsaid is what safeguards, if any, are in place to ensure that the debts are genuine and that they are indeed owed by the owner of the unclaimed property. Since the proposed (and evidently existing) program involves depriving people of property, albeit currently unclaimed, due process arguably demands that such safeguards be in place.
According to the Controller’s office:
The FTB administers the offset program under the “Interagency Intercept Collection Program” for other state agencies and many other government entities. The FTB does not determine if or advise on acceptable debt types for collection. It is each agency’s responsibility to do this. Departments are advised to consult with their legal department to determine acceptable debts.
A significant step in the process that addresses due process protection is a preliminary step requiring each participating agency to first submit a “Pre-Intercept Notice” to the debtor that contains specific due process language, refer to sample FTB 2288, Pre-Intercept Notice Instructions. (https://www.ftb.ca.gov/forms/misc/2288.pdf)
The notice must:
- Provide the Government Code Sections that authorize your agency to submit debts for intercept.
- Allow your debtors 30 days to resolve or dispute the debts, before submitting their debts to us.
- Provide your agency’s contact information where the debtor can dispute the liability.
More info is available about this program on FTB’s website at https://www.ftb.ca.gov/individuals/Interagency_Intercept_Collections/index.shtml
As far as timing and reasonable belief, the offset takes place after a claim for property is made and validated with our Unclaimed Property staff.
The only way an unclaimed property payment would be subject to offset is if the reported owner (or their heir) filed a claim on their own volition. If their claim is proved to be valid and they are determined to be the rightful owner through corroborating evidence and documentation submitted, we would then be in a position to believe they are in fact the rightful owner and the property belongs to them. The Unclaimed Property Program has exhaustive claim evaluation procedures in place to make a reasonable determination that property we hold is approved for the correct person. Only after this would an unclaimed property payment be subject to the offset program.
Support: None known
Opposition: None known
HISTORY
Source: State Controller Betty T. Yee
Related Pending Legislation: None known
Prior Legislation:
SB 134 (Hertzberg, Ch. 488, Stats. 2015) required unclaimed funds in Interest on Lawyers’ Trust Accounts (IOLTA accounts), rather than escheating to the state, to be deposited into an Abandoned IOLTA Property Account within the Unclaimed Property Fund. From the balance of this Abandoned IOLTA Property Account, the bill required 75 percent to be transferred each year to the Public Interest Attorney Loan Repayment Account in the State Treasury, with the remaining 25 percent to be held in the IOLTA Claims Reserve Subaccount to be used, upon appropriation by the Legislature, for paying refunds, claims, and costs relating to the return of unclaimed IOLTA funds to their owner.
SB 184 (Committee on Governance and Finance, Ch. 210, Stats. 2013) authorized the State Controller to use unclaimed Franchise Tax Board refunds to satisfy state, county, city, and special district debts with any residual amount to be paid to the rightful owner through the claim process.
SB 906 (Dills, Ch. 917, Stats. 1989) authorized the State Controller to use unclaimed property to satisfy state, county, city, and special district debts with any residual amount to be paid to the rightful owner through the claim process.
AB 1032 (Wright, Ch. 155, Stats. 1989) created the Child Support Intercept Account for the payment of child and spousal support obligations, which consist of all moneys obtained by the state pursuant to child and spousal support intercept programs.
Prior Vote:
Assembly Floor (Ayes 78, Noes 0)
Assembly Appropriations Committee (Ayes 16, Noes 0)
Assembly Judiciary Committee (Ayes 10, Noes 0)
**************
ASSEMBLY THIRD READING
ATR Bill Id:AB 2350
Author:(Obernolte)
As Introduced Ver:February 13, 2018
2/3 vote
Committee | Votes | Ayes | Noes |
Judiciary | 10-0 | Mark Stone, Calderon, Berman, Obernolte, Gonzalez Fletcher, Holden, Kalra, Kiley, Maienschein, Reyes | |
Appropriations | 16-0 | Gonzalez Fletcher, Bigelow, Bloom, Bonta, Calderon, Carrillo, Chau, Eggman, Fong, Friedman, Gallagher, Eduardo Garcia, Nazarian, Obernolte, Quirk, Reyes |
|
SUMMARY: Gives the State Controller continuous appropriation authority to make payments from the Interest on Lawyers' Trust Accounts (IOLTA) Claims Reserve Subaccount, and codifies the Controller's use of the Franchise Tax Board Offset Account. Specifically, this bill:
- Provides that, notwithstanding other law, funds in the IOLTA Claims Reserve Subaccount are continuously appropriated to the Controller (instead of upon appropriation by the Legislature) for the payment of all refunds, claims, and costs related to escheated IOLTA funds, as specified.
- Establishes the Unclaimed Property Offset Account in the Special Deposit Fund in the State Treasury, and provide that moneys in the account are continuously appropriated, for both of the following purposes:
- The payment of moneys to a state or local governmental entity, to offset the moneys owed by a person claiming to be the owner of unclaimed property that has escheated to the state under the Code of Civil Procedure, Title 10 (commencing with Section 1300).
- The payment of moneys to owners of unclaimed property that has escheated to the state after offsetting moneys paid pursuant to 2a), above.
- Permits the Controller to transfer to the Unclaimed Property Offset Account moneys held by the Controller from property that has escheated to the state, as provided, if the Controller has reason to believe the owner of the property has a debt to a state or local governmental entity.
FISCAL EFFECT: According to the Assembly Appropriations Committee:
- Continuously appropriates to the State Controller's Office (SCO) funds in the IOLTA Claims Reserve Subaccount. According the SCO, no money has been deposited to the subaccount. However, SCO anticipates banks may deposit funds into the subaccount. SCO could not estimate the amount of fund that might be deposited into the account. Absent the continuous appropriation authorized by this bill, the SCO would need the Legislature to appropriate funds in the subaccount to the SCO before it could distribute the funds for authorized uses.
- Establishes in the Special Deposit Fund in the State Treasury the Unclaimed Property Offset Account and continuously appropriates monies in the fund for the following purposes:
- Payment of moneys to a state agency, local agency, city, county, community college district, special district, or court, or any other state or local governmental entity, to offset the moneys owed by a person claiming to be the owner of unclaimed property that has escheated to the state.
- Payment of moneys to owners of unclaimed property that has escheated to the state after offsetting moneys paid as described in (a) above.
- Authorizes the SCO to transfer to the Unclaimed Property Offset Account moneys held by the Controller from property that has escheated to the state if the SCO has reason to believe the owner of the property has a debt to a state or local governmental entity.
- Negligible SCO administrative costs.
COMMENTS: This non-controversial bill, sponsored by SCO, seeks to implement two separate changes to accounting procedures used by the SCO to manage escheated funds under the unclaimed property program. According to the author, the bill is needed to give the SCO continuous appropriation authority to make payments from the Interest on Lawyers' Trust Account (IOLTA), consistent with the authority to administer the rest of the Abandoned Property Fund, and to codify the Unclaimed Property Offset Account, which is a Special Deposit Fund (SDF) that has been temporarily authorized by the Department of Finance to collect debts owed to governmental entities by individuals receiving their unclaimed property.
Background on SB 134-- IOLTA Claims Reserve Subaccount. In order to address the high cost of a legal education and to encourage law students and new attorneys to pursue careers in public service, the Legislature enacted SB 134 (Hertzberg), Chapter. 488, Statutes of 2015, to require unclaimed funds in Interest on Lawyers' Trust Accounts (IOLTA accounts), rather than escheating to the state, to be deposited into the newly created Public Interest Attorney Loan Repayment Account in the State Treasury for the purposes of providing, upon appropriation by the Legislature, additional funding for the Public Interest Attorney Loan Repayment Program.
Existing state law requires attorneys to place their clients' funds (advances for attorney expenses, etc.) in a special IOLTA account on which interest is paid to the California State Bar in order to fund indigent legal services. Existing state law (the Unclaimed Property Law, or UPL) also provides that if there is no activity for a specified time (generally three years) on an account held by a bank or financial institution, the property in the account escheats to the state and the bank or financial institution (or "holder") is required to relinquish any unclaimed property in the account to the Controller's office. The Controller deposits all unclaimed funds, including funds from abandoned IOLTA accounts, into the Abandoned Property Account in the Unclaimed Property Fund, which is continuously appropriated by the state, as needed by the state's General Fund. However, the owner of the escheated funds, or even the owner's heirs, can always make a claim for the funds. When a claim is approved by the Controller, the state issues a check (without paying any interest on the funds) to the claimant.
The new law enacted by SB 134 effectively creates an exception to the Unclaimed Property Law for IOLTA funds that escheat to the state. Instead of being deposited in the Abandoned Property Account for use by the state's General Fund until and unless the owners file claims for their return, abandoned IOLTA funds are deposited into the Public Interest Attorney Loan Repayment Account in the State Treasury for the purpose of providing, upon appropriation by the Legislature, additional funding for the Public Interest Attorney Loan Repayment Program and administering the program.
Codifying continuous appropriation authority for the IOLTA Claims Reserve Subaccount. As enacted by SB 134, Code of Civil Procedure Section 1564.5 requires twenty-five percent (25%) of the money in the Abandoned IOLTA Property Account to be deposited into the IOLTA Claims Reserve Subaccount. The law also provides that funds in the subaccount shall, upon appropriation by the Legislature, be available to the Controller for the payment of all refunds, claims, and costs related to escheated IOLTA funds.
The Abandoned IOLTA Property Account has continuous appropriation authorization from the Legislature. However, this authority does not apply to funds in the IOLTA Claim Reserve Subaccount. For the Controller to issue loan repayments from this subaccount, the Legislature must provide an appropriation. The author notes that this is inconsistent with the authority that applies to the rest of the Abandoned IOLTA Property Account, within which this subaccount resides. Accordingly, this bill seeks to provide the Controller with continuous appropriation authority to make loan repayments from the IOLTA Claim Reserve Subaccount, removing the administrative burden of waiting for an appropriation to administer the program.
Codifying permanent authority for the Unclaimed Property Offset Account. According to the State Controller, its Unclaimed Property Division began participating in the Franchise Tax Board's intercept program in September 2009. This program intercepts claim payments set to be mailed to people who owe money to the state of California, a county, a city or a special district. The Department of Finance granted the Controller the authority to establish an Unclaimed Property Offset account in the Special Deposit Fund to account for this FTB offset activity to pay the debt owed, and then send the claimant the balance of their unclaimed property. The offset program is currently, however, a temporarily authorized account. The author contends that to continue the intercept program, the account should be made permanent in statute.
According to the Controller's office, this offset program is similar to the Special Deposit Fund used by the Department of Child Support Services for child and spousal support intercept, as codified in Government Code Section 16377. The Child Support Intercept account is for the payment of child and spousal support obligations, and consists of all funds obtained by the state pursuant to child and spousal support intercept programs. In order to facilitate its permanent use, this bill would codify establishment of the Unclaimed Property Offset Account in the Special Deposit Fund, and provide that moneys in the account are continuously appropriated for the purpose of offsetting payment of funds to owners of unclaimed property that has escheated to the state, as specified.
Analysis Prepared by: Anthony Lew / JUD. / (916) 319-2334 FN: 0003040
Date of Hearing: April 4, 2018
ASSEMBLY COMMITTEE ON APPROPRIATIONS
Lorena Gonzalez Fletcher, Chair
ABPCA Bill Id:AB 2350
Author:(Obernolte) – As Introduced Ver:February 13, 2018
Policy Committee: | Judiciary | Vote: | 10 - 0 |
|
| ||
|
|
Urgency: No State Mandated Local Program: No Reimbursable: No
SUMMARY:
This bill, sponsored by the State Controller’s Office (SCO): 1) gives the SCO continuous appropriation authority to make payments from the Interest on Lawyers’ Trust Account (IOLTA) Claims Reserve Subaccount and 2) establishes the Unclaimed Property Offset Account and continuously appropriates money in the account for specified purposes.
FISCAL EFFECT:
- Continuously appropriates to the SCO funds in the IOLTA Claims Reserve Subaccount. According the SCO, no money has been deposited to the subaccount. However, SCO anticipates banks may deposit funds into the subaccount. SCO could not estimate the amount of fund that might be deposited into the account. Absent the continuous appropriation authorized by this bill, the SCO would need the Legislature to appropriate funds in the subaccount to the SCO before the SCO could distribute the funds for authorized uses.
- Establishes in the Special Deposit Fund in the State Treasury the Unclaimed Property Offset Account and continuously appropriates monies in the fund for the following purposes:
- Payment of moneys to a state agency, local agency, city, county, community college district, special district, or court, or any other state or local governmental entity, to offset the moneys owed by a person claiming to be the owner of unclaimed property that has escheated to the state.
- Payment of moneys to owners of unclaimed property that has escheated to the state after offsetting moneys paid as described in (a) above.
- Authorizes the SCO to transfer to the Unclaimed Property Offset Account moneys held by the Controller from property that has escheated to the state if the SCO has reason to believe the owner of the property has a debt to a state or local governmental entity.
- Negligible SCO administrative costs.
COMMENTS:
- Purpose. According to the author:
The State Controller operates the Abandoned Property Fund with continuous appropriation authorization from the Legislature. However, this authority does not apply to funds in the IOLTA Claim Reserve Subaccount. For the Controller to issue payments from this subaccount, the Legislature must provide an appropriation, which is inconsistent with the authority that applies to the rest of the fund. AB 2350 will give the State Controller continuous appropriation authority to make payments from the IOLTA, consistent with the authority to administer the rest of the Abandoned Property Fund.
The State Controller also operates an intercept program by using a Special Deposit Fund (SDF) that has been temporarily authorized by the Department of Finance to collect debts owed to governmental entities by individuals receiving their unclaimed property. To continue the intercept program, the account should be made permanent in statute. Accordingly, AB 2350 codifies the Controller’s use of a Special Deposit Fund, namely the Unclaimed Property Offset Account.
- IOLTA Claims Subaccount Subject to Legislative Appropriation. Current law requires attorneys to place their clients’ funds (advances for attorney expenses, etc.) in a special IOLTA account on which interest earnings are remitted to the California State Bar in order to fund indigent legal services. The state's Unclaimed Property Law (UPL) also provides that if there is no activity for a specified time (generally three years) on an account held by a bank or financial institution, the property in the account escheats to the state and the bank or financial institution is required to relinquish any unclaimed property in the account to the SCO.
Statute directs all monies received from funds held in an IOLTA account that escheats the state to the Abandoned IOLTA Property Account within the Unclaimed Property Fund, as follows:
- 25% of the funds are to be deposited into the IOLTA Claims Reserve Subaccount to be available to the SCO, upon appropriation by the Legislature, for the payment of all refunds, claims, and costs related to escheated IOLTA funds.
- The balance of the funds is transferred annually to the Public Interest Attorney Loan Repayment Account to provide funding for the Public Interest Attorney Loan Repayment Program.
- Statute Generally Prohibits Continuous Appropriations. Statute generally provides that no moneys in any fund that, by any statute other than a Budget Act, are continuously appropriated without regard to fiscal years may be encumbered unless the Legislature, by statute, specifies that the moneys in the fund are appropriated for encumbrance. Statute provides several exceptions to this general prohibition, principally for distribution of tax and fee revenue to local governments. This generally prohibition provides the Legislature the opportunity to regularly consider uses of funds for various purposes.
Nonetheless, statute continuously appropriates to the SCO all money in the Abandoned Property Account in the Unclaimed Property Fund. Arguably, money in any unclaimed or abandoned property account should be treated similarly to money in the Abandoned Property Account since the SCO uses the monies for similar purposes, that is, to pay refund claims and costs related to abandoned property.
- Analysis Prepared by: Jay Dickenson / APPR. / (916) 319-2081
Date of Hearing: March 20, 2018
ASSEMBLY COMMITTEE ON JUDICIARY
Mark Stone, Chair
ABPCA Bill Id:AB 2350
Author:(Obernolte) – As Introduced Ver:February 13, 2018
PROPOSED CONSENT
SUBJECT: UNCLAIMED PROPERTY
KEY ISSUE: should SPECIFied changes to various accounting and management procedures be made to streamline operation of the state controller's unclaimed property program and provide continuous appropriation authority for certain accounts?
SYNOPSIS
This non-controversial bill, sponsored by the State Controller, seeks to implement two separate changes to accounting procedures used by the Controller to manage escheated funds under the unclaimed property program. First, this bill seeks to provide the Controller with continuous appropriation authority to make loan repayments from the IOLTA Claim Reserve Subaccount, removing the administrative burden of waiting for an appropriation to administer the program. Under existing law, the Legislature must provide an appropriation in order for the Controller to issue funds from this Subaccount, generally for the purpose of paying refunds, claims, and costs associated with escheated IOLTA funds. The author contends a change is warranted because this is inconsistent with the continuous appropriation authority that applies to the rest of the Abandoned IOLTA Property Account, within which this Subaccount resides. Second, the bill codifies the Controller's use of the Unclaimed Property Offset Account, a so-called Special Deposit Fund temporarily authorized by the Department of Finance. The Offset Account allows the Controller to operate an intercept program to collect debts owed to governmental entities by individuals receiving their unclaimed property, and thus should be permanently authorized in statute to continue the intercept program on an ongoing basis. There is no known opposition to this bill.
SUMMARY: Gives the State Controller continuous appropriation authority to make payments from the IOLTA Claims Reserve Subaccount, and codifies the Controller's use of the Franchise Tax Board Offset Account. Specifically, this bill:
- Provides that, notwithstanding other law, funds in the IOLTA Claims Reserve Subaccount are continuously appropriated to the Controller (instead of upon appropriation by the Legislature) for the payment of all refunds, claims, and costs related to escheated IOLTA funds, as specified.
- Establishes the Unclaimed Property Offset Account in the Special Deposit Fund in the State Treasury, and provide that moneys in the account are continuously appropriated, for both of the following purposes:
- The payment of moneys to a state or local governmental entity, to offset the moneys owed by a person claiming to be the owner of unclaimed property that has escheated to the state under Title 10 (commencing with Section 1300) of Part 3 of the Code of Civil Procedure.
- The payment of moneys to owners of unclaimed property that has escheated to the state after offsetting moneys paid pursuant to 2a), above.
- Permits the Controller to transfer to the Unclaimed Property Offset Account moneys held by the Controller from property that has escheated to the state, as provided, if the Controller has reason to believe the owner of the property has a debt to a state or local governmental entity.
EXISTING LAW:
- Establishes the Public Interest Attorney Loan Repayment Program for licensed attorneys who practice or agree to practice in public interest areas of law in this state and provides that participants are eligible for a maximum of $11,000 in loan assistance over four years. (Education Code Sections 69741, 69741.5.)
- Establishes the Public Interest Attorney Loan Repayment Account within the State Treasury, and requires funds from an IOLTA account that escheat to the state and that are deposited into this Account to be used, upon appropriation by the Legislature, by the Student Aid Commission for the purpose of providing increased funding for the Public Interest Attorney Loan Repayment Program, as provided. (Business and Professions Code Section 6032.5.)
- Establishes the Abandoned IOLTA Property Account within the Unclaimed Property Fund, and provides that notwithstanding any law, any property held in an IOLTA account that escheats to the state shall be deposited into the Abandoned IOLTA Property Account. (Code of Civil Procedure Section 1564.5 (a).)
- Requires twenty-five percent (25%) of the money in the Abandoned IOLTA Property Account to be deposited into the IOLTA Claims Reserve Subaccount, within the Abandoned IOLTA Property Account. Further provides that funds in the subaccount shall, upon appropriation by the Legislature, be available to the Controller for the payment of all refunds, claims, and costs related to escheated IOLTA funds. (Code of Civil Procedure Section 1564.5 (b).)
- Requires the balance of the funds in the Abandoned IOLTA Property Account, excluding funds in the subaccount, to be transferred on an annual basis to the Public Interest Attorney Loan Repayment Account (See 1), above). Further requires the Controller, before making such a transfer, to record the name and last known address of each person appearing from the holders’ report to be entitled to the escheated property, and to make the record available for public inspection at all reasonable business hours. (Code of Civil Procedure Section 1564.5 (c).)
- Requires an attorney or law firm that receives or disburses trust funds to establish an interest bearing demand trust account and to deposit in the account all client deposits that are nominal in amount or are on deposit or invested for a short period of time. (Business & Professions Code Section 6211 (a).)
- Provides, in the Unclaimed Property Law (UPL), for the escheat of property to the state and requires all property that escheats to the state to be deposited into the Abandoned Property Account in the Unclaimed Property Fund, which is continuously appropriated for specified purposes, and establishes procedures for submitting a claim for property that has escheated. (Code of Civil Procedure Section 1500 et seq.)
- Provides that moneys in any fund that, by any statute other than a Budget Act, are continuously appropriated without regard to fiscal years may be encumbered unless the Legislature, by statute, specifies that the moneys in the fund are appropriated for encumbrance. (Government Code Section 13340.)
FISCAL EFFECT: As currently in print this bill is keyed fiscal.
COMMENTS: This non-controversial bill, sponsored by the State Controller, seeks to implement two separate changes to accounting procedures used by the Controller to manage escheated funds under the unclaimed property program. According to the author:
The State Controller operates the Abandoned Property Fund with continuous appropriation authorization from the Legislature. However, this authority does not apply to funds in the Interest on Lawyers’ Trust Account (IOLTA) Claim Reserve Subaccount. For the Controller to issue payments from this subaccount, the Legislature must provide an appropriation, which is inconsistent with the authority that applies to the rest of the fund. AB 2350 will give the State Controller continuous appropriation authority to make payments from the Interest on Lawyers’ Trust Account (IOLTA), consistent with the authority to administer the rest of the Abandoned Property Fund
The State Controller also operates an intercept program by using a Special Deposit Fund (SDF) that has been temporarily authorized by the Department of Finance to collect debts owed to governmental entities by individuals receiving their unclaimed property. To continue the intercept program, the account should be made permanent in statute. Accordingly, AB 2350 codifies the Controller’s use of a Special Deposit Fund, namely the Unclaimed Property Offset Account.
Background on IOLTA. In the course of their legal practice, attorneys are frequently required to hold clients' funds for various lengths of time. It has long been recognized that attorneys have a professional and fiduciary obligation to avoid commingling their clients' money with their own. Before 1980, client funds were typically held in non-interest-bearing federally insured checking accounts. Because of federal banking regulations in effect since the Great Depression, banks were prohibited from paying interest on checking accounts. As a result, the value of the use of the clients' money in such accounts inured to the banking institutions.
In 1980, Congress authorized federally insured banks to pay interest on a limited category of demand deposits referred to as "NOW accounts." This category includes deposits made by individuals and charitable organizations, but does not include those made by for-profit corporations or partnerships unless the deposits are made pursuant to a program under which charitable organizations have "the exclusive right to the interest."
In response to the change in federal law, Florida adopted the first IOLTA program in 1981 authorizing the use of NOW accounts for the deposit of client funds, and providing that all of the interest on such accounts be used for charitable purposes. Every state in the nation and the District of Columbia has followed Florida's lead and adopted an IOLTA program, either through their legislatures or their highest courts. The result is that, whereas before 1980 the banks retained the value of the use of the money deposited in non-interest-bearing client trust accounts, today, because of the adoption of IOLTA programs, that value is transferred to charitable entities providing legal services for the poor. The aggregate value of those contributions in 2001 apparently exceeded $200 million. (Brown v. Legal Found. (2003) 538 U.S. 216, 221-223.)
Background on SB 134-- IOLTA Claims Reserve Subaccount. In order to address the high cost of a legal education and to encourage law students and new attorneys to pursue careers in public service, the Legislature enacted SB 134 (Hertzberg), Chap. 488, Stats. 2015, to require unclaimed funds in Interest on Lawyers’ Trust Accounts (IOLTA accounts), rather than escheating to the state, to be deposited into the newly created Public Interest Attorney Loan Repayment Account in the State Treasury for the purposes of providing, upon appropriation by the Legislature, additional funding for the Public Interest Attorney Loan Repayment Program.
Existing state law requires attorneys to place their clients’ funds (advances for attorney expenses, etc.) in a special IOLTA account on which interest is paid to the California State Bar in order to fund indigent legal services. Existing state law (the Unclaimed Property Law, or UPL) also provides that if there is no activity for a specified time (generally three years) on an account held by a bank or financial institution, the property in the account escheats to the state and the bank or financial institution (or “holder”) is required to relinquish any unclaimed property in the account to the Controller’s office. The Controller deposits all unclaimed funds, including funds from abandoned IOLTA accounts, into the Abandoned Property Account in the Unclaimed Property Fund, which is continuously appropriated by the state, as needed by the state’s General Fund. However, the owner of the escheated funds, or even the owner’s heirs, can always make a claim for the funds. When a claim is approved by the Controller, the state issues a check (without paying any interest on the funds) to the claimant.
The new law enacted by SB 134 effectively creates an exception to the Unclaimed Property Law for IOLTA funds that escheat to the state. Instead of being deposited in the Abandoned Property Account for use by the state’s General Fund until and unless the owners file claims for their return, abandoned IOLTA funds are deposited into the Public Interest Attorney Loan Repayment Account in the State Treasury for the purpose of providing, upon appropriation by the Legislature, additional funding for the Public Interest Attorney Loan Repayment Program and administering the program.
Codifying continuous appropriation authority for the IOLTA Claims Reserve Subaccount. As enacted by SB 134, CCP Section 1564.5 requires twenty-five percent (25%) of the money in the Abandoned IOLTA Property Account to be deposited into the IOLTA Claims Reserve Subaccount. The law also provides that funds in the subaccount shall, upon appropriation by the Legislature, be available to the Controller for the payment of all refunds, claims, and costs related to escheated IOLTA funds.
The Abandoned IOLTA Property Account has continuous appropriation authorization from the Legislature. However, this authority does not apply to funds in the IOLTA Claim Reserve Subaccount. For the Controller to issue loan repayments from this subaccount, the Legislature must provide an appropriation. The author notes that this is inconsistent with the authority that applies to the rest of the Abandoned IOLTA Property Account, within which this subaccount resides. Accordingly, this bill seeks to provide the Controller with continuous appropriation authority to make loan repayments from the IOLTA Claim Reserve Subaccount, removing the administrative burden of waiting for an appropriation to administer the program.
Codifying permanent authority for the Unclaimed Property Offset Account. According to the State Controller, its Unclaimed Property Division began participating in the Franchise Tax Board’s intercept program in September 2009. This program intercepts claim payments set to be mailed to people who owe money to the state of California, a county, a city or a special district. The Department of Finance granted the Controller the authority to establish an Unclaimed Property Offset account in the Special Deposit Fund to account for this FTB offset activity to pay the debt owed, and then send the claimant the balance of their unclaimed property. The offset program is currently, however, a temporarily authorized account. The author contends that to continue the intercept program, the account should be made permanent in statute.
According to the Controller's office, this offset program is similar to the Special Deposit Fund used by the Department of Child Support Services for child and spousal support intercept, as codified in Government Code Section 16377. The Child Support Intercept account is for the payment of child and spousal support obligations, and consists of all funds obtained by the state pursuant to child and spousal support intercept programs. In order to facilitate its permanent use, this bill would codify establishment of the Unclaimed Property Offset Account in the Special Deposit Fund, and provide that moneys in the account are continuously appropriated for the purpose of offsetting payment of funds to owners of unclaimed property that has escheated to the state, as specified.
REGISTERED SUPPORT / OPPOSITION:
Support
State Controller's Office
Opposition
None on file
Analysis Prepared by: Anthony Lew / JUD. / (916) 319-2334
Discussed in Hearing
 1MIN
Assembly Floor
 2MIN
Senate Floor
 1H
Senate Standing Committee on Appropriations
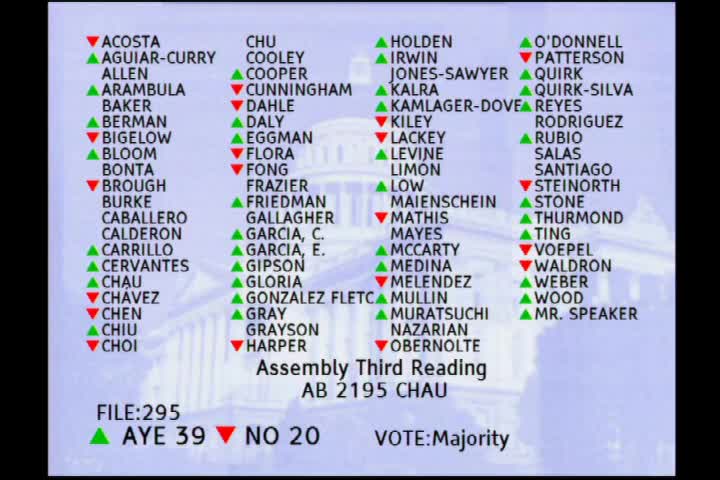 44SEC
Assembly Floor
Bill Author
Bill Co-Author(s):