SB 219: Greenhouse gases: climate corporate accountability: climate-related financial risk.
- Session Year: 2023-2024
- House: Senate
- Latest Version Date: 2024-09-27
Current Status:
Passed
(2024-09-27: Chaptered by Secretary of State. Chapter 766, Statutes of 2024.)
Introduced
In Committee
First Chamber
In Committee
Second Chamber
Enacted
Existing law, the Climate Corporate Data Accountability Act, requires, on or before January 1, 2025, the State Air Resources Board to develop and adopt regulations to require a reporting entity to annually disclose to the emissions reporting organization, as defined, all of the reporting entitys scope 1 emissions, scope 2 emissions, and scope 3 emissions, as defined. Existing law requires the state board to ensure that the regulations require a reporting entity, starting in 2027 and annually thereafter, to publicly disclose its scope 3 emissions no later than 180 days after its scope 1 emissions and scope 2 emissions are publicly disclosed to the emissions reporting organization. Existing law requires the reporting entities to pay an annual fee upon filing the disclosure. Existing law also requires the state board to contract with an emissions reporting organization to develop a reporting program to receive and make certain required disclosures publicly available, and sets forth other duties of the emissions reporting organization and the state board.
This bill would delay the requirement that the state board adopt regulations until July 1, 2025, and would require that the regulations adopted by the state board require, among other things, a reporting entity to make the annual disclosure to either the emissions reporting organization or the state board, and that the reporting entity publicly disclose its scope 3 emissions on a schedule specified by the state board, rather than no later than 180 days after its scope 1 emissions and scope 2 emissions are publicly disclosed. The bill would authorize reports to be consolidated at the parent company level and would delete the requirement that the annual fee be paid upon filing the disclosure. The bill would authorize, rather than require, the state board to contract with an emissions reporting organization to develop a reporting program to receive and make certain required disclosures publicly available. The bill would make other related changes to the duties of the emissions reporting organization and the state board, as provided.
Existing law requires, on or before January 1, 2026, and biennially thereafter, a covered entity, as defined to mean a corporation, partnership, limited liability company, or other business entity with total annual revenues in excess of $500,000,000, as specified, to prepare a climate-related financial risk report disclosing the entitys climate-related financial risk and measures adopted to reduce and adapt to climate-related financial risk. Existing law requires the state board to contract with a climate reporting organization, as defined, to prepare a biennial public report on the climate-related financial risk disclosures and requires the climate reporting organization to be contracted to take other actions, including biennially preparing a public report that includes a review of the disclosure of climate-related financial risk contained in a subset of publicly available climate-related financial risk reports and monitoring federal regulatory actions, as specified. Existing law requires, on or before January 1, 2026, and annually thereafter, a covered entity to pay a fee upon filing its disclosure to the state board for the administration and implementation of these requirements.
This bill would authorize, rather than require, the state board to contract with a climate reporting organization to carry out the above-described actions that the state board deems appropriate. The bill would also delete the requirement that the entitys fee be paid upon filing its disclosure.
Existing law, the Climate Corporate Data Accountability Act, requires, on or before January 1, 2025, the State Air Resources Board to develop and adopt regulations to require a reporting entity to annually disclose to the emissions reporting organization, as defined, all of the reporting entitys scope 1 emissions, scope 2 emissions, and scope 3 emissions, as defined. Existing law requires the state board to ensure that the regulations require a reporting entity, starting in 2027 and annually thereafter, to publicly disclose its scope 3 emissions no later than 180 days after its scope 1 emissions and scope 2 emissions are publicly disclosed to the emissions reporting organization. Existing law requires the reporting entities to pay an annual fee upon filing the disclosure. Existing law also requires the state board to contract with an emissions reporting organization to develop a reporting program to receive and make certain required disclosures publicly available, and sets forth other duties of the emissions reporting organization and the state board.
This bill would delay the requirement that the state board adopt regulations until July 1, 2025, and would require that the regulations adopted by the state board require, among other things, a reporting entity to make the annual disclosure to either the emissions reporting organization or the state board, and that the reporting entity publicly disclose its scope 3 emissions on a schedule specified by the state board, rather than no later than 180 days after its scope 1 emissions and scope 2 emissions are publicly disclosed. The bill would authorize reports to be consolidated at the parent company level and would delete the requirement that the annual fee be paid upon filing the disclosure. The bill would authorize, rather than require, the state board to contract with an emissions reporting organization to develop a reporting program to receive and make certain required disclosures publicly available. The bill would make other related changes to the duties of the emissions reporting organization and the state board, as provided.
Existing law requires, on or before January 1, 2026, and biennially thereafter, a covered entity, as defined to mean a corporation, partnership, limited liability company, or other business entity with total annual revenues in excess of $500,000,000, as specified, to prepare a climate-related financial risk report disclosing the entitys climate-related financial risk and measures adopted to reduce and adapt to climate-related financial risk. Existing law requires the state board to contract with a climate reporting organization, as defined, to prepare a biennial public report on the climate-related financial risk disclosures and requires the climate reporting organization to be contracted to take other actions, including biennially preparing a public report that includes a review of the disclosure of climate-related financial risk contained in a subset of publicly available climate-related financial risk reports and monitoring federal regulatory actions, as specified. Existing law requires, on or before January 1, 2026, and annually thereafter, a covered entity to pay a fee upon filing its disclosure to the state board for the administration and implementation of these requirements.
This bill would authorize, rather than require, the state board to contract with a climate reporting organization to carry out the above-described actions that the state board deems appropriate. The bill would also delete the requirement that the entitys fee be paid upon filing its disclosure.
Existing law, the Climate Corporate Data Accountability Act, requires, on or before January 1, 2025, the State Air Resources Board to develop and adopt regulations to require a reporting entity to annually disclose to the emissions reporting organization, as defined, all of the reporting entitys scope 1 emissions, scope 2 emissions, and scope 3 emissions, as defined. Existing law requires the state board to ensure that the regulations require a reporting entity, starting in 2027 and annually thereafter, to publicly disclose its scope 3 emissions no later than 180 days after its scope 1 emissions and scope 2 emissions are publicly disclosed to the emissions reporting organization. Existing law requires the reporting entities to pay an annual fee upon filing the disclosure. Existing law also requires the state board to contract with an emissions reporting organization to develop a reporting program to receive and make certain required disclosures publicly available, and sets forth other duties of the emissions reporting organization and the state board.
This bill would delay the requirement that the state board adopt regulations until July 1, 2025, and would require that the regulations adopted by the state board require, among other things, a reporting entity to make the annual disclosure to either the emissions reporting organization or the state board, and that the reporting entity publicly disclose its scope 3 emissions on a schedule specified by the state board, rather than no later than 180 days after its scope 1 emissions and scope 2 emissions are publicly disclosed. The bill would authorize reports to be consolidated at the parent company level and would delete the requirement that the annual fee be paid upon filing the disclosure. The bill would authorize, rather than require, the state board to contract with an emissions reporting organization to develop a reporting program to receive and make certain required disclosures publicly available. The bill would make other related changes to the duties of the emissions reporting organization and the state board, as provided.
Existing law requires, on or before January 1, 2026, and biennially thereafter, a covered entity, as defined to mean a corporation, partnership, limited liability company, or other business entity with total annual revenues in excess of $500,000,000, as specified, to prepare a climate-related financial risk report disclosing the entitys climate-related financial risk and measures adopted to reduce and adapt to climate-related financial risk. Existing law requires the state board to contract with a climate reporting organization, as defined, to prepare a biennial public report on the climate-related financial risk disclosures required by the act and requires the climate reporting organization to be contracted to take other actions, including biennially preparing a public report that includes a review of the disclosure of climate-related financial risk contained in a subset of publicly available climate-related financial risk reports and monitoring federal regulatory actions, as specified. Existing law requires, on or before January 1, 2026, and annually thereafter, a covered entity to pay a fee upon filing its disclosure to the state board for the administration and implementation of these requirements.
This bill would authorize, rather than require, the state board to contract with a climate reporting organization to carry out the above-described actions that the state board deems appropriate. The bill would also delete the requirement that the entitys fee be paid upon filing its disclosure.
Existing law, the Climate Corporate Data Accountability Act, requires, on or before January 1, 2025, the State Air Resources Board to develop and adopt regulations to require a reporting entity to annually disclose to the emissions reporting organization, as defined, all of the reporting entitys scope 1 emissions, scope 2 emissions, and scope 3 emissions, as defined. Existing law requires the state board to ensure that the regulations require a reporting entity, starting in 2027 and annually thereafter, to publicly disclose its scope 3 emissions no later than 180 days after its scope 1 emissions and scope 2 emissions are publicly disclosed to the emissions reporting organization. Existing law requires the reporting entities to pay an annual fee upon filing the disclosure. Existing law also requires the state board to contract with an emissions reporting organization to develop a reporting program to receive and make certain required disclosures publicly available, and sets forth other duties of the emissions reporting organization and the state board.
This bill would delay the requirement that the state board adopt regulations until July 1, 2025, and would require that the regulations adopted by the state board require, among other things, a reporting entity to make the annual disclosure to either the emissions reporting organization or the state board, and that the reporting entity publicly disclose its scope 3 emissions on a schedule specified by the state board, rather than no later than 180 days after its scope 1 emissions and scope 2 emissions are publicly disclosed. The bill would authorize reports to be consolidated at the parent company level and would delete the requirement that the annual fee be paid upon filing the disclosure. The bill would authorize, rather than require, the state board to contract with an emissions reporting organization to develop a reporting program to receive and make certain required disclosures publicly available. The bill would make other related changes to the duties of the emissions reporting organization and the state board, as provided.
Existing law requires, on or before January 1, 2026, and biennially thereafter, a covered entity, as defined to mean a corporation, partnership, limited liability company, or other business entity with total annual revenues in excess of $500,000,000, as specified, to prepare a climate-related financial risk report disclosing the entitys climate-related financial risk and measures adopted to reduce and adapt to climate-related financial risk. Existing law requires the state board to contract with a climate reporting organization, as defined, to prepare a biennial public report on the climate-related financial risk disclosures required by the act and requires the climate reporting organization to be contracted to take other actions, including biennially preparing a public report that includes a review of the disclosure of climate-related financial risk contained in a subset of publicly available climate-related financial risk reports and monitoring federal regulatory actions, as specified. Existing law requires, on or before January 1, 2026, and annually thereafter, a covered entity to pay a fee upon filing its disclosure to the state board for the administration and implementation of these requirements.
This bill would authorize, rather than require, the state board to contract with a climate reporting organization to carry out the above-described actions that the state board deems appropriate. The bill would also delete the requirement that the entitys fee be paid upon filing its disclosure.
This bill would express the intent of the Legislature to enact statutory changes relating to the Budget Act of 2023.This bill would express the intent of the Legislature to enact statutory changes relating to the Budget Act of 2023.
(a)This section shall be known, and may be cited, as the Climate Corporate Data Accountability Act.
(b)For purposes of this section, the following terms have the following definitions:
(1)Emissions reporting organization means a nonprofit emissions reporting organization contracted by the state board pursuant to paragraph (3) of subdivision (c) that both:
(A)Currently operates a greenhouse gas emission reporting organization for organizations operating in the United States.
(B)Has experience with greenhouse gas emissions disclosure by entities operating in California.
(2)Reporting entity means a partnership, corporation, limited liability company, or other business entity formed under the laws of this state, the laws of any other state of the United States or the District of Columbia, or under an act of the Congress of the United States with total annual revenues in excess of one billion dollars ($1,000,000,000) and that does business in California. Applicability shall be determined based on the reporting entitys revenue for the prior fiscal year.
(3)Scope 1 emissions means all direct greenhouse gas emissions that stem from sources that a reporting entity owns or directly controls, regardless of location, including, but not limited to, fuel combustion activities.
(4)Scope 2 emissions means indirect greenhouse gas emissions from consumed electricity, steam, heating, or cooling purchased or acquired by a reporting entity, regardless of location.
(5)Scope 3 emissions means indirect upstream and downstream greenhouse gas emissions, other than scope 2 emissions, from sources that the reporting entity does not own or directly control and may include, but are not limited to, purchased goods and services, business travel, employee commutes, and processing and use of sold products.
(c)(1)On or before July 1, 2025, the state board shall develop and adopt regulations to require a reporting entity to annually disclose all of the reporting entitys scope 1 emissions, scope 2 emissions, and scope 3 emissions, and obtain an assurance engagement performed by an independent third-party assurance provider. Those regulations shall require the reporting entity to make the annual disclosure to either of the following:
(A)The emissions reporting organization, if contracted for services.
(B)The state board.
(2)The state board shall ensure that the regulations adopted pursuant to this subdivision require all of the following:
(A)(i)(I)That a reporting entity, starting in 2026 on or by a date to be determined by the state board, and annually thereafter on or by that date, publicly disclose to the emissions reporting organization, if contracted for services, or the state board, all of the reporting entitys scope 1 emissions and scope 2 emissions for the reporting entitys prior fiscal year.
(II)That a reporting entity, starting in 2027 and annually thereafter, publicly disclose its scope 3 emissions on a schedule specified by the state board as part of the regulations developed pursuant to this subdivision for the prior fiscal year.
(ii)A reporting entity shall, beginning in 2026, measure and report its emissions of greenhouse gases in conformance with the Greenhouse Gas Protocol standards and guidance, including the Greenhouse Gas Protocol Corporate Accounting and Reporting Standard and the Greenhouse Gas Protocol Corporate Value Chain (Scope 3) Accounting and Reporting Standard developed by the World Resources Institute and the World Business Council for Sustainable Development, including guidance for scope 3 emissions calculations that detail acceptable use of both primary and secondary data sources, including the use of industry average data, proxy data, and other generic data in its scope 3 emissions calculations.
(iii)Reports may be consolidated at the parent company level. If a subsidiary of a parent company qualifies as a reporting entity pursuant to paragraph (2) of subdivision (b), the subsidiary is not required to prepare a separate report.
(iv)(I)Starting in 2033, the state board may survey and assess currently available greenhouse gas accounting and reporting standards. At the conclusion of this assessment the state board may adopt a globally recognized alternative accounting and reporting standard if it determines its use would more effectively further the goals of this section. This review process shall include consultation with the stakeholders identified in paragraph (5).
(II)If the state board adopts an alternative accounting and reporting standard, the state board shall develop and adopt new regulations, pursuant to paragraph (1), to ensure full conformance with the new standard and reporting of scope 1 emissions, scope 2 emissions, and scope 3 emissions and other requirements of this section.
(v)During 2029 the state board shall review, and on or before January 1, 2030, the state board shall update as necessary, the public disclosure deadlines established pursuant to clause (i) to evaluate trends in scope 3 emissions reporting and consider changes to the disclosure deadlines to ensure that scope 3 emissions data is disclosed to the emissions reporting organization, if contracted for services, or the state board, as close in time as practicable to the deadline for reporting entities to disclose scope 1 emissions and scope 2 emissions data.
(vi)The reporting timelines shall consider industry stakeholder input and shall take into account the timelines by which reporting entities typically receive scope 1 emissions, scope 2 emissions, and scope 3 emissions data, as well as the capacity for an independent assurance engagement to be performed by a third-party assurance provider.
(B)That a reporting entitys public disclosure maximizes access for consumers, investors, and other stakeholders to comprehensive and detailed greenhouse gas emissions data across scope 1 emissions, scope 2 emissions, and scope 3 emissions, as defined by this section, and is made in a manner that is easily understandable and accessible.
(C)That a reporting entitys public disclosure includes the name of the reporting entity and any fictitious names, trade names, assumed names, and logos used by the reporting entity.
(D)(i)That the emissions reporting is structured in a way that minimizes duplication of effort and allows a reporting entity to submit to the emissions reporting organization, if contracted for services, or the state board, reports prepared to meet other national and international reporting requirements, including any reports required by the federal government, as long as those reports satisfy all of the requirements of this section.
(ii)Reporting entities that are required to report mandatory industrial emissions pursuant to regulations adopted pursuant to Section 38530 may provide that data with the disclosure required pursuant to this section.
(E)That a reporting entitys disclosure takes into account acquisitions, divestments, mergers, and other structural changes that can affect the greenhouse gas emissions reporting, and is disclosed in a manner consistent with the Greenhouse Gas Protocol standards and guidance or an alternative standard, if one is adopted after 2033.
(F)(i)That a reporting entity obtains an assurance engagement, performed by an independent third-party assurance provider, of their public disclosure. The reporting entity shall ensure that a copy of the complete assurance providers report on the greenhouse gas emissions inventory, including the name of the third-party assurance provider, is provided to the emissions reporting organization, if contracted for services, or the state board, as part of or in connection with the reporting entitys public disclosure.
(ii)The assurance engagement for scope 1 emissions and scope 2 emissions shall be performed at a limited assurance level beginning in 2026 and at a reasonable assurance level beginning in 2030.
(iii)During 2026, the state board shall review and evaluate trends in third-party assurance requirements for scope 3 emissions. On or before January 1, 2027, the state board may establish an assurance requirement for third-party assurance engagements of scope 3 emissions. The assurance engagement for scope 3 emissions shall be performed at a limited assurance level beginning in 2030.
(iv)A third-party assurance provider shall have significant experience in measuring, analyzing, reporting, or attesting to the emission of greenhouse gasses and sufficient competence and capabilities necessary to perform engagements in accordance with professional standards and applicable legal and regulatory requirements. The assurance provider shall be able to issue reports that are appropriate under the circumstances and independent with respect to the reporting entity, and any of the reporting entitys affiliates for which it is providing the assurance report. During 2029 the state board shall review and, on or before January 1, 2030, shall update as necessary, the qualifications for third-party assurance providers based on an evaluation of trends in education relating to the emission of greenhouse gases and the qualifications of third-party assurance providers.
(v)The state board shall ensure that the assurance process minimizes the need for reporting entities to engage multiple assurance providers and ensures sufficient assurance provider capacity, as well as timely reporting implementation as required under clause (i) of subparagraph (A).
(G)(i)That a reporting entity shall pay an annual fee to the state board for the administration and implementation of this section.
(ii)The state board shall set the fee established pursuant to clause (i) in an amount sufficient to cover the state boards full costs of administrating and implementing this section. The total amount of fees collected shall not exceed the state boards actual and reasonable costs to administer and implement this section.
(iii)The proceeds of the fees imposed pursuant to clause (i) shall be deposited in the Climate Accountability and Emissions Disclosure Fund, which is hereby created in the State Treasury. Notwithstanding Section 13340 of the Government Code, the money in the fund is continuously appropriated to the state board and shall be expended by the state board for the state boards activities pursuant to this section and to reimburse any outstanding loans made from other funds used to finance the initial costs of the state boards activities pursuant to this section. Moneys in the fund shall not be expended for any purpose not enumerated in this section.
(iv)The state board may adjust the fee in any year to reflect changes in the California Consumer Price Index during the prior year.
(3)The state board may contract with an emissions reporting organization to develop a reporting program to receive and make publicly available disclosures required by this section pursuant to paragraph (1).
(4)The state board may adopt or update any other regulations that it deems necessary and appropriate to implement this section.
(5)In developing the regulations required pursuant to this subdivision, the state board shall consult with all of the following:
(A)The Attorney General.
(B)Other government stakeholders, including, but not limited to, experts in climate science and corporate carbon emissions accounting and reporting.
(C)Investors.
(D)Stakeholders representing consumer and environmental justice interests.
(E)Reporting entities that have demonstrated leadership in full-scope greenhouse gas emissions accounting and public disclosure and greenhouse gas emissions reductions.
(6)This section does not require additional reporting of emissions of greenhouse gases beyond the reporting of scope 1 emissions, scope 2 emissions, and scope 3 emissions required pursuant to the Greenhouse Gas Protocol standards and guidance or an alternative standard, if one is adopted after 2033.
(d)(1)On or before July 1, 2027, the state board shall contract with the University of California, the California State University, a national laboratory, or another equivalent academic institution to prepare a report on the public disclosures made by reporting entities to the emissions reporting organization, if contracted for services, or the state board, pursuant to subdivision (c) and the regulations adopted by the state board pursuant to that subdivision. In preparing the report, consideration shall be given to, at a minimum, greenhouse gas emissions from reporting entities in the context of state greenhouse gas emissions reduction and climate goals. The entity preparing the report shall not require reporting entities to report any information beyond what is required pursuant to subdivision (c) or the regulations adopted by the state board pursuant to that subdivision.
(2)The state board shall ensure the report required by this subdivision is posted publicly by either of the following:
(A)The emissions reporting organization, if contracted for services, to be made publicly available on the digital platform required to be created by the emissions reporting organization pursuant to subdivision (e).
(B)The state board on its public internet website.
(e)(1)(A)The state board, or the emissions reporting organization, if contracted for services, on or before the date determined by the state board pursuant to clause (i) of subparagraph (A) of paragraph (2) of subdivision (c), shall create a digital platform, which shall be accessible to the public, that will feature the emissions data of reporting entities in conformance with the regulations adopted by the state board pursuant to subdivision (c) and the report prepared for the state board pursuant to subdivision (d). The state board, or the emissions reporting organization, if contracted for services, shall make the reporting entities disclosures and the state boards report available on the digital platform no later than 90 days after receipt.
(B)The digital platform shall be capable of featuring individual reporting entity disclosures, and shall allow consumers, investors, and other stakeholders to view reported data elements aggregated in a variety of ways, including multiyear data, in a manner that is easily understandable and accessible to residents of the state. All data sets and customized views shall be available in electronic format for access and use by the public.
(C)Any contract for services with a reporting organization shall be considered a noninformation technology services contract for procurement purposes.
(2)The emissions reporting organization, if contracted for services, or the state board, shall submit, within 30 days of receipt, the report prepared for the state board pursuant to subdivision (d) to the relevant policy committees of the Legislature.
(f)(1)Section 38580 does not apply to a violation of this section.
(2)(A)The state board shall adopt regulations that authorize it to seek administrative penalties for nonfiling, late filing, or other failure to meet the requirements of this section. The administrative penalties authorized by this section shall be imposed and recovered by the state board in administrative hearings conducted pursuant to Article 3 (commencing with Section 60065.1) and Article 4 (commencing with Section 60075.1) of Subchapter 1.25 of Chapter 1 of Division 3 of Title 17 of the California Code of Regulations. The administrative penalties imposed on a reporting entity shall not exceed five hundred thousand dollars ($500,000) in a reporting year. In imposing penalties for a violation of this section, the state board shall consider all relevant circumstances, including both of the following:
(i)The violators past and present compliance with this section.
(ii)Whether the violator took good faith measures to comply with this section and when those measures were taken.
(B) A reporting entity shall not be subject to an administrative penalty under this section for any misstatements with regard to scope 3 emissions disclosures made with a reasonable basis and disclosed in good faith.
(C)Penalties assessed on scope 3 reporting, between 2027 and 2030, shall only occur for nonfiling.
(g)This section applies to the University of California only to the extent that the Regents of the University of California, by resolution, make any of these provisions applicable to the university.
(h) The provisions of this section are severable. If any provision of this section or its application is held invalid, that invalidity shall not affect other provisions or applications that can be given effect without the invalid provision or application.
SEC. 2.Section 38533 of the Health and Safety Code is amended to read:38533.(a)For purposes of this section, the following definitions apply:
(1)Climate reporting organization means a nonprofit climate reporting organization contracted by the state board pursuant to subdivision (d) that both:
(A)Currently operates a climate reporting organization for organizations operating in the United States.
(B)Has experience with climate-related financial risk disclosure by entities operating in California.
(2)Climate-related financial risk means material risk of harm to immediate and long-term financial outcomes due to physical and transition risks, including, but not limited to, risks to corporate operations, provision of goods and services, supply chains, employee health and safety, capital and financial investments, institutional investments, financial standing of loan recipients and borrowers, shareholder value, consumer demand, and financial markets and economic health.
(3)Climate-related financial risk report means a report required by subdivision (b).
(4)Covered entity means a corporation, partnership, limited liability company, or other business entity formed under the laws of the state, the laws of any other state of the United States or the District of Columbia, or under an act of the Congress of the United States with total annual revenues in excess of five hundred million United States dollars ($500,000,000) and that does business in California. Applicability shall be determined based on the business entitys revenue for the prior fiscal year. Covered entity does not include a business entity that is subject to regulation by the Department of Insurance in this state, or that is in the business of insurance in any other state.
(b)(1)(A)On or before January 1, 2026, and biennially thereafter, a covered entity shall prepare a climate-related financial risk report disclosing both of the following:
(i)Its climate-related financial risk, in accordance with the recommended framework and disclosures contained in the Final Report of Recommendations of the Task Force on Climate-related Financial Disclosures (June 2017) published by the Task Force on Climate-related Financial Disclosures, or any successor thereto, or pursuant to an equivalent reporting requirement as described in paragraph (3).
(ii)Its measures adopted to reduce and adapt to climate-related financial risk disclosed pursuant to clause (i).
(B)If a covered entity does not complete a report consistent with all required disclosures pursuant to clause (i) of subparagraph (A), the covered entity shall provide the recommended disclosures to the best of its ability, provide a detailed explanation for any reporting gaps, and describe steps the covered entity will take to prepare complete disclosures.
(2)Climate-related financial risk reports may be consolidated at the parent company level. If a subsidiary of a parent company qualifies as a covered entity pursuant to paragraph (4) of subdivision (a), the subsidiary is not required to prepare a separate climate-related financial risk report.
(3)Notwithstanding paragraph (1), a covered entity satisfies the requirements of paragraph (1) if it prepares a publicly accessible biennial report that includes climate-related financial risk disclosure information by any of the following methods:
(A)Pursuant to a law, regulation, or listing requirement issued by any regulated exchange, national government, or other governmental entity, including a law or regulation issued by the United States government, incorporating disclosure requirements consistent with clause (i) of subparagraph (A) of paragraph (1), including the International Financial Reporting Standards Sustainability Disclosure Standards, as issued by the International Sustainability Standards Board.
(B)Voluntarily using a framework that meets the requirements of clause (i) of subparagraph (A) of paragraph (1) or the International Financial Reporting Standards Sustainability Disclosure Standards, as issued by the International Sustainability Standards Board.
(4)To the extent a climate-related financial risk report contains a description of a covered entitys greenhouse gas emissions or voluntary mitigation of greenhouse gas emissions, the state board may consider the covered entitys claims if those claims are verified by a third-party independent verifier.
(c)(1)On or before January 1, 2026, and biennially thereafter, a covered entity shall make available to the public, on its own internet website, a copy of the report required by this section.
(2)(A)On or before January 1, 2026, and annually thereafter, a covered entity shall pay a fee to the state board for the administration and implementation of this section.
(B)(i)The state board shall set the fee described in subparagraph (A) at an amount adequate to cover the state boards full costs of administrating and implementing this section. The total amount of fees collected shall not exceed the state boards actual and reasonable costs to administer and implement this section.
(ii)The state board may adjust the fee in any year to reflect changes in the California Consumer Price Index during the prior year.
(C)The proceeds of the fees imposed pursuant to this paragraph shall be deposited in the Climate-Related Financial Risk Disclosure Fund, which is hereby created in the State Treasury. Notwithstanding Section 13340 of the Government Code, the money in the fund is continuously appropriated to the state board and shall be expended by the state board for the state boards activities pursuant to this section and to reimburse any outstanding loans made from other funds used to finance the initial costs of the state boards activities pursuant to this section. Money in the fund shall not be expended for any other purpose not described in this subparagraph.
(d)The state board may contract with a climate reporting organization to do any of the following it deems appropriate:
(1)Biennially prepare a public report that contains all of the following elements:
(A)A review of the disclosure of climate-related financial risk contained in a subset of publicly available climate-related financial risk reports by industry.
(B)Analysis of the systemic and sectorwide climate-related financial risks facing the state based on the contents of climate-related financial risk reports, including, but not limited to, potential impacts on economically vulnerable communities.
(C)Identification of inadequate or insufficient reports.
(2)Regularly convene representatives of sectors responsible for reporting climate-related financial risks, state agencies responsible for oversight of reporting sectors, investment managers, academic experts, standard-setting organizations, climate and corporate sustainability organizations, labor union representatives whose members work in impacted sectors, and other stakeholders to offer input on current best practices regarding the disclosure of financial risks resulting from climate change, including, but not limited to, proposals to update the definition of climate-related financial risk, and the framework or disclosure standard of climate-related financial risk reports that meets the requirements of clause (i) of subparagraph (A) of paragraph (1) of subdivision (b).
(3)Monitor federal regulatory actions among agency members of the federal Financial Stability Oversight Council, as well as nonindependent regulators overseen by the White House.
(e)Any contract for services with a reporting organization shall be considered a noninformation technology services contract for procurement purposes.
(f)(1)Section 38580 does not apply to a violation of this section.
(2)The state board shall adopt regulations that authorize it to seek administrative penalties from a covered entity that fails to make the report required by this section publicly available on its internet website or publishes an inadequate or insufficient report. The administrative penalties authorized by this section shall be imposed and recovered by the state board in administrative hearings conducted pursuant to Article 3 (commencing with Section 60065.1) and Article 4 (commencing with Section 60075.1) of Subchapter 1.25 of Chapter 1 of Division 3 of Title 17 of the California Code of Regulations. The administrative penalties imposed on a reporting entity shall not exceed fifty thousand dollars ($50,000) in a reporting year. In imposing penalties for a violation of this section, the state board shall consider all relevant circumstances, including both of the following:
(A)The violators past and present compliance with this section.
(B)Whether the violator took good faith measures to comply with this section and when those measures were taken.
(a)This section shall be known, and may be cited, as the Climate Corporate Data Accountability Act.
(b)For purposes of this section, the following terms have the following definitions:
(1)Emissions reporting organization means a nonprofit emissions reporting organization contracted by the state board pursuant to paragraph (3) of subdivision (c) that both:
(A)Currently operates a greenhouse gas emission reporting organization for organizations operating in the United States.
(B)Has experience with greenhouse gas emissions disclosure by entities operating in California.
(2)Reporting entity means a partnership, corporation, limited liability company, or other business entity formed under the laws of this state, the laws of any other state of the United States or the District of Columbia, or under an act of the Congress of the United States with total annual revenues in excess of one billion dollars ($1,000,000,000) and that does business in California. Applicability shall be determined based on the reporting entitys revenue for the prior fiscal year.
(3)Scope 1 emissions means all direct greenhouse gas emissions that stem from sources that a reporting entity owns or directly controls, regardless of location, including, but not limited to, fuel combustion activities.
(4)Scope 2 emissions means indirect greenhouse gas emissions from consumed electricity, steam, heating, or cooling purchased or acquired by a reporting entity, regardless of location.
(5)Scope 3 emissions means indirect upstream and downstream greenhouse gas emissions, other than scope 2 emissions, from sources that the reporting entity does not own or directly control and may include, but are not limited to, purchased goods and services, business travel, employee commutes, and processing and use of sold products.
(c)(1)On or before July 1, 2025, the state board shall develop and adopt regulations to require a reporting entity to annually disclose all of the reporting entitys scope 1 emissions, scope 2 emissions, and scope 3 emissions, and obtain an assurance engagement performed by an independent third-party assurance provider. Those regulations shall require the reporting entity to make the annual disclosure to either of the following:
(A)The emissions reporting organization, if contracted for services.
(B)The state board.
(2)The state board shall ensure that the regulations adopted pursuant to this subdivision require all of the following:
(A)(i)(I)That a reporting entity, starting in 2026 on or by a date to be determined by the state board, and annually thereafter on or by that date, publicly disclose to the emissions reporting organization, if contracted for services, or the state board, all of the reporting entitys scope 1 emissions and scope 2 emissions for the reporting entitys prior fiscal year.
(II)That a reporting entity, starting in 2027 and annually thereafter, publicly disclose its scope 3 emissions on a schedule specified by the state board as part of the regulations developed pursuant to this subdivision for the prior fiscal year.
(ii)A reporting entity shall, beginning in 2026, measure and report its emissions of greenhouse gases in conformance with the Greenhouse Gas Protocol standards and guidance, including the Greenhouse Gas Protocol Corporate Accounting and Reporting Standard and the Greenhouse Gas Protocol Corporate Value Chain (Scope 3) Accounting and Reporting Standard developed by the World Resources Institute and the World Business Council for Sustainable Development, including guidance for scope 3 emissions calculations that detail acceptable use of both primary and secondary data sources, including the use of industry average data, proxy data, and other generic data in its scope 3 emissions calculations.
(iii)Reports may be consolidated at the parent company level. If a subsidiary of a parent company qualifies as a reporting entity pursuant to paragraph (2) of subdivision (b), the subsidiary is not required to prepare a separate report.
(iv)(I)Starting in 2033, the state board may survey and assess currently available greenhouse gas accounting and reporting standards. At the conclusion of this assessment the state board may adopt a globally recognized alternative accounting and reporting standard if it determines its use would more effectively further the goals of this section. This review process shall include consultation with the stakeholders identified in paragraph (5).
(II)If the state board adopts an alternative accounting and reporting standard, the state board shall develop and adopt new regulations, pursuant to paragraph (1), to ensure full conformance with the new standard and reporting of scope 1 emissions, scope 2 emissions, and scope 3 emissions and other requirements of this section.
(v)During 2029 the state board shall review, and on or before January 1, 2030, the state board shall update as necessary, the public disclosure deadlines established pursuant to clause (i) to evaluate trends in scope 3 emissions reporting and consider changes to the disclosure deadlines to ensure that scope 3 emissions data is disclosed to the emissions reporting organization, if contracted for services, or the state board, as close in time as practicable to the deadline for reporting entities to disclose scope 1 emissions and scope 2 emissions data.
(vi)The reporting timelines shall consider industry stakeholder input and shall take into account the timelines by which reporting entities typically receive scope 1 emissions, scope 2 emissions, and scope 3 emissions data, as well as the capacity for an independent assurance engagement to be performed by a third-party assurance provider.
(B)That a reporting entitys public disclosure maximizes access for consumers, investors, and other stakeholders to comprehensive and detailed greenhouse gas emissions data across scope 1 emissions, scope 2 emissions, and scope 3 emissions, as defined by this section, and is made in a manner that is easily understandable and accessible.
(C)That a reporting entitys public disclosure includes the name of the reporting entity and any fictitious names, trade names, assumed names, and logos used by the reporting entity.
(D)(i)That the emissions reporting is structured in a way that minimizes duplication of effort and allows a reporting entity to submit to the emissions reporting organization, if contracted for services, or the state board, reports prepared to meet other national and international reporting requirements, including any reports required by the federal government, as long as those reports satisfy all of the requirements of this section.
(ii)Reporting entities that are required to report mandatory industrial emissions pursuant to regulations adopted pursuant to Section 38530 may provide that data with the disclosure required pursuant to this section.
(E)That a reporting entitys disclosure takes into account acquisitions, divestments, mergers, and other structural changes that can affect the greenhouse gas emissions reporting, and is disclosed in a manner consistent with the Greenhouse Gas Protocol standards and guidance or an alternative standard, if one is adopted after 2033.
(F)(i)That a reporting entity obtains an assurance engagement, performed by an independent third-party assurance provider, of their public disclosure. The reporting entity shall ensure that a copy of the complete assurance providers report on the greenhouse gas emissions inventory, including the name of the third-party assurance provider, is provided to the emissions reporting organization, if contracted for services, or the state board, as part of or in connection with the reporting entitys public disclosure.
(ii)The assurance engagement for scope 1 emissions and scope 2 emissions shall be performed at a limited assurance level beginning in 2026 and at a reasonable assurance level beginning in 2030.
(iii)During 2026, the state board shall review and evaluate trends in third-party assurance requirements for scope 3 emissions. On or before January 1, 2027, the state board may establish an assurance requirement for third-party assurance engagements of scope 3 emissions. The assurance engagement for scope 3 emissions shall be performed at a limited assurance level beginning in 2030.
(iv)A third-party assurance provider shall have significant experience in measuring, analyzing, reporting, or attesting to the emission of greenhouse gasses and sufficient competence and capabilities necessary to perform engagements in accordance with professional standards and applicable legal and regulatory requirements. The assurance provider shall be able to issue reports that are appropriate under the circumstances and independent with respect to the reporting entity, and any of the reporting entitys affiliates for which it is providing the assurance report. During 2029 the state board shall review and, on or before January 1, 2030, shall update as necessary, the qualifications for third-party assurance providers based on an evaluation of trends in education relating to the emission of greenhouse gases and the qualifications of third-party assurance providers.
(v)The state board shall ensure that the assurance process minimizes the need for reporting entities to engage multiple assurance providers and ensures sufficient assurance provider capacity, as well as timely reporting implementation as required under clause (i) of subparagraph (A).
(G)(i)That a reporting entity shall pay an annual fee to the state board for the administration and implementation of this section.
(ii)The state board shall set the fee established pursuant to clause (i) in an amount sufficient to cover the state boards full costs of administrating and implementing this section. The total amount of fees collected shall not exceed the state boards actual and reasonable costs to administer and implement this section.
(iii)The proceeds of the fees imposed pursuant to clause (i) shall be deposited in the Climate Accountability and Emissions Disclosure Fund, which is hereby created in the State Treasury. Notwithstanding Section 13340 of the Government Code, the money in the fund is continuously appropriated to the state board and shall be expended by the state board for the state boards activities pursuant to this section and to reimburse any outstanding loans made from other funds used to finance the initial costs of the state boards activities pursuant to this section. Moneys in the fund shall not be expended for any purpose not enumerated in this section.
(iv)The state board may adjust the fee in any year to reflect changes in the California Consumer Price Index during the prior year.
(3)The state board may contract with an emissions reporting organization to develop a reporting program to receive and make publicly available disclosures required by this section pursuant to paragraph (1).
(4)The state board may adopt or update any other regulations that it deems necessary and appropriate to implement this section.
(5)In developing the regulations required pursuant to this subdivision, the state board shall consult with all of the following:
(A)The Attorney General.
(B)Other government stakeholders, including, but not limited to, experts in climate science and corporate carbon emissions accounting and reporting.
(C)Investors.
(D)Stakeholders representing consumer and environmental justice interests.
(E)Reporting entities that have demonstrated leadership in full-scope greenhouse gas emissions accounting and public disclosure and greenhouse gas emissions reductions.
(6)This section does not require additional reporting of emissions of greenhouse gases beyond the reporting of scope 1 emissions, scope 2 emissions, and scope 3 emissions required pursuant to the Greenhouse Gas Protocol standards and guidance or an alternative standard, if one is adopted after 2033.
(d)(1)On or before July 1, 2027, the state board shall contract with the University of California, the California State University, a national laboratory, or another equivalent academic institution to prepare a report on the public disclosures made by reporting entities to the emissions reporting organization, if contracted for services, or the state board, pursuant to subdivision (c) and the regulations adopted by the state board pursuant to that subdivision. In preparing the report, consideration shall be given to, at a minimum, greenhouse gas emissions from reporting entities in the context of state greenhouse gas emissions reduction and climate goals. The entity preparing the report shall not require reporting entities to report any information beyond what is required pursuant to subdivision (c) or the regulations adopted by the state board pursuant to that subdivision.
(2)The state board shall ensure the report required by this subdivision is posted publicly by either of the following:
(A)The emissions reporting organization, if contracted for services, to be made publicly available on the digital platform required to be created by the emissions reporting organization pursuant to subdivision (e).
(B)The state board on its public internet website.
(e)(1)(A)The state board, or the emissions reporting organization, if contracted for services, on or before the date determined by the state board pursuant to clause (i) of subparagraph (A) of paragraph (2) of subdivision (c), shall create a digital platform, which shall be accessible to the public, that will feature the emissions data of reporting entities in conformance with the regulations adopted by the state board pursuant to subdivision (c) and the report prepared for the state board pursuant to subdivision (d). The state board, or the emissions reporting organization, if contracted for services, shall make the reporting entities disclosures and the state boards report available on the digital platform no later than 90 days after receipt.
(B)The digital platform shall be capable of featuring individual reporting entity disclosures, and shall allow consumers, investors, and other stakeholders to view reported data elements aggregated in a variety of ways, including multiyear data, in a manner that is easily understandable and accessible to residents of the state. All data sets and customized views shall be available in electronic format for access and use by the public.
(C)Any contract for services with a reporting organization shall be considered a noninformation technology services contract for procurement purposes.
(2)The emissions reporting organization, if contracted for services, or the state board, shall submit, within 30 days of receipt, the report prepared for the state board pursuant to subdivision (d) to the relevant policy committees of the Legislature.
(f)(1)Section 38580 does not apply to a violation of this section.
(2)(A)The state board shall adopt regulations that authorize it to seek administrative penalties for nonfiling, late filing, or other failure to meet the requirements of this section. The administrative penalties authorized by this section shall be imposed and recovered by the state board in administrative hearings conducted pursuant to Article 3 (commencing with Section 60065.1) and Article 4 (commencing with Section 60075.1) of Subchapter 1.25 of Chapter 1 of Division 3 of Title 17 of the California Code of Regulations. The administrative penalties imposed on a reporting entity shall not exceed five hundred thousand dollars ($500,000) in a reporting year. In imposing penalties for a violation of this section, the state board shall consider all relevant circumstances, including both of the following:
(i)The violators past and present compliance with this section.
(ii)Whether the violator took good faith measures to comply with this section and when those measures were taken.
(B) A reporting entity shall not be subject to an administrative penalty under this section for any misstatements with regard to scope 3 emissions disclosures made with a reasonable basis and disclosed in good faith.
(C)Penalties assessed on scope 3 reporting, between 2027 and 2030, shall only occur for nonfiling.
(g)This section applies to the University of California only to the extent that the Regents of the University of California, by resolution, make any of these provisions applicable to the university.
(h) The provisions of this section are severable. If any provision of this section or its application is held invalid, that invalidity shall not affect other provisions or applications that can be given effect without the invalid provision or application.
SEC. 2.Section 38533 of the Health and Safety Code is amended to read:38533.(a)For purposes of this section, the following definitions apply:
(1)Climate reporting organization means a nonprofit climate reporting organization contracted by the state board pursuant to subdivision (d) that both:
(A)Currently operates a climate reporting organization for organizations operating in the United States.
(B)Has experience with climate-related financial risk disclosure by entities operating in California.
(2)Climate-related financial risk means material risk of harm to immediate and long-term financial outcomes due to physical and transition risks, including, but not limited to, risks to corporate operations, provision of goods and services, supply chains, employee health and safety, capital and financial investments, institutional investments, financial standing of loan recipients and borrowers, shareholder value, consumer demand, and financial markets and economic health.
(3)Climate-related financial risk report means a report required by subdivision (b).
(4)Covered entity means a corporation, partnership, limited liability company, or other business entity formed under the laws of the state, the laws of any other state of the United States or the District of Columbia, or under an act of the Congress of the United States with total annual revenues in excess of five hundred million United States dollars ($500,000,000) and that does business in California. Applicability shall be determined based on the business entitys revenue for the prior fiscal year. Covered entity does not include a business entity that is subject to regulation by the Department of Insurance in this state, or that is in the business of insurance in any other state.
(b)(1)(A)On or before January 1, 2026, and biennially thereafter, a covered entity shall prepare a climate-related financial risk report disclosing both of the following:
(i)Its climate-related financial risk, in accordance with the recommended framework and disclosures contained in the Final Report of Recommendations of the Task Force on Climate-related Financial Disclosures (June 2017) published by the Task Force on Climate-related Financial Disclosures, or any successor thereto, or pursuant to an equivalent reporting requirement as described in paragraph (3).
(ii)Its measures adopted to reduce and adapt to climate-related financial risk disclosed pursuant to clause (i).
(B)If a covered entity does not complete a report consistent with all required disclosures pursuant to clause (i) of subparagraph (A), the covered entity shall provide the recommended disclosures to the best of its ability, provide a detailed explanation for any reporting gaps, and describe steps the covered entity will take to prepare complete disclosures.
(2)Climate-related financial risk reports may be consolidated at the parent company level. If a subsidiary of a parent company qualifies as a covered entity pursuant to paragraph (4) of subdivision (a), the subsidiary is not required to prepare a separate climate-related financial risk report.
(3)Notwithstanding paragraph (1), a covered entity satisfies the requirements of paragraph (1) if it prepares a publicly accessible biennial report that includes climate-related financial risk disclosure information by any of the following methods:
(A)Pursuant to a law, regulation, or listing requirement issued by any regulated exchange, national government, or other governmental entity, including a law or regulation issued by the United States government, incorporating disclosure requirements consistent with clause (i) of subparagraph (A) of paragraph (1), including the International Financial Reporting Standards Sustainability Disclosure Standards, as issued by the International Sustainability Standards Board.
(B)Voluntarily using a framework that meets the requirements of clause (i) of subparagraph (A) of paragraph (1) or the International Financial Reporting Standards Sustainability Disclosure Standards, as issued by the International Sustainability Standards Board.
(4)To the extent a climate-related financial risk report contains a description of a covered entitys greenhouse gas emissions or voluntary mitigation of greenhouse gas emissions, the state board may consider the covered entitys claims if those claims are verified by a third-party independent verifier.
(c)(1)On or before January 1, 2026, and biennially thereafter, a covered entity shall make available to the public, on its own internet website, a copy of the report required by this section.
(2)(A)On or before January 1, 2026, and annually thereafter, a covered entity shall pay a fee to the state board for the administration and implementation of this section.
(B)(i)The state board shall set the fee described in subparagraph (A) at an amount adequate to cover the state boards full costs of administrating and implementing this section. The total amount of fees collected shall not exceed the state boards actual and reasonable costs to administer and implement this section.
(ii)The state board may adjust the fee in any year to reflect changes in the California Consumer Price Index during the prior year.
(C)The proceeds of the fees imposed pursuant to this paragraph shall be deposited in the Climate-Related Financial Risk Disclosure Fund, which is hereby created in the State Treasury. Notwithstanding Section 13340 of the Government Code, the money in the fund is continuously appropriated to the state board and shall be expended by the state board for the state boards activities pursuant to this section and to reimburse any outstanding loans made from other funds used to finance the initial costs of the state boards activities pursuant to this section. Money in the fund shall not be expended for any other purpose not described in this subparagraph.
(d)The state board may contract with a climate reporting organization to do any of the following it deems appropriate:
(1)Biennially prepare a public report that contains all of the following elements:
(A)A review of the disclosure of climate-related financial risk contained in a subset of publicly available climate-related financial risk reports by industry.
(B)Analysis of the systemic and sectorwide climate-related financial risks facing the state based on the contents of climate-related financial risk reports, including, but not limited to, potential impacts on economically vulnerable communities.
(C)Identification of inadequate or insufficient reports.
(2)Regularly convene representatives of sectors responsible for reporting climate-related financial risks, state agencies responsible for oversight of reporting sectors, investment managers, academic experts, standard-setting organizations, climate and corporate sustainability organizations, labor union representatives whose members work in impacted sectors, and other stakeholders to offer input on current best practices regarding the disclosure of financial risks resulting from climate change, including, but not limited to, proposals to update the definition of climate-related financial risk, and the framework or disclosure standard of climate-related financial risk reports that meets the requirements of clause (i) of subparagraph (A) of paragraph (1) of subdivision (b).
(3)Monitor federal regulatory actions among agency members of the federal Financial Stability Oversight Council, as well as nonindependent regulators overseen by the White House.
(e)Any contract for services with a reporting organization shall be considered a noninformation technology services contract for procurement purposes.
(f)(1)Section 38580 does not apply to a violation of this section.
(2)The state board shall adopt regulations that authorize it to seek administrative penalties from a covered entity that fails to make the report required by this section publicly available on its internet website or publishes an inadequate or insufficient report. The administrative penalties authorized by this section shall be imposed and recovered by the state board in administrative hearings conducted pursuant to Article 3 (commencing with Section 60065.1) and Article 4 (commencing with Section 60075.1) of Subchapter 1.25 of Chapter 1 of Division 3 of Title 17 of the California Code of Regulations. The administrative penalties imposed on a reporting entity shall not exceed fifty thousand dollars ($50,000) in a reporting year. In imposing penalties for a violation of this section, the state board shall consider all relevant circumstances, including both of the following:
(A)The violators past and present compliance with this section.
(B)Whether the violator took good faith measures to comply with this section and when those measures were taken.
(a)This section shall be known, and may be cited, as the Climate Corporate Data Accountability Act.
(b)For purposes of this section, the following terms have the following definitions:
(1)Emissions reporting organization means a nonprofit emissions reporting organization contracted by the state board pursuant to paragraph (3) of subdivision (c) that both:
(A)Currently operates a greenhouse gas emission reporting organization for organizations operating in the United States.
(B)Has experience with greenhouse gas emissions disclosure by entities operating in California.
(2)Reporting entity means a partnership, corporation, limited liability company, or other business entity formed under the laws of this state, the laws of any other state of the United States or the District of Columbia, or under an act of the Congress of the United States with total annual revenues in excess of one billion dollars ($1,000,000,000) and that does business in California. Applicability shall be determined based on the reporting entitys revenue for the prior fiscal year.
(3)Scope 1 emissions means all direct greenhouse gas emissions that stem from sources that a reporting entity owns or directly controls, regardless of location, including, but not limited to, fuel combustion activities.
(4)Scope 2 emissions means indirect greenhouse gas emissions from consumed electricity, steam, heating, or cooling purchased or acquired by a reporting entity, regardless of location.
(5)Scope 3 emissions means indirect upstream and downstream greenhouse gas emissions, other than scope 2 emissions, from sources that the reporting entity does not own or directly control and may include, but are not limited to, purchased goods and services, business travel, employee commutes, and processing and use of sold products.
(c)(1)On or before July 1, 2025, the state board shall develop and adopt regulations to require a reporting entity to annually disclose all of the reporting entitys scope 1 emissions, scope 2 emissions, and scope 3 emissions, and obtain an assurance engagement performed by an independent third-party assurance provider. Those regulations shall require the reporting entity to make the annual disclosure to either of the following:
(A)The emissions reporting organization, if contracted for services.
(B)The state board.
(2)The state board shall ensure that the regulations adopted pursuant to this subdivision require all of the following:
(A)(i)(I)That a reporting entity, starting in 2026 on or by a date to be determined by the state board, and annually thereafter on or by that date, publicly disclose to the emissions reporting organization, if contracted for services, or the state board, all of the reporting entitys scope 1 emissions and scope 2 emissions for the reporting entitys prior fiscal year.
(II)That a reporting entity, starting in 2027 and annually thereafter, publicly disclose its scope 3 emissions on a schedule specified by the state board as part of the regulations developed pursuant to this subdivision for the prior fiscal year.
(ii)A reporting entity shall, beginning in 2026, measure and report its emissions of greenhouse gases in conformance with the Greenhouse Gas Protocol standards and guidance, including the Greenhouse Gas Protocol Corporate Accounting and Reporting Standard and the Greenhouse Gas Protocol Corporate Value Chain (Scope 3) Accounting and Reporting Standard developed by the World Resources Institute and the World Business Council for Sustainable Development, including guidance for scope 3 emissions calculations that detail acceptable use of both primary and secondary data sources, including the use of industry average data, proxy data, and other generic data in its scope 3 emissions calculations.
(iii)Reports may be consolidated at the parent company level. If a subsidiary of a parent company qualifies as a reporting entity pursuant to paragraph (2) of subdivision (b), the subsidiary is not required to prepare a separate report.
(iv)(I)Starting in 2033, the state board may survey and assess currently available greenhouse gas accounting and reporting standards. At the conclusion of this assessment the state board may adopt a globally recognized alternative accounting and reporting standard if it determines its use would more effectively further the goals of this section. This review process shall include consultation with the stakeholders identified in paragraph (5).
(II)If the state board adopts an alternative accounting and reporting standard, the state board shall develop and adopt new regulations, pursuant to paragraph (1), to ensure full conformance with the new standard and reporting of scope 1 emissions, scope 2 emissions, and scope 3 emissions and other requirements of this section.
(v)During 2029 the state board shall review, and on or before January 1, 2030, the state board shall update as necessary, the public disclosure deadlines established pursuant to clause (i) to evaluate trends in scope 3 emissions reporting and consider changes to the disclosure deadlines to ensure that scope 3 emissions data is disclosed to the emissions reporting organization, if contracted for services, or the state board, as close in time as practicable to the deadline for reporting entities to disclose scope 1 emissions and scope 2 emissions data.
(vi)The reporting timelines shall consider industry stakeholder input and shall take into account the timelines by which reporting entities typically receive scope 1 emissions, scope 2 emissions, and scope 3 emissions data, as well as the capacity for an independent assurance engagement to be performed by a third-party assurance provider.
(B)That a reporting entitys public disclosure maximizes access for consumers, investors, and other stakeholders to comprehensive and detailed greenhouse gas emissions data across scope 1 emissions, scope 2 emissions, and scope 3 emissions, as defined by this section, and is made in a manner that is easily understandable and accessible.
(C)That a reporting entitys public disclosure includes the name of the reporting entity and any fictitious names, trade names, assumed names, and logos used by the reporting entity.
(D)(i)That the emissions reporting is structured in a way that minimizes duplication of effort and allows a reporting entity to submit to the emissions reporting organization, if contracted for services, or the state board, reports prepared to meet other national and international reporting requirements, including any reports required by the federal government, as long as those reports satisfy all of the requirements of this section.
(ii)Reporting entities that are required to report mandatory industrial emissions pursuant to regulations adopted pursuant to Section 38530 may provide that data with the disclosure required pursuant to this section.
(E)That a reporting entitys disclosure takes into account acquisitions, divestments, mergers, and other structural changes that can affect the greenhouse gas emissions reporting, and is disclosed in a manner consistent with the Greenhouse Gas Protocol standards and guidance or an alternative standard, if one is adopted after 2033.
(F)(i)That a reporting entity obtains an assurance engagement, performed by an independent third-party assurance provider, of their public disclosure. The reporting entity shall ensure that a copy of the complete assurance providers report on the greenhouse gas emissions inventory, including the name of the third-party assurance provider, is provided to the emissions reporting organization, if contracted for services, or the state board, as part of or in connection with the reporting entitys public disclosure.
(ii)The assurance engagement for scope 1 emissions and scope 2 emissions shall be performed at a limited assurance level beginning in 2026 and at a reasonable assurance level beginning in 2030.
(iii)During 2026, the state board shall review and evaluate trends in third-party assurance requirements for scope 3 emissions. On or before January 1, 2027, the state board may establish an assurance requirement for third-party assurance engagements of scope 3 emissions. The assurance engagement for scope 3 emissions shall be performed at a limited assurance level beginning in 2030.
(iv)A third-party assurance provider shall have significant experience in measuring, analyzing, reporting, or attesting to the emission of greenhouse gasses and sufficient competence and capabilities necessary to perform engagements in accordance with professional standards and applicable legal and regulatory requirements. The assurance provider shall be able to issue reports that are appropriate under the circumstances and independent with respect to the reporting entity, and any of the reporting entitys affiliates for which it is providing the assurance report. During 2029 the state board shall review and, on or before January 1, 2030, shall update as necessary, the qualifications for third-party assurance providers based on an evaluation of trends in education relating to the emission of greenhouse gases and the qualifications of third-party assurance providers.
(v)The state board shall ensure that the assurance process minimizes the need for reporting entities to engage multiple assurance providers and ensures sufficient assurance provider capacity, as well as timely reporting implementation as required under clause (i) of subparagraph (A).
(G)(i)That a reporting entity shall pay an annual fee to the state board for the administration and implementation of this section.
(ii)The state board shall set the fee established pursuant to clause (i) in an amount sufficient to cover the state boards full costs of administrating and implementing this section. The total amount of fees collected shall not exceed the state boards actual and reasonable costs to administer and implement this section.
(iii)The proceeds of the fees imposed pursuant to clause (i) shall be deposited in the Climate Accountability and Emissions Disclosure Fund, which is hereby created in the State Treasury. Notwithstanding Section 13340 of the Government Code, the money in the fund is continuously appropriated to the state board and shall be expended by the state board for the state boards activities pursuant to this section and to reimburse any outstanding loans made from other funds used to finance the initial costs of the state boards activities pursuant to this section. Moneys in the fund shall not be expended for any purpose not enumerated in this section.
(iv)The state board may adjust the fee in any year to reflect changes in the California Consumer Price Index during the prior year.
(3)The state board may contract with an emissions reporting organization to develop a reporting program to receive and make publicly available disclosures required by this section pursuant to paragraph (1).
(4)The state board may adopt or update any other regulations that it deems necessary and appropriate to implement this section.
(5)In developing the regulations required pursuant to this subdivision, the state board shall consult with all of the following:
(A)The Attorney General.
(B)Other government stakeholders, including, but not limited to, experts in climate science and corporate carbon emissions accounting and reporting.
(C)Investors.
(D)Stakeholders representing consumer and environmental justice interests.
(E)Reporting entities that have demonstrated leadership in full-scope greenhouse gas emissions accounting and public disclosure and greenhouse gas emissions reductions.
(6)This section does not require additional reporting of emissions of greenhouse gases beyond the reporting of scope 1 emissions, scope 2 emissions, and scope 3 emissions required pursuant to the Greenhouse Gas Protocol standards and guidance or an alternative standard, if one is adopted after 2033.
(d)(1)On or before July 1, 2027, the state board shall contract with the University of California, the California State University, a national laboratory, or another equivalent academic institution to prepare a report on the public disclosures made by reporting entities to the emissions reporting organization, if contracted for services, or the state board, pursuant to subdivision (c) and the regulations adopted by the state board pursuant to that subdivision. In preparing the report, consideration shall be given to, at a minimum, greenhouse gas emissions from reporting entities in the context of state greenhouse gas emissions reduction and climate goals. The entity preparing the report shall not require reporting entities to report any information beyond what is required pursuant to subdivision (c) or the regulations adopted by the state board pursuant to that subdivision.
(2)The state board shall ensure the report required by this subdivision is posted publicly by either of the following:
(A)The emissions reporting organization, if contracted for services, to be made publicly available on the digital platform required to be created by the emissions reporting organization pursuant to subdivision (e).
(B)The state board on its public internet website.
(e)(1)(A)The state board, or the emissions reporting organization, if contracted for services, on or before the date determined by the state board pursuant to clause (i) of subparagraph (A) of paragraph (2) of subdivision (c), shall create a digital platform, which shall be accessible to the public, that will feature the emissions data of reporting entities in conformance with the regulations adopted by the state board pursuant to subdivision (c) and the report prepared for the state board pursuant to subdivision (d). The state board, or the emissions reporting organization, if contracted for services, shall make the reporting entities disclosures and the state boards report available on the digital platform no later than 90 days after receipt.
(B)The digital platform shall be capable of featuring individual reporting entity disclosures, and shall allow consumers, investors, and other stakeholders to view reported data elements aggregated in a variety of ways, including multiyear data, in a manner that is easily understandable and accessible to residents of the state. All data sets and customized views shall be available in electronic format for access and use by the public.
(C)Any contract for services with a reporting organization shall be considered a noninformation technology services contract for procurement purposes.
(2)The emissions reporting organization, if contracted for services, or the state board, shall submit, within 30 days of receipt, the report prepared for the state board pursuant to subdivision (d) to the relevant policy committees of the Legislature.
(f)(1)Section 38580 does not apply to a violation of this section.
(2)(A)The state board shall adopt regulations that authorize it to seek administrative penalties for nonfiling, late filing, or other failure to meet the requirements of this section. The administrative penalties authorized by this section shall be imposed and recovered by the state board in administrative hearings conducted pursuant to Article 3 (commencing with Section 60065.1) and Article 4 (commencing with Section 60075.1) of Subchapter 1.25 of Chapter 1 of Division 3 of Title 17 of the California Code of Regulations. The administrative penalties imposed on a reporting entity shall not exceed five hundred thousand dollars ($500,000) in a reporting year. In imposing penalties for a violation of this section, the state board shall consider all relevant circumstances, including both of the following:
(i)The violators past and present compliance with this section.
(ii)Whether the violator took good faith measures to comply with this section and when those measures were taken.
(B) A reporting entity shall not be subject to an administrative penalty under this section for any misstatements with regard to scope 3 emissions disclosures made with a reasonable basis and disclosed in good faith.
(C)Penalties assessed on scope 3 reporting, between 2027 and 2030, shall only occur for nonfiling.
(g)This section applies to the University of California only to the extent that the Regents of the University of California, by resolution, make any of these provisions applicable to the university.
(h) The provisions of this section are severable. If any provision of this section or its application is held invalid, that invalidity shall not affect other provisions or applications that can be given effect without the invalid provision or application.
SEC. 2.Section 38533 of the Health and Safety Code is amended to read:38533.(a)For purposes of this section, the following definitions apply:
(1)Climate reporting organization means a nonprofit climate reporting organization contracted by the state board pursuant to subdivision (d) that both:
(A)Currently operates a climate reporting organization for organizations operating in the United States.
(B)Has experience with climate-related financial risk disclosure by entities operating in California.
(2)Climate-related financial risk means material risk of harm to immediate and long-term financial outcomes due to physical and transition risks, including, but not limited to, risks to corporate operations, provision of goods and services, supply chains, employee health and safety, capital and financial investments, institutional investments, financial standing of loan recipients and borrowers, shareholder value, consumer demand, and financial markets and economic health.
(3)Climate-related financial risk report means a report required by subdivision (b).
(4)Covered entity means a corporation, partnership, limited liability company, or other business entity formed under the laws of the state, the laws of any other state of the United States or the District of Columbia, or under an act of the Congress of the United States with total annual revenues in excess of five hundred million United States dollars ($500,000,000) and that does business in California. Applicability shall be determined based on the business entitys revenue for the prior fiscal year. Covered entity does not include a business entity that is subject to regulation by the Department of Insurance in this state, or that is in the business of insurance in any other state.
(b)(1)(A)On or before January 1, 2026, and biennially thereafter, a covered entity shall prepare a climate-related financial risk report disclosing both of the following:
(i)Its climate-related financial risk, in accordance with the recommended framework and disclosures contained in the Final Report of Recommendations of the Task Force on Climate-related Financial Disclosures (June 2017) published by the Task Force on Climate-related Financial Disclosures, or any successor thereto, or pursuant to an equivalent reporting requirement as described in paragraph (3).
(ii)Its measures adopted to reduce and adapt to climate-related financial risk disclosed pursuant to clause (i).
(B)If a covered entity does not complete a report consistent with all required disclosures pursuant to clause (i) of subparagraph (A), the covered entity shall provide the recommended disclosures to the best of its ability, provide a detailed explanation for any reporting gaps, and describe steps the covered entity will take to prepare complete disclosures.
(2)Climate-related financial risk reports may be consolidated at the parent company level. If a subsidiary of a parent company qualifies as a covered entity pursuant to paragraph (4) of subdivision (a), the subsidiary is not required to prepare a separate climate-related financial risk report.
(3)Notwithstanding paragraph (1), a covered entity satisfies the requirements of paragraph (1) if it prepares a publicly accessible biennial report that includes climate-related financial risk disclosure information by any of the following methods:
(A)Pursuant to a law, regulation, or listing requirement issued by any regulated exchange, national government, or other governmental entity, including a law or regulation issued by the United States government, incorporating disclosure requirements consistent with clause (i) of subparagraph (A) of paragraph (1), including the International Financial Reporting Standards Sustainability Disclosure Standards, as issued by the International Sustainability Standards Board.
(B)Voluntarily using a framework that meets the requirements of clause (i) of subparagraph (A) of paragraph (1) or the International Financial Reporting Standards Sustainability Disclosure Standards, as issued by the International Sustainability Standards Board.
(4)To the extent a climate-related financial risk report contains a description of a covered entitys greenhouse gas emissions or voluntary mitigation of greenhouse gas emissions, the state board may consider the covered entitys claims if those claims are verified by a third-party independent verifier.
(c)(1)On or before January 1, 2026, and biennially thereafter, a covered entity shall make available to the public, on its own internet website, a copy of the report required by this section.
(2)(A)On or before January 1, 2026, and annually thereafter, a covered entity shall pay a fee to the state board for the administration and implementation of this section.
(B)(i)The state board shall set the fee described in subparagraph (A) at an amount adequate to cover the state boards full costs of administrating and implementing this section. The total amount of fees collected shall not exceed the state boards actual and reasonable costs to administer and implement this section.
(ii)The state board may adjust the fee in any year to reflect changes in the California Consumer Price Index during the prior year.
(C)The proceeds of the fees imposed pursuant to this paragraph shall be deposited in the Climate-Related Financial Risk Disclosure Fund, which is hereby created in the State Treasury. Notwithstanding Section 13340 of the Government Code, the money in the fund is continuously appropriated to the state board and shall be expended by the state board for the state boards activities pursuant to this section and to reimburse any outstanding loans made from other funds used to finance the initial costs of the state boards activities pursuant to this section. Money in the fund shall not be expended for any other purpose not described in this subparagraph.
(d)The state board may contract with a climate reporting organization to do any of the following it deems appropriate:
(1)Biennially prepare a public report that contains all of the following elements:
(A)A review of the disclosure of climate-related financial risk contained in a subset of publicly available climate-related financial risk reports by industry.
(B)Analysis of the systemic and sectorwide climate-related financial risks facing the state based on the contents of climate-related financial risk reports, including, but not limited to, potential impacts on economically vulnerable communities.
(C)Identification of inadequate or insufficient reports.
(2)Regularly convene representatives of sectors responsible for reporting climate-related financial risks, state agencies responsible for oversight of reporting sectors, investment managers, academic experts, standard-setting organizations, climate and corporate sustainability organizations, labor union representatives whose members work in impacted sectors, and other stakeholders to offer input on current best practices regarding the disclosure of financial risks resulting from climate change, including, but not limited to, proposals to update the definition of climate-related financial risk, and the framework or disclosure standard of climate-related financial risk reports that meets the requirements of clause (i) of subparagraph (A) of paragraph (1) of subdivision (b).
(3)Monitor federal regulatory actions among agency members of the federal Financial Stability Oversight Council, as well as nonindependent regulators overseen by the White House.
(e)Any contract for services with a reporting organization shall be considered a noninformation technology services contract for procurement purposes.
(e)(f)(1)Section 38580 does not apply to a violation of this section.
(2)The state board shall adopt regulations that authorize it to seek administrative penalties from a covered entity that fails to make the report required by this section publicly available on its internet website or publishes an inadequate or insufficient report. The administrative penalties authorized by this section shall be imposed and recovered by the state board in administrative hearings conducted pursuant to Article 3 (commencing with Section 60065.1) and Article 4 (commencing with Section 60075.1) of Subchapter 1.25 of Chapter 1 of Division 3 of Title 17 of the California Code of Regulations. The administrative penalties imposed on a reporting entity shall not exceed fifty thousand dollars ($50,000) in a reporting year. In imposing penalties for a violation of this section, the state board shall consider all relevant circumstances, including both of the following:
(A)The violators past and present compliance with this section.
(B)Whether the violator took good faith measures to comply with this section and when those measures were taken.
(a)This section shall be known, and may be cited, as the Climate Corporate Data Accountability Act.
(b)For purposes of this section, the following terms have the following definitions:
(1)Emissions reporting organization means a nonprofit emissions reporting organization contracted by the state board pursuant to paragraph (2) (3) of subdivision (c) that both:
(A)Currently operates a greenhouse gas emission reporting organization for organizations operating in the United States.
(B)Has experience with greenhouse gas emissions disclosure by entities operating in California.
(2)Reporting entity means a partnership, corporation, limited liability company, or other business entity formed under the laws of this state, the laws of any other state of the United States or the District of Columbia, or under an act of the Congress of the United States with total annual revenues in excess of one billion dollars ($1,000,000,000) and that does business in California. Applicability shall be determined based on the reporting entitys revenue for the prior fiscal year.
(3)Scope 1 emissions means all direct greenhouse gas emissions that stem from sources that a reporting entity owns or directly controls, regardless of location, including, but not limited to, fuel combustion activities.
(4)Scope 2 emissions means indirect greenhouse gas emissions from consumed electricity, steam, heating, or cooling purchased or acquired by a reporting entity, regardless of location.
(5)Scope 3 emissions means indirect upstream and downstream greenhouse gas emissions, other than scope 2 emissions, from sources that the reporting entity does not own or directly control and may include, but are not limited to, purchased goods and services, business travel, employee commutes, and processing and use of sold products.
(c)(1)On or before January July 1, 2025, the state board shall develop and adopt regulations to require a reporting entity to annually disclose to the emissions reporting organization, all of the reporting entitys scope 1 emissions, scope 2 emissions, and scope 3 emissions, and obtain an assurance engagement performed by an independent third-party assurance provider on all of the reporting entitys scope 1 emissions, scope 2 emissions, and scope 3 emissions. The state board shall ensure that the regulations adopted pursuant to this subdivision require all provider. Those regulations shall require the reporting entity to make the annual disclosure to either of the following:
(A)The emissions reporting organization, if contracted for services.
(B)The state board.
(2)The state board shall ensure that the regulations adopted pursuant to this subdivision require all of the following:
(A)(i)(I)That a reporting entity, starting in 2026 on or by a date to be determined by the state board, and annually thereafter on or by that date, publicly disclose to the emissions reporting organization organization, if contracted for services, or the state board, all of the reporting entitys scope 1 emissions and scope 2 emissions for the reporting entitys prior fiscal year.
(II)That a reporting entity, starting in 2027 and annually thereafter, publicly disclose its scope 3 emissions no later than 180 days after its scope 1 emissions and scope 2 emissions are publicly disclosed to the emissions reporting organization on a schedule specified by the state board as part of the regulations developed pursuant to this subdivision for the prior fiscal year.
(ii)A reporting entity shall, beginning in 2026, measure and report its emissions of greenhouse gases in conformance with the Greenhouse Gas Protocol standards and guidance, including the Greenhouse Gas Protocol Corporate Accounting and Reporting Standard and the Greenhouse Gas Protocol Corporate Value Chain (Scope 3) Accounting and Reporting Standard developed by the World Resources Institute and the World Business Council for Sustainable Development, including guidance for scope 3 emissions calculations that detail acceptable use of both primary and secondary data sources, including the use of industry average data, proxy data, and other generic data in its scope 3 emissions calculations.
(iii)Reports may be consolidated at the parent company level. If a subsidiary of a parent company qualifies as a reporting entity pursuant to paragraph (2) of subdivision (b), the subsidiary is not required to prepare a separate report.
(iii)(iv)(I)Starting in 2033 and every five years thereafter, 2033, the state board may survey and assess currently available greenhouse gas accounting and reporting standards. At the conclusion of this assessment the state board may adopt a globally recognized alternative accounting and reporting standard if it determines its use would more effectively further the goals of this section. This review process shall include consultation with the stakeholders identified in paragraph (4). (5).
(II)If the state board adopts an alternative accounting and reporting standard, the state board shall develop and adopt new regulations, pursuant to paragraph (1), to ensure full conformance with the new standard and reporting of scopes 1, 2, and scope 1 emissions, scope 2 emissions, and scope 3 emissions and other requirements of this section.
(iv)(v)During 2029 the state board shall review, and on or before January 1, 2030, the state board shall update as necessary, the public disclosure deadlines established pursuant to clause (i) to evaluate trends in scope 3 emissions reporting and consider changes to the disclosure deadlines to ensure that scope 3 emissions data is disclosed to the emissions reporting organization organization, if contracted for services, or the state board, as close in time as practicable to the deadline for reporting entities to disclose scope 1 emissions and scope 2 emissions data.
(v)(vi)The reporting timelines shall consider industry stakeholder input and shall take into account the timelines by which reporting entities typically receive scope 1, scope 2, scope 1 emissions, scope 2 emissions, and scope 3 emissions data, as well as the capacity for an independent assurance engagement to be performed by a third-party assurance provider.
(B)That a reporting entitys public disclosure maximizes access for consumers, investors, and other stakeholders to comprehensive and detailed greenhouse gas emissions data across scopes 1, 2, and scope 1 emissions, scope 2 emissions, and scope 3 emissions, as defined by this section, and is made in a manner that is easily understandable and accessible.
(C)That a reporting entitys public disclosure includes the name of the reporting entity and any fictitious names, trade names, assumed names, and logos used by the reporting entity.
(D)(i)That the emissions reporting is structured in a way that minimizes duplication of effort and allows a reporting entity to submit to the emissions reporting organization organization, if contracted for services, or the state board, reports prepared to meet other national and international reporting requirements, including any reports required by the federal government, as long as those reports satisfy all of the requirements of this section.
(ii)Reporting entities that are required to report mandatory industrial emissions pursuant to regulations adopted pursuant to Section 38530 may provide that data with the disclosure required pursuant to this section.
(E)That a reporting entitys disclosure takes into account acquisitions, divestments, mergers, and other structural changes that can affect the greenhouse gas emissions reporting, and is disclosed in a manner consistent with the Greenhouse Gas Protocol standards and guidance or an alternative standard, if one is adopted after 2033.
(F)(i)That a reporting entity obtains an assurance engagement, performed by an independent third-party assurance provider, of their public disclosure. The reporting entity shall ensure that a copy of the complete assurance providers report on the greenhouse gas emissions inventory, including the name of the third-party assurance provider, is provided to the emissions reporting organization organization, if contracted for services, or the state board, as part of or in connection with the reporting entitys public disclosure.
(ii)The assurance engagement for scope 1 emissions and scope 2 emissions shall be performed at a limited assurance level beginning in 2026 and at a reasonable assurance level beginning in 2030.
(iii)During 2026, the state board shall review and evaluate trends in third-party assurance requirements for scope 3 emissions. On or before January 1, 2027, the state board may establish an assurance requirement for third-party assurance engagements of scope 3 emissions. The assurance engagement for scope 3 emissions shall be performed at a limited assurance level beginning in 2030.
(iv)A third-party assurance provider shall have significant experience in measuring, analyzing, reporting, or attesting to the emission of greenhouse gasses and sufficient competence and capabilities necessary to perform engagements in accordance with professional standards and applicable legal and regulatory requirements. The assurance provider shall be able to issue reports that are appropriate under the circumstances and independent with respect to the reporting entity, and any of the reporting entitys affiliates for which it is providing the assurance report. During 2029 the state board shall review and, on or before January 1, 2030, shall update as necessary, the qualifications for third-party assurance providers based on an evaluation of trends in education relating to the emission of greenhouse gases and the qualifications of third-party assurance providers.
(v)The state board shall ensure that the assurance process minimizes the need for reporting entities to engage multiple assurance providers and ensures sufficient assurance provider capacity, as well as timely reporting implementation as required under clause (i) of subparagraph (A).
(G)(i)That a reporting entity, upon filing its disclosure, entity shall pay an annual fee to the state board for the administration and implementation of this section.
(ii)The state board shall set the fee established pursuant to clause (i) in an amount sufficient to cover the state boards full costs of administrating and implementing this section. The total amount of fees collected shall not exceed the state boards actual and reasonable costs to administer and implement this section.
(iii)The proceeds of the fees imposed pursuant to clause (i) shall be deposited in the Climate Accountability and Emissions Disclosure Fund, which is hereby created in the State Treasury. Notwithstanding Section 13340 of the Government Code, the money in the fund is continuously appropriated to the state board and shall be expended by the state board for the state boards activities pursuant to this section and to reimburse any outstanding loans made from other funds used to finance the initial costs of the state boards activities pursuant to this section. Moneys in the fund shall not be expended for any purpose not enumerated in this section.
(iv)The state board may adjust the fee in any year to reflect changes in the California Consumer Price Index during the prior year.
(2)(3)The state board shall may contract with an emissions reporting organization to develop a reporting program to receive and make publicly available disclosures required by this section pursuant to paragraph (1).
(3)(4)The state board may adopt or update any other regulations that it deems necessary and appropriate to implement this section.
(4)(5)In developing the regulations required pursuant to this subdivision, the state board shall consult with all of the following:
(A)The Attorney General.
(B)Other government stakeholders, including, but not limited to, experts in climate science and corporate carbon emissions accounting and reporting.
(C)Investors.
(D)Stakeholders representing consumer and environmental justice interests.
(E)Reporting entities that have demonstrated leadership in full-scope greenhouse gas emissions accounting and public disclosure and greenhouse gas emissions reductions.
(5)(6)This section does not require additional reporting of emissions of greenhouse gases beyond the reporting of scope 1 emissions, scope 2 emissions, and scope 3 emissions required pursuant to the Greenhouse Gas Protocol standards and guidance or an alternative standard, if one is adopted after 2033.
(d)(1)On or before July 1, 2027, the state board shall contract with the University of California, the California State University, a national laboratory, or another equivalent academic institution to prepare a report on the public disclosures made by reporting entities to the emissions reporting organization organization, if contracted for services, or the state board, pursuant to subdivision (c) and the regulations adopted by the state board pursuant to that subdivision. In preparing the report, consideration shall be given to, at a minimum, greenhouse gas emissions from reporting entities in the context of state greenhouse gas emissions reduction and climate goals. The entity preparing the report shall not require reporting entities to report any information beyond what is required pursuant to subdivision (c) or the regulations adopted by the state board pursuant to that subdivision.
(2)The state board shall submit ensure the report required by this subdivision to the is posted publicly by either of the following:
(A)The emissions reporting organization organization, if contracted for services, to be made publicly available on the digital platform required to be created by the emissions reporting organization pursuant to subdivision (e).
(B)The state board on its public internet website.
(e)(1)(A)The state board, or the emissions reporting organization, if contracted for services, on or before the date determined by the state board pursuant to clause (i) of subparagraph (A) of paragraph (1) (2) of subdivision (c), shall create a digital platform, which shall be accessible to the public, that will feature the emissions data of reporting entities in conformance with the regulations adopted by the state board pursuant to subdivision (c) and the report prepared for the state board pursuant to subdivision (d). The state board, or the emissions reporting organization organization, if contracted for services, shall make the reporting entities disclosures and the state boards report available on the digital platform within 30 days of receipt. no later than 90 days after receipt.
(B)The digital platform shall be capable of featuring individual reporting entity disclosures, and shall allow consumers, investors, and other stakeholders to view reported data elements aggregated in a variety of ways, including multiyear data, in a manner that is easily understandable and accessible to residents of the state. All data sets and customized views shall be available in electronic format for access and use by the public.
(C)Any contract for services with a reporting organization shall be considered a noninformation technology services contract for procurement purposes.
(2)The emissions reporting organization organization, if contracted for services, or the state board, shall submit, within 30 days of receipt, the report prepared for the state board pursuant to subdivision (d) to the relevant policy committees of the Legislature.
(f)(1)Section 38580 does not apply to a violation of this section.
(2)(A)The state board shall adopt regulations that authorize it to seek administrative penalties for nonfiling, late filing, or other failure to meet the requirements of this section. The administrative penalties authorized by this section shall be imposed and recovered by the state board in administrative hearings conducted pursuant to Article 3 (commencing with Section 60065.1) and Article 4 (commencing with Section 60075.1) of Subchapter 1.25 of Chapter 1 of Division 3 of Title 17 of the California Code of Regulations. The administrative penalties imposed on a reporting entity shall not exceed five hundred thousand dollars ($500,000) in a reporting year. In imposing penalties for a violation of this section, the state board shall consider all relevant circumstances, including both of the following:
(i)The violators past and present compliance with this section.
(ii)Whether the violator took good faith measures to comply with this section and when those measures were taken.
(B) A reporting entity shall not be subject to an administrative penalty under this section for any misstatements with regard to scope 3 emissions disclosures made with a reasonable basis and disclosed in good faith.
(C)Penalties assessed on scope 3 reporting, between 2027 and 2030, shall only occur for nonfiling.
(g)This section applies to the University of California only to the extent that the Regents of the University of California, by resolution, make any of these provisions applicable to the university.
(h) The provisions of this section are severable. If any provision of this section or its application is held invalid, that invalidity shall not affect other provisions or applications that can be given effect without the invalid provision or application.
SEC. 2.Section 38533 of the Health and Safety Code is amended to read:38533.(a)For purposes of this section, the following definitions apply:
(1)Climate reporting organization means a nonprofit climate reporting organization contracted by the state board pursuant to paragraph (2) of subdivision (b) subdivision (d) that both:
(A)Currently operates a climate reporting organization for organizations operating in the United States.
(B)Has experience with climate-related financial risk disclosure by entities operating in California.
(2)Climate-related financial risk means material risk of harm to immediate and long-term financial outcomes due to physical and transition risks, including, but not limited to, risks to corporate operations, provision of goods and services, supply chains, employee health and safety, capital and financial investments, institutional investments, financial standing of loan recipients and borrowers, shareholder value, consumer demand, and financial markets and economic health.
(3)Climate-related financial risk report means a report required by subdivision (b).
(4)Covered entity means a corporation, partnership, limited liability company, or other business entity formed under the laws of the state, the laws of any other state of the United States or the District of Columbia, or under an act of the Congress of the United States with total annual revenues in excess of five hundred million United States dollars ($500,000,000) and that does business in California. Applicability shall be determined based on the business entitys revenue for the prior fiscal year. Covered entity does not include a business entity that is subject to regulation by the Department of Insurance in this state, or that is in the business of insurance in any other state.
(b)(1)(A)On or before January 1, 2026, and biennially thereafter, a covered entity shall prepare a climate-related financial risk report disclosing both of the following:
(i)Its climate-related financial risk, in accordance with the recommended framework and disclosures contained in the Final Report of Recommendations of the Task Force on Climate-related Financial Disclosures (June 2017) published by the Task Force on Climate-related Financial Disclosures, or any successor thereto, or pursuant to an equivalent reporting requirement as described in paragraph (4). (3).
(ii)Its measures adopted to reduce and adapt to climate-related financial risk disclosed pursuant to clause (i).
(B)If a covered entity does not complete a report consistent with all required disclosures pursuant to clause (i) of subparagraph (A), the covered entity shall provide the recommended disclosures to the best of its ability, provide a detailed explanation for any reporting gaps, and describe steps the covered entity will take to prepare complete disclosures.
(2)Climate-related financial risk reports may be consolidated at the parent company level. If a subsidiary of a parent company qualifies as a covered entity pursuant to paragraph (4) of subdivision (a), the subsidiary is not required to prepare a separate climate-related financial risk report.
(3)The state board shall contract with a climate reporting organization to prepare a biennial public report on the climate-related financial risk disclosures required by this section.(4)(3)Notwithstanding paragraph (1), a covered entity satisfies the requirements of paragraph (1) if it prepares a publicly accessible biennial report that includes climate-related financial risk disclosure information by any of the following methods:
(A)Pursuant to a law, regulation, or listing requirement issued by any regulated exchange, national government, or other governmental entity, including a law or regulation issued by the United States government, incorporating disclosure requirements consistent with clause (i) of subparagraph (A) of paragraph (1), including the International Financial Reporting Standards Sustainability Disclosure Standards, as issued by the International Sustainability Standards Board.
(B)Voluntarily using a framework that meets the requirements of clause (i) of subparagraph (A) of paragraph (1) or the International Financial Reporting Standards Sustainability Disclosure Standards, as issued by the International Sustainability Standards Board.
(5)(4)To the extent a climate-related financial risk report contains a description of a covered entitys greenhouse gases gas emissions or voluntary mitigation of greenhouse gases, gas emissions, the state board may consider the covered entitys claims if those claims are verified by a third-party independent verifier.
(c)(1)On or before January 1, 2026, and biennially thereafter, a covered entity shall make available to the public, on its own internet website, a copy of the report required by this section.
(2)(A)On or before January 1, 2026, and annually thereafter, a covered entity shall pay a fee, upon filing its disclosure, fee to the state board for the administration and implementation of this section.
(B)(i)The state board shall set the fee described in subparagraph (A) at an amount adequate to cover the state boards full costs of administrating and implementing this section. The total amount of fees collected shall not exceed the state boards actual and reasonable costs to administer and implement this section.
(ii)The state board may adjust the fee in any year to reflect changes in the California Consumer Price Index during the prior year.
(C)The proceeds of the fees imposed pursuant to this paragraph shall be deposited in the Climate-Related Financial Risk Disclosure Fund, which is hereby created in the State Treasury. Notwithstanding Section 13340 of the Government Code, the money in the fund is continuously appropriated to the state board and shall be expended by the state board for the state boards activities pursuant to this section and to reimburse any outstanding loans made from other funds used to finance the initial costs of the state boards activities pursuant to this section. Money in the fund shall not be expended for any other purpose not described in this subparagraph.
(d)The state board may contract with a climate reporting organization shall be contracted to do all any of the following: following it deems appropriate:
(1)Biennially prepare a public report that contains all of the following elements:
(A)A review of the disclosure of climate-related financial risk contained in a subset of publicly available climate-related financial risk reports by industry.
(B)Analysis of the systemic and sectorwide climate-related financial risks facing the state based on the contents of climate-related financial risk reports, including, but not limited to, potential impacts on economically vulnerable communities.
(C)Identification of inadequate or insufficient reports.
(2)Regularly convene representatives of sectors responsible for reporting climate-related financial risks, state agencies responsible for oversight of reporting sectors, investment managers, academic experts, standard-setting organizations, climate and corporate sustainability organizations, labor union representatives whose members work in impacted sectors, and other stakeholders to offer input on current best practices regarding the disclosure of financial risks resulting from climate change, including, but not limited to, proposals to update the definition of climate-related financial risk, and the framework or disclosure standard of climate-related financial risk reports that meets the requirements of clause (i) of subparagraph (A) of paragraph (1) of subdivision (b).
(3)Monitor federal regulatory actions among agency members of the federal Financial Stability Oversight Council, as well as nonindependent regulators overseen by the White House.
(e)(1)Section 38580 does not apply to a violation of this section.
(2)The state board shall adopt regulations that authorize it to seek administrative penalties from a covered entity that fails to make the report required by this section publicly available on its internet website or publishes an inadequate or insufficient report. The administrative penalties authorized by this section shall be imposed and recovered by the state board in administrative hearings conducted pursuant to Article 3 (commencing with Section 60065.1) and Article 4 (commencing with Section 60075.1) of Subchapter 1.25 of Chapter 1 of Division 3 of Title 17 of the California Code of Regulations. The administrative penalties imposed on a reporting entity shall not exceed fifty thousand dollars ($50,000) in a reporting year. In imposing penalties for a violation of this section, the state board shall consider all relevant circumstances, including both of the following:
(A)The violators past and present compliance with this section.
(B)Whether the violator took good faith measures to comply with this section and when those measures were taken.
SECTION 1.It is the intent of the Legislature to enact statutory changes relating to the Budget Act of 2023.It is the intent of the Legislature to enact statutory changes relating to the Budget Act of 2023.
|
Date
|
Status
|
|---|---|
| Sep 27, 2024 | Chaptered by Secretary of State. Chapter 766, Statutes of 2024. |
| Sep 27, 2024 | Approved by the Governor. |
| Sep 12, 2024 | Enrolled and presented to the Governor at 3 p.m. |
| Aug 31, 2024 | Assembly amendments concurred in. (Ayes 33. Noes 4. Page 5787.) Ordered to engrossing and enrolling. |
| Aug 31, 2024 | In Senate. Concurrence in Assembly amendments pending. |
| Aug 31, 2024 | Read third time. Passed. (Ayes 77. Noes 0. Page 7045.) Ordered to the Senate. |
| Aug 30, 2024 | Read second time. Ordered to third reading. |
| Aug 29, 2024 | From committee: Do pass. (Ayes 12. Noes 0.) (August 29). |
| Aug 29, 2024 | Joint Rule 62(a) suspended. |
| Aug 23, 2024 | Read third time and amended. |
| Aug 23, 2024 | Re-referred to Com. on NAT. RES. pursuant to Assembly Rule 77.2. |
| Aug 23, 2024 | Ordered to third reading. |
| Aug 19, 2024 | Read second time. Ordered to third reading. |
| Aug 15, 2024 | Withdrawn from committee. |
| Aug 15, 2024 | Ordered to second reading. |
| Aug 15, 2024 | Assembly Rule 96 suspended. |
| Aug 13, 2024 | From committee with author's amendments. Read second time and amended. Re-referred to Com. on BUDGET. |
| Mar 30, 2023 | Referred to Com. on BUDGET. |
| Mar 27, 2023 | In Assembly. Read first time. Held at Desk. |
| Mar 27, 2023 | Read third time. Passed. (Ayes 29. Noes 8. Page 525.) Ordered to the Assembly. |
| Mar 20, 2023 | Read second time. Ordered to third reading. |
| Mar 16, 2023 | Withdrawn from committee. (Ayes 28. Noes 8. Page 357.) |
| Mar 16, 2023 | Ordered to second reading. |
| Jan 25, 2023 | Referred to Com. on B. & F.R. |
| Jan 19, 2023 | From printer. May be acted upon on or after February 18. |
| Jan 18, 2023 | Introduced. Read first time. To Com. on RLS. for assignment. To print. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Aug 31, 2024 | SB 219 Wiener Senate Third Reading By Hart | Assembly Floor |
Passed |
|
| Aug 31, 2024 | Unfinished Business SB219 Wiener et al. Concurrence | Senate Floor |
Passed |
|
| Aug 29, 2024 | Do pass. | Assembly Standing Committee on Natural Resources |
Passed |
|
| Mar 27, 2023 | Senate 3rd Reading SB219 B. & F.R. (Skinner) | Senate Floor |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| 350 Bay Area Action | ** Support | |
| 350 Sacramento | ** Support | |
| Active San Gabriel Valley | ** Support | |
| Amalgamated Bank | ** Support | |
| Americans for Financial Reform | ** Support | |
| Audubon California | ** Support | |
| Ban SUP | ** Support | |
| CA Coalition for Clean Air | ** Support | |
| California Environmental Voters | ** Support | |
| Californians Against Waste | ** Support | |
| CALPIRG, California Public Interest Research Group | ** Support | |
| Carbon Accountable | ** Support | |
| Center For Biological Diversity | ** Support | |
| Center for Community Action & Environmental Justice | ** Support | |
| Central Valley Air Quality Coalition | ** Support | |
| Ceres, Inc. | ** Support | |
| cleanearth4kids.org | ** Support | |
| Climate Action California | ** Support | |
| Climate Equity Policy Center | ** Support | |
| Climate Hawks Vote | ** Support | |
| Climate Reality Project: San Fernando Valley Chapter | ** Support | |
| Community Water Center | ** Support | |
| Courage California | ** Support | |
| Dayenu Circle of Congregation Shir Ami, Castro Valley | ** Support | |
| Dayenu: A Jewish Call to Climate Action | ** Support | |
| Earthjustice | ** Support | |
| Environment California | ** Support | |
| Environmental Defense Fund | ** Support | |
| Fossil Free California | ** Support | |
| Friends Committee On Legislation Of California | ** Support | |
| Friends of the Earth U.S. | ** Support | |
| Greenlining Institute; The | ** Support | |
| Habitat Recovery Project | ** Support | |
| Hammond Climate Solutions Foundation | ** Support | |
| Hangoutdogood | ** Support | |
| Indivisible Ca Statestrong | ** Support | |
| Institute for Agriculture and Trade Policy | ** Support | |
| jobs to move america | ** Support | |
| Lutheran Office Of Public Policy - California | ** Support | |
| Natural Resources Defense Council | ** Support | |
| NextGen California | ** Support | |
| Ocean Conservancy | ** Support | |
| Pacific Environment | ** Support | |
| Planning And Conservation League | ** Support | |
| Public Citizen | ** Support | |
| Rise Economy | ** Support | |
| Rising Sun Center for Opportunity | ** Support | |
| Sacramento Area Congregations Together | ** Support | |
| San Francisco Bay Physicians for Social Responsibility | ** Support | |
| Sierra Club California | ** Support | |
| Sunflower Alliance | ** Support | |
| The Climate Center | ** Support | |
| Third ACT | ** Support | |
| Third Act Bay Area | ** Support | |
| Third Act Sacramento | ** Support | |
| Third ACT SoCal | ** Support | |
| Transformative Wealth Management LLC | ** Support | |
| Union Of Concerned Scientists | ** Support | |
| Voices for Progress | ** Support | |
| Vote Solar | ** Support | |
| 350 Conejo / San Fernando Valley | ** Support |
SENATE RULES COMMITTEE Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | SB 219 |
UNFINISHED BUSINESS
Bill No: SB 219
Author: Wiener (D) and Stern (D)
Amended: 8/23/24
Vote: 21
PRIOR VOTES NOT RELEVANT
ASSEMBLY FLOOR: 48-0, 8/31/24 – Roll call vote not available
SUBJECT: Greenhouse gases: climate corporate accountability: climate-related financial risk
SOURCE: Author
DIGEST:
This bill delays the requirement that the California Air Resources Board (CARB) adopt regulations implementing SB 253 (Wiener, Chapter 382, Statutes of 2023) until July 1, 2025; allows for consolidation of reports at the parent company level; requires that the reporting entity publicly disclose its Scope 3 emissions on a schedule specified by CARB, rather than no later than 180 days after its Scope 1 emissions and Scope 2 emissions are publicly disclosed; and makes other changes to the laws created by SB 253 and SB 261 (Stern, Chapter 383, Statutes of 2023).
Assembly Amendments
deleted the contents and created a new bill.
ANALYSIS:
Existing law:
- Pursuant to California Global Warming Solutions Act of 2006 [AB 32 (Núñez), Chapter 488, Statutes of 2006] (Health & Safety (HSC) Code §38500 et seq.):
- Requires CARB to adopt a statewide GHG emissions limit equivalent to 1990 levels by 2020, and requires the reduction of GHGs to 40% below 1990 levels by 2030 and to 85% below 1990 levels by 2045; and
- Requires the monitoring and annual reporting of GHG emissions from GHG emission sources beginning with the sources or categories of sources that contribute the most to statewide emissions, and dictates that for the cap-and-trade program established pursuant to AB 32, entities that voluntarily participated in the California Climate Action Registry prior to December 31, 2006, and had developed a GHG emission reporting program, would not be required to significantly alter their reporting or verification program except as necessary for compliance.
- Pursuant to the Climate Corporate Data Accountability Act (HSC §38532):
- Requires CARB, on or before January 1, 2025, to develop and adopt regulations requiring specified partnerships, corporations, limited liability companies, and other business entities with total annual revenues in excess of $1 billion and that do business in California, defined as “reporting entities,” to publicly disclose to the emissions reporting organization, as defined, and obtain an assurance engagement on, starting in 2026 on a date to be determined by CARB, and annually thereafter, their Scope 1 and Scope 2 greenhouse gas emissions, as defined, and, starting in 2027 and annually thereafter, their Scope 3 GHG emissions, as defined, from the reporting entity’s prior fiscal year, as provided.
- Requires CARB to review during 2029, and update as necessary on or before January 1, 2030, these deadlines to evaluate trends in Scope 3 emissions reporting and to consider changes to the deadlines, as provided.
- Authorizes CARB, starting in 2033 and every five years thereafter, to assess the global GHG accounting and reporting standards and to adopt an alternative standard if it determines that using the alternative standard would more effectively further the goals of the law.
This bill:
- Amends the provisions of SB 253 (Wiener, Chapter 382, Statutes of 2023) to:
- Extend the deadline by six months, from January 1, 2025, to July 1, 2025, for CARB to develop and adopt regulations to require a reporting entity to annually disclose all of the reporting entity’s Scope 1 emissions, Scope 2 emissions, and Scope 3 emissions, and obtain an assurance engagement performed by an independent third-party assurance provider;
- Allow reports to be consolidated at the parent company level. Provides that if a subsidiary of a parent company qualifies as a reporting entity, the subsidiary is not required to prepare a separate report;
- Gives CARB the authority to develop a schedule for Scope 3 emissions to be reported, rather than 180 days after the Scope 1 emissions and Scope 2 emissions are disclosed;
- Provide for either an emissions reporting organization, if contracted for services, or CARB to manage several elements of the program and make conforming changes;
- Extends by 60 days (from 30 days to 90 days) when CARB or the emissions reporting organization is required to make the reporting entities’ disclosures and CARB’s report available on the digital platform; and
- Make other technical and clarifying changes.
- Amends the provisions of SB 261 (Stern, Chapter 383, Statutes of 2023) to:
- Makes it optional for CARB to contract with a climate reporting organization; and
- Make other technical and clarifying changes.
Background
- Scope 1, 2, and 3 emissions. The “scope” framework was introduced in 2001 by the World Resources Institute (WRI) and World Business Council for Sustainable Development as part of their Greenhouse Gas Protocol Corporate Accounting and Reporting Standard. The goal was to create a universal method for companies to measure and report the emissions associated with their business. The three scopes allow companies to differentiate between the emissions they emit directly into the air, which they have the most control over, and the emissions they contribute to indirectly.
Scope 1 covers direct emissions from owned or controlled sources, such as fuel combustion, company vehicles, or fugitive emissions. Scope 2 covers indirect emissions from the generation of purchased electricity, steam, heating and cooling consumed by the reporting company. Scope 3 includes all other indirect emissions that occur in a company’s value chain. Recent research from CDP (formerly the Carbon Disclosure Project) found that among full-scope (i.e. 1, 2, and 3) reports, scope 3 supply chain emissions are on average 11.4 times higher than combined scope 1 and 2 emissions.
Scope 3 emissions are divided into fifteen categories: Purchased goods and services; capital goods; fuel-and energy-related activities; upstream transportation and distribution; waste generated in operations; business travel; employee commuting; upstream leased assets; downstream transportation and distribution; processing of sold products; end-of-life treatment of sold products; downstream leased assets; franchises; and investments.
Comments
- Purpose of Bill. According to the author, “California, like the rest of the world, is already deeply impacted by climate change, with worsening droughts, floods, and the unforgettable devastation brought on by an influx of massive wildfires – the top five largest wildfires in the state's history have all occurred in 2018 or later. We no longer have the time to rely on massive corporations to voluntarily report their emissions, and cannot afford any possibility that the emissions we are being told about have been altered or manipulated to ensure a positive public-facing appearance for a particular company. Material and financial risks associated with climate change additionally have the potential to destabilize capital markets and lead to serious negative consequences for financial institutions and the broader economy. To address these challenges, the Legislature passed SB 253 and 261 in 2023.
“Senate Bill 219, joint authored by Senators Wiener and Stern, makes a number of technical amendments to SB 253—the Climate Corporate Data Accountability Act (Wiener, 2023) and SB 261— The Climate-Related Financial Risk Act (Stern, 2023). It also extends The California Air Resources Board (CARB)’s window to complete a rule-making process by six months, while leaving intact the requirement for disclosures to begin in 2026. - Deadlines. SB 219 proposes a six-month deadline extension for CARB to promulgate regulations to require a reporting entity to annually disclose its GHG emissions.
With an appropriation from the Legislature last year, CARB is positioned to hire staff in fall/winter 2024 and plans to begin informal workshops with stakeholders on the draft regulations as soon as feasible thereafter, likely early to mid-2025. CARB feels a more realistic timeline for implementation would include a two-year delay due to the public comment timelines in the Administrative Procedures Act, under which regulations are adopted, and the Bagley-Keene Open Meeting Act, to which CARB is subject.
Supporters of SB 219 argue that a two-year delay would cause both uncertainty and increased burden for businesses. Further, advocates of the bill point to other state agencies promulgating more complex regulations in less time than CARB is suggesting is needed for the SB 253 regulations. - Transparency guides action. In recent years, many companies have made or increased their commitments to climate action. The Climate Pledge, which calls for companies to commit to net zero carbon emissions by 2040, boasts 510 signatories as of August 2024. This is up nearly tenfold from 53 signatories when the original version of the Climate Corporate Data Accountability Act (SB 260, Wiener, 2021) was first introduced.
Emission-reducing actions like shifting to cleaner power or greening supply chains—whether they are initiated by activists, board members, or investors—depends on transparency. Without an accurate accounting of a business’s real emissions, it is nigh impossible to target meaningful climate action. Scope 1, scope 2, and scope 3 emissions are all required for this transparency. Even existing voluntary reporting frameworks like CDP are neither necessarily public nor independently audited. Reducing scope 1 and 2 emissions by outsourcing polluting processes does not lead to a real, global reduction of GHG emissions. This underscores the need for scope 3 reporting to capture the climate impacts of a business’s full supply chain and the importance of that data for targeting meaningful climate action.
FISCAL EFFECT: Appropriation: No Fiscal Com.: Yes Local: No
SUPPORT: (Verified 8/29/24)
350 Bay Area Action
350 Conejo / San Fernando Valley
350 Sacramento
Active San Gabriel Valley
Amalgamated Bank
Americans for Financial Reform
Audubon California
Ban Sup
CA Coalition for Clean Air
California Environmental Voters
Californians Against Waste
Calpirg, California Public Interest Research Group
Carbon Accountable
Center for Biological Diversity
Center for Community Action & Environmental Justice
Central Valley Air Quality Coalition
Ceres, INC.
Cleanearth4kids.org
Climate Action California
Climate Equity Policy Center
Climate Hawks Vote
Climate Reality Project San Fernando Valley Chapter
Community Water Center
Courage California
Dayenu Circle of Congregation Shir Ami, Castro Valley
Dayenu: a Jewish Call to Climate Action
Earthjustice
Environment California
Environmental Defense Fund
Fossil Free California
Friends Committee on Legislation of California
Friends of The Earth U.s.
Greenlining Institute; the
Habitat Recovery Project
Hammond Climate Solutions Foundation
Hangoutdogood
Indivisible CA Statestrong
Institute for Agriculture and Trade Policy
Jobs to Move America
Lutheran Office of Public Policy - California
Natural Resources Defense Council
Nextgen California
Ocean Conservancy
Pacific Environment
Planning and Conservation League
Public Citizen
Rise Economy
Rising Sun Center for Opportunity
Sacramento Area Congregations Together
San Francisco Bay Physicians for Social Responsibility
Sierra Club California
Sunflower Alliance
The Climate Center
Third ACT
Third ACT Bay Area
Third ACT Sacramento
Third ACT Socal
Transformative Wealth Management LLC
Union of Concerned Scientists
Voices for Progress
Vote Solar
OPPOSITION: (Verified 8/29/24)
None received
Prepared by: Eric Walters / E.Q. / (916) 651-4108
8/31/24 17:53:52
**** END ****
SENATE THIRD READING
STR Bill Id:SB 219
Author:(Wiener and Stern)
As Amended Ver:August 23, 2024
Majority vote
SUMMARY
Delays the requirement that the State Air Resources Board (ARB) adopt regulations until July 1, 2025; requires that the regulations adopted by ARB to require, among other things, a reporting entity to make the annual disclosure to either the greenhouse gas emissions (GHG) reporting organization or ARB; and, requires that the reporting entity publicly disclose its Scope 3 emissions on a schedule specified by ARB, rather than no later than 180 days after its Scope 1 emissions and Scope 2 emissions are publicly disclosed.
Major Provisions
- Extends the deadline by six months, from January 1, 2025, to July 1, 2025, for ARB to develop and adopt regulations to require a reporting entity to annually disclose all of the reporting entity's Scope 1 emissions, Scope 2 emissions, and Scope 3 emissions, and obtain an assurance engagement performed by an independent third-party assurance provider.
- Requires those regulations to require the reporting entity to make the annual disclosure to either the emissions reporting organization, if contracted for services, or ARB.
- Revise the reporting schedule for a reporting entity, starting in 2027 and annually thereafter, to publicly disclose its Scope 3 emissions on a schedule specified by ARB as part of the regulations developed for the prior fiscal year.
- Allows reports to be consolidated at the parent company level. Provides that if a subsidiary of a parent company qualifies as a reporting entity, the subsidiary is not required to prepare a separate report
- Deletes the suggestion for ARB to assess currently available GHG accounting and reporting standards every five years.
- Requires ARB to ensure the report done with an academic institution on the public disclosures made by reporting entities to the emissions reporting is posted publicly by either the emissions reporting organization, if contracted for services, to be made publicly available on the digital platform required to be created by the emissions reporting organization, or ARB on its public internet website.
- Extends by 60-days, from 30-days to 90-days, when ARB or the emissions reporting organization is required to make the reporting entities' disclosures and ARB's report available on the digital platform.
- Deletes the requirement for ARB to contract with a climate reporting organization to prepare a biennial public report on the climate-related financial risk disclosures.
COMMENTS
SB 253 (Wiener), Chapter 382, Statutes of 2023, requires any partnership, corporation, limited liability company, or other U.S. business entity with total annual revenues greater than $1 billion and that does business in California to publicly report their annual GHG emissions, as specified by the ARB.
SB 253 requires specified companies to use the Greenhouse Gas Protocol Corporate Accounting and Reporting Standard and the Greenhouse Gas Protocol Corporate Value Chain (Scope 3) Accounting and Reporting Standard to detail its Scope 3 emissions calculations. The emissions disclosures are required to be independently verified by an outside auditor, and requires businesses to pay an annual fee of up to $1,000 to cover state administrative costs.
SB 261 (Stern), Chapter 383, Statutes of 2023, requires companies that do business in California and have gross revenues exceeding $500 million annually, excluding insurance companies, to report on their climate-related financial risk, and requires the ARB to contract with a qualified climate reporting organization to review and publish an analysis of those reports, as specified.
SB 219 proposes a six month deadline extension for ARB to promulgate regulations to require a reporting entity to annually disclose its GHG emissions, among other technical changes to both GHG disclosure laws.
According to the Author
California, like the rest of the world, is already deeply impacted by climate change, with worsening droughts, floods, and the unforgettable devastation brought on by an influx of massive wildfires – the top five largest wildfires in the state's history have all occurred in 2018 or later. We no longer have the time to rely on massive corporations to voluntarily report their emissions, and cannot afford any possibility that the emissions we are being told about have been altered or manipulated to ensure a positive public-facing appearance for a particular company. Material and financial risks associated with climate change additionally have the potential to destabilize capital markets and lead to serious negative consequences for financial institutions and the broader economy. To address these challenges, the Legislature passed SB 253 and 261 in 2023.
Senate Bill 219, joint authored by Senators Wiener and Stern, makes a number of technical amendments to SB 253—the Climate Corporate Data Accountability Act (Wiener, 2023) and SB 261— The Climate-Related Financial Risk Act (Stern, 2023). It also extends The California Air Resources Board (CARB)'s window to complete a rule-making process by six months, while leaving intact the requirement for disclosures to begin in 2026.
Arguments in Support
A coalition of environmental organizations, including California Environmental Voters and Ceres, Inc., write in support that SB 219 makes common-sense technical amendments while preserving the foundational GHG emissions and climate risk disclosure requirements, including the requirement for first reporting in 2026, thereby ensuring the people of California benefit from these critical climate transparency laws without delay.
Arguments in Opposition
None on file.
FISCAL COMMENTS
Unknown.
VOTES
SENATE FLOOR: 29-8-3
YES: Allen, Alvarado-Gil, Archuleta, Atkins, Becker, Blakespear, Bradford, Caballero, Cortese, Dodd, Durazo, Eggman, Glazer, Gonzalez, Hurtado, Laird, Limón, McGuire, Menjivar, Min, Newman, Padilla, Portantino, Roth, Skinner, Smallwood-Cuevas, Umberg, Wahab, Wiener
NO: Dahle, Grove, Jones, Nguyen, Niello, Ochoa Bogh, Seyarto, Wilk
ABS, ABST OR NV: Ashby, Rubio, Stern
ASM NATURAL RESOURCES: 12-0-0
YES: Bryan, Flora, Bauer-Kahan, Connolly, Friedman, Hoover, Kalra, Mathis, Muratsuchi, Pellerin, Wicks, Wood
UPDATED
VERSION: August 23, 2024
CONSULTANT: Paige Brokaw / NAT. RES. / (916) 319-2092 FN: 0004985
Date of Hearing: August 29, 2024
ASSEMBLY COMMITTEE ON NATURAL RESOURCES
Isaac G. Bryan, Chair
SBPCA Bill Id:SB 219
Author:(Wiener and Stern) – As Amended Ver:August 13, 2024
SENATE VOTE: 29-8
SUBJECT: Greenhouse gases: climate corporate accountability: climate-related financial risk.
SUMMARY: Delays the requirement that the State Air Resources Board (ARB) adopt regulations until July 1, 2025; requires that the regulations adopted by ARB to require, among other things, a reporting entity to make the annual disclosure to either the greenhouse gas emissions (GHG) reporting organization or ARB; and, requires that the reporting entity publicly disclose its Scope 3 emissions on a schedule specified by ARB, rather than no later than 180 days after its Scope 1 emissions and Scope 2 emissions are publicly disclosed.
EXISTING LAW:
- Pursuant to California Global Warming Solutions Act of 2006 [AB 32 (Núñez), Chapter 488, Statutes of 2006] (Health & Safety (HSC) Code 38500 et seq.):
- Requires ARB to adopt a statewide GHG emissions limit equivalent to 1990 levels by 2020, and requires the reduction of GHGs to 40% below 1990 levels by 2030 and to 85% below 1990 levels by 2045.
- Authorizes ARB to adopt a regulation that establishes a system of market-based declining annual aggregate emission limits for sources or categories of sources that emit GHG emissions, applicable until December 31, 2030. Under this authority, ARB adopted a cap and trade regulation that applies to large industrial facilities and electricity generators emitting more than 25,000 metric tons of carbon dioxide equivalent per year, as well as distributors of fuels, including gasoline, diesel, and natural gas.
- Requires the monitoring and annual reporting of GHG emissions from GHG emission sources beginning with the sources or categories of sources that contribute the most to statewide emissions, and dictates that for the cap-and-trade program established pursuant to AB 32, entities that voluntarily participated in the California Climate Action Registry prior to December 31, 2006, and had developed a GHG emission reporting program, would not be required to significantly alter their reporting or verification program except as necessary for compliance.
- Pursuant to the Climate Corporate Data Accountability Act (HSC 38532):
- Requires ARB, on or before January 1, 2025, to develop and adopt regulations requiring specified partnerships, corporations, limited liability companies, and other business entities with total annual revenues in excess of $1 billion and that do business in California, defined as “reporting entities,” to publicly disclose to the emissions reporting organization, as defined, and obtain an assurance engagement on, starting in 2026 on a date to be determined by ARB, and annually thereafter, their Scope 1 and Scope 2 greenhouse gas emissions, as defined, and, starting in 2027 and annually thereafter, their Scope 3 GHG emissions, as defined, from the reporting entity’s prior fiscal year, as provided.
- Requires ARB to review during 2029, and update as necessary on or before January 1, 2030, these deadlines to evaluate trends in Scope 3 emissions reporting and to consider changes to the deadlines, as provided.
- Authorizes ARB, starting in 2033 and every five years thereafter, to assess the global GHG accounting and reporting standards and to adopt an alternative standard if it determines that using the alternative standard would more effectively further the goals of the law.
THIS BILL:
- Extends the deadline by six months, from January 1, 2025, to July 1, 2025, for ARB to develop and adopt regulations to require a reporting entity to annually disclose all of the reporting entity’s Scope 1 emissions, Scope 2 emissions, and Scope 3 emissions, and obtain an assurance engagement performed by an independent third-party assurance provider.
- Requires those regulations to require the reporting entity to make the annual disclosure to either the emissions reporting organization, if contracted for services, or ARB.
- Revise the reporting schedule for a reporting entity, starting in 2027 and annually thereafter, to publicly disclose its Scope 3 emissions on a schedule specified by ARB as part of the regulations developed for the prior fiscal year.
- Allows reports to be consolidated at the parent company level. Provides that if a subsidiary of a parent company qualifies as a reporting entity, the subsidiary is not required to prepare a separate report
- Deletes the suggestion for ARB to assess currently available GHG accounting and reporting standards every five years.
- Requires ARB to ensure the report done with an academic institution on the public disclosures made by reporting entities to the emissions reporting is posted publicly by either the emissions reporting organization, if contracted for services, to be made publicly available on the digital platform required to be created by the emissions reporting organization, or ARB on its public internet website.
- Extends by 60-days, from 30-days to 90-days, when ARB or the emissions reporting organization is required to make the reporting entities’ disclosures and ARB’s report available on the digital platform.
- Deletes the requirement for ARB to contract with a climate reporting organization to prepare a biennial public report on the climate-related financial risk disclosures.
- Makes other technical changes.
FISCAL EFFECT: Unknown
COMMENTS:
- Author’s statement:
California, like the rest of the world, is already deeply impacted by climate change, with worsening droughts, floods, and the unforgettable devastation brought on by an influx of massive wildfires – the top five largest wildfires in the state's history have all occurred in 2018 or later. We no longer have the time to rely on massive corporations to voluntarily report their emissions, and cannot afford any possibility that the emissions we are being told about have been altered or manipulated to ensure a positive public-facing appearance for a particular company. Material and financial risks associated with climate change additionally have the potential to destabilize capital markets and lead to serious negative consequences for financial institutions and the broader economy. To address these challenges, the Legislature passed SB 253 and 261 in 2023.
Senate Bill 219, joint authored by Senators Wiener and Stern, makes a number of technical amendments to SB 253—the Climate Corporate Data Accountability Act (Wiener, 2023) and SB 261— The Climate-Related Financial Risk Act (Stern, 2023). It also extends The California Air Resources Board (CARB)’s window to complete a rule-making process by six months, while leaving intact the requirement for disclosures to begin in 2026.
- Corporate emission reporting. SB 261 (Stern), Chapter 383, Statutes of 2023, requires more than 10,000 companies with annual revenues exceeding $500 million to detail how climate change poses financial risks to their operations, not just in California, but around the world. Under that law, a company is required to annually report on its climate-related financial risk, in accordance with the recommended framework and disclosures contained in the Final Report of Recommendations of the Task Force on Climate-related Financial Disclosure, and post the disclosure report on its website and pay a fee to ARB. Then ARB, through a contracted climate reporting organization, would generate an annual public report of climate related financial risk based on a subset of companies’ reports.
SB 253 (Wiener), Chapter 382, Statutes of 2023, requires any partnership, corporation, limited liability company, or other U.S. business entity with total annual revenues greater than $1 billion and that does business in California to publicly report their annual GHG emissions, as specified by the ARB.
On a global scale, the “Scope” framework was introduced in 2001 by the WRI and World Business Council for Sustainable Development as part of their Greenhouse Gas Protocol Corporate Accounting and Reporting Standard. The goal was to create a universal method for companies to measure and report the emissions associated with their business. The three Scopes allow companies to differentiate between the emissions they emit directly into the air, which they have the most control over, and the emissions they contribute to indirectly.
Scope 1 covers all direct GHGs that stem from sources that a reporting entity owns or directly controls, regardless of location, including, but not limited to, fuel combustion activities. Scope 2 covers indirect GHGs from consumed electricity, steam, heating, or cooling purchased or acquired by a reporting entity, regardless of location. Scope 3 includes all other indirect emissions that occur in a company’s value chain, such as purchased goods and services, business travel, employee commuting, waste disposal, use of sold products, transportation and distribution (up- and downstream), investments, and leased assets and franchises.
SB 253 requires specified companies to use the Greenhouse Gas Protocol Corporate Accounting and Reporting Standard and the Greenhouse Gas Protocol Corporate Value Chain (Scope 3) Accounting and Reporting Standard to detail its Scope 3 emissions calculations. The emissions disclosures are required to be independently verified by an outside auditor, and requires businesses to pay an annual fee of up to $1,000 to cover state administrative costs.
SB 219, among other changes, allows companies to consolidate their GHG emissions reporting at the parent company level.
- Deadlines. SB 219 proposes a six month deadline extension for ARB to promulgate regulations to require a reporting entity to annually disclose its GHG emissions.
With an appropriation from the Legislature last year, ARB is positioned to hire staff in fall/winter 2024 and plans to begin informal workshops with stakeholders on the draft regulations as soon as feasible thereafter, likely early to mid-2025. ARB feels a more realistic timeline for implementation would include a two-year delay due to the public comment timelines in the Administrative Procedures Act, under which regulations are adopted, and the Bagley-Keene Open Meeting Act, to which ARB is subject.
Supporters of SB 219 argue that a two-year delay would cause both uncertainty and increased burden for businesses. Further, advocates of the bill point to other state agencies promulgating more complex regulations in less time than ARB is suggesting is needed for the SB 253 regulations.
- Technical changes. SB 219 makes further technical changes to the climate disclosure laws, including allowing ARB to contract with a third party entity when implementing SB 261 in order to prepare a biennial report and other analysis as it deems necessary, and allows ARB to contract with a third party entity to receive emissions reports and create a public website to provide access to SB 253 emissions data.
REGISTERED SUPPORT / OPPOSITION:
Support
350 Bay Area Action
350 Conejo / San Fernando Valley
350 Sacramento
Active San Gabriel Valley
Amalgamated Bank
Americans for Financial Reform
Audubon California
Ban Sup (single Use Plastic)
California Environmental Voters
Californians Against Waste
Calpirg, California Public Interest Research Group
Center for Biological Diversity
Center for Community Action & Environmental Justice
Central Valley Air Quality Coalition
Ceres
Cleanearth4kids.org
Climate Action California
Climate Equity Policy Center
Climate Hawks Vote
Climate Reality Project San Fernando Valley Chapter
Coalition for Clean Air
Community Water Center
Courage California
Dayenu: a Jewish Call to Climate Action
Earthjustice
Environment California
Environmental Defense Fund
Fossil Free California
Friends Committee on Legislation of California
Friends of The Earth U.S.
Greenlining Institute
Habitat Recovery Project
Hammond Climate Solutions Foundation
Hang Out Do Good
Indivisible Ca: Statestrong
Institute for Agriculture and Trade Policy
Jobs to Move America
Lutheran Office of Public Policy - California
Natural Resources Defense Council
Nextgen California
Ocean Conservancy
Pacific Environment
Planning and Conservation League
Public Citizen
Rise Economy
Rising Sun Center for Opportunity
Sacramento Area Congregations Together
San Francisco Bay Physicians for Social Responsibility
Sierra Club California
Sunflower Alliance
The Climate Center
Third ACT
Third ACT Bay Area
Third ACT Sacramento
Third ACT Socal
Transformative Wealth Management LLC
Union of Concerned Scientists
Voices for Progress
Vote Solar
Opposition
None on file
Analysis Prepared by: Paige Brokaw / NAT. RES. /
SENATE THIRD READING
STR Bill Id:SB 219
Author:(Wiener and Stern)
As Amended Ver:August 23, 2024
Majority vote
SUMMARY
Delays the requirement that the State Air Resources Board (ARB) adopt regulations until July 1, 2025; requires that the regulations adopted by ARB to require, among other things, a reporting entity to make the annual disclosure to either the greenhouse gas emissions (GHG) reporting organization or ARB; and, requires that the reporting entity publicly disclose its Scope 3 emissions on a schedule specified by ARB, rather than no later than 180 days after its Scope 1 emissions and Scope 2 emissions are publicly disclosed.
Major Provisions
- Extends the deadline by six months, from January 1, 2025, to July 1, 2025, for ARB to develop and adopt regulations to require a reporting entity to annually disclose all of the reporting entity's Scope 1 emissions, Scope 2 emissions, and Scope 3 emissions, and obtain an assurance engagement performed by an independent third-party assurance provider.
- Requires those regulations to require the reporting entity to make the annual disclosure to either the emissions reporting organization, if contracted for services, or ARB.
- Revise the reporting schedule for a reporting entity, starting in 2027 and annually thereafter, to publicly disclose its Scope 3 emissions on a schedule specified by ARB as part of the regulations developed for the prior fiscal year.
- Allows reports to be consolidated at the parent company level. Provides that if a subsidiary of a parent company qualifies as a reporting entity, the subsidiary is not required to prepare a separate report
- Deletes the suggestion for ARB to assess currently available GHG accounting and reporting standards every five years.
- Requires ARB to ensure the report done with an academic institution on the public disclosures made by reporting entities to the emissions reporting is posted publicly by either the emissions reporting organization, if contracted for services, to be made publicly available on the digital platform required to be created by the emissions reporting organization, or ARB on its public internet website.
- Extends by 60-days, from 30-days to 90-days, when ARB or the emissions reporting organization is required to make the reporting entities' disclosures and ARB's report available on the digital platform.
- Deletes the requirement for ARB to contract with a climate reporting organization to prepare a biennial public report on the climate-related financial risk disclosures.
COMMENTS
SB 253 (Wiener), Chapter 382, Statutes of 2023, requires any partnership, corporation, limited liability company, or other U.S. business entity with total annual revenues greater than $1 billion and that does business in California to publicly report their annual GHG emissions, as specified by the ARB.
SB 253 requires specified companies to use the Greenhouse Gas Protocol Corporate Accounting and Reporting Standard and the Greenhouse Gas Protocol Corporate Value Chain (Scope 3) Accounting and Reporting Standard to detail its Scope 3 emissions calculations. The emissions disclosures are required to be independently verified by an outside auditor, and requires businesses to pay an annual fee of up to $1,000 to cover state administrative costs.
SB 261 (Stern), Chapter 383, Statutes of 2023, requires companies that do business in California and have gross revenues exceeding $500 million annually, excluding insurance companies, to report on their climate-related financial risk, and requires the ARB to contract with a qualified climate reporting organization to review and publish an analysis of those reports, as specified.
SB 219 proposes a six month deadline extension for ARB to promulgate regulations to require a reporting entity to annually disclose its GHG emissions, among other technical changes to both GHG disclosure laws.
According to the Author
California, like the rest of the world, is already deeply impacted by climate change, with worsening droughts, floods, and the unforgettable devastation brought on by an influx of massive wildfires – the top five largest wildfires in the state's history have all occurred in 2018 or later. We no longer have the time to rely on massive corporations to voluntarily report their emissions, and cannot afford any possibility that the emissions we are being told about have been altered or manipulated to ensure a positive public-facing appearance for a particular company. Material and financial risks associated with climate change additionally have the potential to destabilize capital markets and lead to serious negative consequences for financial institutions and the broader economy. To address these challenges, the Legislature passed SB 253 and 261 in 2023.
Senate Bill 219, joint authored by Senators Wiener and Stern, makes a number of technical amendments to SB 253—the Climate Corporate Data Accountability Act (Wiener, 2023) and SB 261— The Climate-Related Financial Risk Act (Stern, 2023). It also extends The California Air Resources Board (CARB)'s window to complete a rule-making process by six months, while leaving intact the requirement for disclosures to begin in 2026.
Arguments in Support
A coalition of environmental organizations, including California Environmental Voters and Ceres, Inc., write in support that SB 219 makes common-sense technical amendments while preserving the foundational GHG emissions and climate risk disclosure requirements, including the requirement for first reporting in 2026, thereby ensuring the people of California benefit from these critical climate transparency laws without delay.
Arguments in Opposition
None on file.
FISCAL COMMENTS
Unknown.
VOTES
SENATE FLOOR: 29-8-3
YES: Allen, Alvarado-Gil, Archuleta, Atkins, Becker, Blakespear, Bradford, Caballero, Cortese, Dodd, Durazo, Eggman, Glazer, Gonzalez, Hurtado, Laird, Limón, McGuire, Menjivar, Min, Newman, Padilla, Portantino, Roth, Skinner, Smallwood-Cuevas, Umberg, Wahab, Wiener
NO: Dahle, Grove, Jones, Nguyen, Niello, Ochoa Bogh, Seyarto, Wilk
ABS, ABST OR NV: Ashby, Rubio, Stern
UPDATED
VERSION: August 23, 2024
CONSULTANT: Paige Brokaw / NAT. RES. / (916) 319-2092 FN: 0004985
SENATE RULES COMMITTEE Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | SB 219 |
THIRD READING
Bill No: SB 219
Author: Committee on Budget and Fiscal Review
Introduced: 1/18/23
Vote: 21
SOURCE: Author
DIGEST:
This bill expresses the intent of the Legislature to enact statutory changes relating to the Budget Act of 2023.
ANALYSIS: Senate Bills 100 through 219, inclusive, are to be considered as vehicles for the 2023-24 Budget Trailer Bills.
FISCAL EFFECT: Appropriation: No Fiscal Com.: No Local: No
SUPPORT: (Verified 3/17/23)
None received
OPPOSITION: (Verified 3/17/23)
None received
Prepared by: Karen Chow / SFA / (916) 651-1520
3/27/23 9:29:04
**** END ****
Discussed in Hearing
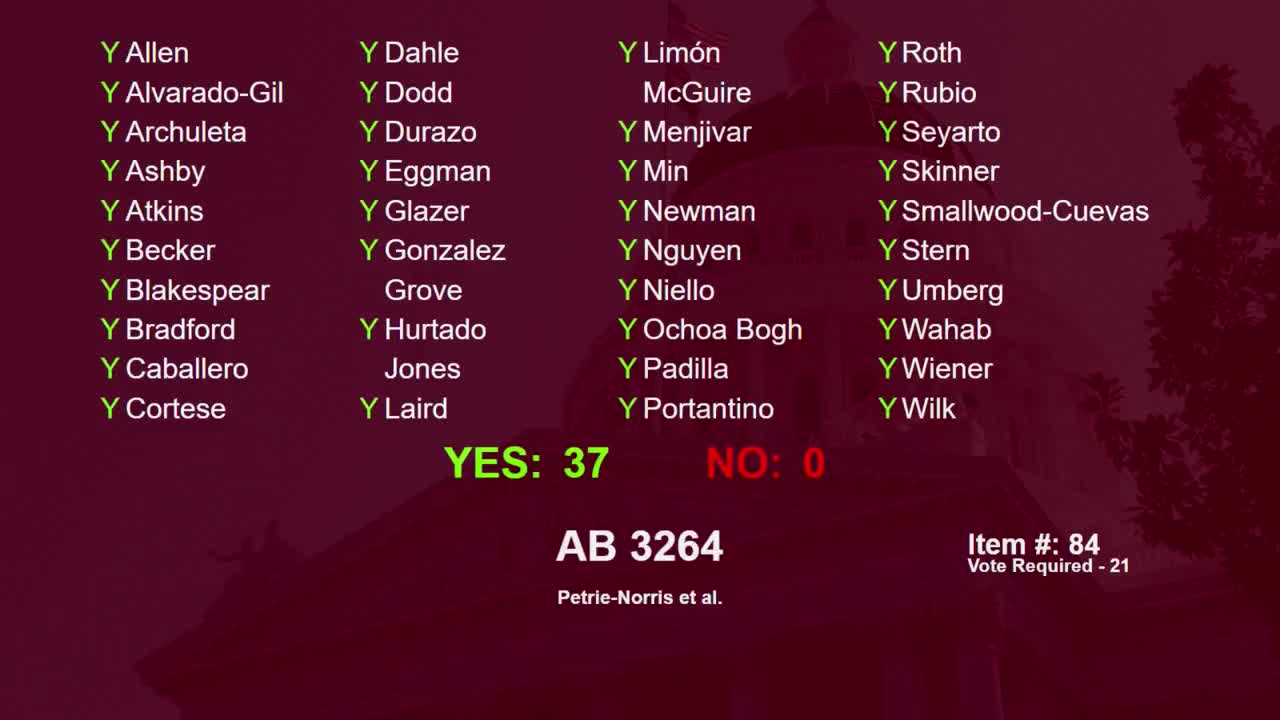 3MIN
Senate Floor
 1MIN
Assembly Floor
 11MIN
Assembly Standing Committee on Natural Resources
Bill Co-Author(s):