SB 890: Property taxation: change of ownership and base year value transfers.
- Session Year: 2023-2024
- House: Senate
- Latest Version Date: 2023-10-04
Current Status:
Passed
(2023-10-04: Chaptered by Secretary of State. Chapter 312, Statutes of 2023.)
Introduced
In Committee
First Chamber
In Committee
Second Chamber
Enacted
The California Constitution generally limits ad valorem taxes on real property to 1% of the full cash value of that property. For purposes of this limitation, full cash value is defined as the assessors valuation of real property as shown on the 197576 tax bill under full cash value or, thereafter, the appraised value of that real property when purchased, newly constructed, or a change in ownership has occurred.
Existing property tax law, pursuant to constitutional authorization applicable to purchase or transfers that occurred on or before February 15, 2021, provides that the purchase or transfer of the principal residence, and the first $1,000,000 of other real property, of a transferor in the case of a transfer between parents and their children or, if certain conditions are met, between grandparents and their grandchildren, is not a purchase or change in ownership for purposes of determining the full cash value of property for taxation (prior intergenerational transfer exclusion). Existing property tax law, pursuant to constitutional authorization, excludes, beginning on and after February 16, 2021, from the term change in ownership purchases or transfers of real property that is the principal residence, or is a family farm, of an eligible transferor in the case of a purchase or transfer between parents and their children or, if certain requirements are met, between grandparents and their grandchildren, and certain other requirements are satisfied (intergenerational transfer exclusion).
Existing property tax law provides that a change in ownership does not include certain transfers of a mobilehome park or a floating home marina to a nonprofit corporation, stock cooperative corporation, limited equity stock cooperative, or other entity formed by the tenants of a mobilehome park or floating home marina, respectively, for the purpose of purchasing the mobilehome park or floating home marina, as applicable, if certain requirements relating to tenant rental and participation are met. Existing law provides that if a transfer of a mobilehome park or floating home marina is excluded from a change of ownership pursuant to that provision but the park or floating home marina has not been converted to a condominium, stock cooperative ownership, or limited equity cooperative ownership, then any transfer of shares of the voting stock of, or other ownership or membership interests in, the entity that acquired the park or floating home marina is a change in ownership of a pro rata portion of the real property of the park or floating home marina, unless the transfer is for the purpose of converting the park or floating home marina into one of specified entities or the transfer is excluded from change in ownership pursuant to specified laws, including provisions relating to interspousal transfers.
This bill would also provide that if a transfer of a mobilehome park or floating home marina, as applicable, is excluded from a change of ownership pursuant to the above-described provision but the park or floating home marina has not been converted to a condominium, stock cooperative ownership, or limited equity cooperative ownership, then any transfer of shares of the voting stock of, or other ownership or membership interests in, the entity that acquired the park or floating home marina is a change in ownership of a pro rata portion of the real property of the park or floating home marina, unless the transfer is excluded from change in ownership pursuant to the intergenerational transfer exclusion.
Existing property tax law, pursuant to a constitutional authorization, allows the transfer of the base year value of a qualified contaminated property to a comparable replacement property of equal or lesser value that is located in the same county and is acquired or newly constructed as a replacement for the contaminated property, as described. That law requires the county assessor to determine a new base year value for the original property upon the sale or transfer of that property, as described. That law states that these transfer provisions do not apply unless the sale or transfer of the original property is a change in ownership that subjects the original property to reappraisal at its current fair market value, as described, or results in a base year value determined in accordance with specified laws. That law also prohibits the application of this property tax relief for a replacement property if the owner or owners of the original property receive property tax relief under another law or sign a claim under the prior intergenerational transfer exclusion allowing the base year value to stay with the original property.
Existing law, pursuant to constitutional authorization, allows, beginning on and after April 1, 2021, an owner who is over 55 years of age, severely disabled, or a victim of a wildfire or natural disaster to transfer the taxable value, as described, of a primary residence eligible for either the homeowners exemption or the disabled veterans exemption to a replacement primary residence, located anywhere in this state and regardless of value, that is purchased or newly constructed as that persons principal residence within 2 years of the sale of the original primary residence (age, disability, and disaster base year value transfer).
This bill would authorize the application of the qualified contaminated property base year value transfer provisions if the sale or transfer of the original property results in a base year value determined in accordance with the age, disability, and disaster base year value transfer because the property qualifies under that age, disability, and disaster base year value transfer. The bill would prohibit the application of the qualified contaminated property base year value transfer provisions if the owner or owners of the original property sign a claim under the intergenerational transfer exclusion allowing the base year value to stay with the original property. The bill would also make nonsubstantive changes to the age, disability, and disaster base year value transfer provisions.
By imposing additional duties on local tax officials, the bill would impose a state-mandated local program.
The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement.
This bill would provide that, if the Commission on State Mandates determines that the bill contains costs mandated by the state, reimbursement for those costs shall be made pursuant to the statutory provisions noted above.
Existing law requires the state to reimburse local agencies annually for certain property tax revenues lost as a result of any exemption or classification of property for purposes of ad valorem property taxation.
This bill would provide that, notwithstanding those provisions, no appropriation is made and the state shall not reimburse local agencies for property tax revenues lost by them pursuant to the bill.
This bill would take effect immediately as a tax levy.
The California Constitution generally limits ad valorem taxes on real property to 1% of the full cash value of that property. For purposes of this limitation, full cash value is defined as the assessors valuation of real property as shown on the 197576 tax bill under full cash value or, thereafter, the appraised value of that real property when purchased, newly constructed, or a change in ownership has occurred.
Existing property tax law, pursuant to constitutional authorization applicable to purchase or transfers that occurred on or before February 15, 2021, provides that the purchase or transfer of the principal residence, and the first $1,000,000 of other real property, of a transferor in the case of a transfer between parents and their children or, if certain conditions are met, between grandparents and their grandchildren, is not a purchase or change in ownership for purposes of determining the full cash value of property for taxation (prior intergenerational transfer exclusion). Existing property tax law, pursuant to constitutional authorization, excludes, beginning on and after February 16, 2021, from the term change in ownership purchases or transfers of real property that is the principal residence, or is a family farm, of an eligible transferor in the case of a purchase or transfer between parents and their children or, if certain requirements are met, between grandparents and their grandchildren, and certain other requirements are satisfied (intergenerational transfer exclusion).
Existing property tax law provides that a change in ownership does not include certain transfers of a mobilehome park or a floating home marina to a nonprofit corporation, stock cooperative corporation, limited equity stock cooperative, or other entity formed by the tenants of a mobilehome park or floating home marina, respectively, for the purpose of purchasing the mobilehome park or floating home marina, as applicable, if certain requirements relating to tenant rental and participation are met. Existing law provides that if a transfer of a mobilehome park or floating home marina is excluded from a change of ownership pursuant to that provision but the park or floating home marina has not been converted to a condominium, stock cooperative ownership, or limited equity cooperative ownership, then any transfer of shares of the voting stock of, or other ownership or membership interests in, the entity that acquired the park or floating home marina is a change in ownership of a pro rata portion of the real property of the park or floating home marina, unless the transfer is for the purpose of converting the park or floating home marina into one of specified entities or the transfer is excluded from change in ownership pursuant to specified laws, including provisions relating to interspousal transfers.
This bill would also provide that if a transfer of a mobilehome park or floating home marina, as applicable, is excluded from a change of ownership pursuant to the above-described provision but the park or floating home marina has not been converted to a condominium, stock cooperative ownership, or limited equity cooperative ownership, then any transfer of shares of the voting stock of, or other ownership or membership interests in, the entity that acquired the park or floating home marina is a change in ownership of a pro rata portion of the real property of the park or floating home marina, unless the transfer is excluded from change in ownership pursuant to the intergenerational transfer exclusion.
Existing property tax law, pursuant to a constitutional authorization, allows the transfer of the base year value of a qualified contaminated property to a comparable replacement property of equal or lesser value that is located in the same county and is acquired or newly constructed as a replacement for the contaminated property, as described. That law requires the county assessor to determine a new base year value for the original property upon the sale or transfer of that property, as described. That law states that these transfer provisions do not apply unless the sale or transfer of the original property is a change in ownership that subjects the original property to reappraisal at its current fair market value, as described, or results in a base year value determined in accordance with specified laws. That law also prohibits the application of this property tax relief for a replacement property if the owner or owners of the original property receive property tax relief under another law or sign a claim under the prior intergenerational transfer exclusion allowing the base year value to stay with the original property.
Existing law, pursuant to constitutional authorization, allows, beginning on and after April 1, 2021, an owner who is over 55 years of age, severely disabled, or a victim of a wildfire or natural disaster to transfer the taxable value, as described, of a primary residence eligible for either the homeowners exemption or the disabled veterans exemption to a replacement primary residence, located anywhere in this state and regardless of value, that is purchased or newly constructed as that persons principal residence within 2 years of the sale of the original primary residence (age, disability, and disaster base year value transfer).
This bill would authorize the application of the qualified contaminated property base year value transfer provisions if the sale or transfer of the original property results in a base year value determined in accordance with the age, disability, and disaster base year value transfer because the property qualifies under that age, disability, and disaster base year value transfer. The bill would prohibit the application of the qualified contaminated property base year value transfer provisions if the owner or owners of the original property sign a claim under the intergenerational transfer exclusion allowing the base year value to stay with the original property. The bill would also make nonsubstantive changes to the age, disability, and disaster base year value transfer provisions.
By imposing additional duties on local tax officials, the bill would impose a state-mandated local program.
The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement.
This bill would provide that, if the Commission on State Mandates determines that the bill contains costs mandated by the state, reimbursement for those costs shall be made pursuant to the statutory provisions noted above.
Existing law requires the state to reimburse local agencies annually for certain property tax revenues lost as a result of any exemption or classification of property for purposes of ad valorem property taxation.
This bill would provide that, notwithstanding those provisions, no appropriation is made and the state shall not reimburse local agencies for property tax revenues lost by them pursuant to the bill.
This bill would take effect immediately as a tax levy.
The California Constitution generally limits ad valorem taxes on real property to 1% of the full cash value of that property. For purposes of this limitation, full cash value is defined as the assessors valuation of real property as shown on the 197576 tax bill under full cash value or, thereafter, the appraised value of that real property when purchased, newly constructed, or a change in ownership has occurred.
Existing property tax law, pursuant to constitutional authorization applicable to purchase or transfers that occurred on or before February 15, 2021, provides that the purchase or transfer of the principal residence, and the first $1,000,000 of other real property, of a transferor in the case of a transfer between parents and their children or, if certain conditions are met, between grandparents and their grandchildren, is not a purchase or change in ownership for purposes of determining the full cash value of property for taxation (prior intergenerational transfer exclusion). Existing property tax law, pursuant to constitutional authorization, excludes, beginning on and after February 16, 2021, from the term change in ownership purchases or transfers of real property that is the principal residence, or is of a family farm, of an eligible transferor in the case of a purchase or transfer between parents and their children or, if certain requirements are met, between grandparents and their grandchildren, and certain other requirements are satisfied (intergenerational transfer exclusion).
Existing property tax law provides that a change in ownership does not include certain transfers of a mobilehome park or a floating home marina to a nonprofit corporation, stock cooperative corporation, limited equity stock cooperative, or other entity formed by the tenants of a mobilehome park or floating home marina, respectively, for the purpose of purchasing the mobilehome park or floating home marina, as applicable, if certain requirements relating to tenant rental and participation are met. Existing law provides that if a transfer of a mobilehome park or floating home marina is excluded from a change of ownership pursuant to that provision but the park or floating home marina has not been converted to a condominium, stock cooperative ownership, or limited equity cooperative ownership, then any transfer of shares of the voting stock of, or other ownership or membership interests in, the entity that acquired the park or floating home marina is a change in ownership of a pro rata portion of the real property of the park or floating home marina, unless the transfer is for the purpose of converting the park or floating home marina into one of specified entities or the transfer is excluded from change in ownership pursuant to specified laws, including provisions relating to interspousal transfers.
This bill would also provide that if a transfer of a mobilehome park or floating home marina, as applicable, is excluded from a change of ownership pursuant to the above-described provision but the park or floating home marina has not been converted to a condominium, stock cooperative ownership, or limited equity cooperative ownership, then any transfer of shares of the voting stock of, or other ownership or membership interests in, the entity that acquired the park or floating home marina is a change in ownership of a pro rata portion of the real property of the park or floating home marina, unless the transfer is excluded from change in ownership pursuant to the intergenerational transfer exclusion.
Existing property tax law, pursuant to a constitutional authorization, allows the transfer of the base year value of a qualified contaminated property to a comparable replacement property of equal or lesser value that is located in the same county and is acquired or newly constructed as a replacement for the contaminated property, as described. That law requires the county assessor to determine a new base year value for the original property upon the sale or transfer of that property, as described. That law states that these transfer provisions do not apply unless the sale or transfer of the original property is a change in ownership that subjects the original property to reappraisal at its current fair market value, as described, or results in a base year value determined in accordance with specified laws. That law also prohibits the application of this property tax relief for a replacement property if the owner or owners of the original property receive property tax relief under another law or sign a claim under the prior intergenerational transfer exclusion allowing the base year value to stay with the original property.
Existing law, pursuant to constitutional authorization, allows, beginning on and after April 1, 2021, an owner who is over 55 years of age, severely disabled, or a victim of a wildfire or natural disaster to transfer the taxable value, as described, of a primary residence eligible for either the homeowners exemption or the disabled veterans exemption to a replacement primary residence, located anywhere in this state and regardless of value, that is purchased or newly constructed as that persons principal residence within 2 years of the sale of the original primary residence (age, disability, and disaster base year value transfer).
This bill would authorize the application of the qualified contaminated property base year value transfer provisions if the sale or transfer of the original property results in a base year value determined in accordance with the age, disability, and disaster base year value transfer because the property qualifies under that age, disability, and disaster base year value transfer. The bill would prohibit the application of the qualified contaminated property base year value transfer provisions if the owner or owners of the original property sign a claim under the intergenerational transfer exclusion allowing the base year value to stay with the original property. The bill would also make nonsubstantive changes to the age, disability, and disaster base year value transfer provisions.
By imposing additional duties on local tax officials, the bill would impose a state-mandated local program.
The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement.
This bill would provide that, if the Commission on State Mandates determines that the bill contains costs mandated by the state, reimbursement for those costs shall be made pursuant to the statutory provisions noted above.
Existing law requires the state to reimburse local agencies annually for certain property tax revenues lost as a result of any exemption or classification of property for purposes of ad valorem property taxation.
This bill would provide that, notwithstanding those provisions, no appropriation is made and the state shall not reimburse local agencies for property tax revenues lost by them pursuant to the bill.
This bill would take effect immediately as a tax levy.
The California Constitution generally limits ad valorem taxes on real property to 1% of the full cash value of that property. For purposes of this limitation, full cash value is defined as the assessors valuation of real property as shown on the 197576 tax bill under full cash value or, thereafter, the appraised value of that real property when purchased, newly constructed, or a change in ownership has occurred.
Existing property tax law, pursuant to constitutional authorization applicable to purchase or transfers that occurred on or before February 15, 2021, provides that the purchase or transfer of the principal residence, and the first $1,000,000 of other real property, of a transferor in the case of a transfer between parents and their children or, if certain conditions are met, between grandparents and their grandchildren, is not a purchase or change in ownership for purposes of determining the full cash value of property for taxation (prior intergenerational transfer exclusion). Existing property tax law, pursuant to constitutional authorization, excludes, beginning on and after February 16, 2021, from the term change in ownership purchases or transfers of real property that is the principal residence, or is of a family farm, of an eligible transferor in the case of a purchase or transfer between parents and their children or, if certain requirements are met, between grandparents and their grandchildren, and certain other requirements are satisfied (intergenerational transfer exclusion).
Existing property tax law provides that a change in ownership does not include certain transfers of a mobilehome park or a floating home marina to a nonprofit corporation, stock cooperative corporation, limited equity stock cooperative, or other entity formed by the tenants of a mobilehome park or floating home marina, respectively, for the purpose of purchasing the mobilehome park or floating home marina, as applicable, if certain requirements relating to tenant rental and participation are met. Existing law provides that if a transfer of a mobilehome park or floating home marina is excluded from a change of ownership pursuant to that provision but the park or floating home marina has not been converted to a condominium, stock cooperative ownership, or limited equity cooperative ownership, then any transfer of shares of the voting stock of, or other ownership or membership interests in, the entity that acquired the park or floating home marina is a change in ownership of a pro rata portion of the real property of the park or floating home marina, unless the transfer is for the purpose of converting the park or floating home marina into one of specified entities or the transfer is excluded from change in ownership pursuant to specified laws, including provisions relating to interspousal transfers.
This bill would also provide that if a transfer of a mobilehome park or floating home marina, as applicable, is excluded from a change of ownership pursuant to the above-described provision but the park or floating home marina has not been converted to a condominium, stock cooperative ownership, or limited equity cooperative ownership, then any transfer of shares of the voting stock of, or other ownership or membership interests in, the entity that acquired the park or floating home marina is a change in ownership of a pro rata portion of the real property of the park or floating home marina, unless the transfer is excluded from change in ownership pursuant to the intergenerational transfer exclusion.
Existing property tax law, pursuant to a constitutional authorization, allows the transfer of the base year value of a qualified contaminated property to a comparable replacement property of equal or lesser value that is located in the same county and is acquired or newly constructed as a replacement for the contaminated property, as described. That law requires the county assessor to determine a new base year value for the original property upon the sale or transfer of that property, as described. That law states that these transfer provisions do not apply unless the sale or transfer of the original property is a change in ownership that subjects the original property to reappraisal at its current fair market value, as described, or results in a base year value determined in accordance with specified laws. That law also prohibits the application of this property tax relief for a replacement property if the owner or owners of the original property receive property tax relief under another law or sign a claim under the prior intergenerational transfer exclusion allowing the base year value to stay with the original property.
Existing law, pursuant to constitutional authorization, allows, beginning on and after April 1, 2021, an owner who is over 55 years of age, severely disabled, or a victim of a wildfire or natural disaster to transfer the taxable value, as described, of a primary residence eligible for either the homeowners exemption or the disabled veterans exemption to a replacement primary residence, located anywhere in this state and regardless of value, that is purchased or newly constructed as that persons principal residence within 2 years of the sale of the original primary residence (age, disability, and disaster base year value transfer).
This bill would authorize the application of the qualified contaminated property base year value transfer provisions if the sale or transfer of the original property results in a base year value determined in accordance with the age, disability, and disaster base year value transfer because the property qualifies under that age, disability, and disaster base year value transfer. The bill would prohibit the application of the qualified contaminated property base year value transfer provisions if the owner or owners of the original property sign a claim under the intergenerational transfer exclusion allowing the base year value to stay with the original property.
By imposing additional duties on local tax officials, the bill would impose a state-mandated local program.
The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement.
This bill would provide that, if the Commission on State Mandates determines that the bill contains costs mandated by the state, reimbursement for those costs shall be made pursuant to the statutory provisions noted above.
Existing law requires the state to reimburse local agencies annually for certain property tax revenues lost as a result of any exemption or classification of property for purposes of ad valorem property taxation.
This bill would provide that, notwithstanding those provisions, no appropriation is made and the state shall not reimburse local agencies for property tax revenues lost by them pursuant to the bill.
This bill would take effect immediately as a tax levy.
(a)Change in ownership shall not include the following:
(1)Any transfer, on or after January 1, 1985, of a mobilehome park to a nonprofit corporation, stock cooperative corporation, limited equity stock cooperative, or other entity formed by the tenants of a mobilehome park, for the purpose of purchasing the mobilehome park, provided that, with respect to any transfer of a mobilehome park on or after January 1, 1989, subject to this paragraph, the individual tenants who were renting at least 51 percent of the spaces in the mobilehome park prior to the transfer participate in the transaction through the ownership of an aggregate of at least 51 percent of the voting stock of, or other ownership or membership interests in, the entity which acquires the park. If, on or after January 1, 1998, a park is acquired by an entity that did not attain an initial tenant participation level of at least 51 percent on the date of the transfer, the entity shall have up to one year after the date of the transfer to attain a tenant participation level of at least 51 percent. If an individual tenant notifies the county assessor of the intention to comply with the conditions set forth in the preceding sentence, the mobilehome park may not be reappraised by the assessor during that period. However, if a tenant participation level of at least 51 percent is not attained within the one-year period, the county assessor shall thereafter levy escape assessments for the mobilehome park transfer.
(2)Any transfer or transfers on or after January 1, 1985, of rental spaces in a mobilehome park to the individual tenants of the rental spaces, provided that (1) at least 51 percent of the rental spaces are purchased by individual tenants renting their spaces prior to purchase, and (2) the individual tenants of these spaces form, within one year after the first purchase of a rental space by an individual tenant, a resident organization as described in subdivision (l) of Section 50781 of the Health and Safety Code, to operate and maintain the park. If, on or after January 1, 1985, an individual tenant or tenants notify the county assessor of the intention to comply with the conditions set forth in the preceding sentence, any mobilehome park rental space that is purchased by an individual tenant in that mobilehome park during that period shall not be reappraised by the assessor. However, if all of the conditions set forth in the first sentence of this paragraph are not satisfied, the county assessor shall thereafter levy escape assessments for the spaces so transferred. This paragraph shall apply only to those rental mobilehome parks that have been in operation for five years or more.
(b)(1)If the transfer of a mobilehome park has been excluded from a change in ownership pursuant to paragraph (1) of subdivision (a) and the park has not been converted to condominium, stock cooperative ownership, or limited equity cooperative ownership, any transfer on or after January 1, 1989, of shares of the voting stock of, or other ownership or membership interests in, the entity that acquired the park in accordance with paragraph (1) of subdivision (a) shall be a change in ownership of a pro rata portion of the real property of the park unless the transfer is for the purpose of converting the park to condominium, stock cooperative ownership, or limited equity cooperative ownership or is excluded from change in ownership by Section 62, 63, 63.1, or 63.2.
(2)For the purposes of this subdivision, pro rata portion of the real property means the total real property of the mobilehome park multiplied by a fraction consisting of the number of shares of voting stock, or other ownership or membership interests, transferred divided by the total number of outstanding issued or unissued shares of voting stock of, or other ownership or membership interests in, the entity that acquired the park in accordance with paragraph (1) of subdivision (a).
(3)Any pro rata portion or portions of real property that changed ownership pursuant to this subdivision may be separately assessed as provided in Section 2188.10.
(4)(A)Notwithstanding any other provision of law, after an exclusion under subdivision (a), the assessor may not levy any escape or supplemental assessment with respect to any change in ownership of a pro rata portion of the real property of the mobilehome park that occurred between January 1, 1989, and January 1, 2002, and for which the assessor did not, prior to January 1, 2000, levy any assessments. However, commencing with the January 1, 2002, lien date, the assessor shall correct the base year value of the pro rata portion of the real property of the park to properly reflect these changes in ownership. A mobilehome park shall provide information requested by the assessor that is necessary to correct the base year value of the property for purposes of this paragraph.
(B)When an assessor corrects the base year value of the real property of the park pursuant to subparagraph (A), the assessor shall notify parks that residents may be eligible for property tax assistance programs offered by either the Controller or the Franchise Tax Board for senior citizens, or blind or disabled persons.
(C)Any outstanding taxes that were levied between January 1, 2000, and January 1, 2002, as a result of a pro rata change in ownership as described in subparagraph (A) shall be canceled. However, there shall be no refund of taxes, as so levied, that were paid prior to January 1, 2002.
(5)A mobilehome park that does not utilize recorded deeds to transfer ownership interest in the spaces or lots shall file, by February 1 of each year, a report with the county assessors office containing all of the following information:
(A)The full name and mailing address of each owner, stockholder, or holder of an ownership interest in the mobilehome park.
(B)The situs address, including space number, of each unit.
(C)The date that the ownership interest was acquired.
(D)If the unit is a manufactured home, the Department of Housing and Community Development decal number or serial number, or both, and whether the manufactured home is subject to the vehicle license fee or the local property tax.
(6)Within 30 days of a change in ownership, the new resident owner or other purchaser or transferee of a manufactured home within a mobilehome park that does not utilize recorded deeds to transfer ownership interest in the spaces or lots shall file a change in ownership statement described in either Section 480 or 480.2.
(7)Failure to comply with the reporting requirement described in paragraph (5) shall result in a penalty pursuant to Section 482.
(c)It is the intent of the Legislature that, in order to facilitate affordable conversions of mobilehome parks to tenant ownership, paragraph (1) of subdivision (a) apply to all bona fide transfers of rental mobilehome parks to tenant ownership, including, but not limited to, those parks converted to tenant ownership as a nonprofit corporation made on or after January 1, 1985.
SEC. 2.Section 62.5 of the Revenue and Taxation Code is amended to read:62.5.(a)Notwithstanding any provision of this chapter, a change in ownership shall not include a transfer of a floating home marina to a nonprofit corporation, stock cooperative corporation, limited equity stock cooperative, or other entity formed by the tenants of a floating home marina for the purpose of purchasing the floating home marina, provided that the individual tenants who were renting at least 51 percent of the berths in the floating home marina prior to the transfer participate in the transaction through the ownership of an aggregate of at least 51 percent of the voting stock of, or other ownership or membership interests in, the entity that acquires the floating home marina.
(b)(1)If the transfer of a floating home marina has been excluded from a change in ownership pursuant to subdivision (a) and the floating home marina has not been converted to condominium, stock cooperative ownership, or limited equity cooperative ownership, any transfer of shares of the voting stock of, or other ownership or membership interests in, the entity that acquired the floating home marina in accordance with subdivision (a) shall be a change in ownership of a pro rata portion of the real property of the floating home marina, unless the transfer is for the purpose of converting the floating home marina to condominium, stock cooperative ownership, or limited equity cooperative ownership, or is excluded from change in ownership by Section 62, 63, 63.1, or 63.2.
(2)A floating home marina that does not utilize recorded deeds to transfer ownership interest in the berths shall file, by February 1 of each year, a report with the county assessors office containing all of the following information:
(A)The full name and mailing address of each owner, stock holder, or holder of an ownership interest in the floating home marina.
(B)The situs address, including berth number and dock, of each unit.
(C)The date the ownership interest was acquired.
(D)The Department of Housing and Community Development decal number or serial number, or both.
(3)Within 30 days of a change in ownership, the new resident owner or other purchaser or transferee of a floating home within a floating home marina that does not utilize recorded deeds to transfer ownership interest in the berths, shall file a change in ownership statement described in either Section 480 or 480.2.
(c)For purposes of this section, both of the following shall apply:
(1)Floating home marina has the same meaning as defined in Section 800.4 of the Civil Code.
(2)Pro rata portion of the real property means the total real property of the floating home marina multiplied by a fraction consisting of the number of shares of voting stock, or other ownership or membership interests, transferred divided by the total number of outstanding issued or unissued shares of voting stock of, or other ownership or membership interests in, the entity that acquired the floating home marina in accordance with subdivision (a).
SEC. 3.Section 69.4 of the Revenue and Taxation Code is amended to read:69.4.(a)(1)Notwithstanding any other provision of law, pursuant to the authority of subdivision (i) of Section 2 of Article XIIIA of the California Constitution, the base year value of qualified contaminated property may be transferred, subject to the conditions and limitations of that subdivision and this section, to a comparable replacement property of equal or lesser value that is located in the same county and is acquired or newly constructed as a replacement for the contaminated property, pursuant to subparagraph (A) of paragraph (1) of that subdivision.
(2)The limitation in paragraph (1) requiring that the qualified contaminated property and the replacement property be located in the same county does not apply in a county in which the county board of supervisors adopts a resolution making the provisions of this section applicable to replacement properties acquired to replace qualified contaminated properties located in another county within this state. The resolution shall specify the date on and after which its provisions are applicable. The specified date may be a date earlier than the date on which the county adopts the ordinance, but no earlier than November 3, 1998.
(b)The replacement property shall be acquired or newly constructed within five years after the original property is sold or otherwise transferred.
(c)(1)Upon the sale or transfer of the original property, the assessor shall determine a new base year value for that property in accordance with subdivision (a) of Section 2 of Article XIIIA of the California Constitution and Section 110.1.
(2)This section does not apply unless the sale or transfer of the original property is a change in ownership that does either of the following:
(A)Subjects the original property to reappraisal at its current fair market value in accordance with Section 110.1 or 5803.
(B)Results in a base year value determined in accordance with this section, Section 69, Section 69.3, Section 69.5, or Section 69.6 because the property qualifies under this section, Section 69, Section 69.3, Section 69.5, or Section 69.6 as a replacement dwelling or property.
(d)Property tax relief under this section is not available for a replacement property if the owner or owners of the original property do either of the following:
(1)Receive property tax relief under Section 74.7.
(2)Sign a claim under Section 63.1 or 63.2 allowing the base year value to stay with the original property.
(e)For purposes of this section:
(1)The original property means the qualified contaminated property.
(2)Equal or lesser value means the amount of the full cash value of a replacement property that does not exceed one of the following:
(A)One hundred five percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the first year following the date of the sale of the original property.
(B)One hundred ten percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the second year following the date of the sale of the original property.
(C)One hundred fifteen percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the third year following the date of the sale of the original property.
(D)One hundred twenty percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the fourth year following the date of the sale of the original property.
(E)One hundred twenty-five percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the fifth year following the date of the sale of the original property.
For purposes of this paragraph, if the replacement property is, in part, purchased and, in part, newly constructed, the date the replacement property is acquired or newly constructed is the date of acquisition or the date of completion of construction, whichever is later.
(3)The base year value of the original property shall be the base year value of the original property as determined in accordance with Section 110.1, with the inflation factor adjustments permitted by subdivision (f) of Section 110.1. The base year value of the original property shall also include any inflation factor adjustments permitted by subdivision (f) of Section 110.1 up to the date the replacement property is acquired or newly constructed, regardless of whether the claimant continued to own the original property during this entire period. The base year or years used to compute the base year value of the original property shall be deemed to be the base year or years of any property to which that base year value is transferred pursuant to this section.
(4)Fair market value of the replacement property means the full cash value of the replacement property determined in accordance with Section 110.1 as of the date on which that property was acquired or new construction was completed. If the replacement property is, in part, acquired and, in part, newly constructed, fair market value of the replacement property means the fair market value of the land and the improvements as of the date of completion.
(5)Fair market value of the qualified contaminated property means the full cash value of the qualified contaminated property, as if that property was not contaminated, determined in accordance with Section 110.1, as of the date of its sale or transfer by the claimant.
(6)Claimant means any owner of qualified contaminated property claiming the property tax relief provided by this section.
(7)Comparable replacement property means a property that is similar in utility and function to the property that it replaces. Property is similar in function and utility if it is, or is intended to be, used in the same manner as the qualified contaminated property.
(f)(1)A claimant is not eligible for the property tax relief provided by this section unless a claim is filed within three years of the date the replacement property was purchased or the new construction of the replacement property was completed.
(2)The claimant shall provide to the assessor the following information:
(A)Proof that the claimant did not participate or acquiesce in any act or omission that rendered the real property uninhabitable or unusable, as applicable, or is related to any individual or entity that committed that act or omission.
(B)Proof that the qualified contaminated property has been designated as a toxic or environmental hazard or as an environmental cleanup site by an agency of the State of California or the federal government.
(3)The State Board of Equalization shall design the form for claiming eligibility.
(g)(1)Upon the timely filing of a claim, the assessor shall adjust the new base year value as of the date the replacement property is acquired or the date the new construction of the replacement property is completed, whichever is later.
(2)Any taxes that were levied on the replacement property prior to the filing of the claim on the basis of the replacement propertys new base year value, and any allowable annual adjustments thereto, shall be canceled or refunded to the claimant to the extent that the taxes exceed the amount that would be due when determined on the basis of the adjusted new base year value.
(3)Notwithstanding Section 75.10, Chapter 3.5 (commencing with Section 75) of Part 0.5 of Division 1 shall be utilized for purposes of implementing this subdivision, including adjustments of the new base year value of replacement properties acquired prior to the sale or transfer of the qualified contaminated property.
(h)This section applies only to replacement property that is acquired or newly constructed on or after January 1, 1995.
SEC. 4.Section 69.6 of the Revenue and Taxation Code is amended to read:69.6.Notwithstanding any other law, on and after April 1, 2021, the following shall apply:
(a)Pursuant to subdivision (b) of Section 2.1 of Article XIIIA of the California Constitution, any person over 55 years of age, any severely and permanently disabled person, or a victim of wildfire or natural disaster who resides in property that is eligible for either the homeowners exemption, under subdivision (k) of Section 3 of Article XIII of the California Constitution and Section 218, or the disabled veterans exemption, under subdivision (a) of Section 4 of Article XIII of the California Constitution and Section 205.5, may transfer, subject to the conditions and limitations provided in this section, the taxable value of that property to any replacement dwelling that is purchased or newly constructed by that person as their principal residence within two years of the sale by that person of the original property, provided that the taxable value of the original property shall not be transferred to the replacement dwelling until the original property is sold. A person shall not be allowed to transfer the taxable value of a primary residence pursuant to this section more than three times as a claimant who is over 55 years of age or severely or permanently disabled.
(b)In addition to meeting the requirements of subdivision (a), any person claiming the property tax relief provided by this section shall be eligible for that relief only if the following conditions are met:
(1)The claimant is an owner and a resident of the original property either at the time of its sale or within two years of the purchase or new construction of the replacement dwelling.
(2)The original property is eligible for the homeowners exemption or the disabled veterans exemption, as the result of the claimants ownership and occupation of the property as their principal residence, either at the time of its sale or within two years of the purchase or new construction of the replacement dwelling.
(3)At the time of the sale of the original property, the claimant is over 55 years of age, is severely and permanently disabled, or is a victim of wildfire or natural disaster.
(4)At the time of claiming the property tax relief provided by subdivision (a), the claimant is an owner of a replacement dwelling and occupies it as their principal place of residence and, as a result thereof, the property is currently eligible for the homeowners exemption or the disabled veterans exemption, or would be eligible for the exemption except that the property is already receiving the exemption because of an exemption claim filed by the previous owner.
(5)The claimant sells the original property within two years of the purchase or new construction of the replacement dwelling. For purposes of this paragraph:
(A)Either the sale of the original property or the purchase or new construction of the replacement dwelling, but not both, may occur before April 1, 2021.
(B)The purchase or new construction of the replacement dwelling includes the purchase of that portion of land on which the replacement building, structure, or other shelter constituting a place of abode of the claimant will be situated and that constitutes a part of the replacement dwelling.
(6)The claimant has not previously been granted, as a claimant who is over 55 years of age or severely and permanently disabled, the property tax relief provided by this section more than two times. This limitation shall not apply to claimants who are victims of wildfire or natural disaster. In order to prevent more than three claims under this section within this state per person, each county assessor shall report quarterly to the State Board of Equalization that information from claims filed and from county records as is specified by the board to be necessary to identify fully all claims under this section allowed by assessors and all claimants who have thereby received relief. The board may specify that the information include all or a part of the names and social security numbers of claimants and the identity and location of the replacement dwelling to which the claim applies. The information may be required in the form of data processing media or other media and in a format that is compatible with the recordkeeping processes of the counties and the auditing procedures of the state.
(c)(1)To receive the property tax relief under this section, a claim shall be filed within three years of the date the replacement dwelling was purchased or the new construction of the replacement dwelling was completed.
(2)A claim for transfer of taxable value under this section that is filed after the expiration of the filing period set forth in paragraph (1) shall be considered by the assessor, subject to both of the following conditions:
(A)Any base year value transfer granted pursuant to that claim shall apply, commencing with the lien date of the assessment year in which the claim is filed.
(B)The full cash value of the replacement dwelling in the assessment year described in subparagraph (A) shall be the base year value of the real property in the assessment year in which the base year value was transferred, factored to the assessment year described in subparagraph (A) for all of the following:
(i)Inflation as annually determined in accordance with paragraph (1) of subdivision (a) of Section 51.
(ii)Any subsequent new construction occurring with respect to the subject real property that does not qualify for property tax relief pursuant to the criteria set forth in subparagraphs (A) and (B) of paragraph (7) of subdivision (e).
(d)For the purposes of this section, the following terms have the following meanings:
(1)Person over 55 years of age means any person who has attained the age of 55 years or older at the time of the sale of the original property.
(2)Taxable value of the original property means its base year value, as determined in accordance with Section 110.1, with the adjustments permitted by subdivision (b) of Section 2 of Article XIII A of the California Constitution and subdivision (f) of Section 110.1, determined as of the date that the original property is sold by the claimant, or in the case where the original property has been substantially damaged or destroyed by wildfire or natural disaster and the owner does not rebuild on the original property, determined as of the date immediately before the wildfire or natural disaster.
(3)Replacement dwelling means a building, structure, or other shelter constituting a place of abode, whether real property or personal property, that is owned and occupied by a claimant as the claimants principal place of residence, and any land owned by the claimant on which the building, structure, or other shelter is situated. For purposes of this paragraph, land constituting a part of a replacement dwelling includes only that area of reasonable size that is used as a site for a residence, and land owned by the claimant includes land for which the claimant either holds a leasehold interest described in subdivision (c) of Section 61 or a land purchase contract. Each unit of a multiunit dwelling shall be considered a separate replacement dwelling. For purposes of this paragraph, area of reasonable size that is used as a site for a residence includes all land if any nonresidential uses of the property are only incidental to the use of the property as a residential site. For purposes of this paragraph, land owned by the claimant includes an ownership interest in a resident-owned mobilehome park that is assessed pursuant to subdivision (b) of Section 62.1.
(4)Original property means a building, structure, or other shelter constituting a place of abode, whether real property or personal property, that is owned and occupied by a claimant as the claimants principal place of residence, and any land owned by the claimant on which the building, structure, or other shelter is situated. For purposes of this paragraph, land constituting a part of the original property includes only that area of reasonable size that is used as a site for a residence, and land owned by the claimant includes land for which the claimant either holds a leasehold interest described in subdivision (c) of Section 61 or a land purchase contract. Each unit of a multiunit dwelling shall be considered a separate original property. For purposes of this paragraph, area of reasonable size that is used as a site for a residence includes all land if any nonresidential uses of the property are only incidental to the use of the property as a residential site. For purposes of this paragraph, land owned by the claimant includes an ownership interest in a resident-owned mobilehome park that is assessed pursuant to subdivision (b) of Section 62.1.
(5)For purposes of this section, an original dwelling or replacement dwelling shall not be considered a multiunit dwelling if: (A) there is a dwelling unit on the property, (B) the only other units on the real property are accessory dwelling units or junior accessory dwelling units, (C) any accessory dwelling units and junior accessory dwelling units are not separately alienable from the title of any other dwelling unit on the property, and (D) the claimant occupies one of the structures as their primary residence.
(6)For the purposes of this subdivision, except as otherwise provided in paragraph (7) of subdivision (e), if the replacement dwelling is, in part, purchased and, in part, newly constructed, the date the replacement dwelling is purchased or newly constructed is the date of purchase or the date of completion of construction, whichever is later.
(7)Full cash value of the replacement dwelling means its full cash value, determined in accordance with Section 110.1, as of the date on which it was purchased or new construction was completed, and after the purchase or the completion of new construction.
(8)Full cash value of the original property means either of the following, as applicable:
(A)Its new base year value, in accordance with Section 75.8, without the application of subdivision (c) of Section 2.1 of Article XIIIA of the California Constitution, plus the adjustments permitted by subdivision (b) of Section 2 of Article XIIIA and subdivision (f) of Section 110.1 for the period from the date of its sale by the claimant to the date on which the replacement dwelling was purchased or new construction was completed.
(B)In the case where the original property has been substantially damaged or destroyed by wildfire or natural disaster and the owner does not rebuild on the original property, its full cash value, as determined in accordance with Section 110, immediately before its substantial damage or destruction by wildfire or natural disaster, as determined by the assessor of the county in which the property is located, without the application of subdivision (c) of Section 2.1 of Article XIIIA of the California Constitution, plus the adjustments permitted by subdivision (b) of Section 2 of Article XIIIA of the California Constitution and subdivision (f) of Section 110.1, for the period from the date of its sale by the claimant to the date on which the replacement property was purchased or new construction was completed.
(9)Sale means any change in ownership of the original property for consideration.
(10)Claimant means any person claiming the property tax relief provided by this section.
(11)Property that is eligible for the homeowners exemption includes property that is the principal place of residence of its owner and is entitled to exemption pursuant to Section 205.5.
(12)Person means any individual, but does not include any firm, partnership, association, corporation, company, or other legal entity or organization of any kind. Person includes an individual who is the present beneficiary of a trust.
(13)Equal or lesser value means that the amount of the full cash value of a replacement dwelling does not exceed one of the following:
(A)One hundred percent of the amount of the full cash value of the original property if the replacement dwelling is purchased or newly constructed prior to the date of the sale of the original property.
(B)One hundred and five percent of the amount of the full cash value of the original property if the replacement dwelling is purchased or newly constructed within the first year following the date of the sale of the original property.
(C)One hundred and ten percent of the amount of the full cash value of the original property if the replacement dwelling is purchased or newly constructed within the second year following the date of the sale of the original property.
(14)For the purposes of this section, original property is substantially damaged or destroyed by wildfire or natural disaster if either the land or the improvements sustain physical damage amounting to more than 50 percent of either the lands or the improvements full cash value immediately before the wildfire or natural disaster. Damage includes a diminution in the value of the original property as a result of restricted access caused by the wildfire or natural disaster.
(e)(1)Upon the timely filing of a claim described in paragraph (1) of subdivision (c), the assessor shall adjust the new base year value of the replacement dwelling in conformity with this section. This adjustment shall be made as of the latest of the following dates:
(A)The date the original property is sold.
(B)The date the replacement dwelling is purchased.
(C)The date the new construction of the replacement dwelling is completed.
(2)If the full cash value of the replacement dwelling is of equal or lesser value than that of the original property, the taxable value shall be deemed to be the taxable value of the original property.
(3)If the full cash value of the replacement dwelling is of greater value than the original property, the taxable value of the replacement dwelling shall be calculated by adding the difference between the full cash value of the original property and the full cash value of the replacement dwelling to the taxable value of the original property.
(4)If the replacement dwelling is purchased or newly constructed after the transfer of the original property, taxable value of the original property also includes any inflation factor adjustments permitted by subdivision (f) of Section 110.1 for the period subsequent to the sale of the original property. The base year or years used to compute the taxable value of the original property shall be deemed to be the base year or years of any property to which that base year value is transferred pursuant to this section.
(5)Any taxes that were levied on the replacement dwelling prior to the filing of the claim on the basis of the replacement dwellings new base year value, and any allowable annual adjustments thereto, shall be canceled or refunded to the claimant to the extent that the taxes exceed the amount that would be due when determined on the basis of the adjusted new base year value.
(6)Notwithstanding Section 75.10, Chapter 3.5 (commencing with Section 75) shall be utilized for purposes of implementing this subdivision, including adjustments of the new base year value of replacement dwellings acquired prior to the sale of the original property.
(7)In the case when a claim under this section has been timely filed and granted, and new construction is performed upon the replacement dwelling subsequent to the transfer of base year value, the property tax relief provided by this section also shall apply to the replacement dwelling, as improved, and thus there shall be no reassessment upon completion of the new construction if both of the following conditions are met:
(A)The new construction is completed within two years of the date of the sale of the original property and the owner notifies the assessor in writing of completion of the new construction within six months after completion.
(B)The fair market value of the new construction on the date of completion, plus the full cash value of the replacement dwelling on the date of acquisition, is not more than the full cash value of the original property as determined pursuant to paragraph (8) of subdivision (d) for purposes of granting the original claim.
(f)A claim filed under this section is not a public document and is not subject to public inspection, except that a claim shall be available for inspection by the claimant or the claimants spouse, the claimants or the claimants spouses legal representative, the trustee of a trust in which the claimant or the claimants spouse is a present beneficiary, and the executor or administrator of the claimants or the claimants spouses estate.
(g)(1)After consultation with the California Assessors Association, the Board of Equalization shall, by emergency regulation, adopt regulations and produce claim forms and instructions necessary to implement this section and Section 2.1 of Article XIII A of the California Constitution.
(2)Any emergency regulation prescribed, adopted, or enforced pursuant to this section shall be adopted in accordance with Chapter 3.5 (commencing with Section 11340) of Part 1 of Division 3 of Title 2 of the Government Code, and, for purposes of that chapter, including Section 11349.6 of the Government Code, the adoption of the regulation is an emergency and shall be considered by the Office of Administrative Law as necessary for the immediate preservation of the public peace, health and safety, and general welfare.
SEC. 5.If the Commission on State Mandates determines that this act contains costs mandated by the state, reimbursement to local agencies and school districts for those costs shall be made pursuant to Part 7 (commencing with Section 17500) of Division 4 of Title 2 of the Government Code.
SEC. 6.Notwithstanding Section 2229 of the Revenue and Taxation Code, no appropriation is made by this act and the state shall not reimburse any local agency for any property tax revenues lost by it pursuant to this act.
SEC. 7.This act provides for a tax levy within the meaning of Article IV of the California Constitution and shall go into immediate effect.
(a)Change in ownership shall not include the following:
(1)Any transfer, on or after January 1, 1985, of a mobilehome park to a nonprofit corporation, stock cooperative corporation, limited equity stock cooperative, or other entity formed by the tenants of a mobilehome park, for the purpose of purchasing the mobilehome park, provided that, with respect to any transfer of a mobilehome park on or after January 1, 1989, subject to this paragraph, the individual tenants who were renting at least 51 percent of the spaces in the mobilehome park prior to the transfer participate in the transaction through the ownership of an aggregate of at least 51 percent of the voting stock of, or other ownership or membership interests in, the entity which acquires the park. If, on or after January 1, 1998, a park is acquired by an entity that did not attain an initial tenant participation level of at least 51 percent on the date of the transfer, the entity shall have up to one year after the date of the transfer to attain a tenant participation level of at least 51 percent. If an individual tenant notifies the county assessor of the intention to comply with the conditions set forth in the preceding sentence, the mobilehome park may not be reappraised by the assessor during that period. However, if a tenant participation level of at least 51 percent is not attained within the one-year period, the county assessor shall thereafter levy escape assessments for the mobilehome park transfer.
(2)Any transfer or transfers on or after January 1, 1985, of rental spaces in a mobilehome park to the individual tenants of the rental spaces, provided that (1) at least 51 percent of the rental spaces are purchased by individual tenants renting their spaces prior to purchase, and (2) the individual tenants of these spaces form, within one year after the first purchase of a rental space by an individual tenant, a resident organization as described in subdivision (l) of Section 50781 of the Health and Safety Code, to operate and maintain the park. If, on or after January 1, 1985, an individual tenant or tenants notify the county assessor of the intention to comply with the conditions set forth in the preceding sentence, any mobilehome park rental space that is purchased by an individual tenant in that mobilehome park during that period shall not be reappraised by the assessor. However, if all of the conditions set forth in the first sentence of this paragraph are not satisfied, the county assessor shall thereafter levy escape assessments for the spaces so transferred. This paragraph shall apply only to those rental mobilehome parks that have been in operation for five years or more.
(b)(1)If the transfer of a mobilehome park has been excluded from a change in ownership pursuant to paragraph (1) of subdivision (a) and the park has not been converted to condominium, stock cooperative ownership, or limited equity cooperative ownership, any transfer on or after January 1, 1989, of shares of the voting stock of, or other ownership or membership interests in, the entity that acquired the park in accordance with paragraph (1) of subdivision (a) shall be a change in ownership of a pro rata portion of the real property of the park unless the transfer is for the purpose of converting the park to condominium, stock cooperative ownership, or limited equity cooperative ownership or is excluded from change in ownership by Section 62, 63, 63.1, or 63.2.
(2)For the purposes of this subdivision, pro rata portion of the real property means the total real property of the mobilehome park multiplied by a fraction consisting of the number of shares of voting stock, or other ownership or membership interests, transferred divided by the total number of outstanding issued or unissued shares of voting stock of, or other ownership or membership interests in, the entity that acquired the park in accordance with paragraph (1) of subdivision (a).
(3)Any pro rata portion or portions of real property that changed ownership pursuant to this subdivision may be separately assessed as provided in Section 2188.10.
(4)(A)Notwithstanding any other provision of law, after an exclusion under subdivision (a), the assessor may not levy any escape or supplemental assessment with respect to any change in ownership of a pro rata portion of the real property of the mobilehome park that occurred between January 1, 1989, and January 1, 2002, and for which the assessor did not, prior to January 1, 2000, levy any assessments. However, commencing with the January 1, 2002, lien date, the assessor shall correct the base year value of the pro rata portion of the real property of the park to properly reflect these changes in ownership. A mobilehome park shall provide information requested by the assessor that is necessary to correct the base year value of the property for purposes of this paragraph.
(B)When an assessor corrects the base year value of the real property of the park pursuant to subparagraph (A), the assessor shall notify parks that residents may be eligible for property tax assistance programs offered by either the Controller or the Franchise Tax Board for senior citizens, or blind or disabled persons.
(C)Any outstanding taxes that were levied between January 1, 2000, and January 1, 2002, as a result of a pro rata change in ownership as described in subparagraph (A) shall be canceled. However, there shall be no refund of taxes, as so levied, that were paid prior to January 1, 2002.
(5)A mobilehome park that does not utilize recorded deeds to transfer ownership interest in the spaces or lots shall file, by February 1 of each year, a report with the county assessors office containing all of the following information:
(A)The full name and mailing address of each owner, stockholder, or holder of an ownership interest in the mobilehome park.
(B)The situs address, including space number, of each unit.
(C)The date that the ownership interest was acquired.
(D)If the unit is a manufactured home, the Department of Housing and Community Development decal number or serial number, or both, and whether the manufactured home is subject to the vehicle license fee or the local property tax.
(6)Within 30 days of a change in ownership, the new resident owner or other purchaser or transferee of a manufactured home within a mobilehome park that does not utilize recorded deeds to transfer ownership interest in the spaces or lots shall file a change in ownership statement described in either Section 480 or 480.2.
(7)Failure to comply with the reporting requirement described in paragraph (5) shall result in a penalty pursuant to Section 482.
(c)It is the intent of the Legislature that, in order to facilitate affordable conversions of mobilehome parks to tenant ownership, paragraph (1) of subdivision (a) apply to all bona fide transfers of rental mobilehome parks to tenant ownership, including, but not limited to, those parks converted to tenant ownership as a nonprofit corporation made on or after January 1, 1985.
SEC. 2.Section 62.5 of the Revenue and Taxation Code is amended to read:62.5.(a)Notwithstanding any provision of this chapter, a change in ownership shall not include a transfer of a floating home marina to a nonprofit corporation, stock cooperative corporation, limited equity stock cooperative, or other entity formed by the tenants of a floating home marina for the purpose of purchasing the floating home marina, provided that the individual tenants who were renting at least 51 percent of the berths in the floating home marina prior to the transfer participate in the transaction through the ownership of an aggregate of at least 51 percent of the voting stock of, or other ownership or membership interests in, the entity that acquires the floating home marina.
(b)(1)If the transfer of a floating home marina has been excluded from a change in ownership pursuant to subdivision (a) and the floating home marina has not been converted to condominium, stock cooperative ownership, or limited equity cooperative ownership, any transfer of shares of the voting stock of, or other ownership or membership interests in, the entity that acquired the floating home marina in accordance with subdivision (a) shall be a change in ownership of a pro rata portion of the real property of the floating home marina, unless the transfer is for the purpose of converting the floating home marina to condominium, stock cooperative ownership, or limited equity cooperative ownership, or is excluded from change in ownership by Section 62, 63, 63.1, or 63.2.
(2)A floating home marina that does not utilize recorded deeds to transfer ownership interest in the berths shall file, by February 1 of each year, a report with the county assessors office containing all of the following information:
(A)The full name and mailing address of each owner, stock holder, or holder of an ownership interest in the floating home marina.
(B)The situs address, including berth number and dock, of each unit.
(C)The date the ownership interest was acquired.
(D)The Department of Housing and Community Development decal number or serial number, or both.
(3)Within 30 days of a change in ownership, the new resident owner or other purchaser or transferee of a floating home within a floating home marina that does not utilize recorded deeds to transfer ownership interest in the berths, shall file a change in ownership statement described in either Section 480 or 480.2.
(c)For purposes of this section, both of the following shall apply:
(1)Floating home marina has the same meaning as defined in Section 800.4 of the Civil Code.
(2)Pro rata portion of the real property means the total real property of the floating home marina multiplied by a fraction consisting of the number of shares of voting stock, or other ownership or membership interests, transferred divided by the total number of outstanding issued or unissued shares of voting stock of, or other ownership or membership interests in, the entity that acquired the floating home marina in accordance with subdivision (a).
SEC. 3.Section 69.4 of the Revenue and Taxation Code is amended to read:69.4.(a)(1)Notwithstanding any other provision of law, pursuant to the authority of subdivision (i) of Section 2 of Article XIIIA of the California Constitution, the base year value of qualified contaminated property may be transferred, subject to the conditions and limitations of that subdivision and this section, to a comparable replacement property of equal or lesser value that is located in the same county and is acquired or newly constructed as a replacement for the contaminated property, pursuant to subparagraph (A) of paragraph (1) of that subdivision.
(2)The limitation in paragraph (1) requiring that the qualified contaminated property and the replacement property be located in the same county does not apply in a county in which the county board of supervisors adopts a resolution making the provisions of this section applicable to replacement properties acquired to replace qualified contaminated properties located in another county within this state. The resolution shall specify the date on and after which its provisions are applicable. The specified date may be a date earlier than the date on which the county adopts the ordinance, but no earlier than November 3, 1998.
(b)The replacement property shall be acquired or newly constructed within five years after the original property is sold or otherwise transferred.
(c)(1)Upon the sale or transfer of the original property, the assessor shall determine a new base year value for that property in accordance with subdivision (a) of Section 2 of Article XIIIA of the California Constitution and Section 110.1.
(2)This section does not apply unless the sale or transfer of the original property is a change in ownership that does either of the following:
(A)Subjects the original property to reappraisal at its current fair market value in accordance with Section 110.1 or 5803.
(B)Results in a base year value determined in accordance with this section, Section 69, Section 69.3, Section 69.5, or Section 69.6 because the property qualifies under this section, Section 69, Section 69.3, Section 69.5, or Section 69.6 as a replacement dwelling or property.
(d)Property tax relief under this section is not available for a replacement property if the owner or owners of the original property do either of the following:
(1)Receive property tax relief under Section 74.7.
(2)Sign a claim under Section 63.1 or 63.2 allowing the base year value to stay with the original property.
(e)For purposes of this section:
(1)The original property means the qualified contaminated property.
(2)Equal or lesser value means the amount of the full cash value of a replacement property that does not exceed one of the following:
(A)One hundred five percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the first year following the date of the sale of the original property.
(B)One hundred ten percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the second year following the date of the sale of the original property.
(C)One hundred fifteen percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the third year following the date of the sale of the original property.
(D)One hundred twenty percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the fourth year following the date of the sale of the original property.
(E)One hundred twenty-five percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the fifth year following the date of the sale of the original property.
For purposes of this paragraph, if the replacement property is, in part, purchased and, in part, newly constructed, the date the replacement property is acquired or newly constructed is the date of acquisition or the date of completion of construction, whichever is later.
(3)The base year value of the original property shall be the base year value of the original property as determined in accordance with Section 110.1, with the inflation factor adjustments permitted by subdivision (f) of Section 110.1. The base year value of the original property shall also include any inflation factor adjustments permitted by subdivision (f) of Section 110.1 up to the date the replacement property is acquired or newly constructed, regardless of whether the claimant continued to own the original property during this entire period. The base year or years used to compute the base year value of the original property shall be deemed to be the base year or years of any property to which that base year value is transferred pursuant to this section.
(4)Fair market value of the replacement property means the full cash value of the replacement property determined in accordance with Section 110.1 as of the date on which that property was acquired or new construction was completed. If the replacement property is, in part, acquired and, in part, newly constructed, fair market value of the replacement property means the fair market value of the land and the improvements as of the date of completion.
(5)Fair market value of the qualified contaminated property means the full cash value of the qualified contaminated property, as if that property was not contaminated, determined in accordance with Section 110.1, as of the date of its sale or transfer by the claimant.
(6)Claimant means any owner of qualified contaminated property claiming the property tax relief provided by this section.
(7)Comparable replacement property means a property that is similar in utility and function to the property that it replaces. Property is similar in function and utility if it is, or is intended to be, used in the same manner as the qualified contaminated property.
(f)(1)A claimant is not eligible for the property tax relief provided by this section unless a claim is filed within three years of the date the replacement property was purchased or the new construction of the replacement property was completed.
(2)The claimant shall provide to the assessor the following information:
(A)Proof that the claimant did not participate or acquiesce in any act or omission that rendered the real property uninhabitable or unusable, as applicable, or is related to any individual or entity that committed that act or omission.
(B)Proof that the qualified contaminated property has been designated as a toxic or environmental hazard or as an environmental cleanup site by an agency of the State of California or the federal government.
(3)The State Board of Equalization shall design the form for claiming eligibility.
(g)(1)Upon the timely filing of a claim, the assessor shall adjust the new base year value as of the date the replacement property is acquired or the date the new construction of the replacement property is completed, whichever is later.
(2)Any taxes that were levied on the replacement property prior to the filing of the claim on the basis of the replacement propertys new base year value, and any allowable annual adjustments thereto, shall be canceled or refunded to the claimant to the extent that the taxes exceed the amount that would be due when determined on the basis of the adjusted new base year value.
(3)Notwithstanding Section 75.10, Chapter 3.5 (commencing with Section 75) of Part 0.5 of Division 1 shall be utilized for purposes of implementing this subdivision, including adjustments of the new base year value of replacement properties acquired prior to the sale or transfer of the qualified contaminated property.
(h)This section applies only to replacement property that is acquired or newly constructed on or after January 1, 1995.
SEC. 4.Section 69.6 of the Revenue and Taxation Code is amended to read:69.6.Notwithstanding any other law, on and after April 1, 2021, the following shall apply:
(a)Pursuant to subdivision (b) of Section 2.1 of Article XIIIA of the California Constitution, any person over 55 years of age, any severely and permanently disabled person, or a victim of wildfire or natural disaster who resides in property that is eligible for either the homeowners exemption, under subdivision (k) of Section 3 of Article XIII of the California Constitution and Section 218, or the disabled veterans exemption, under subdivision (a) of Section 4 of Article XIII of the California Constitution and Section 205.5, may transfer, subject to the conditions and limitations provided in this section, the taxable value of that property to any replacement dwelling that is purchased or newly constructed by that person as their principal residence within two years of the sale by that person of the original property, provided that the taxable value of the original property shall not be transferred to the replacement dwelling until the original property is sold. A person shall not be allowed to transfer the taxable value of a primary residence pursuant to this section more than three times as a claimant who is over 55 years of age or severely or permanently disabled.
(b)In addition to meeting the requirements of subdivision (a), any person claiming the property tax relief provided by this section shall be eligible for that relief only if the following conditions are met:
(1)The claimant is an owner and a resident of the original property either at the time of its sale or within two years of the purchase or new construction of the replacement dwelling.
(2)The original property is eligible for the homeowners exemption or the disabled veterans exemption, as the result of the claimants ownership and occupation of the property as their principal residence, either at the time of its sale or within two years of the purchase or new construction of the replacement dwelling.
(3)At the time of the sale of the original property, the claimant is over 55 years of age, is severely and permanently disabled, or is a victim of wildfire or natural disaster.
(4)At the time of claiming the property tax relief provided by subdivision (a), the claimant is an owner of a replacement dwelling and occupies it as their principal place of residence and, as a result thereof, the property is currently eligible for the homeowners exemption or the disabled veterans exemption, or would be eligible for the exemption except that the property is already receiving the exemption because of an exemption claim filed by the previous owner.
(5)The claimant sells the original property within two years of the purchase or new construction of the replacement dwelling. For purposes of this paragraph:
(A)Either the sale of the original property or the purchase or new construction of the replacement dwelling, but not both, may occur before April 1, 2021.
(B)The purchase or new construction of the replacement dwelling includes the purchase of that portion of land on which the replacement building, structure, or other shelter constituting a place of abode of the claimant will be situated and that constitutes a part of the replacement dwelling.
(6)The claimant has not previously been granted, as a claimant who is over 55 years of age or severely and permanently disabled, the property tax relief provided by this section more than two times. This limitation shall not apply to claimants who are victims of wildfire or natural disaster. In order to prevent more than three claims under this section within this state per person, each county assessor shall report quarterly to the State Board of Equalization that information from claims filed and from county records as is specified by the board to be necessary to identify fully all claims under this section allowed by assessors and all claimants who have thereby received relief. The board may specify that the information include all or a part of the names and social security numbers of claimants and the identity and location of the replacement dwelling to which the claim applies. The information may be required in the form of data processing media or other media and in a format that is compatible with the recordkeeping processes of the counties and the auditing procedures of the state.
(c)(1)To receive the property tax relief under this section, a claim shall be filed within three years of the date the replacement dwelling was purchased or the new construction of the replacement dwelling was completed.
(2)A claim for transfer of taxable value under this section that is filed after the expiration of the filing period set forth in paragraph (1) shall be considered by the assessor, subject to both of the following conditions:
(A)Any base year value transfer granted pursuant to that claim shall apply, commencing with the lien date of the assessment year in which the claim is filed.
(B)The full cash value of the replacement dwelling in the assessment year described in subparagraph (A) shall be the base year value of the real property in the assessment year in which the base year value was transferred, factored to the assessment year described in subparagraph (A) for all of the following:
(i)Inflation as annually determined in accordance with paragraph (1) of subdivision (a) of Section 51.
(ii)Any subsequent new construction occurring with respect to the subject real property that does not qualify for property tax relief pursuant to the criteria set forth in subparagraphs (A) and (B) of paragraph (7) of subdivision (e).
(d)For the purposes of this section, the following terms have the following meanings:
(1)Person over 55 years of age means any person who has attained the age of 55 years or older at the time of the sale of the original property.
(2)Taxable value of the original property means its base year value, as determined in accordance with Section 110.1, with the adjustments permitted by subdivision (b) of Section 2 of Article XIII A of the California Constitution and subdivision (f) of Section 110.1, determined as of the date that the original property is sold by the claimant, or in the case where the original property has been substantially damaged or destroyed by wildfire or natural disaster and the owner does not rebuild on the original property, determined as of the date immediately before the wildfire or natural disaster.
(3)Replacement dwelling means a building, structure, or other shelter constituting a place of abode, whether real property or personal property, that is owned and occupied by a claimant as the claimants principal place of residence, and any land owned by the claimant on which the building, structure, or other shelter is situated. For purposes of this paragraph, land constituting a part of a replacement dwelling includes only that area of reasonable size that is used as a site for a residence, and land owned by the claimant includes land for which the claimant either holds a leasehold interest described in subdivision (c) of Section 61 or a land purchase contract. Each unit of a multiunit dwelling shall be considered a separate replacement dwelling. For purposes of this paragraph, area of reasonable size that is used as a site for a residence includes all land if any nonresidential uses of the property are only incidental to the use of the property as a residential site. For purposes of this paragraph, land owned by the claimant includes an ownership interest in a resident-owned mobilehome park that is assessed pursuant to subdivision (b) of Section 62.1.
(4)Original property means a building, structure, or other shelter constituting a place of abode, whether real property or personal property, that is owned and occupied by a claimant as the claimants principal place of residence, and any land owned by the claimant on which the building, structure, or other shelter is situated. For purposes of this paragraph, land constituting a part of the original property includes only that area of reasonable size that is used as a site for a residence, and land owned by the claimant includes land for which the claimant either holds a leasehold interest described in subdivision (c) of Section 61 or a land purchase contract. Each unit of a multiunit dwelling shall be considered a separate original property. For purposes of this paragraph, area of reasonable size that is used as a site for a residence includes all land if any nonresidential uses of the property are only incidental to the use of the property as a residential site. For purposes of this paragraph, land owned by the claimant includes an ownership interest in a resident-owned mobilehome park that is assessed pursuant to subdivision (b) of Section 62.1.
(5)For purposes of this section, an original dwelling or replacement dwelling shall not be considered a multiunit dwelling if: (A) there is a dwelling unit on the property, (B) the only other units on the real property are accessory dwelling units or junior accessory dwelling units, (C) any accessory dwelling units and junior accessory dwelling units are not separately alienable from the title of any other dwelling unit on the property, and (D) the claimant occupies one of the structures as their primary residence.
(6)For the purposes of this subdivision, except as otherwise provided in paragraph (7) of subdivision (e), if the replacement dwelling is, in part, purchased and, in part, newly constructed, the date the replacement dwelling is purchased or newly constructed is the date of purchase or the date of completion of construction, whichever is later.
(7)Full cash value of the replacement dwelling means its full cash value, determined in accordance with Section 110.1, as of the date on which it was purchased or new construction was completed, and after the purchase or the completion of new construction.
(8)Full cash value of the original property means either of the following, as applicable:
(A)Its new base year value, in accordance with Section 75.8, without the application of subdivision (c) of Section 2.1 of Article XIIIA of the California Constitution, plus the adjustments permitted by subdivision (b) of Section 2 of Article XIIIA and subdivision (f) of Section 110.1 for the period from the date of its sale by the claimant to the date on which the replacement dwelling was purchased or new construction was completed.
(B)In the case where the original property has been substantially damaged or destroyed by wildfire or natural disaster and the owner does not rebuild on the original property, its full cash value, as determined in accordance with Section 110, immediately before its substantial damage or destruction by wildfire or natural disaster, as determined by the assessor of the county in which the property is located, without the application of subdivision (c) of Section 2.1 of Article XIIIA of the California Constitution, plus the adjustments permitted by subdivision (b) of Section 2 of Article XIIIA of the California Constitution and subdivision (f) of Section 110.1, for the period from the date of its sale by the claimant to the date on which the replacement property was purchased or new construction was completed.
(9)Sale means any change in ownership of the original property for consideration.
(10)Claimant means any person claiming the property tax relief provided by this section.
(11)Property that is eligible for the homeowners exemption includes property that is the principal place of residence of its owner and is entitled to exemption pursuant to Section 205.5.
(12)Person means any individual, but does not include any firm, partnership, association, corporation, company, or other legal entity or organization of any kind. Person includes an individual who is the present beneficiary of a trust.
(13)Equal or lesser value means that the amount of the full cash value of a replacement dwelling does not exceed one of the following:
(A)One hundred percent of the amount of the full cash value of the original property if the replacement dwelling is purchased or newly constructed prior to the date of the sale of the original property.
(B)One hundred and five percent of the amount of the full cash value of the original property if the replacement dwelling is purchased or newly constructed within the first year following the date of the sale of the original property.
(C)One hundred and ten percent of the amount of the full cash value of the original property if the replacement dwelling is purchased or newly constructed within the second year following the date of the sale of the original property.
(14)For the purposes of this section, original property is substantially damaged or destroyed by wildfire or natural disaster if either the land or the improvements sustain physical damage amounting to more than 50 percent of either the lands or the improvements full cash value immediately before the wildfire or natural disaster. Damage includes a diminution in the value of the original property as a result of restricted access caused by the wildfire or natural disaster.
(e)(1)Upon the timely filing of a claim described in paragraph (1) of subdivision (c), the assessor shall adjust the new base year value of the replacement dwelling in conformity with this section. This adjustment shall be made as of the latest of the following dates:
(A)The date the original property is sold.
(B)The date the replacement dwelling is purchased.
(C)The date the new construction of the replacement dwelling is completed.
(2)If the full cash value of the replacement dwelling is of equal or lesser value than that of the original property, the taxable value shall be deemed to be the taxable value of the original property.
(3)If the full cash value of the replacement dwelling is of greater value than the original property, the taxable value of the replacement dwelling shall be calculated by adding the difference between the full cash value of the original property and the full cash value of the replacement dwelling to the taxable value of the original property.
(4)If the replacement dwelling is purchased or newly constructed after the transfer of the original property, taxable value of the original property also includes any inflation factor adjustments permitted by subdivision (f) of Section 110.1 for the period subsequent to the sale of the original property. The base year or years used to compute the taxable value of the original property shall be deemed to be the base year or years of any property to which that base year value is transferred pursuant to this section.
(5)Any taxes that were levied on the replacement dwelling prior to the filing of the claim on the basis of the replacement dwellings new base year value, and any allowable annual adjustments thereto, shall be canceled or refunded to the claimant to the extent that the taxes exceed the amount that would be due when determined on the basis of the adjusted new base year value.
(6)Notwithstanding Section 75.10, Chapter 3.5 (commencing with Section 75) shall be utilized for purposes of implementing this subdivision, including adjustments of the new base year value of replacement dwellings acquired prior to the sale of the original property.
(7)In the case when a claim under this section has been timely filed and granted, and new construction is performed upon the replacement dwelling subsequent to the transfer of base year value, the property tax relief provided by this section also shall apply to the replacement dwelling, as improved, and thus there shall be no reassessment upon completion of the new construction if both of the following conditions are met:
(A)The new construction is completed within two years of the date of the sale of the original property and the owner notifies the assessor in writing of completion of the new construction within six months after completion.
(B)The fair market value of the new construction on the date of completion, plus the full cash value of the replacement dwelling on the date of acquisition, is not more than the full cash value of the original property as determined pursuant to paragraph (8) of subdivision (d) for purposes of granting the original claim.
(f)A claim filed under this section is not a public document and is not subject to public inspection, except that a claim shall be available for inspection by the claimant or the claimants spouse, the claimants or the claimants spouses legal representative, the trustee of a trust in which the claimant or the claimants spouse is a present beneficiary, and the executor or administrator of the claimants or the claimants spouses estate.
(g)(1)After consultation with the California Assessors Association, the Board of Equalization shall, by emergency regulation, adopt regulations and produce claim forms and instructions necessary to implement this section and Section 2.1 of Article XIII A of the California Constitution.
(2)Any emergency regulation prescribed, adopted, or enforced pursuant to this section shall be adopted in accordance with Chapter 3.5 (commencing with Section 11340) of Part 1 of Division 3 of Title 2 of the Government Code, and, for purposes of that chapter, including Section 11349.6 of the Government Code, the adoption of the regulation is an emergency and shall be considered by the Office of Administrative Law as necessary for the immediate preservation of the public peace, health and safety, and general welfare.
SEC. 5.If the Commission on State Mandates determines that this act contains costs mandated by the state, reimbursement to local agencies and school districts for those costs shall be made pursuant to Part 7 (commencing with Section 17500) of Division 4 of Title 2 of the Government Code.
SEC. 6.Notwithstanding Section 2229 of the Revenue and Taxation Code, no appropriation is made by this act and the state shall not reimburse any local agency for any property tax revenues lost by it pursuant to this act.
SEC. 7.This act provides for a tax levy within the meaning of Article IV of the California Constitution and shall go into immediate effect.
(a)Change in ownership shall not include the following:
(1)Any transfer, on or after January 1, 1985, of a mobilehome park to a nonprofit corporation, stock cooperative corporation, limited equity stock cooperative, or other entity formed by the tenants of a mobilehome park, for the purpose of purchasing the mobilehome park, provided that, with respect to any transfer of a mobilehome park on or after January 1, 1989, subject to this paragraph, the individual tenants who were renting at least 51 percent of the spaces in the mobilehome park prior to the transfer participate in the transaction through the ownership of an aggregate of at least 51 percent of the voting stock of, or other ownership or membership interests in, the entity which acquires the park. If, on or after January 1, 1998, a park is acquired by an entity that did not attain an initial tenant participation level of at least 51 percent on the date of the transfer, the entity shall have up to one year after the date of the transfer to attain a tenant participation level of at least 51 percent. If an individual tenant notifies the county assessor of the intention to comply with the conditions set forth in the preceding sentence, the mobilehome park may not be reappraised by the assessor during that period. However, if a tenant participation level of at least 51 percent is not attained within the one-year period, the county assessor shall thereafter levy escape assessments for the mobilehome park transfer.
(2)Any transfer or transfers on or after January 1, 1985, of rental spaces in a mobilehome park to the individual tenants of the rental spaces, provided that (1) at least 51 percent of the rental spaces are purchased by individual tenants renting their spaces prior to purchase, and (2) the individual tenants of these spaces form, within one year after the first purchase of a rental space by an individual tenant, a resident organization as described in subdivision (l) of Section 50781 of the Health and Safety Code, to operate and maintain the park. If, on or after January 1, 1985, an individual tenant or tenants notify the county assessor of the intention to comply with the conditions set forth in the preceding sentence, any mobilehome park rental space that is purchased by an individual tenant in that mobilehome park during that period shall not be reappraised by the assessor. However, if all of the conditions set forth in the first sentence of this paragraph are not satisfied, the county assessor shall thereafter levy escape assessments for the spaces so transferred. This paragraph shall apply only to those rental mobilehome parks that have been in operation for five years or more.
(b)(1)If the transfer of a mobilehome park has been excluded from a change in ownership pursuant to paragraph (1) of subdivision (a) and the park has not been converted to condominium, stock cooperative ownership, or limited equity cooperative ownership, any transfer on or after January 1, 1989, of shares of the voting stock of, or other ownership or membership interests in, the entity that acquired the park in accordance with paragraph (1) of subdivision (a) shall be a change in ownership of a pro rata portion of the real property of the park unless the transfer is for the purpose of converting the park to condominium, stock cooperative ownership, or limited equity cooperative ownership or is excluded from change in ownership by Section 62, 63, 63.1, or 63.2.
(2)For the purposes of this subdivision, pro rata portion of the real property means the total real property of the mobilehome park multiplied by a fraction consisting of the number of shares of voting stock, or other ownership or membership interests, transferred divided by the total number of outstanding issued or unissued shares of voting stock of, or other ownership or membership interests in, the entity that acquired the park in accordance with paragraph (1) of subdivision (a).
(3)Any pro rata portion or portions of real property that changed ownership pursuant to this subdivision may be separately assessed as provided in Section 2188.10.
(4)(A)Notwithstanding any other provision of law, after an exclusion under subdivision (a), the assessor may not levy any escape or supplemental assessment with respect to any change in ownership of a pro rata portion of the real property of the mobilehome park that occurred between January 1, 1989, and January 1, 2002, and for which the assessor did not, prior to January 1, 2000, levy any assessments. However, commencing with the January 1, 2002, lien date, the assessor shall correct the base year value of the pro rata portion of the real property of the park to properly reflect these changes in ownership. A mobilehome park shall provide information requested by the assessor that is necessary to correct the base year value of the property for purposes of this paragraph.
(B)When an assessor corrects the base year value of the real property of the park pursuant to subparagraph (A), the assessor shall notify parks that residents may be eligible for property tax assistance programs offered by either the Controller or the Franchise Tax Board for senior citizens, or blind or disabled persons.
(C)Any outstanding taxes that were levied between January 1, 2000, and January 1, 2002, as a result of a pro rata change in ownership as described in subparagraph (A) shall be canceled. However, there shall be no refund of taxes, as so levied, that were paid prior to January 1, 2002.
(5)A mobilehome park that does not utilize recorded deeds to transfer ownership interest in the spaces or lots shall file, by February 1 of each year, a report with the county assessors office containing all of the following information:
(A)The full name and mailing address of each owner, stockholder, or holder of an ownership interest in the mobilehome park.
(B)The situs address, including space number, of each unit.
(C)The date that the ownership interest was acquired.
(D)If the unit is a manufactured home, the Department of Housing and Community Development decal number or serial number, or both, and whether the manufactured home is subject to the vehicle license fee or the local property tax.
(6)Within 30 days of a change in ownership, the new resident owner or other purchaser or transferee of a manufactured home within a mobilehome park that does not utilize recorded deeds to transfer ownership interest in the spaces or lots shall file a change in ownership statement described in either Section 480 or 480.2.
(7)Failure to comply with the reporting requirement described in paragraph (5) shall result in a penalty pursuant to Section 482.
(c)It is the intent of the Legislature that, in order to facilitate affordable conversions of mobilehome parks to tenant ownership, paragraph (1) of subdivision (a) apply to all bona fide transfers of rental mobilehome parks to tenant ownership, including, but not limited to, those parks converted to tenant ownership as a nonprofit corporation made on or after January 1, 1985.
SEC. 2.Section 62.5 of the Revenue and Taxation Code is amended to read:62.5.(a)Notwithstanding any provision of this chapter, a change in ownership shall not include a transfer of a floating home marina to a nonprofit corporation, stock cooperative corporation, limited equity stock cooperative, or other entity formed by the tenants of a floating home marina for the purpose of purchasing the floating home marina, provided that the individual tenants who were renting at least 51 percent of the berths in the floating home marina prior to the transfer participate in the transaction through the ownership of an aggregate of at least 51 percent of the voting stock of, or other ownership or membership interests in, the entity that acquires the floating home marina.
(b)(1)If the transfer of a floating home marina has been excluded from a change in ownership pursuant to subdivision (a) and the floating home marina has not been converted to condominium, stock cooperative ownership, or limited equity cooperative ownership, any transfer of shares of the voting stock of, or other ownership or membership interests in, the entity that acquired the floating home marina in accordance with subdivision (a) shall be a change in ownership of a pro rata portion of the real property of the floating home marina, unless the transfer is for the purpose of converting the floating home marina to condominium, stock cooperative ownership, or limited equity cooperative ownership, or is excluded from change in ownership by Section 62, 63, 63.1, or 63.2.
(2)A floating home marina that does not utilize recorded deeds to transfer ownership interest in the berths shall file, by February 1 of each year, a report with the county assessors office containing all of the following information:
(A)The full name and mailing address of each owner, stock holder, or holder of an ownership interest in the floating home marina.
(B)The situs address, including berth number and dock, of each unit.
(C)The date the ownership interest was acquired.
(D)The Department of Housing and Community Development decal number or serial number, or both.
(3)Within 30 days of a change in ownership, the new resident owner or other purchaser or transferee of a floating home within a floating home marina that does not utilize recorded deeds to transfer ownership interest in the berths, shall file a change in ownership statement described in either Section 480 or 480.2.
(c)For purposes of this section, both of the following shall apply:
(1)Floating home marina has the same meaning as defined in Section 800.4 of the Civil Code.
(2)Pro rata portion of the real property means the total real property of the floating home marina multiplied by a fraction consisting of the number of shares of voting stock, or other ownership or membership interests, transferred divided by the total number of outstanding issued or unissued shares of voting stock of, or other ownership or membership interests in, the entity that acquired the floating home marina in accordance with subdivision (a).
SEC. 3.Section 69.4 of the Revenue and Taxation Code is amended to read:69.4.(a)(1)Notwithstanding any other provision of law, pursuant to the authority of subdivision (i) of Section 2 of Article XIIIA of the California Constitution, the base year value of qualified contaminated property may be transferred, subject to the conditions and limitations of that subdivision and this section, to a comparable replacement property of equal or lesser value that is located in the same county and is acquired or newly constructed as a replacement for the contaminated property, pursuant to subparagraph (A) of paragraph (1) of that subdivision.
(2)The limitation in paragraph (1) requiring that the qualified contaminated property and the replacement property be located in the same county does not apply in a county in which the county board of supervisors adopts a resolution making the provisions of this section applicable to replacement properties acquired to replace qualified contaminated properties located in another county within this state. The resolution shall specify the date on and after which its provisions are applicable. The specified date may be a date earlier than the date on which the county adopts the ordinance, but no earlier than November 3, 1998.
(b)The replacement property shall be acquired or newly constructed within five years after the original property is sold or otherwise transferred.
(c)(1)Upon the sale or transfer of the original property, the assessor shall determine a new base year value for that property in accordance with subdivision (a) of Section 2 of Article XIIIA of the California Constitution and Section 110.1.
(2)This section does not apply unless the sale or transfer of the original property is a change in ownership that does either of the following:
(A)Subjects the original property to reappraisal at its current fair market value in accordance with Section 110.1 or 5803.
(B)Results in a base year value determined in accordance with this section, Section 69, Section 69.3, Section 69.5, or Section 69.6 because the property qualifies under this section, Section 69, Section 69.3, Section 69.5, or Section 69.6 as a replacement dwelling or property.
(d)Property tax relief under this section is not available for a replacement property if the owner or owners of the original property do either of the following:
(1)Receive property tax relief under Section 74.7.
(2)Sign a claim under Section 63.1 or 63.2 allowing the base year value to stay with the original property.
(e)For purposes of this section:
(1)The original property means the qualified contaminated property.
(2)Equal or lesser value means the amount of the full cash value of a replacement property that does not exceed one of the following:
(A)One hundred five percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the first year following the date of the sale of the original property.
(B)One hundred ten percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the second year following the date of the sale of the original property.
(C)One hundred fifteen percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the third year following the date of the sale of the original property.
(D)One hundred twenty percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the fourth year following the date of the sale of the original property.
(E)One hundred twenty-five percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the fifth year following the date of the sale of the original property.
For purposes of this paragraph, if the replacement property is, in part, purchased and, in part, newly constructed, the date the replacement property is acquired or newly constructed is the date of acquisition or the date of completion of construction, whichever is later.
(3)The base year value of the original property shall be the base year value of the original property as determined in accordance with Section 110.1, with the inflation factor adjustments permitted by subdivision (f) of Section 110.1. The base year value of the original property shall also include any inflation factor adjustments permitted by subdivision (f) of Section 110.1 up to the date the replacement property is acquired or newly constructed, regardless of whether the claimant continued to own the original property during this entire period. The base year or years used to compute the base year value of the original property shall be deemed to be the base year or years of any property to which that base year value is transferred pursuant to this section.
(4)Fair market value of the replacement property means the full cash value of the replacement property determined in accordance with Section 110.1 as of the date on which that property was acquired or new construction was completed. If the replacement property is, in part, acquired and, in part, newly constructed, fair market value of the replacement property means the fair market value of the land and the improvements as of the date of completion.
(5)Fair market value of the qualified contaminated property means the full cash value of the qualified contaminated property, as if that property was not contaminated, determined in accordance with Section 110.1, as of the date of its sale or transfer by the claimant.
(6)Claimant means any owner of qualified contaminated property claiming the property tax relief provided by this section.
(7)Comparable replacement property means a property that is similar in utility and function to the property that it replaces. Property is similar in function and utility if it is, or is intended to be, used in the same manner as the qualified contaminated property.
(f)(1)A claimant is not eligible for the property tax relief provided by this section unless a claim is filed within three years of the date the replacement property was purchased or the new construction of the replacement property was completed.
(2)The claimant shall provide to the assessor the following information:
(A)Proof that the claimant did not participate or acquiesce in any act or omission that rendered the real property uninhabitable or unusable, as applicable, or is related to any individual or entity that committed that act or omission.
(B)Proof that the qualified contaminated property has been designated as a toxic or environmental hazard or as an environmental cleanup site by an agency of the State of California or the federal government.
(3)The State Board of Equalization shall design the form for claiming eligibility.
(g)(1)Upon the timely filing of a claim, the assessor shall adjust the new base year value as of the date the replacement property is acquired or the date the new construction of the replacement property is completed, whichever is later.
(2)Any taxes that were levied on the replacement property prior to the filing of the claim on the basis of the replacement propertys new base year value, and any allowable annual adjustments thereto, shall be canceled or refunded to the claimant to the extent that the taxes exceed the amount that would be due when determined on the basis of the adjusted new base year value.
(3)Notwithstanding Section 75.10, Chapter 3.5 (commencing with Section 75) of Part 0.5 of Division 1 shall be utilized for purposes of implementing this subdivision, including adjustments of the new base year value of replacement properties acquired prior to the sale or transfer of the qualified contaminated property.
(h)This section applies only to replacement property that is acquired or newly constructed on or after January 1, 1995.
SEC. 4.Section 69.6 of the Revenue and Taxation Code is amended to read:69.6.Notwithstanding any other law, on and after April 1, 2021, the following shall apply:
(a)Pursuant to subdivision (b) of Section 2.1 of Article XIIIA of the California Constitution, any person over 55 years of age, any severely and permanently disabled person, or a victim of wildfire or natural disaster who resides in property that is eligible for either the homeowners exemption, under subdivision (k) of Section 3 of Article XIII of the California Constitution and Section 218, or the disabled veterans exemption, under subdivision (a) of Section 4 of Article XIII of the California Constitution and Section 205, 205.5, may transfer, subject to the conditions and limitations provided in this section, the taxable value of that property to any replacement dwelling that is purchased or newly constructed by that person as their principal residence within two years of the sale by that person of the original property, provided that the taxable value of the original property shall not be transferred to the replacement dwelling until the original property is sold. A person shall not be allowed to transfer the taxable value of a primary residence pursuant to this section more than three times as a claimant who is over 55 years of age or severely or permanently disabled.
(b)In addition to meeting the requirements of subdivision (a), any person claiming the property tax relief provided by this section shall be eligible for that relief only if the following conditions are met:
(1)The claimant is an owner and a resident of the original property either at the time of its sale or within two years of the purchase or new construction of the replacement dwelling.
(2)The original property is eligible for the homeowners exemption or the disabled veterans exemption, as the result of the claimants ownership and occupation of the property as their principal residence, either at the time of its sale or within two years of the purchase or new construction of the replacement dwelling.
(3)At the time of the sale of the original property, the claimant is over 55 years of age, is severely and permanently disabled, or is a victim of wildfire or natural disaster.
(4)At the time of claiming the property tax relief provided by subdivision (a), the claimant is an owner of a replacement dwelling and occupies it as their principal place of residence and, as a result thereof, the property is currently eligible for the homeowners exemption or the disabled veterans exemption, or would be eligible for the exemption except that the property is already receiving the exemption because of an exemption claim filed by the previous owner.
(5)The claimant sells the original property within two years of the purchase or new construction of the replacement dwelling. For purposes of this paragraph:
(A)Either the sale of the original property or the purchase or new construction of the replacement dwelling, but not both, may occur before April 1, 2021.
(B)The purchase or new construction of the replacement dwelling includes the purchase of that portion of land on which the replacement building, structure, or other shelter constituting a place of abode of the claimant will be situated and that constitutes a part of the replacement dwelling.
(6)The claimant has not previously been granted, as a claimant who is over 55 years of age or severely and permanently disabled, the property tax relief provided by this section more than two times. This limitation shall not apply to claimants who are victims of wildfire or natural disaster. In order to prevent more than three claims under this section within this state per person, each county assessor shall report quarterly to the State Board of Equalization that information from claims filed and from county records as is specified by the board to be necessary to identify fully all claims under this section allowed by assessors and all claimants who have thereby received relief. The board may specify that the information include all or a part of the names and social security numbers of claimants and the identity and location of the replacement dwelling to which the claim applies. The information may be required in the form of data processing media or other media and in a format that is compatible with the recordkeeping processes of the counties and the auditing procedures of the state.
(c)(1)To receive the property tax relief under this section, a claim shall be filed within three years of the date the replacement dwelling was purchased or the new construction of the replacement dwelling was completed.
(2)A claim for transfer of taxable value under this section that is filed after the expiration of the filing period set forth in paragraph (1) shall be considered by the assessor, subject to both of the following conditions:
(A)Any base year value transfer granted pursuant to that claim shall apply, commencing with the lien date of the assessment year in which the claim is filed.
(B)The full cash value of the replacement dwelling in the assessment year described in subparagraph (A) shall be the base year value of the real property in the assessment year in which the base year value was transferred, factored to the assessment year described in subparagraph (A) for all of the following:
(i)Inflation as annually determined in accordance with paragraph (1) of subdivision (a) of Section 51.
(ii)Any subsequent new construction occurring with respect to the subject real property that does not qualify for property tax relief pursuant to the criteria set forth in subparagraphs (A) and (B) of paragraph (7) of subdivision (e).
(d)For the purposes of this section, the following terms have the following meanings:
(1)Person over 55 years of age means any person who has attained the age of 55 years or older at the time of the sale of the original property.
(2)Taxable value of the original property means its base year value, as determined in accordance with Section 110.1, with the adjustments permitted by subdivision (b) of Section 2 of Article XIII A of the California Constitution and subdivision (f) of Section 110.1, determined as of the date that the original property is sold by the claimant, or in the case where the original property has been substantially damaged or destroyed by wildfire or natural disaster and the owner does not rebuild on the original property, determined as of the date immediately before the wildfire or natural disaster.
(3)Replacement dwelling means a building, structure, or other shelter constituting a place of abode, whether real property or personal property, that is owned and occupied by a claimant as the claimants principal place of residence, and any land owned by the claimant on which the building, structure, or other shelter is situated. For purposes of this paragraph, land constituting a part of a replacement dwelling includes only that area of reasonable size that is used as a site for a residence, and land owned by the claimant includes land for which the claimant either holds a leasehold interest described in subdivision (c) of Section 61 or a land purchase contract. Each unit of a multiunit dwelling shall be considered a separate replacement dwelling. For purposes of this paragraph, area of reasonable size that is used as a site for a residence includes all land if any nonresidential uses of the property are only incidental to the use of the property as a residential site. For purposes of this paragraph, land owned by the claimant includes an ownership interest in a resident-owned mobilehome park that is assessed pursuant to subdivision (b) of Section 62.1.
(4)Original property means a building, structure, or other shelter constituting a place of abode, whether real property or personal property, that is owned and occupied by a claimant as the claimants principal place of residence, and any land owned by the claimant on which the building, structure, or other shelter is situated. For purposes of this paragraph, land constituting a part of the original property includes only that area of reasonable size that is used as a site for a residence, and land owned by the claimant includes land for which the claimant either holds a leasehold interest described in subdivision (c) of Section 61 or a land purchase contract. Each unit of a multiunit dwelling shall be considered a separate original property. For purposes of this paragraph, area of reasonable size that is used as a site for a residence includes all land if any nonresidential uses of the property are only incidental to the use of the property as a residential site. For purposes of this paragraph, land owned by the claimant includes an ownership interest in a resident-owned mobilehome park that is assessed pursuant to subdivision (b) of Section 62.1.
(5)For purposes of this section, an original dwelling or replacement dwelling shall be not be considered a multiunit dwelling if: (A) there is a dwelling unit on the property, (B) the only other units on the real property are accessory dwelling units or junior accessory dwelling units, (C) any accessory dwelling units and junior accessory dwelling units are not separately alienable from the title of any other dwelling unit on the property, and (D) the claimant occupies one of the structures as their primary residence.
(6)For the purposes of this subdivision, except as otherwise provided in paragraph (7) of subdivision (e), if the replacement dwelling is, in part, purchased and, in part, newly constructed, the date the replacement dwelling is purchased or newly constructed is the date of purchase or the date of completion of construction, whichever is later.
(7)Full cash value of the replacement dwelling means its full cash value, determined in accordance with Section 110.1, as of the date on which it was purchased or new construction was completed, and after the purchase or the completion of new construction.
(8)Full cash value of the original property means either of the following, as applicable:
(A)Its new base year value, in accordance with Section 75.8, without the application of subdivision (c) of Section 2.1 of Article XIIIA of the California Constitution, plus the adjustments permitted by subdivision (b) of Section 2 of Article XIIIA and subdivision (f) of Section 110.1 for the period from the date of its sale by the claimant to the date on which the replacement dwelling was purchased or new construction was completed.
(B)In the case where the original property has been substantially damaged or destroyed by wildfire or natural disaster and the owner does not rebuild on the original property, its full cash value, as determined in accordance with Section 110, immediately before its substantial damage or destruction by wildfire or natural disaster, as determined by the assessor of the county in which the property is located, without the application of subdivision (c) of Section 2.1 of Article XIIIA of the California Constitution, plus the adjustments permitted by subdivision (b) of Section 2 of Article XIIIA of the California Constitution and subdivision (f) of Section 110.1, for the period from the date of its sale by the claimant to the date on which the replacement property was purchased or new construction was completed.
(9)Sale means any change in ownership of the original property for consideration.
(10)Claimant means any person claiming the property tax relief provided by this section.
(11)Property that is eligible for the homeowners exemption includes property that is the principal place of residence of its owner and is entitled to exemption pursuant to Section 205.5.
(12)Person means any individual, but does not include any firm, partnership, association, corporation, company, or other legal entity or organization of any kind. Person includes an individual who is the present beneficiary of a trust.
(13)Equal or lesser value means that the amount of the full cash value of a replacement dwelling does not exceed one of the following:
(A)One hundred percent of the amount of the full cash value of the original property if the replacement dwelling is purchased or newly constructed prior to the date of the sale of the original property.
(B)One hundred and five percent of the amount of the full cash value of the original property if the replacement dwelling is purchased or newly constructed within the first year following the date of the sale of the original property.
(C)One hundred and ten percent of the amount of the full cash value of the original property if the replacement dwelling is purchased or newly constructed within the second year following the date of the sale of the original property.
(14)For the purposes of this section, original property is substantially damaged or destroyed by wildfire or natural disaster if either the land or the improvements sustain physical damage amounting to more than 50 percent of either the lands or the improvements full cash value immediately before the wildfire or natural disaster. Damage includes a diminution in the value of the original property as a result of restricted access caused by the wildfire or natural disaster.
(e)(1)Upon the timely filing of a claim described in paragraph (1) of subdivision (c), the assessor shall adjust the new base year value of the replacement dwelling in conformity with this section. This adjustment shall be made as of the latest of the following dates:
(A)The date the original property is sold.
(B)The date the replacement dwelling is purchased.
(C)The date the new construction of the replacement dwelling is completed.
(2)If the full cash value of the replacement dwelling is of equal or lesser value than that of the original property, the taxable value shall be deemed to be the taxable value of the original property.
(3)If the full cash value of the replacement dwelling is of greater value than the original property, the taxable value of the replacement dwelling shall be calculated by adding the difference between the full cash value of the original property and the full cash value of the replacement dwelling to the taxable value of the original property.
(4)If the replacement dwelling is purchased or newly constructed after the transfer of the original property, taxable value of the original property also includes any inflation factor adjustments permitted by subdivision (f) of Section 110.1 for the period subsequent to the sale of the original property. The base year or years used to compute the taxable value of the original property shall be deemed to be the base year or years of any property to which that base year value is transferred pursuant to this section.
(5)Any taxes that were levied on the replacement dwelling prior to the filing of the claim on the basis of the replacement dwellings new base year value, and any allowable annual adjustments thereto, shall be canceled or refunded to the claimant to the extent that the taxes exceed the amount that would be due when determined on the basis of the adjusted new base year value.
(6)Notwithstanding Section 75.10, Chapter 3.5 (commencing with Section 75) shall be utilized for purposes of implementing this subdivision, including adjustments of the new base year value of replacement dwellings acquired prior to the sale of the original property.
(7)In the case when a claim under this section has been timely filed and granted, and new construction is performed upon the replacement dwelling subsequent to the transfer of base year value, the property tax relief provided by this section also shall apply to the replacement dwelling, as improved, and thus there shall be no reassessment upon completion of the new construction if both of the following conditions are met:
(A)The new construction is completed within two years of the date of the sale of the original property and the owner notifies the assessor in writing of completion of the new construction within six months after completion.
(B)The fair market value of the new construction on the date of completion, plus the full cash value of the replacement dwelling on the date of acquisition, is not more than the full cash value of the original property as determined pursuant to paragraph (8) of subdivision (d) for purposes of granting the original claim.
(f)A claim filed under this section is not a public document and is not subject to public inspection, except that a claim shall be available for inspection by the claimant or the claimants spouse, the claimants or the claimants spouses legal representative, the trustee of a trust in which the claimant or the claimants spouse is a present beneficiary, and the executor or administrator of the claimants or the claimants spouses estate.
(g)(1)After consultation with the California Assessors Association, the Board of Equalization shall, by emergency regulation, adopt regulations and produce claim forms and instructions necessary to implement this section and Section 2.1 of Article XIII A of the California Constitution.
(2)Any emergency regulation prescribed, adopted, or enforced pursuant to this section shall be adopted in accordance with Chapter 3.5 (commencing with Section 11340) of Part 1 of Division 3 of Title 2 of the Government Code, and, for purposes of that chapter, including Section 11349.6 of the Government Code, the adoption of the regulation is an emergency and shall be considered by the Office of Administrative Law as necessary for the immediate preservation of the public peace, health and safety, and general welfare.
SEC. 4.SEC. 5.If the Commission on State Mandates determines that this act contains costs mandated by the state, reimbursement to local agencies and school districts for those costs shall be made pursuant to Part 7 (commencing with Section 17500) of Division 4 of Title 2 of the Government Code.
SEC. 5.SEC. 6.Notwithstanding Section 2229 of the Revenue and Taxation Code, no appropriation is made by this act and the state shall not reimburse any local agency for any property tax revenues lost by it pursuant to this act.
SEC. 6.SEC. 7.This act provides for a tax levy within the meaning of Article IV of the California Constitution and shall go into immediate effect.
(a)Change in ownership shall not include the following:
(1)Any transfer, on or after January 1, 1985, of a mobilehome park to a nonprofit corporation, stock cooperative corporation, limited equity stock cooperative, or other entity formed by the tenants of a mobilehome park, for the purpose of purchasing the mobilehome park, provided that, with respect to any transfer of a mobilehome park on or after January 1, 1989, subject to this paragraph, the individual tenants who were renting at least 51 percent of the spaces in the mobilehome park prior to the transfer participate in the transaction through the ownership of an aggregate of at least 51 percent of the voting stock of, or other ownership or membership interests in, the entity which acquires the park. If, on or after January 1, 1998, a park is acquired by an entity that did not attain an initial tenant participation level of at least 51 percent on the date of the transfer, the entity shall have up to one year after the date of the transfer to attain a tenant participation level of at least 51 percent. If an individual tenant notifies the county assessor of the intention to comply with the conditions set forth in the preceding sentence, the mobilehome park may not be reappraised by the assessor during that period. However, if a tenant participation level of at least 51 percent is not attained within the one-year period, the county assessor shall thereafter levy escape assessments for the mobilehome park transfer.
(2)Any transfer or transfers on or after January 1, 1985, of rental spaces in a mobilehome park to the individual tenants of the rental spaces, provided that (1) at least 51 percent of the rental spaces are purchased by individual tenants renting their spaces prior to purchase, and (2) the individual tenants of these spaces form, within one year after the first purchase of a rental space by an individual tenant, a resident organization as described in subdivision (l) of Section 50781 of the Health and Safety Code, to operate and maintain the park. If, on or after January 1, 1985, an individual tenant or tenants notify the county assessor of the intention to comply with the conditions set forth in the preceding sentence, any mobilehome park rental space that is purchased by an individual tenant in that mobilehome park during that period shall not be reappraised by the assessor. However, if all of the conditions set forth in the first sentence of this paragraph are not satisfied, the county assessor shall thereafter levy escape assessments for the spaces so transferred. This paragraph shall apply only to those rental mobilehome parks that have been in operation for five years or more.
(b)(1)If the transfer of a mobilehome park has been excluded from a change in ownership pursuant to paragraph (1) of subdivision (a) and the park has not been converted to condominium, stock cooperative ownership, or limited equity cooperative ownership, any transfer on or after January 1, 1989, of shares of the voting stock of, or other ownership or membership interests in, the entity that acquired the park in accordance with paragraph (1) of subdivision (a) shall be a change in ownership of a pro rata portion of the real property of the park unless the transfer is for the purpose of converting the park to condominium, stock cooperative ownership, or limited equity cooperative ownership or is excluded from change in ownership by Section 62, 63, or 63.1. 63.1, or 63.2.
(2)For the purposes of this subdivision, pro rata portion of the real property means the total real property of the mobilehome park multiplied by a fraction consisting of the number of shares of voting stock, or other ownership or membership interests, transferred divided by the total number of outstanding issued or unissued shares of voting stock of, or other ownership or membership interests in, the entity that acquired the park in accordance with paragraph (1) of subdivision (a).
(3)Any pro rata portion or portions of real property that changed ownership pursuant to this subdivision may be separately assessed as provided in Section 2188.10.
(4)(A)Notwithstanding any other provision of law, after an exclusion under subdivision (a), the assessor may not levy any escape or supplemental assessment with respect to any change in ownership of a pro rata portion of the real property of the mobilehome park that occurred between January 1, 1989, and January 1, 2002, and for which the assessor did not, prior to January 1, 2000, levy any assessments. However, commencing with the January 1, 2002, lien date, the assessor shall correct the base year value of the pro rata portion of the real property of the park to properly reflect these changes in ownership. A mobilehome park shall provide information requested by the assessor that is necessary to correct the base year value of the property for purposes of this paragraph.
(B)When an assessor corrects the base year value of the real property of the park pursuant to subparagraph (A), the assessor shall notify parks that residents may be eligible for property tax assistance programs offered by either the Controller or the Franchise Tax Board for senior citizens, or blind or disabled persons.
(C)Any outstanding taxes that were levied between January 1, 2000, and January 1, 2002, as a result of a pro rata change in ownership as described in subparagraph (A) shall be canceled. However, there shall be no refund of taxes, as so levied, that were paid prior to January 1, 2002.
(5)A mobilehome park that does not utilize recorded deeds to transfer ownership interest in the spaces or lots shall file, by February 1 of each year, a report with the county assessors office containing all of the following information:
(A)The full name and mailing address of each owner, stockholder, or holder of an ownership interest in the mobilehome park.
(B)The situs address, including space number, of each unit.
(C)The date that the ownership interest was acquired.
(D)If the unit is a manufactured home, the Department of Housing and Community Development decal number or serial number, or both, and whether the manufactured home is subject to the vehicle license fee or the local property tax.
(6)Within 30 days of a change in ownership, the new resident owner or other purchaser or transferee of a manufactured home within a mobilehome park that does not utilize recorded deeds to transfer ownership interest in the spaces or lots shall file a change in ownership statement described in either Section 480 or 480.2.
(7)Failure to comply with the reporting requirement described in paragraph (5) shall result in a penalty pursuant to Section 482.
(c)It is the intent of the Legislature that, in order to facilitate affordable conversions of mobilehome parks to tenant ownership, paragraph (1) of subdivision (a) apply to all bona fide transfers of rental mobilehome parks to tenant ownership, including, but not limited to, those parks converted to tenant ownership as a nonprofit corporation made on or after January 1, 1985.
SEC. 2.Section 62.5 of the Revenue and Taxation Code is amended to read:62.5.(a)Notwithstanding any provision of this chapter, a change in ownership shall not include a transfer of a floating home marina to a nonprofit corporation, stock cooperative corporation, limited equity stock cooperative, or other entity formed by the tenants of a floating home marina for the purpose of purchasing the floating home marina, provided that the individual tenants who were renting at least 51 percent of the berths in the floating home marina prior to the transfer participate in the transaction through the ownership of an aggregate of at least 51 percent of the voting stock of, or other ownership or membership interests in, the entity that acquires the floating home marina.
(b)(1)If the transfer of a floating home marina has been excluded from a change in ownership pursuant to subdivision (a) and the floating home marina has not been converted to condominium, stock cooperative ownership, or limited equity cooperative ownership, any transfer of shares of the voting stock of, or other ownership or membership interests in, the entity that acquired the floating home marina in accordance with subdivision (a) shall be a change in ownership of a pro rata portion of the real property of the floating home marina, unless the transfer is for the purpose of converting the floating home marina to condominium, stock cooperative ownership, or limited equity cooperative ownership, or is excluded from change in ownership by Section 62, 63, or 63.1. 63.1, or 63.2.
(2)A floating home marina that does not utilize recorded deeds to transfer ownership interest in the berths shall file, by February 1 of each year, a report with the county assessors office containing all of the following information:
(A)The full name and mailing address of each owner, stock holder, or holder of an ownership interest in the floating home marina.
(B)The situs address, including berth number and dock, of each unit.
(C)The date the ownership interest was acquired.
(D)The Department of Housing and Community Development decal number or serial number, or both.
(3)Within 30 days of a change in ownership, the new resident owner or other purchaser or transferee of a floating home within a floating home marina that does not utilize recorded deeds to transfer ownership interest in the berths, shall file a change in ownership statement described in either Section 480 or 480.2.
(c)For purposes of this section, both of the following shall apply:
(1)Floating home marina has the same meaning as defined in Section 800.4 of the Civil Code.
(2)Pro rata portion of the real property means the total real property of the floating home marina multiplied by a fraction consisting of the number of shares of voting stock, or other ownership or membership interests, transferred divided by the total number of outstanding issued or unissued shares of voting stock of, or other ownership or membership interests in, the entity that acquired the floating home marina in accordance with subdivision (a).
SEC. 3.Section 69.4 of the Revenue and Taxation Code is amended to read:69.4.(a)(1)Notwithstanding any other provision of law, pursuant to the authority of subdivision (i) of Section 2 of Article XIIIA of the California Constitution, the base year value of qualified contaminated property may be transferred, subject to the conditions and limitations of that subdivision and this section, to a comparable replacement property of equal or lesser value that is located in the same county and is acquired or newly constructed as a replacement for the contaminated property, pursuant to subparagraph (A) of paragraph (1) of that subdivision.
(2)The limitation in paragraph (1) requiring that the qualified contaminated property and the replacement property be located in the same county does not apply in a county in which the county board of supervisors adopts a resolution making the provisions of this section applicable to replacement properties acquired to replace qualified contaminated properties located in another county within this state. The resolution shall specify the date on and after which its provisions are applicable. The specified date may be a date earlier than the date on which the county adopts the ordinance, but no earlier than November 3, 1998.
(b)The replacement property shall be acquired or newly constructed within five years after the original property is sold or otherwise transferred.
(c)(1)Upon the sale or transfer of the original property, the assessor shall determine a new base year value for that property in accordance with subdivision (a) of Section 2 of Article XIIIA of the California Constitution and Section 110.1.
(2)This section does not apply unless the sale or transfer of the original property is a change in ownership that does either of the following:
(A)Subjects the original property to reappraisal at its current fair market value in accordance with Section 110.1 or 5803.
(B)Results in a base year value determined in accordance with this section, Section 69, Section 69.3, or Section 69.5 69.5, or Section 69.6 because the property qualifies under this section, Section 69, Section 69.3, or Section 69.5 69.5, or Section 69.6 as a replacement dwelling or property.
(d)Property tax relief under this section is not available for a replacement property if the owner or owners of the original property do either of the following:
(1)Receive property tax relief under Section 74.7.
(2)Sign a claim under Section 63.1 or 63.2 allowing the base year value to stay with the original property.
(e)For purposes of this section:
(1)The original property means the qualified contaminated property.
(2)Equal or lesser value means the amount of the full cash value of a replacement property that does not exceed one of the following:
(A)One hundred five percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the first year following the date of the sale of the original property.
(B)One hundred ten percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the second year following the date of the sale of the original property.
(C)One hundred fifteen percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the third year following the date of the sale of the original property.
(D)One hundred twenty percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the fourth year following the date of the sale of the original property.
(E)One hundred twenty-five percent of the amount of the full cash value of the original property, if the replacement property is purchased or newly constructed within the fifth year following the date of the sale of the original property.
For purposes of this paragraph, if the replacement property is, in part, purchased and, in part, newly constructed, the date the replacement property is acquired or newly constructed is the date of acquisition or the date of completion of construction, whichever is later.
(3)The base year value of the original property shall be the base year value of the original property as determined in accordance with Section 110.1, with the inflation factor adjustments permitted by subdivision (f) of Section 110.1. The base year value of the original property shall also include any inflation factor adjustments permitted by subdivision (f) of Section 110.1 up to the date the replacement property is acquired or newly constructed, regardless of whether the claimant continued to own the original property during this entire period. The base year or years used to compute the base year value of the original property shall be deemed to be the base year or years of any property to which that base year value is transferred pursuant to this section.
(4)Fair market value of the replacement property means the full cash value of the replacement property determined in accordance with Section 110.1 as of the date on which that property was acquired or new construction was completed. If the replacement property is, in part, acquired and, in part, newly constructed, fair market value of the replacement property means the fair market value of the land and the improvements as of the date of completion.
(5)Fair market value of the qualified contaminated property means the full cash value of the qualified contaminated property, as if that property was not contaminated, determined in accordance with Section 110.1, as of the date of its sale or transfer by the claimant.
(6)Claimant means any owner of qualified contaminated property claiming the property tax relief provided by this section.
(7)Comparable replacement property means a property that is similar in utility and function to the property that it replaces. Property is similar in function and utility if it is, or is intended to be, used in the same manner as the qualified contaminated property.
(f)(1)A claimant is not eligible for the property tax relief provided by this section unless a claim is filed within three years of the date the replacement property was purchased or the new construction of the replacement property was completed.
(2)The claimant shall provide to the assessor the following information:
(A)Proof that the claimant did not participate or acquiesce in any act or omission that rendered the real property uninhabitable or unusable, as applicable, or is related to any individual or entity that committed that act or omission.
(B)Proof that the qualified contaminated property has been designated as a toxic or environmental hazard or as an environmental cleanup site by an agency of the State of California or the federal government.
(3)The State Board of Equalization shall design the form for claiming eligibility.
(g)(1)Upon the timely filing of a claim, the assessor shall adjust the new base year value as of the date the replacement property is acquired or the date the new construction of the replacement property is completed, whichever is later.
(2)Any taxes that were levied on the replacement property prior to the filing of the claim on the basis of the replacement propertys new base year value, and any allowable annual adjustments thereto, shall be canceled or refunded to the claimant to the extent that the taxes exceed the amount that would be due when determined on the basis of the adjusted new base year value.
(3)Notwithstanding Section 75.10, Chapter 3.5 (commencing with Section 75) of Part 0.5 of Division 1 shall be utilized for purposes of implementing this subdivision, including adjustments of the new base year value of replacement properties acquired prior to the sale or transfer of the qualified contaminated property.
(h)This section applies only to replacement property that is acquired or newly constructed on or after January 1, 1995.
SEC. 4.If the Commission on State Mandates determines that this act contains costs mandated by the state, reimbursement to local agencies and school districts for those costs shall be made pursuant to Part 7 (commencing with Section 17500) of Division 4 of Title 2 of the Government Code.
SEC. 5.Notwithstanding Section 2229 of the Revenue and Taxation Code, no appropriation is made by this act and the state shall not reimburse any local agency for any property tax revenues lost by it pursuant to this act.
SEC. 6.This act provides for a tax levy within the meaning of Article IV of the California Constitution and shall go into immediate effect.
|
Date
|
Status
|
|---|---|
| Oct 4, 2023 | Chaptered by Secretary of State. Chapter 312, Statutes of 2023. |
| Oct 4, 2023 | Approved by the Governor. |
| Sep 21, 2023 | Enrolled and presented to the Governor at 4 p.m. |
| Sep 14, 2023 | Assembly amendments concurred in. (Ayes 40. Noes 0. Page 2834.) Ordered to engrossing and enrolling. |
| Sep 11, 2023 | In Senate. Concurrence in Assembly amendments pending. |
| Sep 11, 2023 | Read third time. Passed. (Ayes 80. Noes 0. Page 3146.) Ordered to the Senate. |
| Sep 6, 2023 | Read third time and amended. |
| Sep 6, 2023 | Ordered to third reading. |
| Aug 28, 2023 | Ordered to third reading. |
| Aug 28, 2023 | From consent calendar on motion of Assembly Member Bryan. |
| Aug 24, 2023 | Read second time. Ordered to consent calendar. |
| Aug 23, 2023 | From committee: Do pass. Ordered to consent calendar. (Ayes 15. Noes 0.) (August 23). |
| Jun 27, 2023 | From committee: Do pass and re-refer to Com. on APPR. with recommendation: To consent calendar. (Ayes 11. Noes 0.) (June 26). Re-referred to Com. on APPR. |
| Jun 12, 2023 | June 12 hearing postponed by committee. |
| May 18, 2023 | Referred to Com. on REV. & TAX. |
| May 11, 2023 | In Assembly. Read first time. Held at Desk. |
| May 11, 2023 | Read third time. Passed. (Ayes 39. Noes 0. Page 1056.) Ordered to the Assembly. |
| May 9, 2023 | Read second time. Ordered to consent calendar. |
| May 8, 2023 | From committee: Be ordered to second reading pursuant to Senate Rule 28.8 and ordered to consent calendar. |
| May 1, 2023 | Set for hearing May 8. |
| Apr 27, 2023 | From committee: Do pass and re-refer to Com. on APPR with recommendation: To consent calendar. (Ayes 8. Noes 0. Page 939.) (April 26). Re-referred to Com. on APPR. |
| Apr 13, 2023 | Set for hearing April 26. |
| Mar 29, 2023 | Referred to Com. on GOV. & F. |
| Mar 22, 2023 | From printer. May be acted upon on or after April 21. |
| Mar 21, 2023 | Introduced. Read first time. To Com. on RLS. for assignment. To print. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Sep 14, 2023 | Unfinished Business SB890 GOV. & F. (Caballero) Concurrence | Senate Floor |
Passed |
|
| Sep 11, 2023 | SB 890 Governance and Finance Senate Third Reading By IRWIN | Assembly Floor |
Passed |
|
| Aug 23, 2023 | Do pass. To Consent Calendar. | Assembly Standing Committee on Appropriations |
Passed |
|
| Jun 26, 2023 | Do pass and be re-referred to the Committee on [Appropriations] with recommendation: To Consent Calendar | Assembly Standing Committee on Revenue and Taxation |
Passed |
|
| May 11, 2023 | Consent Calendar SB890 GOV. & F. (Caballero) | Senate Floor |
Passed |
|
| Apr 26, 2023 | Do pass, but first be re-referred to the Committee on [Appropriations] with the recommendation: To Consent Calendar | Senate Standing Committee on Governance and Finance |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| State Board of Equalization | ** Support |
SENATE RULES COMMITTEE Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | SB 890 |
UNFINISHED BUSINESS
Bill No: SB 890
Author: Committee on Governance and Finance
Amended: 9/6/23
Vote: 21
SENATE GOVERNANCE & FIN. COMMITTEE: 8-0, 4/26/23
AYES: Caballero, Seyarto, Blakespear, Dahle, Durazo, Glazer, Skinner, Wiener
SENATE APPROPRIATIONS COMMITTEE: Senate Rule 28.8
SENATE FLOOR: 39-0, 5/11/23 (Consent)
AYES: Allen, Alvarado-Gil, Archuleta, Ashby, Atkins, Becker, Blakespear, Bradford, Caballero, Cortese, Dahle, Dodd, Durazo, Eggman, Glazer, Gonzalez, Hurtado, Jones, Laird, Limón, McGuire, Menjivar, Min, Newman, Nguyen, Niello, Ochoa Bogh, Padilla, Portantino, Roth, Rubio, Seyarto, Skinner, Smallwood-Cuevas, Stern, Umberg, Wahab, Wiener, Wilk
NO VOTE RECORDED: Grove
ASSEMBLY FLOOR: 80-0, 9/11/23 - See last page for vote
SUBJECT: Property taxation: change of ownership and base year value transfers
SOURCE: State Board of Equalization
DIGEST:
This bill changes four sections of the Revenue and Taxation Code to update cross references
Assembly Amendments
correct a cross reference and a grammatical error.
ANALYSIS:
Existing law:
- Limits the maximum amount of any ad valorem tax on real property at 1% of full cash value, and directs assessors to only reappraise property thereafter if there is a change in ownership (California Constitution Article XIIIA, Section One).
- Provides an exception to change in ownership reassessment to allow certain taxpayers to transfer base year values, which allow a taxpayer to continue to pay property taxes at the factored base year value of their previous home (or other property types where the law allows) and not on the value of their newly purchased or constructed home (California Constitution, Article XIIIA, Section Two).
- Exempted, prior to enactment of Proposition 19, from change in ownership transfers of property from parents to children (ACA 2, Hanigan), which voters extended to grandchildren ten years later, so long as the grandparent is deceased (Proposition 193, 1996; ACA 17, Knowles). These exclusions applied to all inherited primary residences, regardless of value or number of transfers. They also applied to up to $1 million in aggregate value of all other types of property, such as second homes or business properties.
- Enacts the Home Protection for Seniors, Severely Disabled, Families, and Victims of Wildfire or Natural Disasters Act (ACA 11, Mullin; Proposition 19, 2020), which:
- Allowed for base year value transfers for disabled taxpayers and those over the age of 55, as well as a victim of a wildfire or other natural disaster, to properties of greater value and across county lines regardless of whether the accepting county enacted an ordinance, so long as the replacement property is purchased or constructed within two years of the date the original property is sold, or damaged or destroyed by a disaster.
- Limited the parent-child and grandparent-grandchild exclusion from change in ownership of a principal residence only if the property continues as the primary residence of the transferee, and repealed the parent-child, grandparent-grandchild exclusion for up to $1 million in aggregate value of all other types of property that is not the principal residence entirely.
- Implements Proposition 19 in statute by creating two new sections of the Revenue and Taxation Code (SB 539, Hertzberg, Chapter 427, Statutes of 2021), one each for base year value transfers and limits to the change in ownership exclusion for intergenerational transfers.
- Excludes a transfer of a mobilehome park to an entity formed by the tenants of the park provided that the individual tenants who were renting at least 51 percent of the spaces in the mobilehome park prior to the transfer participate in the transaction through the ownership of an aggregate of at least 51 percent of the voting stock of, or other ownership or membership interests in, the entity which acquires the park.
- States, once a transfer of a mobilehome park to an entity formed by tenants has been excluded from change in ownership pursuant to the section, that any subsequent transfers of ownership interests in that entity are treated as pro rata changes in ownership and are subject to reassessment unless another change in ownership exclusion in current law applies.
- Provides similar treatment to owners of property in floating home marinas as existing law does for mobile home parks.
- Directs assessors to determine a new base year value of qualified contaminated property upon change in ownership unless a different base year value transfer applies.
This bill:
- Adds references to SB 539’s new section implementing Proposition 19’s modified intergenerational transfers into sections of law directing assessors to treat subsequent transfers of ownership interests following a tenant acquisition in a mobile home parks or floating home marina treating them as pro rata changes in ownership, and subject to reassessment unless another transfer applies.
- Adds a reference to SB 539’s new base year value transfer section into a section of law directing assessors to determine a new base year value of the property upon change in ownership unless a different base year value transfer applies.
- Correct a cross reference and grammatical error in SB 539’s base year value transfer section.
FISCAL EFFECT: Appropriation: No Fiscal Com.: Yes Local: Yes
According to the Assembly Appropriations Committee:
- BOE estimates no revenue impact or state costs as a result of this bill, as this bill solely provides technical changes to reflect the passage of Proposition 19 (2020) and implementing legislation. Thus, any resulting state-mandated local program or lost property tax revenues stem from those prior measures.
SUPPORT: (Verified 9/11/23)
State Board of Equalization (source)
OPPOSITION: (Verified 9/11/23)
None received
ARGUMENTS IN SUPPORT: According to the Committee, “Recently, the BOE identified changes in law necessary to conform to the Legislature’s enactment of SB 539 (Hertzberg). This bill adds cross-references to the sections added by SB 539 into existing laws to help assessors and BOE more uniformly administer property tax law.”
ASSEMBLY FLOOR: 80-0, 9/11/23
AYES: Addis, Aguiar-Curry, Alanis, Alvarez, Arambula, Bains, Bauer-Kahan, Bennett, Berman, Boerner, Bonta, Bryan, Calderon, Juan Carrillo, Wendy Carrillo, Cervantes, Chen, Connolly, Megan Dahle, Davies, Dixon, Essayli, Flora, Mike Fong, Vince Fong, Friedman, Gabriel, Gallagher, Garcia, Gipson, Grayson, Haney, Hart, Holden, Hoover, Irwin, Jackson, Jones-Sawyer, Kalra, Lackey, Lee, Low, Lowenthal, Maienschein, Mathis, McCarty, McKinnor, Muratsuchi, Stephanie Nguyen, Ortega, Pacheco, Papan, Jim Patterson, Joe Patterson, Pellerin, Petrie-Norris, Quirk-Silva, Ramos, Rendon, Reyes, Luz Rivas, Rodriguez, Blanca Rubio, Sanchez, Santiago, Schiavo, Soria, Ta, Ting, Valencia, Villapudua, Waldron, Wallis, Ward, Weber, Wicks, Wilson, Wood, Zbur, Robert Rivas
Prepared by: Colin Grinnell / GOV. & F. / (916) 651-4119
9/11/23 19:44:46
**** END ****
SENATE THIRD READING
STR Bill Id:SB 890
Author:(Committee on Governance and Finance)
As Amended Ver:September 6, 2023
Majority vote. Urgency
SUMMARY
Provides that certain provisions governing the base year value transfer of eligible properties also apply to qualifying contaminated properties, floating home marinas, mobile homes, and mobile home parks, and makes technical corrections in existing statute.
Major Provisions
COMMENTS
Proposition 19 and SB 539: In 2020, Proposition 19 was approved by the voters. The proposition created a new section in the California Constitution allowing a base year value transfer for property owners over the age of 55, severely disabled property owners, and victims of wildfires or natural disasters if the property serves as the owner's principal place of residence. These exclusions were authorized as exclusions separate to those in existing law, which created confusion regarding the implementation of the constitutional authorization in relation to those properties that benefitted from the existing exclusions at the time. Subsequently, the Legislature enacted SB 539 (Hertzberg), Chapter 539, Statutes of 2021, which implemented the provisions of Proposition 19. SB 539, however, did not include cross-references to these newly implemented provisions in three Revenue and Taxation Code (R&TC) sections that did include such cross-references to the exclusions preceding Proposition 19. This bill would rectify that discrepancy by appropriately cross-referencing R&TC Sections 63.2 and 69.6 added by SB 539.
According to the Author
Recently, the BOE identified changes in law necessary to conform to the Legislature's enactment of SB 539 (Hertzberg). This bill adds cross-references to the sections added by SB 539 into existing laws to help assessors and BOE more uniformly administer property tax law. Committee staff circulated the proposal to affected parties before the measure was introduced. As with any other committee-authored measure, should anyone object to an item in the bill, the Committee will remove it.
Arguments in Support
None on file
Arguments in Opposition
None on file
FISCAL COMMENTS
BOE estimates no revenue impact or state costs as a result of this bill, as this bill solely provides technical changes to reflect the passage of Proposition 19 (2020) and implementing legislation. Thus, any resulting state-mandated local program or lost property tax revenues stem from those prior measures.
VOTES
SENATE FLOOR: 39-0-1
YES: Allen, Alvarado-Gil, Archuleta, Ashby, Atkins, Becker, Blakespear, Bradford, Caballero, Cortese, Dahle, Dodd, Durazo, Eggman, Glazer, Gonzalez, Hurtado, Jones, Laird, Limón, McGuire, Menjivar, Min, Newman, Nguyen, Niello, Ochoa Bogh, Padilla, Portantino, Roth, Rubio, Seyarto, Skinner, Smallwood-Cuevas, Stern, Umberg, Wahab, Wiener, Wilk
ABS, ABST OR NV: Grove
ASM REVENUE AND TAXATION: 11-0-0
YES: Irwin, Wallis, Bains, Calderon, Pacheco, Jim Patterson, Petrie-Norris, Luz Rivas, Ta, Valencia, Zbur
ASM APPROPRIATIONS: 15-0-1
YES: Holden, Megan Dahle, Bryan, Calderon, Wendy Carrillo, Dixon, Mike Fong, Hart, Mathis, Papan, Pellerin, Sanchez, Soria, Weber, Wilson
ABS, ABST OR NV: McCarty
UPDATED
VERSION: September 6, 2023
CONSULTANT: Harrison Bowlby / REV. & TAX. / (916) 319-2098 FN: 0001801
SENATE THIRD READING
STR Bill Id:SB 890
Author:(Committee on Governance and Finance)
As Introduced Ver:March 21, 2023
Majority vote. Tax levy
SUMMARY
Provides that certain provisions governing the base year value transfer of eligible properties also apply to qualifying contaminated properties, and floating home marinas, mobile homes, and mobile home parks.
Major Provisions
COMMENTS
Proposition 19 of 2020 and SB 539 (Hertzberg), Chapter 539, Statutes of 2021. In 2020, Proposition 19 was approved by the voters. The proposition created a new section in the California Constitution allowing a base year value transfer for property owners over the age of 55, severely disabled property owners, and victims of wildfires or natural disasters if the property serves as the owner's principal place of residence. These exclusions were authorized as exclusions separate to those in existing law, which created confusion regarding the implementation of the constitutional authorization in relation to those properties that benefitted from the existing exclusions at the time. Subsequently, the Legislature enacted SB 539 in 2021, which implemented the provisions of Proposition 19. SB 539, however, did not include cross-references to these newly implemented provisions in three Revenue and Taxation Code (R&TC) sections that did include such cross-references to the exclusions preceding Proposition 19. This bill would rectify that discrepancy by appropriately cross-referencing R&TC Sections 63.2 and 69.6 added by SB 539.
According to the Author
Recently, the [Board of Equalization (BOE)] identified changes in law necessary to conform to the Legislature's enactment of SB 539 (Hertzberg). This bill adds cross-references to the sections added by SB 539 into existing laws to help assessors and BOE more uniformly administer property tax law. Committee staff circulated the proposal to affected parties before the measure was introduced. As with any other committee-authored measure, should anyone object to an item in the bill, the Committee will remove it.
Arguments in Support
None on file
Arguments in Opposition
None on file
FISCAL COMMENTS
According to the Assembly Appropriations Committee, BOE estimates no revenue impact or state costs as a result of this bill, as this bill solely provides technical changes to reflect the passage of Proposition 19 (2020) and implementing legislation. Thus, any resulting state-mandated local program or lost property tax revenues stem from those prior measures.
VOTES
SENATE FLOOR: 39-0-1
YES: Allen, Alvarado-Gil, Archuleta, Ashby, Atkins, Becker, Blakespear, Bradford, Caballero, Cortese, Dahle, Dodd, Durazo, Eggman, Glazer, Gonzalez, Hurtado, Jones, Laird, Limón, McGuire, Menjivar, Min, Newman, Nguyen, Niello, Ochoa Bogh, Padilla, Portantino, Roth, Rubio, Seyarto, Skinner, Smallwood-Cuevas, Stern, Umberg, Wahab, Wiener, Wilk
ABS, ABST OR NV: Grove
ASM REVENUE AND TAXATION: 11-0-0
YES: Irwin, Wallis, Bains, Calderon, Pacheco, Jim Patterson, Petrie-Norris, Luz Rivas, Ta, Valencia, Zbur
ASM APPROPRIATIONS: 15-0-1
YES: Holden, Megan Dahle, Bryan, Calderon, Wendy Carrillo, Dixon, Mike Fong, Hart, Mathis, Papan, Pellerin, Sanchez, Soria, Weber, Wilson
ABS, ABST OR NV: McCarty
UPDATED
VERSION: March 21, 2023
CONSULTANT: Harrison Bowlby / REV. & TAX. / (916) 319-2098 FN: 0001374
Date of Hearing: August 23, 2023
ASSEMBLY COMMITTEE ON APPROPRIATIONS
Chris Holden, Chair
SBPCA Bill Id:SB 890
Author:(Committee on Governance and Finance) – As Introduced Ver:March 21, 2023
Policy Committee: | Revenue and Taxation | Vote: | 11 - 0 |
|
| ||
|
|
Urgency: No State Mandated Local Program: Yes Reimbursable: No
SUMMARY:
This bill clarifies the change in ownership exclusions relating to intergenerational property transfer and base-year value transfer for a homeowner age 55 or older, severely disabled individual, or victim of a wildfire or natural disaster apply to mobile home parks, floating home marinas, and qualified contaminated property.
FISCAL EFFECT:
BOE estimates no revenue impact or state costs as a result of this bill, as this bill solely provides technical changes to reflect the passage of Proposition 19 (2020) and implementing legislation. Thus, any resulting state-mandated local program or lost property tax revenues stem from those prior measures.
COMMENTS:
- Purpose. According to the author:
Recently, the BOE identified changes in law necessary to conform to the Legislature’s enactment of SB 539 (Hertzberg). This bill adds cross-references to the sections added by SB 539 into existing laws to help assessors and BOE more uniformly administer property tax law. Committee staff circulated the proposal to affected parties before the measure was introduced. As with any other committee-authored measure, should anyone object to an item in the bill, the Committee will remove it.
- Intergenerational Property Transfer and Base-year Value Transfer Exclusions. Prior to Proposition 19, the transfer of a principal residence between parents and children (and grandparents and grandchildren) and the first $1 million of the base-year value of all real property other than a principal residence were excluded from reassessment. Operative February 16, 2021, Proposition 19 replaced the existing exclusion with a new exclusion applicable only to transfers of a family home (essentially, a principal residence), including a family farm, between parents and children (and grandparents and grandchildren) with a value of up to $1 million. If the fair market value of the family home is greater than $ 1 million, the amount in excess must be added to the property’s taxable value. SB 539 (Hertzberg), Chapter 427, Statutes of 2021, clarified key definitions and specified timelines for claiming the exclusion.
Prior to Proposition 19, individuals who were over age 55 or severely disabled or whose property was destroyed in a Governor-proclaimed state of emergency were able to transfer their base-year value from one home to another of equal or lesser value within specified counties, providing an exclusion from reassessment. Operative April 1, 2021, Proposition 19 allows such property owners to transfer their base-year value to a replacement home of greater value, anywhere in the state. If the replacement home is of greater value, the difference in market value between the original home and replacement home must be added to the base-year value. SB 539 clarified key definitions and specified timelines for claiming the relief.
As noted in the Assembly Revenue and Taxation Committee’s analysis of this bill:
SB 539, however, did not include cross-references to these newly implemented [exclusions] in [three Revenue and Taxation Code (R&TC)] sections that did include such cross-references to the exclusions preceding Proposition 19. This bill would rectify that discrepancy by appropriately cross-referencing R&TC Sections 63.2 and 69.6 added by SB 539.
Analysis Prepared by: Irene Ho / APPR. / (916) 319-2081
Date of Hearing: June 26, 2023
ASSEMBLY COMMITTEE ON REVENUE AND TAXATION
Jacqui Irwin, Chair
SBPCA Bill Id:SB 890
Author:(Committee on Governance and Finance) – As Introduced Ver:March 21, 2023
Majority vote. Tax levy. Fiscal committee.
SENATE VOTE: 39-0
SUBJECT: Property taxation: change of ownership and base year value transfers
SUMMARY: Clarifies that certain change in ownership exclusions apply to qualifying properties. Specifically, this bill:
- Provides that floating home marinas, mobilehomes, and mobilehome parks that have benefitted from an existing change in ownership exclusion as a result of transferring the base year value to a specified resident-controlled entity are not subject to a pro-rated property tax if an owner subsequently transfers that property, or ownership shares in the resident-controlled entity, to their child or grandchild pursuant to existing law.
- Prohibits a county assessor from reassessing a qualified contaminated property that has benefitted from a base year value transfer to a replacement property if the qualified contaminated property is eligible to receive a base year value transfer from a separate, third property because the third property's owner is over the age of 55, is severely or permanently disabled, or the property was damaged or destroyed by natural disaster or wildfire, as specified.
- Prohibits the owner of a qualified contaminated property from transferring the base year value to a separate property if the owner chooses to keep the base year value of the original qualified contaminated property with that property because the property owner uses that property as their principal residence and is transferring the property to their child or grandchild, pursuant to existing law, who will maintain the original property as their principal residence.
EXISTING LAW:
- Provides that all property is taxable unless otherwise provided by the California Constitution or the laws of the United States. (California Constitution, Article XIII, Section 1.)
- Limits the maximum amount of ad valorem property taxation on real property to 1% of the full cash value of the property. Generally, the Constitution restricts the full cash value of a property to the assessed value upon a change of ownership in, or new construction on, the property. This is referred to as the base year value, which may be adjusted upwards for inflation by no more than 2% annually. This adjustment is referred to as the factored base year value. (California Constitution, Article XIIIA, Section 1 and 2.)
- Authorizes various exclusions from a reassessment resulting from a change in ownership, including the transfer of the factored base year value of a property owner's principal place of residence to a replacement principal place of residence, as specified, if the property owner is over the age of 55, is severely disabled, or is the victim of a wildfire or natural disaster, and the transfer of the factored base year value of a principal place of residence being transferred to the owner's children or grandchildren if that property will serve as the transferee's principal place of residence, among other limitations. (California Constitution, Article XIIIA, Section 2.1, and Revenue and Taxation Code (R&TC) Sections 63.2 and 69.6, respectively.)
- Authorizes the transfer of the base year value of floating home marinas, mobilehome parks, or rental spaces in a mobile home park if the ownership in the property is being transferred to a resident-controlled entity, as defined. The subsequent transfer of any ownership stake in that resident-controlled entity is subject to a pro-rated property tax in proportion to that ownership stake, unless the property is eligible for specified exclusions from a change in ownership or new construction. (R&TC Sections 62.1 and 62.5.)
- Authorizes the transfer of the base year value of a qualifying contaminated property to a replacement property, if the replacement property is acquired or new construction completed within five years of the sale or transfer of the qualified contaminated property. Upon transferring the base year value, the qualified contaminated property must be reassessed to its fair market value, unless the new owner benefits from a specified change in ownership exclusion. (California Constitution, Article XIIIA, Section 2, subdivision (i) and R&TC Section 69.4.)
FISCAL EFFECT: The State Board of Equalization estimates no revenue impact resulting from this bill.
COMMENTS:
- The author has provided the following statement in support of this bill:
Recently, the BOE identified changes in law necessary to conform to the Legislature's enactment of SB 539 (Hertzberg). This bill adds cross-references to the sections added by SB 539 into existing laws to help assessors and BOE more uniformly administer property tax law. Committee staff circulated the proposal to affected parties before the measure was introduced. As with any other committee-authored measure, should anyone object to an item in the bill, the Committee will remove it.
- Committee Staff Comments:
- Proposition 19 and SB 539: In 2020, Proposition 19 was approved by the voters. The proposition created a new section in the California Constitution allowing a base year value transfer for property owners over the age of 55, severely disabled property owners, and victims of wildfires or natural disasters if the property serves as the owner's principal place of residence. These exclusions were authorized as exclusions separate to those in existing law, which created confusion regarding the implementation of the constitutional authorization in relation to those properties that benefitted from the existing exclusions at the time. Subsequently, the Legislature enacted SB 539 (Hertzberg), Chapter 539, Statutes of 2021, which implemented the provisions of Proposition 19. SB 539, however, did not include cross-references to these newly implemented provisions in R&TC three sections that did include such cross-references to the exclusions preceding Proposition 19. This bill would rectify that discrepancy by appropriately cross-referencing R&TC Sections 63.2 and 69.6 added by SB 539.
REGISTERED SUPPORT / OPPOSITION:
Support
None on file
Opposition
None on file
Analysis Prepared by: Harrison Bowlby / REV. & TAX. / (916) 319-2098
SENATE RULES COMMITTEE Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | SB 890 |
CONSENT
Bill No: SB 890
Author: Committee on Governance and Finance
Introduced: 3/21/23
Vote: 21- Urgency
SENATE GOVERNANCE & FIN. COMMITTEE: 8-0, 4/26/23
AYES: Caballero, Seyarto, Blakespear, Dahle, Durazo, Glazer, Skinner, Wiener
SENATE APPROPRIATIONS COMMITTEE: Senate Rule 28.8
SUBJECT: Property taxation: change of ownership and base year value transfers
SOURCE: State Board of Equalization
DIGEST:
This bill changes three sections of the Revenue and Taxation Code to update cross references.
ANALYSIS:
Existing law:
- Limits the maximum amount of any ad valorem tax on real property at 1% of full cash value, and directs assessors to only reappraise property thereafter if there is a change in ownership (California Constitution Article XIIIA, Section One).
- Provides an exception to change in ownership reassessment to allow certain taxpayers to transfer base year values, which allow a taxpayer to continue to pay property taxes at the factored base year value of their previous home (or other property types where the law allows) and not on the value of their newly purchased or constructed home (California Constitution, Article XIIIA, Section Two).
- Exempted, prior to enactment of Proposition 19, from change in ownership transfers of property from parents to children (ACA 2, Hanigan), which voters extended to grandchildren ten years later, so long as the grandparent is deceased (Proposition 193, 1996; ACA 17, Knowles). These exclusions applied to all inherited primary residences, regardless of value or number of transfers. They also applied to up to $1 million in aggregate value of all other types of property, such as second homes or business properties.
- Enacts the Home Protection for Seniors, Severely Disabled, Families, and Victims of Wildfire or Natural Disasters Act (ACA 11, Mullin; Proposition 19, 2020), which:
- Allowed for base year value transfers for disabled taxpayers and those over the age of 55, as well as a victim of a wildfire or other natural disaster, to properties of greater value and across county lines regardless of whether the accepting county enacted an ordinance, so long as the replacement property is purchased or constructed within two years of the date the original property is sold, or damaged or destroyed by a disaster.
- Limited the parent-child and grandparent-grandchild exclusion from change in ownership of a principal residence only if the property continues as the primary residence of the transferee, and repealed the parent-child, grandparent-grandchild exclusion for up to $1 million in aggregate value of all other types of property that is not the principal residence entirely.
- Implements Proposition 19 in statute by creating two new sections of the Revenue and Taxation Code (SB 539, Hertzberg, Chapter 427, Statutes of 2021).
- Excludes a transfer of a mobilehome park to an entity formed by the tenants of the park provided that the individual tenants who were renting at least 51 percent of the spaces in the mobilehome park prior to the transfer participate in the transaction through the ownership of an aggregate of at least 51 percent of the voting stock of, or other ownership or membership interests in, the entity which acquires the park.
- States, once a transfer of a mobilehome park to an entity formed by tenants has been excluded from change in ownership pursuant to the section, that any subsequent transfers of ownership interests in that entity are treated as pro rata changes in ownership and are subject to reassessment unless another change in ownership exclusion in current law applies.
- Provides similar treatment to owners of property in floating home marinas as existing law does for mobile home parks.
- Directs assessors to determine a new base year value of qualified contaminated property upon change in ownership unless a different base year value transfer applies.
This bill:
- Adds references to SB 539’s new section implementing Proposition 19’s modified intergenerational transfers into sections of law directing assessors to treat subsequent transfers of ownership interests following a tenant acquisition in a mobile home parks or floating home marina treating them as pro rata changes in ownership, and subject to reassessment unless another transfer applies.
- Adds a reference to SB 539’s new base year value transfer section into a section of law directing assessors to determine a new base year value of the property upon change in ownership unless a different base year value transfer applies.
FISCAL EFFECT: Appropriation: No Fiscal Com.: Yes Local: Yes
SUPPORT: (Verified 5/9/23)
State Board of Equalization (source)
OPPOSITION: (Verified 5/9/23)
None received
ARGUMENTS IN SUPPORT: According to the Committee, “Recently, the BOE identified changes in law necessary to conform to the Legislature’s enactment of SB 539 (Hertzberg). This bill adds cross-references to the sections added by SB 539 into existing laws to help assessors and BOE more uniformly administer property tax law.”
Prepared by: Colin Grinnell / GOV. & F. / (916) 651-4119
5/10/23 15:35:09
**** END ****
SENATE COMMITTEE ON GOVERNANCE AND FINANCE
Senator Anna M. Caballero, Chair
2023 - 2024 Regular
Bill No: | SB 890 | Hearing Date: | 4/26/23 |
Author: | Committee on Governance and Finance | Tax Levy: | Yes |
Version: | 3/21/23 | Fiscal: | Yes |
Consultant: | Grinnell | ||
Property taxation: change of ownership and base year value transfers
Makes conforming changes to three sections of the Revenue and Taxation Code to update cross references to reflect the enactment of SB 539 (Hertzberg, 2021).
Background and Proposed Law
Base year value transfers. State law implementing Proposition 13 (1978) generally sets a property’s value as its sales price when purchased or, when there is no sales price, at its fair market value when ownership changes (base year value). Thereafter, the law requires an annual inflation adjustment to that value that cannot exceed 2% (factored base year value). Base year value transfers allow a taxpayer to continue to pay property taxes at the factored base year value of their previous home (or other property types where the law allows) and not on the value of their newly purchased or constructed home, often resulting in tax savings. Before 2020, voters had approved several forms of base year value transfers as exceptions to Proposition 13’s requirement to reassess property upon change of ownership, including Proposition 1 (1998), which allows a base year value transfer for qualified contaminated property to a replacement or newly constructed property of equal or lesser value than the value of the contaminated property if that property was not contaminated.
The Legislature also enacted statutory changes implementing each of these constitutional base year value transfers. The sections of law set forth the specific eligibility requirements for the transfers, including filing a claim with the assessor, as well as specific procedures for calculating the base year value of the replacement property.
In 2020, the Legislature placed on the ballot, and voters approved as Proposition 19, the Home Protection for Seniors, Severely Disabled, Families, and Victims of Wildfire or Natural Disasters Act (ACA 11, Mullin). Among other provisions, the Act created a new section of the California Constitution to allow base year value transfers for disabled taxpayers and those over the age of 55, as well as a victim of a wildfire or other natural disaster. Proposition 19 allowed taxpayers to transfer base year values to properties of greater value and across county lines regardless of whether the accepting county enacted an ordinance, so long as the replacement property is purchased or constructed within two years of the date the original property is sold, or damaged or destroyed by a disaster.
Change in ownership exclusions. The Legislature enacted, and voters approved, two changes in ownership exclusions for transfers of property from one generation to the next. Proposition 58 (1986) exempted from change in ownership transfers of property from parents to children (ACA 2, Hanigan), which voters extended to grandchildren ten years later, so long as the grandparent is deceased (Proposition 193, 1996; ACA 17, Knowles). These exclusions applied to all inherited primary residences, regardless of value or number of transfers. They also applied to up to $1 million in aggregate value of all other types of property, such as second homes or business properties.
To offset potential property tax revenue losses resulting from its new base year value transfer benefits, Proposition 19 created a new section of the California Constitution to limit the parent-child and grandparent-grandchild exclusion from change in ownership of a principal residence only if the property continues as the primary residence of the transferee. The Act further repeals the parent-child, grandparent-grandchild exclusion for up to $1 million in aggregate value of all other types of property that is not the principal residence entirely.
SB 539 (Hertzberg). To implement Proposition 19, the Legislature enacted SB 539 (Hertzberg, 2021), which added new R&T §69.6, similar to provisions in current law for base year value transfers, that provides statutory detail for taxpayers to claim base year value transfers under Proposition 19. SB 539 also added new R&T §63.2 to implement Proposition 19’s limitations on parent-child/grandparent-grandchild change in ownership exclusions.
Mobile home parks. R&T §62.1 excludes a transfer of a mobilehome park to an entity formed by the tenants of the park provided that the individual tenants who were renting at least 51 percent of the spaces in the mobilehome park prior to the transfer participate in the transaction through the ownership of an aggregate of at least 51 percent of the voting stock of, or other ownership or membership interests in, the entity which acquires the park. Once a transfer of a mobilehome park to an entity formed by tenants has been excluded from change in ownership pursuant to the section, any subsequent transfers of ownership interests in that entity are treated as pro rata changes in ownership and are subject to reassessment unless another change in ownership exclusion in current law applies. However, R&T §62.1 does not include a reference to R&T §63.2 added by SB 539. The bill adds the reference. The bill similarly updates the reference in R&T §62.5, which provides similar treatment to owners of property in floating home marinas as R&T §62.1 does for mobile home parks.
Qualified contaminated property. As noted above, Proposition 1 allows a base year value transfer for qualified contaminated property to a replacement or newly constructed property of equal or lesser value than the value of the contaminated property if that property was not contaminated. R&T 69.4 implements this section, including direction to assessors to determine a new base year value of the property upon change in ownership unless a different base year value transfer applies. However, R&T 69.4 does not include a reference to R&T 69.6 added by SB 539. The bill updates the reference.
State Revenue Impact
Pending.
Comments
1. Purpose of the bill. Recently, the BOE identified changes in law necessary to conform to the Legislature’s enactment of SB 539 (Hertzberg). This bill adds cross-references to the sections added by SB 539 into existing laws to help assessors and BOE more uniformly administer property tax law. Committee staff circulated the proposal to affected parties before the measure was introduced. As with any other committee-authored measure, should anyone object to an item in the bill, the Committee will remove it.
Support and Opposition
(4/21/23)
Support: None submitted.
Opposition: None submitted.
-- END --
Discussed in Hearing
View Older Hearings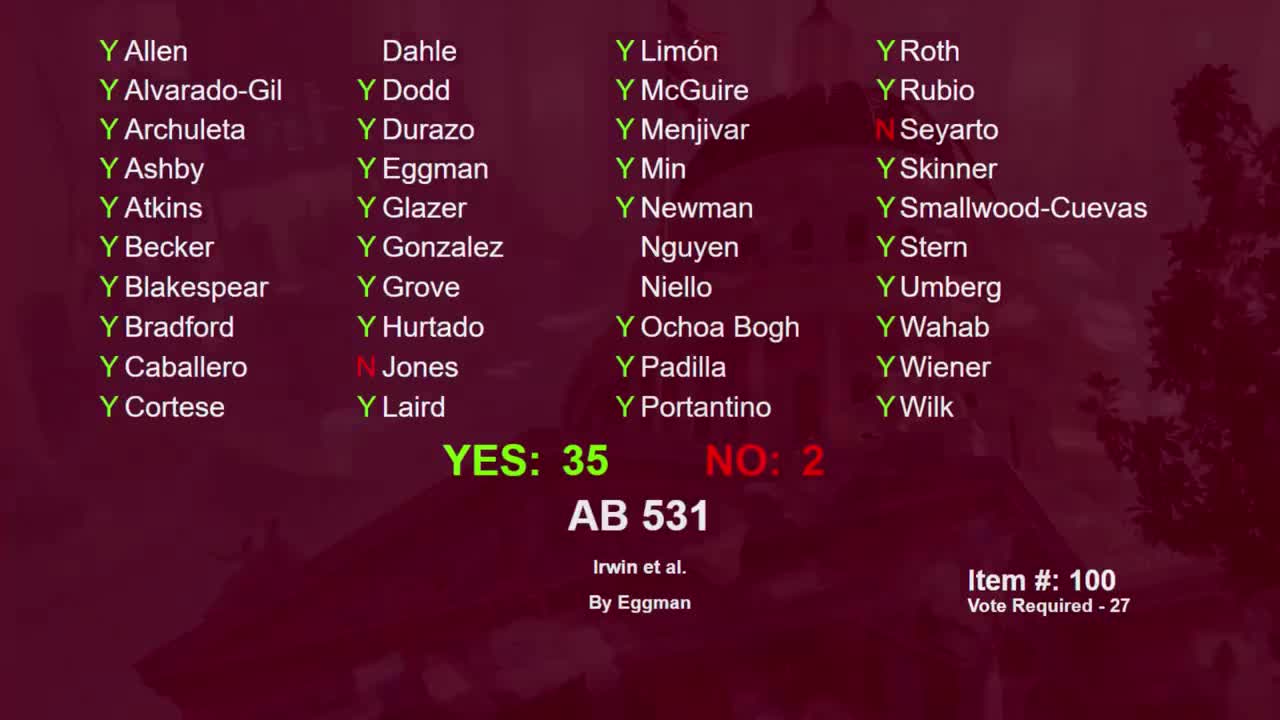
Bill Author
Bill Co-Author(s):