SB 863: Taxation.
- Session Year: 2025-2026
- House: Senate
- Latest Version Date: 2025-10-07
Current Status:
Passed
(2025-10-07: Chaptered by Secretary of State. Chapter 462, Statutes of 2025.)
Introduced
In Committee
Awaiting First Chamber Vote
Passed First Chamber
In Committee
Awaiting Second Chamber Vote
Passed Second Chamber
Enacted
What does this bill do?
This bill changes tax rules for payments, tax‑defaulted property sales, local sales taxes, film tax credits, and cigarette taxes. It counts payments as received when the county treasurer‑tax collector actually gets them if no other delivery date applies; lets collectors lower auction minimums when redemption totals fall because a special assessment or direct charge is reduced; limits when local transactions‑and‑use taxes can start after the election; allows certain motion‑picture credits from disregarded single‑member LLCs (LLCs treated as part of their owner) to be assigned to an owner or affiliate; and replaces State Board of Equalization references with CDTFA for cigarette tax enforcement.
The summary is provided by generative AI which can make mistakes. For original language, please view the details in the table below.
(1)Existing property tax law specifies the date on which a remittance to a taxing agency is deemed to be received depending on the method of delivery, as provided, including for items mailed with an official postmark.
This bill would require, in the absence of any specified dates, the remittance to be deemed received on the date the remittance is received by the county treasurer-tax collector, except as provided.
(2)Existing property tax law authorizes a tax collector to sell property that has become tax defaulted, as provided, and has not been redeemed. Existing law requires the tax collector to sell the property at a public auction to the highest bidder and prohibits the tax collector from accepting an offer less than the minimum price approved, as provided, except that the tax collector may reduce the minimum price if there has been a partial redemption or partial cancellation, as specified.
This bill would also authorize a tax collector to reduce the minimum price where the minimum necessary to redeem is decreased due to the removal or reduction of defaulted taxes resulting from the removal or reduction of a special assessment or a direct charge against the property.
(3)The Transactions and Use Tax Law authorizes various local governmental entities, subject to certain limitations and approval requirements, to levy transactions and use taxes as special taxes in accordance with the procedures and requirements set forth in that law. The Transactions and Use Tax Law prohibits an ordinance adopted under its provisions from becoming operative on other than the first day of a calendar quarter, or prior to the first day of the first calendar quarter, commencing more than 110 days after the adoption of the ordinance.
This bill would instead prohibit an ordinance adopted under the Transactions and Use Tax Law from becoming operative on other than the first day of a calendar quarter, or prior to the first day of the first calendar quarter, commencing more than 110 days after the election on the ordinance proposing the tax.
(4)The Personal Income Tax Law and the Corporation Tax Law allow various credits against the taxes imposed by those laws, including various motion picture credits, commonly referred to as motion picture credit 1.0, 2.0, 3.0, and 4.0, and the certified studio credit, to be allocated by the California Film Commission in differing amounts equal to specified percentages of the qualified expenditures of a qualified motion picture in this state. Existing law allows a qualified taxpayer, if a motion picture credit exceeds the taxpayers tax liability, to elect to assign a portion of the credit to one or more affiliated corporations for each taxable year in which the credit is allowed, as specified. AB 1138 (Chapter 27 of the Statutes of 2025), effective July 3, 2025, among other things, for purposes of the motion picture credit 3.0 and 4.0 and for purposes of the certified studio credit, expands the definition of a qualified taxpayer to include a single member limited liability company that is disregarded for tax purposes. AB 1138 prohibits a motion picture credit 1.0 and 2.0 or certified studio credit generated by a disregarded single member limited liability company from being ineligible for certain reasons for assignment to a corporation that, directly or indirectly, owns the disregarded single member limited liability company, or to an affiliated corporation of that corporation.
This bill would additionally prohibit a motion picture credit 3.0 generated by a disregarded single member limited liability company from being ineligible for those same reasons for assignment to a corporation that, directly or indirectly, owns the disregarded single member limited liability company, or to an affiliated corporation of that corporation.
(5)The California Constitution provides for the establishment of the State Board of Equalization, which, before July 1, 2017, had primary responsibility for most of the states duties, powers, and responsibilities regarding the administration of taxes and fees. Existing law, on July 1, 2017, transferred to the California Department of Tax and Fee Administration various duties, powers, and responsibilities of the State Board of Equalization, including enforcing specified licensing and tax provisions of the Cigarette and Tobacco Products Tax Law and providing information to the Attorney General relative to a sellers failure or attempt to comply with specified provisions of federal law.
This bill would change references in these provisions of the Cigarette and Tobacco Products Tax Law from the State Board of Equalization or board to the California Department of Tax and Fee Administration or department, as applicable, to reflect the transfer of the boards duties, powers, and responsibilities to the department.
(1)Existing property tax law specifies the date on which a remittance to a taxing agency is deemed to be received depending on the method of delivery, as provided, including for items mailed with an official postmark.
This bill would require, in the absence of any specified dates, the remittance to be deemed received on the date the remittance is received by the county treasurer-tax collector, except as provided.
(2)Existing property tax law authorizes a tax collector to sell property that has become tax defaulted, as provided, and has not been redeemed. Existing law requires the tax collector to sell the property at a public auction to the highest bidder and prohibits the tax collector from accepting an offer less than the minimum price approved, as provided, except that the tax collector may reduce the minimum price if there has been a partial redemption or partial cancellation, as specified.
This bill would also authorize a tax collector to reduce the minimum price where the minimum necessary to redeem is decreased due to the removal or reduction of defaulted taxes resulting from the removal or reduction of a special assessment or a direct charge against the property.
(3)The Transactions and Use Tax Law authorizes various local governmental entities, subject to certain limitations and approval requirements, to levy transactions and use taxes as special taxes in accordance with the procedures and requirements set forth in that law. The Transactions and Use Tax Law prohibits an ordinance adopted under its provisions from becoming operative on other than the first day of a calendar quarter, or prior to the first day of the first calendar quarter, commencing more than 110 days after the adoption of the ordinance.
This bill would instead prohibit an ordinance adopted under the Transactions and Use Tax Law from becoming operative on other than the first day of a calendar quarter, or prior to the first day of the first calendar quarter, commencing more than 110 days after the election on the ordinance proposing the tax.
(4)The Personal Income Tax Law and the Corporation Tax Law allow various credits against the taxes imposed by those laws, including various motion picture credits, commonly referred to as motion picture credit 1.0, 2.0, 3.0, and 4.0, and the certified studio credit, to be allocated by the California Film Commission in differing amounts equal to specified percentages of the qualified expenditures of a qualified motion picture in this state. Existing law allows a qualified taxpayer, if a motion picture credit exceeds the taxpayers tax liability, to elect to assign a portion of the credit to one or more affiliated corporations for each taxable year in which the credit is allowed, as specified. AB 1138 (Chapter 27 of the Statutes of 2025), effective July 3, 2025, among other things, for purposes of the motion picture credit 3.0 and 4.0 and for purposes of the certified studio credit, expands the definition of a qualified taxpayer to include a single member limited liability company that is disregarded for tax purposes. AB 1138 prohibits a motion picture credit 1.0 and 2.0 or certified studio credit generated by a disregarded single member limited liability company from being ineligible for certain reasons for assignment to a corporation that, directly or indirectly, owns the disregarded single member limited liability company, or to an affiliated corporation of that corporation.
This bill would additionally prohibit a motion picture credit 3.0 generated by a disregarded single member limited liability company from being ineligible for those same reasons for assignment to a corporation that, directly or indirectly, owns the disregarded single member limited liability company, or to an affiliated corporation of that corporation.
(4)(5)The California Constitution provides for the establishment of the State Board of Equalization, which, before July 1, 2017, had primary responsibility for most of the states duties, powers, and responsibilities regarding the administration of taxes and fees. Existing law, on July 1, 2017, transferred to the California Department of Tax and Fee Administration various duties, powers, and responsibilities of the State Board of Equalization, including enforcing specified licensing and tax provisions of the Cigarette and Tobacco Products Tax Law and providing information to the Attorney General relative to a sellers failure or attempt to comply with specified provisions of federal law.
This bill would change references in these provisions of the Cigarette and Tobacco Products Tax Law from the State Board of Equalization or board to the California Department of Tax and Fee Administration or department, as applicable, to reflect the transfer of the boards duties, powers, and responsibilities to the department.
(1)Existing property tax law specifies the date on which a remittance to a taxing agency is deemed to be received depending on the method of delivery, as provided, including for items mailed with an official postmark.
This bill would provide that if the remittance deposited in the United States mail does not contain an official postmark, require, in the absence of any specified dates, the remittance shall be credited against any amount due as of to be deemed received on the date the remittance is received. received by the county treasurer-tax collector, except as provided.
(2)Existing property tax law authorizes a tax collector to sell property that has become tax defaulted, as provided, and has not been redeemed. Existing law requires the tax collector to sell the property at a public auction to the highest bidder and prohibits the tax collector from accepting an offer less than the minimum price approved, as provided, except that the tax collector may reduce the minimum price if there has been a partial redemption or partial cancellation, as specified.
This bill would also authorize a tax collector to reduce the minimum price where the minimum necessary to redeem is decreased due to the removal or reduction of defaulted taxes resulting from the removal or reduction of a special assessment or a direct charge against the property.
(3)The Transactions and Use Tax Law authorizes various local governmental entities, subject to certain limitations and approval requirements, to levy transactions and use taxes as special taxes in accordance with the procedures and requirements set forth in that law. The Transactions and Use Tax Law prohibits an ordinance adopted under its provisions from becoming operative on other than the first day of a calendar quarter, or prior to the first day of the first calendar quarter, commencing more than 110 days after the adoption of the ordinance.
This bill would instead prohibit an ordinance adopted under the Transactions and Use Tax Law from becoming operative on other than the first day of a calendar quarter, or prior to the first day of the first calendar quarter, commencing more than 110 days after the election on the ordinance proposing the tax.
(4)The California Constitution provides for the establishment of the State Board of Equalization, which, before July 1, 2017, had primary responsibility for most of the states duties, powers, and responsibilities regarding the administration of taxes and fees. Existing law, on July 1, 2017, transferred to the California Department of Tax and Fee Administration various duties, powers, and responsibilities of the State Board of Equalization, including enforcing specified licensing and tax provisions of the Cigarette and Tobacco Products Tax Law and providing information to the Attorney General relative to a sellers failure or attempt to comply with specified provisions of federal law.
This bill would change references in these provisions of the Cigarette and Tobacco Products Tax Law from the State Board of Equalization or board to the California Department of Tax and Fee Administration or department, as applicable, to reflect the transfer of the boards duties, powers, and responsibilities to the department.
(1)Existing property tax law specifies the date on which a remittance to a taxing agency is deemed to be received depending on the method of delivery, as provided, including for items mailed with an official postmark.
This bill would provide that if the remittance deposited in the United States mail does not contain an official postmark, the remittance shall be credited against any amount due as of the date the remittance is received.
(2)Existing property tax law authorizes a tax collector to sell property that has become tax defaulted, as provided, and has not been redeemed. Existing law requires the tax collector to sell the property at a public auction to the highest bidder and prohibits the tax collector from accepting an offer less than the minimum price approved, as provided, except that the tax collector may reduce the minimum price if there has been a partial redemption or partial cancellation, as specified.
This bill would also authorize a tax collector to reduce the minimum price where the minimum necessary to redeem is decreased due to the removal or reduction of defaulted taxes resulting from the removal or reduction of a special assessment or a direct charge against the property.
(a)If a remittance to cover a payment required by law to be made to a taxing agency prior to a specified date and hour is (a) deposited in the United States mail in a sealed envelope, properly addressed with the required postage prepaid, or (b) deposited for shipment with an independent delivery service that is an Internal Revenue Service designated delivery service or has been approved by the tax collector, in a sealed envelope or package, properly addressed with the required fee prepaid, delivery of which shall not be later than 5 p.m. on the next business day after the effective delinquent date, the remittance shall be deemed received on the date shown by the post office cancellation mark stamped upon the envelope containing the remittance, or the independent delivery service shipment date shown on the packing slip or air bill attached to the outside of the envelope or package containing the remittance, or, in the absence of any of the aforementioned dates, on the date received by the county treasurer-tax collector, or on the date it was mailed if proof satisfactory to the tax collector establishes that the mailing occurred on an earlier date. The taxing agency is not required to accept a payment actually received in the mail if it is received more than 30 days after the date and time set by law for the payment.
(b)If a remittance to cover a payment, required by law to be made to a taxing agency prior to a specified date and hour, is made by an electronic payment option, such as wire transfer, telephoned credit card, or electronic internet means, the remittance shall be deemed received on the date the transaction was completed by the taxpayer, if the remittance was made on the taxing agencys authorized internet website or via the taxing agencys authorized telephone number. Proof of completion of the transaction in the form of a confirmation number or other convincing evidence shall be presented by the taxpayer to the satisfaction of the tax collector. This subdivision does not apply to payments by electronic fund transfer as provided in Sections 2503.1 and 2503.2.
(c)This section does not, for purposes of applying subdivision (a) of Section 3707, apply to a remittance sent by mail, by independent delivery service, or by electronic payment option for the redemption of tax-defaulted property.
SEC. 2.Section 3706 of the Revenue and Taxation Code is amended to read:3706.If the property is not redeemed before the close of business on the last business day prior to the date of the sale of the property, the tax collector shall sell the property at public auction to the highest bidder at the time and place fixed.
In the case of a sale at public auction, no bid shall be accepted for a sum less than the minimum price approved in the resolution of the board of supervisors; provided, however, the tax collector may reduce the minimum price under any of the following circumstances:
(a)If a partial redemption has been made under Chapter 2 (commencing with Section 4131) of Part 7 of Division 1.
(b)If a partial cancellation has been made under Chapter 4 (commencing with Section 4985) of Part 9 of Division 1 after that price was fixed, by not more than the ratio that the delinquency on the portion so redeemed or canceled bears to the delinquency upon the whole.
(c)If the total amount necessary to redeem is decreased due to the removal or reduction of default taxes resulting from the removal or reduction of a special assessment or a direct charge against the property.
SEC. 3.Section 7265 of the Revenue and Taxation Code is amended to read:7265.No ordinance adopted pursuant to this part shall be operative on other than the first day of a calendar quarter, or prior to the first day of the first calendar quarter, commencing more than 110 days after the election on the ordinance proposing the tax.
SEC. 4.Section 23696 of the Revenue and Taxation Code is amended to read:23696.(a)Notwithstanding anything to the contrary in Sections 23685 and 23695, and in Section 23698, as that section read on January 1, 2025, a credit, or any portion thereof, allowed under Section 23685, 23695, or 23698 and generated by a disregarded single member limited liability company shall not be ineligible for assignment to a corporation that, directly or indirectly, owns the disregarded single member limited liability company, or to an affiliated corporation of that corporation, based on either of the following:
(1)The disregarded single member limited liability company is not considered a qualified taxpayer, as defined in subdivision (b) of Sections 23685 and 23695 and subdivision (b) of 23698, as that section read on January 1, 2025.
(2)The amount of credit allowed under Section 23685, 23695, or 23698 does not exceed the tax liability of the disregarded single member limited liability company for purposes of paragraph (1) of subdivision (c) of Sections 23685 or 23695 or paragraph (1) of subdivision (c) of Section 23698, as that section read on January 1, 2025, respectively.
(b)For purposes of this section, affiliated corporation has the same meaning as defined in paragraph (1) of subdivision (c) of Sections 23685 and 23695 and paragraph (1) of subdivision (c) of Section 23698, as that section read on January 1, 2025.
(c)This section shall apply only when the credits affected by this section were assigned and claimed on a tax return timely filed with the Franchise Tax Board for taxable years beginning on or before January 1, 2025.
SEC. 5.Section 30101.7 of the Revenue and Taxation Code is amended to read:30101.7.(a)It is the intent of the Legislature in enacting this section to facilitate the collection of all applicable state surtaxes, sales or use taxes, and escrow and other payment obligations on cigarettes sold to residents of the state and to ensure compliance with the Prevent All Cigarette Trafficking Act of 2009 (PACT Act; Public Law 111-154).
(b)Except as provided in subdivision (d), no person may engage in a retail sale of cigarettes or tobacco products in California unless the sale is a vendor-assisted, face-to-face sale.
(c)For the purposes of this section, the following definitions shall apply:
(1)Cigarette has the same meaning as provided in Section 375 of Title 15 of the United States Code, as amended from time to time.
(2)Consumer means a person who purchases cigarettes or tobacco products. Consumer does not include any person licensed under this part or under Division 8.6 (commencing with Section 22970) of the Business and Professions Code and lawfully operating as a manufacturer, distributor, wholesaler, or retailer of cigarettes or tobacco products.
(3)Delivery sale means sale of cigarettes or tobacco products into and in this state in either of the following cases:
(A)The consumer submits the order for the sale by means of a telephone or other method of voice transmission, the mail, or the Internet or other online service, or the seller is otherwise not in the physical presence of the consumer when the request for purchase or order is made.
(B)The cigarettes or tobacco products are delivered to the consumer by common carrier, private delivery service, or other method of remote delivery, or the seller is not in the physical presence of the consumer when the consumer obtains possession of the cigarettes or tobacco products.
(4)Delivery seller means a person who makes a delivery sale.
(5)Face-to-face sale means a sale in which the purchaser is in the physical presence of the seller or the sellers employee or agent at the time of the sale. A face-to-face sale does not include a delivery sale.
(6)Indian country shall have the same meaning as provided in Section 1151 of Title 18 of the United States Code, and includes any other land held by the United States in trust or restricted status for one or more Indian tribes.
(7)Interstate commerce means commerce between a state and any place outside the state, commerce between a state and Indian country in the state, or commerce between points in the same state but through a place outside of the state or through any Indian country.
(8)Tobacco products shall have the same meaning as otherwise defined under this part with the exception of cigars.
(d)A person may engage in delivery sale of cigarettes or tobacco products to a person in California provided that all of the following conditions are met:
(1)The delivery seller has fully complied with all of the requirements of Chapter 10A (commencing with Section 375) of Title 15 of the United States Code, otherwise known as the Jenkins Act.
(2)The delivery seller obtains and maintains any applicable license under this part and under Division 8.6 (commencing with Section 22970) of the Business and Professions Code, as if the delivery sales occurred entirely within this state.
(3)The delivery seller complies with any applicable state law that imposes escrow or other payment obligations on tobacco product manufacturers, including, but not limited to, Sections 104555 to 104557, inclusive, of the Health and Safety Code.
(4)The delivery seller complies with any applicable state law or local ordinance that imposes restrictions on the retail sale of cigarettes or tobacco products directly to the public from a retail location, including Section 104559.5 of the Health and Safety Code, as if the delivery sales occurred entirely within the state and place.
(5)The Attorney General may require the delivery seller to report to the Attorney General its delivery sales of cigarettes and tobacco products to California consumers in the form and manner specified by the Attorney General.
(e)Any violation of this section by any person is a misdemeanor. Each offense shall be punishable by a fine not to exceed five thousand dollars ($5,000), or imprisonment not to exceed one year in a county jail, or both the fine and imprisonment. The amount of any fines assessed shall be deposited in the Cigarette and Tobacco Products Compliance Fund.
(f)The California Department of Tax and Fee Administration may provide information relative to a sellers failure or attempt to comply with the PACT Act and the Jenkins Act to the Attorney General.
(g)The Attorney General or a city attorney, county counsel, or district attorney may bring a civil action to enforce this section against a person that violates this section and, in addition to any other remedy provided by law, the court shall assess a civil penalty in accordance with the following schedule:
(1)A civil penalty of not less than one thousand dollars ($1,000) and not more than two thousand dollars ($2,000) for the first violation.
(2)A civil penalty of not less than two thousand five hundred dollars ($2,500) and not more than three thousand five hundred dollars ($3,500) for the second violation within a five-year period.
(3)A civil penalty of not less than four thousand dollars ($4,000) and not more than five thousand dollars ($5,000) for the third violation within a five-year period.
(4)A civil penalty of not less than five thousand five hundred dollars ($5,500) and not more than six thousand five hundred dollars ($6,500) for a fourth violation within a five-year period.
(5)A civil penalty of up to ten thousand dollars ($10,000) for a fifth or subsequent violation within a five-year period.
(h)This section does not prohibit the lawful sale of a tobacco product that occurs by means of a vending machine.
(i)Nothing in this section shall relieve the seller of cigarettes from any other applicable requirement of state law relating to the sale or distribution of cigarettes or tobacco products in this state.
(j)The California Department of Tax and Fee Administration shall enforce the licensing and tax provisions of this section. Other provisions of this section shall be enforced by the Attorney General.
(k)The provisions of this section are severable. If any provision of this section or its application is held invalid, that invalidity shall not affect other provisions or applications that can be given effect without the invalid provision or application.
(a)If a remittance to cover a payment required by law to be made to a taxing agency prior to a specified date and hour is (a) deposited in the United States mail in a sealed envelope, properly addressed with the required postage prepaid, or (b) deposited for shipment with an independent delivery service that is an Internal Revenue Service designated delivery service or has been approved by the tax collector, in a sealed envelope or package, properly addressed with the required fee prepaid, delivery of which shall not be later than 5 p.m. on the next business day after the effective delinquent date, the remittance shall be deemed received on the date shown by the post office cancellation mark stamped upon the envelope containing the remittance, or the independent delivery service shipment date shown on the packing slip or air bill attached to the outside of the envelope or package containing the remittance, or, in the absence of any of the aforementioned dates, on the date received by the county treasurer-tax collector, or on the date it was mailed if proof satisfactory to the tax collector establishes that the mailing occurred on an earlier date. The taxing agency is not required to accept a payment actually received in the mail if it is received more than 30 days after the date and time set by law for the payment.
(b)If a remittance to cover a payment, required by law to be made to a taxing agency prior to a specified date and hour, is made by an electronic payment option, such as wire transfer, telephoned credit card, or electronic internet means, the remittance shall be deemed received on the date the transaction was completed by the taxpayer, if the remittance was made on the taxing agencys authorized internet website or via the taxing agencys authorized telephone number. Proof of completion of the transaction in the form of a confirmation number or other convincing evidence shall be presented by the taxpayer to the satisfaction of the tax collector. This subdivision does not apply to payments by electronic fund transfer as provided in Sections 2503.1 and 2503.2.
(c)This section does not, for purposes of applying subdivision (a) of Section 3707, apply to a remittance sent by mail, by independent delivery service, or by electronic payment option for the redemption of tax-defaulted property.
SEC. 2.Section 3706 of the Revenue and Taxation Code is amended to read:3706.If the property is not redeemed before the close of business on the last business day prior to the date of the sale of the property, the tax collector shall sell the property at public auction to the highest bidder at the time and place fixed.
In the case of a sale at public auction, no bid shall be accepted for a sum less than the minimum price approved in the resolution of the board of supervisors; provided, however, the tax collector may reduce the minimum price under any of the following circumstances:
(a)If a partial redemption has been made under Chapter 2 (commencing with Section 4131) of Part 7 of Division 1.
(b)If a partial cancellation has been made under Chapter 4 (commencing with Section 4985) of Part 9 of Division 1 after that price was fixed, by not more than the ratio that the delinquency on the portion so redeemed or canceled bears to the delinquency upon the whole.
(c)If the total amount necessary to redeem is decreased due to the removal or reduction of default taxes resulting from the removal or reduction of a special assessment or a direct charge against the property.
SEC. 3.Section 7265 of the Revenue and Taxation Code is amended to read:7265.No ordinance adopted pursuant to this part shall be operative on other than the first day of a calendar quarter, or prior to the first day of the first calendar quarter, commencing more than 110 days after the election on the ordinance proposing the tax.
SEC. 4.Section 23696 of the Revenue and Taxation Code is amended to read:23696.(a)Notwithstanding anything to the contrary in Sections 23685 and 23695, and in Section 23698, as that section read on January 1, 2025, a credit, or any portion thereof, allowed under Section 23685 23685, 23695, or 23695 23698 and generated by a disregarded single member limited liability company shall not be ineligible for assignment to a corporation that, directly or indirectly, owns the disregarded single member limited liability company, or to an affiliated corporation of that corporation, based on either of the following. following:
(1)The disregarded single member limited liability company is not considered a qualified taxpayer, as defined in subdivision (b) of Sections 23685 and 23695. 23695 and subdivision (b) of 23698, as that section read on January 1, 2025.
(2)The amount of credit allowed under Sections 23685 and 23695 Section 23685, 23695, or 23698 does not exceed the tax liability of the disregarded single member limited liability company for purposes of paragraph (1) of subdivision (c) of Section 23685 or Section 23695. Sections 23685 or 23695 or paragraph (1) of subdivision (c) of Section 23698, as that section read on January 1, 2025, respectively.
(b)For purposes of this section, affiliated corporation has the same meaning as defined in paragraph (1) of subdivision (c) of Sections 23685 and 23695. 23695 and paragraph (1) of subdivision (c) of Section 23698, as that section read on January 1, 2025.
(c)This section shall apply only when the credits affected by this section were assigned and claimed on a tax return timely filed with the Franchise Tax Board for taxable years beginning on or before January 1, 2025.
SEC. 4.SEC. 5.Section 30101.7 of the Revenue and Taxation Code is amended to read:30101.7.(a)It is the intent of the Legislature in enacting this section to facilitate the collection of all applicable state surtaxes, sales or use taxes, and escrow and other payment obligations on cigarettes sold to residents of the state and to ensure compliance with the Prevent All Cigarette Trafficking Act of 2009 (PACT Act; Public Law 111-154).
(b)Except as provided in subdivision (d), no person may engage in a retail sale of cigarettes or tobacco products in California unless the sale is a vendor-assisted, face-to-face sale.
(c)For the purposes of this section, the following definitions shall apply:
(1)Cigarette has the same meaning as provided in Section 375 of Title 15 of the United States Code, as amended from time to time.
(2)Consumer means a person who purchases cigarettes or tobacco products. Consumer does not include any person licensed under this part or under Division 8.6 (commencing with Section 22970) of the Business and Professions Code and lawfully operating as a manufacturer, distributor, wholesaler, or retailer of cigarettes or tobacco products.
(3)Delivery sale means sale of cigarettes or tobacco products into and in this state in either of the following cases:
(A)The consumer submits the order for the sale by means of a telephone or other method of voice transmission, the mail, or the Internet or other online service, or the seller is otherwise not in the physical presence of the consumer when the request for purchase or order is made.
(B)The cigarettes or tobacco products are delivered to the consumer by common carrier, private delivery service, or other method of remote delivery, or the seller is not in the physical presence of the consumer when the consumer obtains possession of the cigarettes or tobacco products.
(4)Delivery seller means a person who makes a delivery sale.
(5)Face-to-face sale means a sale in which the purchaser is in the physical presence of the seller or the sellers employee or agent at the time of the sale. A face-to-face sale does not include a delivery sale.
(6)Indian country shall have the same meaning as provided in Section 1151 of Title 18 of the United States Code, and includes any other land held by the United States in trust or restricted status for one or more Indian tribes.
(7)Interstate commerce means commerce between a state and any place outside the state, commerce between a state and Indian country in the state, or commerce between points in the same state but through a place outside of the state or through any Indian country.
(8)Tobacco products shall have the same meaning as otherwise defined under this part with the exception of cigars.
(d)A person may engage in delivery sale of cigarettes or tobacco products to a person in California provided that all of the following conditions are met:
(1)The delivery seller has fully complied with all of the requirements of Chapter 10A (commencing with Section 375) of Title 15 of the United States Code, otherwise known as the Jenkins Act.
(2)The delivery seller obtains and maintains any applicable license under this part and under Division 8.6 (commencing with Section 22970) of the Business and Professions Code, as if the delivery sales occurred entirely within this state.
(3)The delivery seller complies with any applicable state law that imposes escrow or other payment obligations on tobacco product manufacturers, including, but not limited to, Sections 104555 to 104557, inclusive, of the Health and Safety Code.
(4)The delivery seller complies with any applicable state law or local ordinance that imposes restrictions on the retail sale of cigarettes or tobacco products directly to the public from a retail location, including Section 104559.5 of the Health and Safety Code, as if the delivery sales occurred entirely within the state and place.
(5)The Attorney General may require the delivery seller to report to the Attorney General its delivery sales of cigarettes and tobacco products to California consumers in the form and manner specified by the Attorney General.
(e)Any violation of this section by any person is a misdemeanor. Each offense shall be punishable by a fine not to exceed five thousand dollars ($5,000), or imprisonment not to exceed one year in a county jail, or both the fine and imprisonment. The amount of any fines assessed shall be deposited in the Cigarette and Tobacco Products Compliance Fund.
(f)The California Department of Tax and Fee Administration may provide information relative to a sellers failure or attempt to comply with the PACT Act and the Jenkins Act to the Attorney General.
(g)The Attorney General or a city attorney, county counsel, or district attorney may bring a civil action to enforce this section against a person that violates this section and, in addition to any other remedy provided by law, the court shall assess a civil penalty in accordance with the following schedule:
(1)A civil penalty of not less than one thousand dollars ($1,000) and not more than two thousand dollars ($2,000) for the first violation.
(2)A civil penalty of not less than two thousand five hundred dollars ($2,500) and not more than three thousand five hundred dollars ($3,500) for the second violation within a five-year period.
(3)A civil penalty of not less than four thousand dollars ($4,000) and not more than five thousand dollars ($5,000) for the third violation within a five-year period.
(4)A civil penalty of not less than five thousand five hundred dollars ($5,500) and not more than six thousand five hundred dollars ($6,500) for a fourth violation within a five-year period.
(5)A civil penalty of up to ten thousand dollars ($10,000) for a fifth or subsequent violation within a five-year period.
(h)This section does not prohibit the lawful sale of a tobacco product that occurs by means of a vending machine.
(i)Nothing in this section shall relieve the seller of cigarettes from any other applicable requirement of state law relating to the sale or distribution of cigarettes or tobacco products in this state.
(j)The California Department of Tax and Fee Administration shall enforce the licensing and tax provisions of this section. Other provisions of this section shall be enforced by the Attorney General.
(k)The provisions of this section are severable. If any provision of this section or its application is held invalid, that invalidity shall not affect other provisions or applications that can be given effect without the invalid provision or application.
(a)If a remittance to cover a payment required by law to be made to a taxing agency prior to a specified date and hour is (a) deposited in the United States mail in a sealed envelope, properly addressed with the required postage prepaid, or (b) deposited for shipment with an independent delivery service that is an Internal Revenue Service designated delivery service or has been approved by the tax collector, in a sealed envelope or package, properly addressed with the required fee prepaid, delivery of which shall not be later than 5 p.m. on the next business day after the effective delinquent date, the remittance shall be deemed received on the date shown by the post office cancellation mark stamped upon the envelope containing the remittance, or the independent delivery service shipment date shown on the packing slip or air bill attached to the outside of the envelope or package containing the remittance, or, in the absence of any of the aforementioned dates, on the date received by the county treasurer-tax collector, or on the date it was mailed if proof satisfactory to the tax collector establishes that the mailing occurred on an earlier date. If remittance to cover a payment is deposited in the United States mail and does not contain an official postmark, the date of credit shall be the date received by the county treasurer-tax collector. The taxing agency is not required to accept a payment actually received in the mail if it is received more than 30 days after the date and time set by law for the payment.
(b)If a remittance to cover a payment, required by law to be made to a taxing agency prior to a specified date and hour, is made by an electronic payment option, such as wire transfer, telephoned credit card, or electronic internet means, the remittance shall be deemed received on the date the transaction was completed by the taxpayer, if the remittance was made on the taxing agencys authorized internet website or via the taxing agencys authorized telephone number. Proof of completion of the transaction in the form of a confirmation number or other convincing evidence shall be presented by the taxpayer to the satisfaction of the tax collector. This subdivision does not apply to payments by electronic fund transfer as provided in Sections 2503.1 and 2503.2.
(c)This section does not, for purposes of applying subdivision (a) of Section 3707, apply to a remittance sent by mail, by independent delivery service, or by electronic payment option for the redemption of tax-defaulted property.
SEC. 2.Section 3706 of the Revenue and Taxation Code is amended to read:3706.If the property is not redeemed before the close of business on the last business day prior to the date of the sale of the property, the tax collector shall sell the property at public auction to the highest bidder at the time and place fixed.
In the case of a sale at public auction, no bid shall be accepted for a sum less than the minimum price approved in the resolution of the board of supervisors; provided, however, the tax collector may reduce the minimum price under any of the following circumstances:
(a)If a partial redemption has been made under Chapter 2 (commencing with Section 4131) of Part 7 of Division 1.
(b)If a partial cancellation has been made under Chapter 4 (commencing with Section 4985) of Part 9 of Division 1 after that price was fixed, by not more than the ratio that the delinquency on the portion so redeemed or canceled bears to the delinquency upon the whole.
(c)If the total amount necessary to redeem is decreased due to the removal or reduction of default taxes resulting from the removal or reduction of a special assessment or a direct charge against the property.
SEC. 3.Section 7265 of the Revenue and Taxation Code is amended to read:7265.No ordinance adopted pursuant to this part shall be operative on other than the first day of a calendar quarter, or prior to the first day of the first calendar quarter, commencing more than 110 days after the adoption of the ordinance. election on the ordinance proposing the tax.
SEC. 4.Section 30101.7 of the Revenue and Taxation Code is amended to read:30101.7.(a)It is the intent of the Legislature in enacting this section to facilitate the collection of all applicable state surtaxes, sales or use taxes, and escrow and other payment obligations on cigarettes sold to residents of the state and to ensure compliance with the Prevent All Cigarette Trafficking Act of 2009 (PACT Act; Public Law 111-154).
(b)Except as provided in subdivision (d), no person may engage in a retail sale of cigarettes or tobacco products in California unless the sale is a vendor-assisted, face-to-face sale.
(c)For the purposes of this section, the following definitions shall apply:
(1)Cigarette has the same meaning as provided in Section 375 of Title 15 of the United States Code, as amended from time to time.
(2)Consumer means a person who purchases cigarettes or tobacco products. Consumer does not include any person licensed under this part or under Division 8.6 (commencing with Section 22970) of the Business and Professions Code and lawfully operating as a manufacturer, distributor, wholesaler, or retailer of cigarettes or tobacco products.
(3)Delivery sale means sale of cigarettes or tobacco products into and in this state in either of the following cases:
(A)The consumer submits the order for the sale by means of a telephone or other method of voice transmission, the mail, or the Internet or other online service, or the seller is otherwise not in the physical presence of the consumer when the request for purchase or order is made.
(B)The cigarettes or tobacco products are delivered to the consumer by common carrier, private delivery service, or other method of remote delivery, or the seller is not in the physical presence of the consumer when the consumer obtains possession of the cigarettes or tobacco products.
(4)Delivery seller means a person who makes a delivery sale.
(5)Face-to-face sale means a sale in which the purchaser is in the physical presence of the seller or the sellers employee or agent at the time of the sale. A face-to-face sale does not include a delivery sale.
(6)Indian country shall have the same meaning as provided in Section 1151 of Title 18 of the United States Code, and includes any other land held by the United States in trust or restricted status for one or more Indian tribes.
(7)Interstate commerce means commerce between a state and any place outside the state, commerce between a state and Indian country in the state, or commerce between points in the same state but through a place outside of the state or through any Indian country.
(8)Tobacco products shall have the same meaning as otherwise defined under this part with the exception of cigars.
(d)A person may engage in delivery sale of cigarettes or tobacco products to a person in California provided that all of the following conditions are met:
(1)The delivery seller has fully complied with all of the requirements of Chapter 10A (commencing with Section 375) of Title 15 of the United States Code, otherwise known as the Jenkins Act.
(2)The delivery seller obtains and maintains any applicable license under this part and under Division 8.6 (commencing with Section 22970) of the Business and Professions Code, as if the delivery sales occurred entirely within this state.
(3)The delivery seller complies with any applicable state law that imposes escrow or other payment obligations on tobacco product manufacturers, including, but not limited to, Sections 104555 to 104557, inclusive, of the Health and Safety Code.
(4)The delivery seller complies with any applicable state law or local ordinance that imposes restrictions on the retail sale of cigarettes or tobacco products directly to the public from a retail location, including Section 104559.5 of the Health and Safety Code, as if the delivery sales occurred entirely within the state and place.
(5)The Attorney General may require the delivery seller to report to the Attorney General its delivery sales of cigarettes and tobacco products to California consumers in the form and manner specified by the Attorney General.
(e)Any violation of this section by any person is a misdemeanor. Each offense shall be punishable by a fine not to exceed five thousand dollars ($5,000), or imprisonment not to exceed one year in a county jail, or both the fine and imprisonment. The amount of any fines assessed shall be deposited in the Cigarette and Tobacco Products Compliance Fund.
(f)The State Board of Equalization California Department of Tax and Fee Administration may provide information relative to a sellers failure or attempt to comply with the PACT Act and the Jenkins Act to the Attorney General.
(g)The Attorney General or a city attorney, county counsel, or district attorney may bring a civil action to enforce this section against a person that violates this section and, in addition to any other remedy provided by law, the court shall assess a civil penalty in accordance with the following schedule:
(1)A civil penalty of not less than one thousand dollars ($1,000) and not more than two thousand dollars ($2,000) for the first violation.
(2)A civil penalty of not less than two thousand five hundred dollars ($2,500) and not more than three thousand five hundred dollars ($3,500) for the second violation within a five-year period.
(3)A civil penalty of not less than four thousand dollars ($4,000) and not more than five thousand dollars ($5,000) for the third violation within a five-year period.
(4)A civil penalty of not less than five thousand five hundred dollars ($5,500) and not more than six thousand five hundred dollars ($6,500) for a fourth violation within a five-year period.
(5)A civil penalty of up to ten thousand dollars ($10,000) for a fifth or subsequent violation within a five-year period.
(h)This section does not prohibit the lawful sale of a tobacco product that occurs by means of a vending machine.
(i)Nothing in this section shall relieve the seller of cigarettes from any other applicable requirement of state law relating to the sale or distribution of cigarettes or tobacco products in this state.
(j)The board California Department of Tax and Fee Administration shall enforce the licensing and tax provisions of this section. Other provisions of this section shall be enforced by the Attorney General.
(k)The provisions of this section are severable. If any provision of this section or its application is held invalid, that invalidity shall not affect other provisions or applications that can be given effect without the invalid provision or application.
CORRECTIONS: TextPage 4.(a)If a remittance to cover a payment required by law to be made to a taxing agency prior to a specified date and hour is (a) deposited in the United States mail in a sealed envelope, properly addressed with the required postage prepaid, or (b) deposited for shipment with an independent delivery service that is an Internal Revenue Service designated delivery service or has been approved by the tax collector, in a sealed envelope or package, properly addressed with the required fee prepaid, delivery of which shall not be later than 5 p.m. on the next business day after the effective delinquent date, the remittance shall be deemed received on the date shown by the post office cancellation mark stamped upon the envelope containing the remittance, or the independent delivery service shipment date shown on the packing slip or air bill attached to the outside of the envelope or package containing the remittance, or on the date it was mailed if proof satisfactory to the tax collector establishes that the mailing occurred on an earlier date. If remittance to cover a payment is deposited in the United States mail and does not contain an official postmark, the date of credit shall be the date received by the county treasurer-tax collector. The taxing agency is not required to accept a payment actually received in the mail if it is received more than 30 days after the date and time set by law for the payment.
(b)If a remittance to cover a payment, required by law to be made to a taxing agency prior to a specified date and hour, is made by an electronic payment option, such as wire transfer, telephoned credit card, or electronic Internet internet means, the remittance shall be deemed received on the date the transaction was completed by the taxpayer, if the remittance was made on the taxing agencys authorized Internet Web site internet website or via the taxing agencys authorized telephone number. Proof of completion of the transaction in the form of a confirmation number or other convincing evidence shall be presented by the taxpayer to the satisfaction of the tax collector. This subdivision does not apply to payments by electronic fund transfer as provided in Sections 2503.1 and 2503.2.
(c)This section does not, for purposes of applying subdivision (a) of Section 3707, apply to a remittance sent by mail, by independent delivery service, or by electronic payment option for the redemption of tax-defaulted property.
SEC. 2.Section 3706 of the Revenue and Taxation Code is amended to read:3706.If the property is not redeemed before the close of business on the last business day prior to the date of the sale of the property, the tax collector shall sell the property at public auction to the highest bidder at the time and place fixed.
In the case of a sale at public auction, no bid shall be accepted for a sum less than the minimum price approved in the resolution of the board of supervisors; provided, however, the tax collector may reduce such the minimum price when under any of the following circumstances:
(a)If a partial redemption has been made under Chapter 2, 2 (commencing with Section 4131) of Part 7, 7 of Division 1 of this code, or when 1.
(b)If a partial cancellation has been made under Chapter 4, 4 (commencing with Section 4985) of Part 9, 9 of Division 1 of this code, 1 after such that price was fixed, by not more than the ratio that the delinquency on the portion so redeemed or canceled bears to the delinquency upon the whole.
(c)If the total amount necessary to redeem is decreased due to the removal or reduction of default taxes resulting from the removal or reduction of a special assessment or a direct charge against the property.
|
Date
|
Status
|
|---|---|
| Oct 7, 2025 | Chaptered by Secretary of State. Chapter 462, Statutes of 2025. |
| Oct 7, 2025 | Approved by the Governor. |
| Sep 16, 2025 | Enrolled and presented to the Governor at 3 p.m. |
| Sep 8, 2025 | Assembly amendments concurred in. (Ayes 39. Noes 0. Page 2579.) Ordered to engrossing and enrolling. |
| Sep 4, 2025 | In Senate. Concurrence in Assembly amendments pending. |
| Sep 4, 2025 | Read third time. Passed. (Ayes 78. Noes 0. Page 2905.) Ordered to the Senate. |
| Aug 28, 2025 | Read third time and amended. |
| Aug 28, 2025 | Ordered to third reading. |
| Aug 28, 2025 | Action rescinded whereby bill was read third time, passed, and ordered to the Senate. |
| Aug 19, 2025 | In Assembly. Held at Desk. |
| Aug 18, 2025 | Ordered to the Assembly. |
| Jul 14, 2025 | In Senate. Concurrence in Assembly amendments pending. |
| Jul 14, 2025 | Read third time. Passed. (Ayes 77. Noes 0. Page 2539.) Ordered to the Senate. |
| Jul 9, 2025 | Read second time. Ordered to consent calendar. |
| Jul 8, 2025 | From committee: Do pass. Ordered to consent calendar. (Ayes 7. Noes 0.) (July 7). |
| Jul 8, 2025 | (Corrected July 8). |
| Jun 27, 2025 | From committee with author's amendments. Read second time and amended. Re-referred to Com. on REV. & TAX. |
| Jun 24, 2025 | June 23 set for first hearing canceled at the request of author. |
| May 19, 2025 | Referred to Com. on REV. & TAX. |
| May 1, 2025 | In Assembly. Read first time. Held at Desk. |
| May 1, 2025 | Read third time. Passed. (Ayes 37. Noes 0. Page 984.) Ordered to the Assembly. |
| Apr 24, 2025 | Read second time. Ordered to consent calendar. |
| Apr 23, 2025 | From committee: Do pass. Ordered to consent calendar. (Ayes 5. Noes 0. Page 873.) (April 23). |
| Apr 4, 2025 | Set for hearing April 23. |
| Mar 26, 2025 | Referred to Com. on REV. & TAX. |
| Mar 20, 2025 | From printer. May be acted upon on or after April 19. |
| Mar 19, 2025 | Introduced. Read first time. To Com. on RLS. for assignment. To print. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Sep 8, 2025 | Unfinished Business SB863 REV. & TAX. (McNerney) Concurrence | Senate Floor |
Passed |
|
| Sep 4, 2025 | SB 863 Revenue and Taxation Senate Third Reading By GIPSON | Assembly Floor |
Passed |
|
| Jul 14, 2025 | SB 863 Rev. & Tax. Consent Calendar Second Day Regular Session | Assembly Floor |
Passed |
|
| Jul 7, 2025 | Do pass. To Consent Calendar. | Assembly Standing Committee on Revenue and Taxation |
Passed |
|
| May 1, 2025 | Consent Calendar 2nd SB863 REV. & TAX. (McNerney) | Senate Floor |
Passed |
|
| Apr 23, 2025 | Do pass and be ordered to the Consent Calendar | Senate Standing Committee on Revenue and Taxation |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| California Association of County Treasurer-Tax Collectors (Co-Source) | ** Support | |
| California Department of Tax & Fee Administration | ** Support | |
| California Department of Tax & Fee Administration (Co-Source) | ** Support | |
| Senate Committee on Revenue and Taxation | ** Support |
SENATE RULES COMMITTEE Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | SB 863 |
UNFINISHED BUSINESS
Bill No: SB 863
Author: Committee on Revenue and Taxation
Amended: 8/28/25
Vote: 21
SENATE REVENUE AND TAXATION COMMITTEE: 5-0, 4/23/25
AYES: McNerney, Valladares, Ashby, Grayson, Umberg
SENATE FLOOR: 37-0, 5/1/25 (Consent)
AYES: Allen, Archuleta, Arreguín, Ashby, Becker, Blakespear, Cabaldon, Caballero, Cervantes, Choi, Cortese, Dahle, Durazo, Gonzalez, Grayson, Grove, Hurtado, Jones, Laird, Limón, McGuire, McNerney, Menjivar, Niello, Ochoa Bogh, Padilla, Pérez, Richardson, Seyarto, Smallwood-Cuevas, Stern, Strickland, Umberg, Valladares, Wahab, Weber Pierson, Wiener
NO VOTE RECORDED: Alvarado-Gil, Reyes, Rubio
ASSEMBLY FLOOR: 78-0, 9/4/25 - See last page for vote
SUBJECT: Taxation
SOURCE: California Association of County Treasurer-Tax Collectors
California Department of Tax & Fee Administration
DIGEST:
This bill makes four changes to improve tax administration suggested by the California Association of County Treasurer-Tax Collectors and the California Department of Tax & Fee Administration (CDTFA), among others.
Assembly Amendments
(1) clarify that the measure’s deemed received date for property tax payments applies in absence of other dates mentioned in law, (2) add a provision to change the operative date of a new district tax ordinance to commence after the vote on the ordinance instead of the local agency’s adoption of the ordinance, (3) update references in one section of the Cigarette and Tobacco Products Law from the Board of Equalization (BOE) to CDTFA, and (4) add references to Motion Picture and Television Production Credit 3.0 to a section of the Corporation Tax Law to clarify credit assignments made by single member limited liability companies disregarded for federal purposes.
ANALYSIS:
Existing law:
- Provides that property taxes are due in two installments, the first on November 1 and the second on February 1, with delinquency for the second installment occurring on April 10.
- Requires county tax collectors to begin imposing penalties for nonpayment of property taxes for each amount due, plus administrative charges, once taxes become delinquent.
- Deems mailed remittances received as of the date of the postmark on the envelope containing the remittance, or the date on the packing slip or air bill from an independent delivery service.
- Permits tax collectors to also deem the remittance received if it can be proved that the mailing occurred on an earlier date.
- Provides that if payments are made through the tax collector’s authorized website or telephone number, the payment is deemed received on the date the taxpayer completes the electronic payment.
- Deems all other electronic payments received on the date the tax collector actually receives the payment.
- States that a property becomes tax defaulted if a property owner does not pay the property taxes due in the current fiscal year before June 30.
- Allows the tax collector to sell a residential property that has been in default for five years, or a commercial property after three years in default, unless the Board of Supervisors sets a five-year period for commercial property.
- Directs tax collectors to sell properties at public auction, but only when bids exceed the “minimum bid,” which is equal to the total amount of outstanding taxes, assessments, penalties, and fees.
- Requires tax collectors to obtain approval from the Board of Supervisors to reduce a minimum bid, unless a partial redemption or cancellation has been made.
- Imposes the sales tax on every retailer engaged in business in this state that sells tangible personal property, and requires them to collect the appropriate tax from the purchase and remit the amount to CDTFA.
- States that taxes levied by local governments are either general taxes, subject to majority approval of its voters, or special taxes, subject to 2/3 vote (California Constitution, Article XIII C).
- Allows cities, counties, and specified special districts, including the San Francisco Bay Area Rapid Transit District and the Santa Cruz County Metropolitan Transit District, to increase the sales and use tax applied within their jurisdictions, also known as district or transactions and use taxes, for either specific or general purposes pursuant to the California Constitution’s voter approval requirements.
- Precludes a district tax ordinance from becoming operative on other than the first day of a calendar quarter, or prior to the first day of the first calendar quarter, commencing more than 110 days after the adoption of the ordinance.
- Under federal law, provides that a Limited Liability Company (LLC) can either be “disregarded” and considered inseparable from its owner, with income and expenses integrated into its owner’s returns, or be treated as a corporation, and taxed separately.
- Conforms to federal tax treatment of LLCs, but requires entities to make the same election for state purposes as they did for federal, file a tax return, and pay an annual minimum tax of $800 despite their disregarded status.
- Limits the value of credits attributable to a disregarded entity.
- Enacts “Motion Picture and Television Production Tax Credit 1.0,” which directs the California Film Commission (CFC) to annually allocate $100 million in credits until the 2012-13 fiscal year (SB 15 X3, Calderon, Chapter 17, Statutes of 2009-10 Third Extraordinary Session and AB 15 X3, Krekorian, Chapter 10, Statutes of the 2009-10 Third Extraordinary Session).
- Enacts “Motion Picture and Television Production Tax Credit 2.0,” which increased the amount of credit to $330 million each fiscal year through 2019-20, among other changes (AB 1839, Gatto, Chapter 413, Statutes of 2020).
- Enacts “Motion Picture and Television Production Tax Credit 3.0” which authorizes CFC to allocate $330 million in tax credits each fiscal year from 2020-21 to 2024-25, among other changes (SB 878, Committee on Budget & Fiscal Review, Chapter 456, Statutes of 2018), subsequently amended to also allow a credit for qualified motion pictures produced at a certified studio construction project (SB 144, Portantino, Chapter 114, Statutes of 2021).
- Enacts “Motion Picture and Television Production Tax Credit 4.0” extending the CFC authorization from 2025-26 and continuing through 2029-30 (SB 132 Committee on Budget & Fiscal Review, Chapter 56, Statutes of 2023).
- Defines a “qualified taxpayer” as a taxpayer who has paid or incurred qualified expenditures, participated in the Career Readiness requirement, and has been issued a credit certificate by the California Film Commission.
- Permits corporation taxpayers to assign the credit to one or more affiliated corporations within their unitary groups, so long as the value of the credit exceeds the qualified taxpayer’s liability. Taxpayers may assign credits notwithstanding limits placed on credits generated by disregarded entities. Defines “affiliated corporation” as one in the same unitary group for Corporation Tax purposes, where 100% of the voting stock is owned, directly or indirectly, by members of the unitary group and the unitary group is engaged in the same general line of business.
- Enacts several provisions to clarify the ability of Single Member LLCs (SMLLCs) disregarded for tax purposes to assign Motion Picture and Television Production Tax Credits to affiliated corporations (AB 1138, Zbur, Chapter 27, Statutes of 2025), among other provisions amending and expanding Motion Picture and Television Production Tax Credit, including to:
- Amend the Corporations Tax Law sections for the Motion Picture and Television Production Tax 3.0 and 4.0 Credit programs to:
- Add to the definition of “qualified taxpayer” a disregarded SMLLC.
- Provide that a SMLLC disregarded for tax purposes may elect to assign any portion of the credit allowed to one or more affiliated corporations if such single member limited liability company made the federal election to be classified as an association taxable as a corporation.
- Disconnect the requirement that, for a qualified taxpayer to assign a credit, the amount of credit must exceed the taxpayer’s liability.
- Enact a new section of the Corporation Tax Law to provide that under the Motion Picture and Television Production Tax 1.0 and 2.0 Credit programs, so long as credits were assigned and claimed on a timely filed tax return with the FTB on or before January 1, 2025, credits generated by a SMLLC disregarded for tax purposes shall not be ineligible for assignment to either a corporation that owns the SMLLC or to its affiliate based on:
- The SMLLC not being considered a qualified taxpayer.
- The amount of credit not exceeding the SMLLC’s tax liability.
- Amend the Corporations Tax Law sections for the Motion Picture and Television Production Tax 3.0 and 4.0 Credit programs to:
- Enacts the California Cigarette and Tobacco Products Tax Law, which imposes a tax of $2.87 per package of 20 cigarettes.
- Enacts Taxpayer Transparency and Fairness Act of 2017, which created the CDTFA, and shifted all of BOE’s statutory tax administration functions to CDTFA (AB 102, Committee on Budget, Chapter 16, Statutes of 2017).
This bill:
- Deems a property tax payment received as of the date of delivery if it does not contain an official postmark in the absence of any other date mentioned in law.
- Allows the tax collector to reduce the minimum bid at a tax sale when defaulted taxes decrease due to the removal or reduction of a special assessment or a direct charge against the property.
- Modifies the period that precludes a district tax ordinance from becoming operative to provide that it is measured from the date voters approve the ordinance at an election, not from the adoption of the ordinance.
- Adds references to the Corporation Tax Law section for Motion Picture and Production Tax Credit 3.0, as it read on January 1, 2025, into AB 1138’s new section of the Corporation Tax Law that clarifies SMLLC assignment of tax credits under the Motion Picture and Television Production Tax 1.0 and 2.0 Credit programs, and makes conforming changes.
- Replaces references in one section of the Cigarette and Tobacco Products Licensing Law from BOE to CDTFA.
Background
Minimum Bids. In addition to unpaid property taxes, outstanding taxes and assessments can include direct charges imposed by a county, city, or local agency, such as parcel taxes, benefit assessments, or taxes to repay outstanding bonds. When a local agency wants to cancel or reduce a direct charge, state law does not allow the tax collector to reduce the minimum bid without returning to the Board of Supervisors for approval. In this case, the tax sale must generally wait another year, and all the costs incurred to conduct a tax sale for that property are wasted.
District Tax Ordinances. Existing law provides that a district tax ordinance becomes operative no sooner than the first day of the first calendar quarter commencing more than 110 days after the ordinance’s adoption. Historically, cities and counties have generally adopted district tax ordinances on the election date. This provision was intended to allow the CDTFA sufficient time to prepare to administer the new district tax. However, in recent years, more cities and counties have adopted ordinances at various times following voter approval. These delayed adoptions have led to commensurate delays in administration of newly adopted district taxes. For example, the City of Grass Valley obtained voter approval for a district tax on March 5, 2024, and requested an operative date of July 1, 2024. However, the ordinance was not adopted until April 9, 2024, leaving less time than was required by law for the tax to become operative on July 1. Accordingly, the CDTFA was forced to delay the operative date to October 1, 2024, delaying expected revenues.
AB 1138 Clarification. AB 1138 sought to prospectively and retroactively clarify the ability of a Single-Member Limited Liability Company (SMLLC) disregarded for federal tax purposes to assign tax credits to affiliated corporations, and to do so without the limitation imposed on disregarded entities. Credit assignment had been part of the Film and Television Production Credit since its enactment in 2009, but the statute didn’t clearly identify SMLLCs as entities that could generate tax credits, or whether the limit applied.
Specifically, AB 1138 made two changes to clarify assignments and ensure consistent treatment across all four credit statutes in the Corporation Tax. First, it amended film and television production tax credit 3.0 and 4.0 statutes in the Corporation Tax. Second, AB 1138 enacted a new stand-alone section in the Corporation Tax to make these same clarifications under the 1.0 and 2.0 film and television production tax credits.
However, AB 1138’s changes to the 3.0 statute did not contain an explicit effective date, so it’s unclear whether AB 1138’s clarification applies to 3.0 credits claimed before the 2025 taxable year. As a result, they will not likely be treated in the same way as other credits claimed in the 2025 taxable year and after, contrary to the intent of the program and AB 1138. As amended, this bill provides further clarification by adding references to AB 1138’s changes to the 3.0 statute into its standalone section, and make conforming changes, which ensures 3.0 credits are treated the same regardless of the taxable year in which they’re claimed.
FISCAL EFFECT: Appropriation: No Fiscal Com.: No Local: No
SUPPORT: (Verified 9/2/25)
California Association of County Treasurer-Tax Collectors (Co-Source)
California Department of Tax & Fee Administration (Co-Source)
OPPOSITION: (Verified 9/2/25)
None received
ARGUMENTS IN SUPPORT: According to the California Association of County Treasurer-Tax Collectors, “SB 863 … will provide tax collectors the ability to credit the remittance against any amount due as of the date the remittance is received, thereby offering greater clarity and ensuring a fair and transparent process for taxpayers. CACTTC also supports SB 863 because it will authorize a tax collector to reduce the minimum price where the minimum necessary to redeem is decreased due to the removal or reduction of defaulted taxes resulting from the removal or reduction of a special assessment or a direct charge against the property. SB 863 provides tax collectors with a more practical approach to resolving tax-defaulted properties by offering much-needed flexibility in property tax auctions. This helps ensure that properties are sold at fair and reasonable prices, particularly in situations where a portion of the delinquency has been mitigated.”
ASSEMBLY FLOOR: 78-0, 9/4/25
AYES: Addis, Aguiar-Curry, Alanis, Alvarez, Arambula, Ávila Farías, Bains, Bauer-Kahan, Bennett, Berman, Boerner, Bonta, Bryan, Calderon, Caloza, Carrillo, Castillo, Chen, Connolly, Davies, DeMaio, Dixon, Elhawary, Ellis, Flora, Fong, Gabriel, Gallagher, Garcia, Gipson, Jeff Gonzalez, Mark González, Hadwick, Haney, Harabedian, Hart, Hoover, Irwin, Jackson, Kalra, Krell, Lackey, Lee, Lowenthal, Macedo, McKinnor, Muratsuchi, Nguyen, Ortega, Pacheco, Papan, Patel, Patterson, Pellerin, Petrie-Norris, Quirk-Silva, Ramos, Ransom, Celeste Rodriguez, Michelle Rodriguez, Rogers, Blanca Rubio, Sanchez, Schiavo, Schultz, Sharp-Collins, Solache, Soria, Stefani, Ta, Tangipa, Valencia, Wallis, Ward, Wicks, Wilson, Zbur, Rivas
NO VOTE RECORDED: Ahrens
ASSEMBLY FLOOR: 77-0, 7/14/25
AYES: Addis, Aguiar-Curry, Ahrens, Alanis, Alvarez, Arambula, Bains, Bauer-Kahan, Bennett, Berman, Boerner, Bonta, Bryan, Calderon, Caloza, Carrillo, Castillo, Chen, Connolly, Davies, DeMaio, Dixon, Elhawary, Ellis, Flora, Fong, Gabriel, Gallagher, Garcia, Gipson, Jeff Gonzalez, Mark González, Hadwick, Haney, Harabedian, Hart, Hoover, Irwin, Jackson, Kalra, Krell, Lackey, Lee, Lowenthal, Macedo, McKinnor, Muratsuchi, Nguyen, Ortega, Pacheco, Papan, Patel, Patterson, Pellerin, Petrie-Norris, Quirk-Silva, Ramos, Ransom, Celeste Rodriguez, Michelle Rodriguez, Rogers, Blanca Rubio, Sanchez, Schiavo, Sharp-Collins, Solache, Soria, Stefani, Ta, Tangipa, Valencia, Wallis, Ward, Wicks, Wilson, Zbur, Rivas
NO VOTE RECORDED: Ávila Farías, Schultz
Prepared by: Colin Grinnell / REV. & TAX. / (916) 651-4117
9/6/25 10:40:17
SENATE THIRD READING
STR Bill Id:SB 863
Author:(Committee on Revenue and Taxation)
As Amended Ver:August 28, 2025
Majority vote
SUMMARY
Makes various technical and conforming changes to the Revenue and Taxation Code (R&TC) relating to the administration of property taxes, district tax ordinances, cigarette and tobacco products taxes, and motion picture credits under the Corporate Tax (CT) Law.
Major Provisions
- Provides that a property tax remittance (payment) sent by mail is deemed to be received on the date it is received by the county treasurer-tax collector if there is no date shown on the post office cancellation mark stamp or packing slip attached to the outside of the envelope or package containing the remittance.
- Authorizes a county tax collector, when selling a tax-defaulted property at public auction, to reduce the minimum price for the property below the price approved in the resolution by the county's Board of Supervisors when any of the following occur:
- A partial redemption has been made under R&TC Section 4131;
- A partial cancellation has been made under R&TC Section 4985 after that price was fixed by not more than the ratio that the delinquency on the portion so redeemed or canceled bears to the delinquency upon the whole; or,
- The total amount necessary to redeem is decreased due to the removal or reduction of default taxes resulting from the removal or reduction of a special assessment or a direct charge against the property.
- Changes the operative date of a new district ordinance from the first day of a calendar quarter commencing more than 110 days after the adoption of the ordinance to the first day of a calendar quarter commencing more than 110 days after the election where the ordinance proposing the tax was voted on.
- Updates references under the Cigarette and Tobacco Products Tax Law from the "State Board of Equalization" or "board" to the "California Department of Tax and Fee Administration" or "department," as applicable, to reflect the transfer of the board's duties, powers, and responsibilities to the department.
- Clarifies, for purposes of the Corporation Tax Law, that a motion picture credit 3.0 generated by a disregarded single member limited liability company is eligible for assignment to a corporation that, directly or indirectly, owns the disregarded single member limited liability company, or to an affiliated corporation of that corporation.
COMMENTS
- Postmarks: This bill provides a clarification in situations where a mailed property tax payment does not have a postmark or packing slip, which has led to disputes between taxpayers and tax collectors. By clarifying that payments that do not have a dated postmark or packing slip are considered received when they are actually received by the tax collector, this bill seeks to reduce disputes and ensure consistent application of the law for taxpayers.
- Tax-defaulted property sales: Property becomes tax-defaulted land if the property taxes remain unpaid, typically as of 12:01 a.m. on July 1. Property that has become tax-defaulted after five years (or three years in the case of property that is also subject to a nuisance abatement lien) becomes subject to the county tax collector's power to sell in order to satisfy the defaulted property taxes. This process is commonly referred to as a "Chapter 7 Tax Sale".
The county tax collector must attempt to sell the property within four years of becoming subject to sale. The county tax collector may offer the property for sale at public auction, a sealed bid sale, or a negotiated sale to a public agency or qualified nonprofit organization. If no bids are received at a tax sale, an attempt must be made to sell the property at intervals of no more than six year, until it is sold.
Public auctions are the most common way of selling tax-defaulted property. The auction is conducted by the county tax collector, and the property is sold to the highest bidder.
Tax-defaulted properties rendered unusable by their size, location, or other condition, may be offered under a sealed bid to owners of contiguous properties or to holders of a predominant easement or right-of-way easement. After the tax collector notifies eligible bidders of a sealed bid, the bidders respond by mail with a bid price and the highest bidder purchases the property.
County tax collectors are required to notify the State Controller's Office "not less than 45 days nor more than 120 days before the proposed sale." Additionally, R&TC Section 3702 requires the tax collector to publish the intended sale three times in a newspaper of general circulation within the county, at least three weeks prior to the tax sale.
- District tax ordinance operative dates: Existing law provides that a district tax ordinance becomes operative no sooner than the first day of the first calendar quarter commencing more than 110 days after the ordinance's adoption. Historically, cities and counties have generally adopted district tax ordinances on the election date. This provision was intended to allow the CDTFA sufficient time to prepare to administer the new district tax. However, in recent years, more cities and counties have adopted ordinances at various times following voter approval.
This bill changes the operative date of a new district ordinance from the first day of a calendar quarter commencing more than 110 days after the adoption of the ordinance to the first day of a calendar quarter commencing more than 110 days after the election on the ordinance proposing the tax.
- Taxpayer Transparency and Fairness Act of 2017: AB 102 (Committee on Budget), Chapter 16, Statutes of 2017, shifted the responsibility of collecting and administering various excise taxes from the Board of Equalization to the newly created CDTFA, including the Cigarette and Tobacco Products taxes. This bill simply updates references from the "State Board of Equalization" or "board" to the "California Department of Tax and Fee Administration" or "department," as applicable, to reflect the transfer of the board's duties, powers, and responsibilities to the department.
- Motion picture credit cleanup: The Personal Income Tax Law and the CT Law allow various credits against the taxes imposed by those laws, including various motion picture credits, commonly referred to as motion picture credit 1.0, 2.0, 3.0, and 4.0, and the certified studio credit, to be allocated by the California Film Commission. Existing law allows a qualified taxpayer, if a motion picture credit exceeds the taxpayer's tax liability, to elect to assign a portion of the credit to one or more affiliated corporations for each taxable year in which the credit is allowed, as specified. AB 1138 (Zbur) Chapter 27 of the Statutes of 2025, effective July 3, 2025, among other things, for purposes of the motion picture credit 3.0 and 4.0 and for purposes of the certified studio credit, expands the definition of a qualified taxpayer to include a single member limited liability company that is disregarded for tax purposes. AB 1138 prohibits a motion picture credit 1.0 and 2.0 or certified studio credit generated by a disregarded single member limited liability company from being ineligible for certain reasons for assignment to a corporation that, directly or indirectly, owns the disregarded single member limited liability company, or to an affiliated corporation of that corporation.
This bill would additionally prohibit a motion picture credit 3.0 generated by a disregarded single member limited liability company from being ineligible for those same reasons for assignment to a corporation that, directly or indirectly, owns the disregarded single member limited liability company, or to an affiliated corporation of that corporation.
According to the Author
The Senate Committee on Revenue and Taxation has submitted the following statement in support of this bill:
This year, the Senate Committee on Revenue and Taxation introduced SB 863 to make technical, non-controversial changes to improve tax administration suggested by the California Department of Tax and Fee Administration (CDTFA) and the California Association of County Treasurers and Tax Collectors. SB 863 combines noncontroversial statutory changes into one single bill. Moving these proposals as separate bills, even if technical and noncontroversial, through the legislative process would be much less efficient than consolidating them into one measure. Committee staff distributed these proposals to affected parties to review each proposal before including it in the bill. Should anyone object to an item in the bill, it will be removed.
Arguments in Support
Writing in support of this bill, the California Association of County Treasurers and Tax Collectors notes, in part:
CACTTC is proud to co-sponsor and support SB 863 because it will provide tax collectors the ability to credit the remittance against any amount due as of the date the remittance is received, thereby offering greater clarity and ensuring a fair and transparent process for taxpayers. CACTTC also supports SB 863 because it will authorize a tax collector to reduce the minimum price where the minimum necessary to redeem is decreased due to the removal or reduction of defaulted taxes resulting from the removal or reduction of a special assessment or a direct charge against the property. SB 863 provides tax collectors with a more practical approach to resolving tax-defaulted properties by offering much-needed flexibility in property tax auctions. This helps ensure that properties are sold at fair and reasonable prices, particularly in situations where a portion of the delinquency has been mitigated.
Arguments in Opposition
None on file.
FISCAL COMMENTS
None.
VOTES
SENATE FLOOR: 37-0-3
YES: Allen, Archuleta, Arreguín, Ashby, Becker, Blakespear, Cabaldon, Caballero, Cervantes, Choi, Cortese, Dahle, Durazo, Gonzalez, Grayson, Grove, Hurtado, Jones, Laird, Limón, McGuire, McNerney, Menjivar, Niello, Ochoa Bogh, Padilla, Pérez, Richardson, Seyarto, Smallwood-Cuevas, Stern, Strickland, Umberg, Valladares, Wahab, Weber Pierson, Wiener
ABS, ABST OR NV: Alvarado-Gil, Reyes, Rubio
ASM REVENUE AND TAXATION: 7-0-0
YES: Gipson, Ta, Bains, Carrillo, DeMaio, McKinnor, Quirk-Silva
ASSEMBLY FLOOR: 77-0-2
YES: Addis, Aguiar-Curry, Ahrens, Alanis, Alvarez, Arambula, Bains, Bauer-Kahan, Bennett, Berman, Boerner, Bonta, Bryan, Calderon, Caloza, Carrillo, Castillo, Chen, Connolly, Davies, DeMaio, Dixon, Elhawary, Ellis, Flora, Fong, Gabriel, Gallagher, Garcia, Gipson, Jeff Gonzalez, Mark González, Hadwick, Haney, Harabedian, Hart, Hoover, Irwin, Jackson, Kalra, Krell, Lackey, Lee, Lowenthal, Macedo, McKinnor, Muratsuchi, Nguyen, Ortega, Pacheco, Papan, Patel, Patterson, Pellerin, Petrie-Norris, Quirk-Silva, Ramos, Ransom, Celeste Rodriguez, Michelle Rodriguez, Rogers, Blanca Rubio, Sanchez, Schiavo, Sharp-Collins, Solache, Soria, Stefani, Ta, Tangipa, Valencia, Wallis, Ward, Wicks, Wilson, Zbur, Rivas
ABS, ABST OR NV: Ávila Farías, Schultz
UPDATED
VERSION: August 28, 2025
CONSULTANT: Wesley Whitaker / REV. & TAX. / (916) 319-2098 FN: 0001288
SENATE THIRD READING
STR Bill Id:SB 863
Author:(Committee on Revenue and Taxation)
As Amended Ver:August 28, 2025
Majority vote
SUMMARY
Makes various technical and conforming changes to the Revenue and Taxation Code (R&TC) relating to the administration of property taxes, district tax ordinances, cigarette and tobacco products taxes, and motion picture credits under the Corporate Tax (CT) Law.
Major Provisions
- Provides that a property tax remittance (payment) sent by mail is deemed to be received on the date it is received by the county treasurer-tax collector if there is no date shown on the post office cancellation mark stamp or packing slip attached to the outside of the envelope or package containing the remittance.
- Authorizes a county tax collector, when selling a tax-defaulted property at public auction, to reduce the minimum price for the property below the price approved in the resolution by the county's Board of Supervisors when any of the following occur:
- A partial redemption has been made under R&TC Section 4131;
- A partial cancellation has been made under R&TC Section 4985 after that price was fixed by not more than the ratio that the delinquency on the portion so redeemed or canceled bears to the delinquency upon the whole; or,
- The total amount necessary to redeem is decreased due to the removal or reduction of default taxes resulting from the removal or reduction of a special assessment or a direct charge against the property.
- Changes the operative date of a new district ordinance from the first day of a calendar quarter commencing more than 110 days after the adoption of the ordinance to the first day of a calendar quarter commencing more than 110 days after the election where the ordinance proposing the tax was voted on.
- Updates references under the Cigarette and Tobacco Products Tax Law from the "State Board of Equalization" or "board" to the "California Department of Tax and Fee Administration" or "department," as applicable, to reflect the transfer of the board's duties, powers, and responsibilities to the department.
- Clarifies, for purposes of the Corporation Tax Law, that a motion picture credit 3.0 generated by a disregarded single member limited liability company is eligible for assignment to a corporation that, directly or indirectly, owns the disregarded single member limited liability company, or to an affiliated corporation of that corporation.
COMMENTS
- Postmarks: This bill provides a clarification in situations where a mailed property tax payment does not have a postmark or packing slip, which has led to disputes between taxpayers and tax collectors. By clarifying that payments that do not have a dated postmark or packing slip are considered received when they are actually received by the tax collector, this bill seeks to reduce disputes and ensure consistent application of the law for taxpayers.
- Tax-defaulted property sales: Property becomes tax-defaulted land if the property taxes remain unpaid, typically as of 12:01 a.m. on July 1. Property that has become tax-defaulted after five years (or three years in the case of property that is also subject to a nuisance abatement lien) becomes subject to the county tax collector's power to sell in order to satisfy the defaulted property taxes. This process is commonly referred to as a "Chapter 7 Tax Sale".
The county tax collector must attempt to sell the property within four years of becoming subject to sale. The county tax collector may offer the property for sale at public auction, a sealed bid sale, or a negotiated sale to a public agency or qualified nonprofit organization. If no bids are received at a tax sale, an attempt must be made to sell the property at intervals of no more than six year, until it is sold.
Public auctions are the most common way of selling tax-defaulted property. The auction is conducted by the county tax collector, and the property is sold to the highest bidder.
Tax-defaulted properties rendered unusable by their size, location, or other condition, may be offered under a sealed bid to owners of contiguous properties or to holders of a predominant easement or right-of-way easement. After the tax collector notifies eligible bidders of a sealed bid, the bidders respond by mail with a bid price and the highest bidder purchases the property.
County tax collectors are required to notify the State Controller's Office "not less than 45 days nor more than 120 days before the proposed sale." Additionally, R&TC Section 3702 requires the tax collector to publish the intended sale three times in a newspaper of general circulation within the county, at least three weeks prior to the tax sale.
- District tax ordinance operative dates: Existing law provides that a district tax ordinance becomes operative no sooner than the first day of the first calendar quarter commencing more than 110 days after the ordinance's adoption. Historically, cities and counties have generally adopted district tax ordinances on the election date. This provision was intended to allow the CDTFA sufficient time to prepare to administer the new district tax. However, in recent years, more cities and counties have adopted ordinances at various times following voter approval.
This bill changes the operative date of a new district ordinance from the first day of a calendar quarter commencing more than 110 days after the adoption of the ordinance to the first day of a calendar quarter commencing more than 110 days after the election on the ordinance proposing the tax.
- Taxpayer Transparency and Fairness Act of 2017: AB 102 (Committee on Budget), Chapter 16, Statutes of 2017, shifted the responsibility of collecting and administering various excise taxes from the Board of Equalization to the newly created CDTFA, including the Cigarette and Tobacco Products taxes. This bill simply updates references from the "State Board of Equalization" or "board" to the "California Department of Tax and Fee Administration" or "department," as applicable, to reflect the transfer of the board's duties, powers, and responsibilities to the department.
- Motion picture credit cleanup: The Personal Income Tax Law and the CT Law allow various credits against the taxes imposed by those laws, including various motion picture credits, commonly referred to as motion picture credit 1.0, 2.0, 3.0, and 4.0, and the certified studio credit, to be allocated by the California Film Commission. Existing law allows a qualified taxpayer, if a motion picture credit exceeds the taxpayer's tax liability, to elect to assign a portion of the credit to one or more affiliated corporations for each taxable year in which the credit is allowed, as specified. AB 1138 (Chapter 27 of the Statutes of 2025), effective July 3, 2025, among other things, for purposes of the motion picture credit 3.0 and 4.0 and for purposes of the certified studio credit, expands the definition of a qualified taxpayer to include a single member limited liability company that is disregarded for tax purposes. AB 1138 prohibits a motion picture credit 1.0 and 2.0 or certified studio credit generated by a disregarded single member limited liability company from being ineligible for certain reasons for assignment to a corporation that, directly or indirectly, owns the disregarded single member limited liability company, or to an affiliated corporation of that corporation.
This bill would additionally prohibit a motion picture credit 3.0 generated by a disregarded single member limited liability company from being ineligible for those same reasons for assignment to a corporation that, directly or indirectly, owns the disregarded single member limited liability company, or to an affiliated corporation of that corporation.
According to the Author
The Senate Committee on Revenue and Taxation has submitted the following statement in support of this bill:
This year, the Senate Committee on Revenue and Taxation introduced SB 863 to make technical, non-controversial changes to improve tax administration suggested by the California Department of Tax and Fee Administration (CDTFA) and the California Association of County Treasurers and Tax Collectors. SB 863 combines noncontroversial statutory changes into one single bill. Moving these proposals as separate bills, even if technical and noncontroversial, through the legislative process would be much less efficient than consolidating them into one measure. Committee staff distributed these proposals to affected parties to review each proposal before including it in the bill. Should anyone object to an item in the bill, it will be removed.
Arguments in Support
Writing in support of this bill, the California Association of County Treasurers and Tax Collectors notes, in part:
CACTTC is proud to co-sponsor and support SB 863 because it will provide tax collectors the ability to credit the remittance against any amount due as of the date the remittance is received, thereby offering greater clarity and ensuring a fair and transparent process for taxpayers. CACTTC also supports SB 863 because it will authorize a tax collector to reduce the minimum price where the minimum necessary to redeem is decreased due to the removal or reduction of defaulted taxes resulting from the removal or reduction of a special assessment or a direct charge against the property. SB 863 provides tax collectors with a more practical approach to resolving tax-defaulted properties by offering much-needed flexibility in property tax auctions. This helps ensure that properties are sold at fair and reasonable prices, particularly in situations where a portion of the delinquency has been mitigated.
Arguments in Opposition
None on file.
FISCAL COMMENTS
None.
VOTES
SENATE FLOOR: 37-0-3
YES: Allen, Archuleta, Arreguín, Ashby, Becker, Blakespear, Cabaldon, Caballero, Cervantes, Choi, Cortese, Dahle, Durazo, Gonzalez, Grayson, Grove, Hurtado, Jones, Laird, Limón, McGuire, McNerney, Menjivar, Niello, Ochoa Bogh, Padilla, Pérez, Richardson, Seyarto, Smallwood-Cuevas, Stern, Strickland, Umberg, Valladares, Wahab, Weber Pierson, Wiener
ABS, ABST OR NV: Alvarado-Gil, Reyes, Rubio
ASM REVENUE AND TAXATION: 7-0-0
YES: Gipson, Ta, Bains, Carrillo, DeMaio, McKinnor, Quirk-Silva
ASSEMBLY FLOOR: 77-0-2
YES: Addis, Aguiar-Curry, Ahrens, Alanis, Alvarez, Arambula, Bains, Bauer-Kahan, Bennett, Berman, Boerner, Bonta, Bryan, Calderon, Caloza, Carrillo, Castillo, Chen, Connolly, Davies, DeMaio, Dixon, Elhawary, Ellis, Flora, Fong, Gabriel, Gallagher, Garcia, Gipson, Jeff Gonzalez, Mark González, Hadwick, Haney, Harabedian, Hart, Hoover, Irwin, Jackson, Kalra, Krell, Lackey, Lee, Lowenthal, Macedo, McKinnor, Muratsuchi, Nguyen, Ortega, Pacheco, Papan, Patel, Patterson, Pellerin, Petrie-Norris, Quirk-Silva, Ramos, Ransom, Celeste Rodriguez, Michelle Rodriguez, Rogers, Blanca Rubio, Sanchez, Schiavo, Sharp-Collins, Solache, Soria, Stefani, Ta, Tangipa, Valencia, Wallis, Ward, Wicks, Wilson, Zbur, Rivas
ABS, ABST OR NV: Ávila Farías, Schultz
UPDATED
VERSION: August 28, 2025
CONSULTANT: Wesley Whitaker / REV. & TAX. / (916) 319-2098 FN: 0001288
SENATE RULES COMMITTEE Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | SB 863 |
UNFINISHED BUSINESS
Bill No: SB 863
Author: Committee on Revenue and Taxation
Amended: 6/27/25 in Assembly
Vote: 21
SENATE REVENUE AND TAXATION COMMITTEE: 5-0, 4/23/25
AYES: McNerney, Valladares, Ashby, Grayson, Umberg
SENATE FLOOR: 37-0, 5/1/25 (Consent)
AYES: Allen, Archuleta, Arreguín, Ashby, Becker, Blakespear, Cabaldon, Caballero, Cervantes, Choi, Cortese, Dahle, Durazo, Gonzalez, Grayson, Grove, Hurtado, Jones, Laird, Limón, McGuire, McNerney, Menjivar, Niello, Ochoa Bogh, Padilla, Pérez, Richardson, Seyarto, Smallwood-Cuevas, Stern, Strickland, Umberg, Valladares, Wahab, Weber Pierson, Wiener
NO VOTE RECORDED: Alvarado-Gil, Reyes, Rubio
ASSEMBLY FLOOR: 77-0, 7/14/25 (Consent) - See last page for vote
SUBJECT: Taxation
SOURCE: California Association of County Treasurer-Tax Collectors; California Department of Tax & Fee Administration.
DIGEST:
This bill makes four changes to improve tax administration suggested by the California Association of County Treasurer-Tax Collectors and the California Department of Tax & Fee Administration (CDTFA).
Assembly Amendments
(1) clarify that the measure’s deemed received date for property tax payments applies in absence of other dates mentioned in law, (2) add a provision to change the operative date of a new district tax ordinance to commence after the vote on the ordinance instead of the local agency’s adoption of the ordinance, and (3) update references in one section of the Cigarette and Tobacco Products Law from the Board of Equalization (BOE) to CDTFA.
ANALYSIS:
Existing law:
- Provides that property taxes are due in two installments, the first on November 1 and the second on February 1, with delinquency for the second installment occurring on April 10.
- Requires county tax collectors to begin imposing penalties for nonpayment of property taxes for each amount due, plus administrative charges, once taxes become delinquent.
- Deems mailed remittances received as of the date of the postmark on the envelope containing the remittance, or the date on the packing slip or air bill from an independent delivery service.
- Permits tax collectors to also deem the remittance received if it can be proved that the mailing occurred on an earlier date.
- Provides that if payments are made through the tax collector's authorized website or telephone number, the payment is deemed received on the date the taxpayer completes the electronic payment.
- Deems all other electronic payments received on the date the tax collector actually receives the payment.
- States that a property becomes tax defaulted if a property owner does not pay the property taxes due in the current fiscal year before June 30.
- Allows the tax collector to sell a residential property that has been in default for five years, or a commercial property after three years in default, unless the Board of Supervisors sets a five-year period for commercial property.
- Directs tax collectors to sell properties at public auction, but only when bids exceed the “minimum bid,” which is equal to the total amount of outstanding taxes, assessments, penalties, and fees.
- Requires tax collectors to obtain approval from the Board of Supervisors to reduce a minimum bid, unless a partial redemption or cancellation has been made.
- Imposes the sales tax on every retailer engaged in business in this state that sells tangible personal property, and requires them to collect the appropriate tax from the purchase and remit the amount to the California Department of Tax and Fee Administration.
- States that taxes levied by local governments are either general taxes, subject to majority approval of its voters, or special taxes, subject to 2/3 vote (California Constitution, Article XIII C).
- Allows cities, counties, and specified special districts, including the San Francisco Bay Area Rapid Transit District and the Santa Cruz County Metropolitan Transit District, to increase the sales and use tax applied within their jurisdictions, also known as district or transactions and use taxes, for either specific or general purposes pursuant to the California Constitution’s voter approval requirements.
- Precludes a district tax ordinance from becoming operative on other than the first day of a calendar quarter, or prior to the first day of the first calendar quarter, commencing more than 110 days after the adoption of the ordinance.
- Enacts the California Cigarette and Tobacco Products Tax Law, which imposes a tax of $2.87 per package of 20 cigarettes.
- Enacts Taxpayer Transparency and Fairness Act of 2017, which created the CDTFA, and shifted all of the BOE’s statutory tax administration functions to CDTFA (AB 102, Committee on Budget, Chapter 16, Statutes of 2017).
This bill:
- Deems a property tax payment received as of the date of delivery if it does not contain an official postmark in the absence of any other date mentioned in law.
- Allows the tax collector to reduce the minimum bid at a tax sale when defaulted taxes decrease due to the removal or reduction of a special assessment or a direct charge against the property.
- Modifies the period that precludes a district tax ordinance from becoming operative to provide that it is measured from the date voters approve the ordinance at an election, not from the adoption of the ordinance.
- Replace references in one section of the Cigarette and Tobacco Products Licensing Law from BOE to CDTFA.
Background
Minimum Bids. In addition to unpaid property taxes, outstanding taxes and assessments can include direct charges imposed by a county, city, or local agency, such as parcel taxes, benefit assessments, or taxes to repay outstanding bonds. When a local agency wants to cancel or reduce a direct charge, state law does not allow the tax collector to reduce the minimum bid without returning to the Board of Supervisors for approval. In this case, the tax sale must generally wait another year, and all the costs incurred to conduct a tax sale for that property are wasted.
District Tax Ordinances. Existing law provides that a district tax ordinance becomes operative no sooner than the first day of the first calendar quarter commencing more than 110 days after the ordinance's adoption. Historically, cities and counties have generally adopted district tax ordinances on the election date. This provision was intended to allow the CDTFA sufficient time to prepare to administer the new district tax. However, in recent years, more cities and counties have adopted ordinances at various times following voter approval.
These delayed adoptions have led to commensurate delays in administration of newly adopted district taxes. For example, the City of Grass Valley obtained voter approval for a district tax on March 5, 2024, and requested an operative date of July 1, 2024. However, the ordinance was not adopted until April 9, 2024, less time than was required by law for the tax to become operative on July 1. Accordingly, the CDTFA was forced to delay the operative date to October 1, 2024, delaying expected revenues.
FISCAL EFFECT: Appropriation: No Fiscal Com.: No Local: No
Legislative Counsel keyed this bill non-fiscal.
SUPPORT: (Verified 7/16/25)
California Association of County Treasurer-Tax Collectors (co-sponsor)
California Department of Tax & Fee Administration (co-sponsor)
OPPOSITION: (Verified 7/16/25)
None received
ARGUMENTS IN SUPPORT: According to the California Association of County Treasurer-Tax Collectors, “SB 863 … will provide tax collectors the ability to credit the remittance against any amount due as of the date the remittance is received, thereby offering greater clarity and ensuring a fair and transparent process for taxpayers. CACTTC also supports SB 863 because it will authorize a tax collector to reduce the minimum price where the minimum necessary to redeem is decreased due to the removal or reduction of defaulted taxes resulting from the removal or reduction of a special assessment or a direct charge against the property. SB 863 provides tax collectors with a more practical approach to resolving tax-defaulted properties by offering much-needed flexibility in property tax auctions. This helps ensure that properties are sold at fair and reasonable prices, particularly in situations where a portion of the delinquency has been mitigated.”
ASSEMBLY FLOOR: 77-0, 7/14/25
AYES: Addis, Aguiar-Curry, Ahrens, Alanis, Alvarez, Arambula, Bains, Bauer-Kahan, Bennett, Berman, Boerner, Bonta, Bryan, Calderon, Caloza, Carrillo, Castillo, Chen, Connolly, Davies, DeMaio, Dixon, Elhawary, Ellis, Flora, Fong, Gabriel, Gallagher, Garcia, Gipson, Jeff Gonzalez, Mark González, Hadwick, Haney, Harabedian, Hart, Hoover, Irwin, Jackson, Kalra, Krell, Lackey, Lee, Lowenthal, Macedo, McKinnor, Muratsuchi, Nguyen, Ortega, Pacheco, Papan, Patel, Patterson, Pellerin, Petrie-Norris, Quirk-Silva, Ramos, Ransom, Celeste Rodriguez, Michelle Rodriguez, Rogers, Blanca Rubio, Sanchez, Schiavo, Sharp-Collins, Solache, Soria, Stefani, Ta, Tangipa, Valencia, Wallis, Ward, Wicks, Wilson, Zbur, Rivas
NO VOTE RECORDED: Ávila Farías, Schultz
Prepared by: Colin Grinnell / REV. & TAX. / (916) 651-4117
7/16/25 12:52:41
**** END ****
SENATE RULES COMMITTEE Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | SB 863 |
CONSENT
Bill No: SB 863
Author: Committee on Revenue and Taxation
Introduced: 3/19/25
Vote: 21
SENATE REVENUE AND TAXATION COMMITTEE: 5-0, 4/23/25
AYES: McNerney, Valladares, Ashby, Grayson, Umberg
SUBJECT: Real property taxation: tax administration
SOURCE: California Association of County Treasurer-Tax Collectors
DIGEST:
This bill makes two changes to property tax collection law regarding treatment of tax payments without postmarks, and permission for tax collectors to reduce a minimum bid for a property at tax sale.
ANALYSIS:
Existing law:
- Provides that property taxes are due in two installments, the first on November 1 and the second on February 1, with delinquency for the second installment occurring on April 10.
- Requires county tax collectors to begin imposing penalties for nonpayment of property taxes for each amount due, plus administrative charges, once taxes become delinquent.
- Deems mailed remittances received as of the date of the postmark on the envelope containing the remittance, or the date on the packing slip or air bill from an independent delivery service.
- Permits tax collectors to also deem the remittance received if it can be proved that the mailing occurred on an earlier date.
- Provides that if payments are made through the tax collector's authorized website or telephone number, the payment is deemed received on the date the taxpayer completes the electronic payment.
- Deems all other electronic payments received on the date the tax collector actually receives the payment.
- States that a property becomes tax defaulted if a property owner does not pay the property taxes due in the current fiscal year before June 30.
- Allows the tax collector to sell a residential property that has been in default for five years, or a commercial property after three years in default, unless the Board of Supervisors sets a five-year period for commercial property.
- Directs tax collectors to sell properties at public auction, but only when bids exceed the “minimum bid,” which is equal to the total amount of outstanding taxes, assessments, penalties, and fees.
- Requires tax collectors to obtain approval from the Board of Supervisors to reduce a minimum bid, unless a partial redemption or cancellation has been made.
This bill:
- Deems a property tax payment received as of the date of delivery if it does not contain an official postmark.
- Allows the tax collector to reduce the minimum bid at a tax sale when defaulted taxes decrease due to the removal or reduction of a special assessment or a direct charge against the property.
Background
In addition to unpaid property taxes, outstanding taxes and assessments can include direct charges imposed by a county, city, or local agency, such as parcel taxes, benefit assessments, or taxes to repay outstanding bonds. When a local agency wants to cancel or reduce a direct charge, state law does not allow the tax collector to reduce the minimum bid without returning to the Board of Supervisors for approval. In this case, the tax sale must generally wait another year, and all the costs incurred to conduct a tax sale for that property are wasted.
FISCAL EFFECT: Appropriation: No Fiscal Com.: No Local: No
This bill is keyed non-fiscal by Legislative Counsel.
SUPPORT: (Verified 4/24/25)
California Association of County Treasurer-Tax Collectors (source).
OPPOSITION: (Verified 4/24/25)
None received.
ARGUMENTS IN SUPPORT: According to the California Association of County Treasurer-Tax Collectors, “SB 863 … will provide tax collectors the ability to credit the remittance against any amount due as of the date the remittance is received, thereby offering greater clarity and ensuring a fair and transparent process for taxpayers. CACTTC also supports SB 863 because it will authorize a tax collector to reduce the minimum price where the minimum necessary to redeem is decreased due to the removal or reduction of defaulted taxes resulting from the removal or reduction of a special assessment or a direct charge against the property. SB 863 provides tax collectors with a more practical approach to resolving tax-defaulted properties by offering much-needed flexibility in property tax auctions. This helps ensure that properties are sold at fair and reasonable prices, particularly in situations where a portion of the delinquency has been mitigated.”
Prepared by: Colin Grinnell / REV. & TAX. / (916) 651-4117
4/28/25 17:15:01
**** END ****
SENATE COMMITTEE ON REVENUE AND TAXATION
Senator Jerry McNerney, Chair
2025 - 2026 Regular
Bill No: | SB 863 | Hearing Date: | 4/23/25 |
Author: | Committee on Revenue and Taxation | Tax Levy: | No |
Version: | 3/19/25 > | Fiscal: | No |
Consultant: | Grinnell | ||
Real property taxation: tax administration
Makes two changes to property tax collection law regarding tax payments without postmarks and flexibility for tax collectors to continue a tax sale when a taxing entity agrees to reduce or remove a direct charge from the tax bill.
Background
Property taxes are due in two installments, the first on November 1 and the second on February 1, with delinquency for the second installment occurring on April 10. Generally, state law requires county tax collectors to begin imposing penalties of 10% for nonpayment of property taxes for each amount due, plus administrative charges, once taxes become delinquent.
Date of payment received: no postmark. In most cases, the law deems mailed remittances “received” as of the date of the postmark on the envelope containing the remittance, or the date on the packing slip or air bill from an independent delivery service. Tax collectors can also deem the remittance received if it can be proved that the mailing occurred on an earlier date. Additionally, state statutes also provide that if payments are made through the tax collector's authorized website or telephone number, the payment is deemed received on the date the taxpayer completes the electronic payment. For all other electronic payments, the payment is deemed received on the date the tax collector actually receives the payment (SB 823, Committee on Revenue & Taxation, 2009).
Tax-default sales: minimum bid adjustment. If a property owner does not pay the property taxes due in the current fiscal year before June 30, their property becomes tax-defaulted. The tax collector can sell a residential property that has been in default for five years, or a commercial property after three years in default—unless the Board of Supervisors sets a five-year period for commercial property. Upon approval of the sale by the Board of Supervisors, tax collectors sell properties at public auction, but can only accept bids above the “minimum bid,” that is, the total amount of outstanding taxes, assessments, penalties, and fees. In addition to unpaid property taxes, outstanding taxes and assessments can include direct charges imposed by a county, city, or local agency, such as parcel taxes, benefit assessments, or taxes to repay outstanding bonds.
When a local agency wants to cancel or reduce a direct charge, state law does not allow the tax collector to reduce the minimum bid without returning to the Board of Supervisors for approval. In this case, the tax sale must generally wait another year, and all the costs incurred to conduct a tax sale for that property are wasted.
The California Association of County Treasurer-Tax Collectors want to make two changes to property tax law to provides clear statewide guidance to taxpayers and tax collectors when they receive payments without postmarks, and create a modest amount of flexibility for tax collectors to continue a tax sale, should a taxing entity agree to reduce or remove a direct charge from the tax bill.
Proposed Law
Senate Bill 863 deems a property tax payment received as of the date of delivery if it does not contain an official postmark. The measure also allows the tax collector to reduce the minimum bid when defaulted taxes decrease due to the removal or reduction of a special assessment or a direct charge against the property.
State Revenue Impact
No estimate.
Comments
1. Purpose of the bill. The California Association of Country Treasurer-Tax Collectors recently identified changes in property tax law necessary to improve tax collection and tax sales. SB 863 combines these two noncontroversial statutory changes into one single bill. Moving individual proposals as separate bills, even if technical and noncontroversial, through the legislative process is less efficient than consolidating them into one measure. Committee staff distributed these proposals to affected parties to review each proposal before inclusion in the bill. Should anyone object to an item in the bill, the Committee will remove said item.
Support and Opposition
(4/20/25)
Support: California Association of County Treasurers and Tax Collectors (Co-Sponsor)
Opposition: None received.
-- END --
Discussed in Hearing
View Older Hearings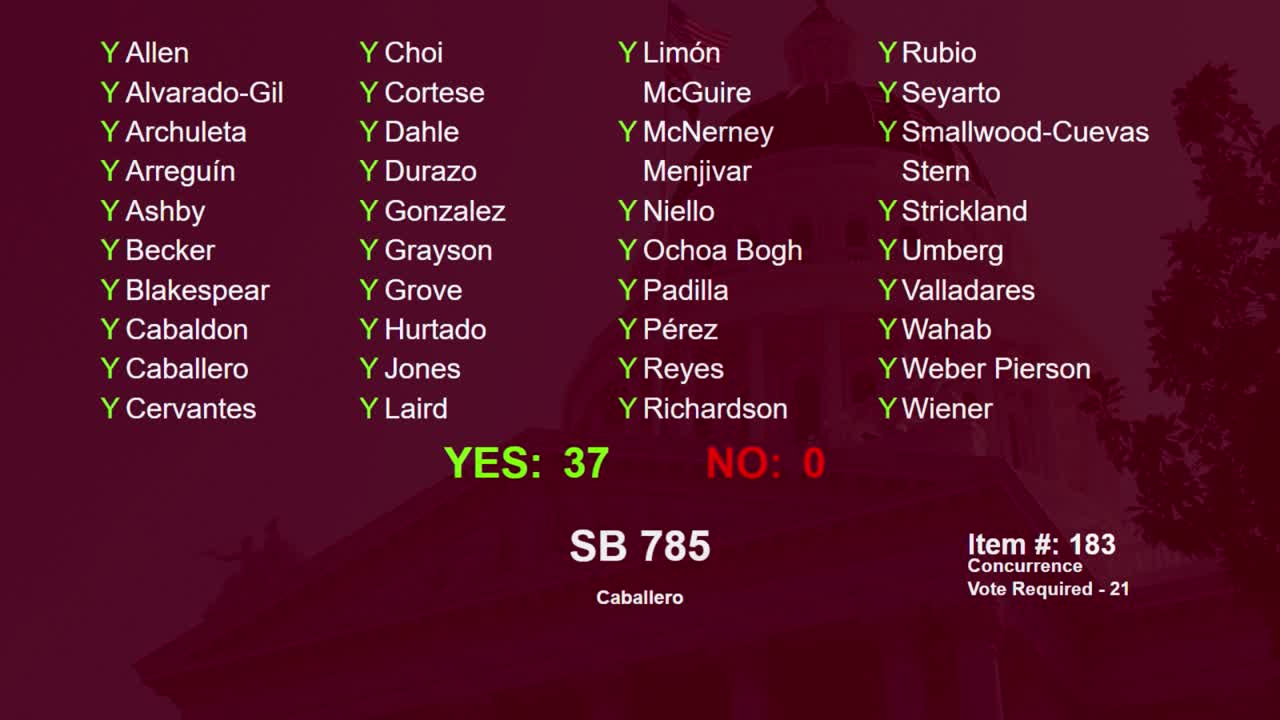
Bill Author
Bill Co-Author(s):