SB 898: Bail: surety insurers.
- Session Year: 2017-2018
- House: Senate
- Latest Version Date: 2018-05-01
Existing law generally regulates the undertaking of bail and the licensing of bail agents, bail permittees, and bail solicitors. Existing law requires an insurer executing an undertaking of bail to do so through a person holding a bail license. Existing law authorizes the Insurance Commissioner to issue bail licenses and to regulate bail licensees. Existing law makes it a public offense to violate these provisions, or any rule of the commissioner made pursuant to these provisions, and makes a violation punishable by a fine not exceeding $10,000, or by imprisonment as specified, or by both that fine and imprisonment.
This bill would require each a surety insurer to report specified information, such as the number and total face value of bail bonds written in the state, to the Insurance Commissioner, the Judicial Council, and the Attorney General on a quarterly and annual basis. Beginning January 1, 2020, the bill would require a bail licensee to post the terms and conditions of its bail contracts online and to translate the terms and conditions of each bail contract into not fewer than 3 and not more than 5 of the most common non-English languages spoken in the county in which the contract is issued. By creating new crimes, the bill would impose a state-mandated local program. The bill would also require the Department of Insurance to conduct a study and make recommendations no later than July 1, 2019, regarding insurers who provide coverage to bail licensees, as specified. on its Internet Web site in English, Spanish, Chinese, Tagalog, Vietnamese, and Korean. The bill, beginning January 1, 2020, would require a bail licensee to provide a bail contract and supporting documents at specified times in plain English, and translations in 5 specified languages upon request. The bill would require a translated document to state in both that language and English that the English version is the official version, and would subject an insurer that knowingly misrepresents information in another language to the penalties for unfair and deceptive acts or practices, effective January 1, 2020. The bill would also require a notice of appointment filed by a bail license applicant to include a copy of a contract between the applicant an a surety insurer, and would require the applicant to provide an updated agreement to the Insurance Commissioner if the contract is amended or superseded. By creating new crimes, the bill would impose a state-mandated local program. The bill would also make related legislative findings and declarations.
The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement.
This bill would provide that no reimbursement is required by this act for a specified reason.
Existing law generally regulates the undertaking of bail and the licensing of bail agents, bail permittees, and bail solicitors. Existing law requires an insurer executing an undertaking of bail to do so through a person holding a bail license. Existing law authorizes the Insurance Commissioner to issue bail licenses and to regulate bail licensees. Existing law makes it a public offense to violate these provisions, or any rule of the commissioner made pursuant to these provisions, and makes a violation punishable by a fine not exceeding $10,000, or by imprisonment as specified, or by both that fine and imprisonment.
This bill would require each bail licensee to post the terms and conditions of its bail contracts online and to translate the terms and conditions of each bail contract into not fewer than 3 and not more than 5 of the most common non-English languages spoken in the county in which the contract is issued. By creating new crimes, the bill would impose a state-mandated local program. The bill would also require the Department of Insurance to conduct a study and make recommendations no later than July 1, 2019, regarding insurers who provide coverage to bail licensees, as specified. The bill would also make related legislative findings and declarations.
The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement.
This bill would provide that no reimbursement is required by this act for a specified reason.
Existing law generally regulates the undertaking of bail and the licensing of bail agents, bail permittees, and bail solicitors. Existing law requires an insurer executing an undertaking of bail to do so through a person holding a bail license.
This bill would require the Department of Insurance to conduct a study and make recommendations no later than July 1, 2019, regarding insurers who provide coverage to bail licensees, as specified. The bill would also make related legislative findings and declarations.
The Legislature finds and declares all of the following:
(a)The for-profit money bail system is a global anomaly, used only in the Philippines and the United States.
(b)Commercial money bail requires people to pay a nonrefundable deposits premium to private companies in order to secure release from jail, often leaving working Californians at risk of losing their jobs, their housing, and even their children.
(c)The commercial money bail system does not improve rates of appearance in court or enhance public safety. It has a coercive effect on people unable to make bail, who are more likely to plead guilty to crimes that they may not have committed in order to get out of jail.
(d)Fewer A report by Color of Change and the American Civil Liberties Union (ACLU) Campaign for Smart Justice states that fewer than 10 insurance companies are behind the vast majority of bail bonds being issued by bail bond agents in the United States. Bail States, and that insurers are increasingly part of larger global companies. They The report also explains that bail insurers collect hundreds of millions of dollars a year and face virtually no risk. By comparison, auto insurers in California average losses of 74 percent. Unlike auto insurance, the risk for bail insurers is completely disconnected from the losses they cover.
(e)For-profit According to that report, for-profit bail insurers are surety companies, but their profits are different than other types of surety insurance. In During the first three months of 2015, the top 100 general surety bond writers had direct losses averaging 13.2 percent. But surety insurers who cover bail bonds have The report notes that some bail companies losses that are minimal, are sometimes almost nonexistent, and according to industry sources are minimal and are often recouped.
(f)One The report cites one large bail insurer has executive who publicly boasted that it the insurer sustained no losses at all in 2014 or 2015. Another An executive for a smaller bail insurer has publicly stated that it has not paid on any losses for 17 years.
(g)In 2015, 63 percent of people in California jails were either awaiting trial or sentencing. In 2016, that climbed to 66 percent. As compared with the rest of the country, California has relied on pretrial detention at much higher rates than other states.
(h)Californias existing pretrial detention practices allow a persons wealth, rather than the persons likelihood of success on pretrial release, to determine whether the person will remain in jail before the persons case is resolved.
(i)While unnecessary pretrial detention has been found to increase the likelihood that some defendants will commit new crimes, appropriate pretrial release can reduce recidivism.
SEC. 2.Section 1820.5 is added to the Insurance Code, to read:1820.5.Each bail licensee shall post the terms and conditions of its bail contracts online. Each bail licensee shall translate the terms and conditions of each bail contract issued into not fewer than three and not more than five of the most common non-English languages spoken in the county in which the contract is issued.SEC. 3.Section 1824 is added to the Insurance Code, to read:1824.(a)The Department of Insurance shall conduct a study and, no later than July 1, 2019, make recommendations regarding insurers who provide coverage to bail licensees. Specifically, the report shall provide an analysis of both of the following:(1)The relationship between risk to insurers and rates charged.(2)A comparison of the risk and rates analyzed pursuant to paragraph (1) and the risk and rates of automobile insurers in California.(b)(1)A report to be submitted pursuant to subdivision (a) shall be submitted in compliance with Section 9795 of the Government Code.(2)Pursuant to Section 10231.5 of the Government Code, this section is repealed on January 1, 2023. SEC. 2.Section 1802.1 of the Insurance Code is amended to read:1802.1.Every (a)An applicant for a license to act as a bail agent shall file with the commissioner a notice of appointment executed by a surety insurer or its authorized representative authorizing that applicant to execute undertakings of bail and to solicit and negotiate those undertakings on its behalf. Additional notices of appointment may be filed by other surety insurers, upon the payment for each additional notice of the fees specified in subdivision (a) of Section 1811, before the license is issued and thereafter, as long as the license remains in force. Each appointment shall, by its terms, continue in force until any of the following occur:
(a)(1)Termination of the bail agents license.
(b)(2)The end of the license term, if the fee provided in subdivision (e) of Section 1811 for filing a renewal application is not paid.
(c)(3)The filing of a notice of termination by the insurer, insurer or its representative, or by the bail agent.
(b)The notice of appointment filed with the commissioner pursuant to subdivision (a) shall include a copy of any contract agreed upon by the surety insurer and the applicant to execute undertakings of bail and to solicit and negotiate those undertakings of bail. If a contract between the surety insurer and the applicant is amended or superseded, the applicant shall provide a copy of the updated agreement to the commissioner. The contract shall be made available to a California court or person identified in subdivision (a) of Section 1269b of the Penal Code upon request.
SEC. 3.Section 1820.5 is added to the Insurance Code, to read:1820.5.(a)A bail licensee shall post on its Internet Web site the terms and conditions of bail contracts or supporting documents utilized by the licensee. These terms and conditions shall be posted in English, Spanish, Chinese, Tagalog, Vietnamese, and Korean.
(b)Before negotiating or executing a bail contract, a licensee shall provide an arrestee, or a person purporting to act on behalf of an arrestee, a written notice indicating the availability of bail contract documents translated into Spanish, Chinese, Tagalog, Vietnamese, and Korean. The notice text shall be in English and shall include the same text in Spanish, Chinese, Tagalog, Vietnamese, and Korean.
(c)During the negotiation of a bail contract, the bail licensee shall provide all of the following to an arrestee or a person purporting to act on behalf of an arrestee:
(1)The bail contract and supporting documents in plain, understandable English.
(2)Upon request, the bail contract and supporting documents translated into Spanish, Chinese, Tagalog, Vietnamese, or Korean.
(3)True and correct copies of the bail contract and supporting documents executed after negotiation.
(d)A bail contract shall disclose both of the following:
(1)The name of the insurer providing surety.
(2)A contact for the Department of Insurance for complaints.
(e)The English version of a bail contract or supporting documents shall be the official version. A document translated into a language other than English shall contain a disclosure statement in both that language and English stating that the English version is the official version and the translated version is for informational purposes only.
(f)An insurer that knowingly misrepresents information provided in a language other than English shall be subject to Article 6.5 (commencing with Section 790) of Chapter 1.
(g)This section shall become operative on January 1, 2020.
SEC. 4.Section 1824 is added to the Insurance Code, to read:1824.(a)A surety insurer transacting bail in California shall report the following information regarding the insurers business operations during a calendar quarter to the commissioner, the Judicial Council, and the Attorney General within 30 days of the end of that calendar quarter:
(1)The number of bail bonds written in the state, itemized by county and bail agent.
(2)The total face value of the bail bonds written in the state, itemized by county and bail agent.
(3)The total gross premium collected by the surety insurers appointed bail agents, itemized by county and bail agent.
(4)The net premium remitted to the surety insurer, itemized by county and bail agent.
(5)The identification of all bail agents appointed by the surety insurer to conduct business in California, including name, license number, and locations, as well as the total number of bail agents appointed by the surety insurer in California.
(6)The identification of all of the surety insurers pending bail agent appointments, including name, license number, and locations, as well as the total number of the surety insurers pending bail agent appointments in California.
(7)A description of a disciplinary action, including, but not limited to, termination and restriction on activities, taken by the surety insurer against an appointed bail agent. The description shall include the identification of the agent subject to disciplinary action, the reason for the disciplinary action, and the terms and duration of the disciplinary action.
(8)A description of a notice of forfeiture letter relating to a California defendant received by the surety insurer. The description shall include the defendants name, court location, criminal case number, bond number, amount paid, and entity paying the forfeiture, itemized by county and bail agent.
(9)A description of a surrender or arrest pursuant to Section 1300 or 1301 of the Penal Code. The description shall include the defendants name, booking number, criminal case number, bond number, bail amount, court location, and all documentation related to the return of premium pursuant to Section 2090 of Title 10 of the California Code of Regulations.
(b)A surety insurer transacting bail in California shall annually submit the following documents to the commissioner, the Judicial Council, and the Attorney General:
(1)Current copies of any procedures used by the surety insurer relating to the screening, selection, and appointment process for licensed bail agents.
(2)Current copies of any standard bail agent producer or subproducer underwriting agreements used by the surety insurer.
(3)Current copies of bail agent producer policies, guidelines, procedures, rules, manuals, or similar documents used or issued by the surety insurer relating to any of the following:
(A)Bail underwriting rules.
(B)Company ethics and bail agent conduct.
(C)Forfeiture process.
(D)Financial reporting procedures.
(E)Rules and protocols regarding surrendering a defendant to jail.
(F)Credit bail process.
(G)Collateral retention.
SEC. 4.SEC. 5.No reimbursement is required by this act pursuant to Section 6 of Article XIIIB of the California Constitution because the only costs that may be incurred by a local agency or school district will be incurred because this act creates a new crime or infraction, eliminates a crime or infraction, or changes the penalty for a crime or infraction, within the meaning of Section 17556 of the Government Code, or changes the definition of a crime within the meaning of Section 6 of Article XIIIB of the California Constitution.
The Legislature finds and declares all of the following:
(a)The for-profit money bail system is a global anomaly, used only in the Philippines and the United States.
(b)Commercial money bail requires people to pay nonrefundable deposits to private companies in order to secure release from jail, often leaving working Californians at risk of losing their jobs, their housing, and even their children.
(c)The commercial money bail system does not improve rates of appearance in court or enhance public safety. It has a coercive effect on people unable to make bail, who are more likely to plead guilty to crimes that they may not have committed in order to get out of jail.
(d)Fewer than 10 insurance companies are behind the vast majority of bail bonds being issued by bail bond agents in the United States. Bail insurers are increasingly part of larger global companies. They collect hundreds of millions of dollars a year and face virtually no risk. By comparison, auto insurers in California average losses of 74 percent. Unlike auto insurance, the risk for bail insurers is completely disconnected from the losses they cover.
(e)For-profit bail insurers are surety companies, but their profits are different than other types of surety insurance. In 2015, the top 100 general surety bond writers had direct losses averaging 13.2 percent. But surety insurers who cover bail bonds have losses that are minimal, are sometimes almost nonexistent, and according to industry sources are often recouped.
(f)One large bail insurer has publicly boasted that it sustained no losses at all in 2014 or 2015. Another smaller bail insurer has publicly stated that it has not paid on any losses for 17 years.
(g)In 2015, 63 percent of people in California jails were either awaiting trial or sentencing. In 2016, that climbed to 66 percent. As compared with the rest of the country, California has relied on pretrial detention at much higher rates than other states.
(h)Californias existing pretrial detention practices allow a persons wealth, rather than the persons likelihood of success on pretrial release, to determine whether the person will remain in jail before the persons case is resolved.
(i)While unnecessary pretrial detention has been found to increase the likelihood that some defendants will commit new crimes, appropriate pretrial release can reduce recidivism.
SEC. 2.Section 1820.5 is added to the Insurance Code, to read:1820.5.Each bail licensee shall post the terms and conditions of its bail contracts online. Each bail licensee shall translate the terms and conditions of each bail contract issued into not fewer than three and not more than five of the most common non-English languages spoken in the county in which the contract is issued.
SEC. 2.SEC. 3.Section 1824 is added to the Insurance Code, to read:1824.(a)The Department of Insurance shall conduct a study and, no later than July 1, 2019, make recommendations regarding insurers who provide coverage to bail licensees. Specifically, the report shall provide an analysis of both of the following:
(1)The relationship between risk to insurers and rates charged.
(2)A comparison of the risk and rates analyzed pursuant to paragraph (1) and the risk and rates of automobile insurers in California.
(b)(1)A report to be submitted pursuant to subdivision (a) shall be submitted in compliance with Section 9795 of the Government Code.
(2)Pursuant to Section 10231.5 of the Government Code, this section is repealed on January 1, 2023.
SEC. 4.No reimbursement is required by this act pursuant to Section 6 of Article XIIIB of the California Constitution because the only costs that may be incurred by a local agency or school district will be incurred because this act creates a new crime or infraction, eliminates a crime or infraction, or changes the penalty for a crime or infraction, within the meaning of Section 17556 of the Government Code, or changes the definition of a crime within the meaning of Section 6 of Article XIIIB of the California Constitution.
The Legislature finds and declares all of the following:
(a)The for-profit money bail system is a global anomaly, used only in the Philippines and the United States.
(b)Commercial money bail requires people to pay nonrefundable deposits to private companies in order to secure release from jail, often leaving working Californians at risk of losing their jobs, housing, and even their children.
(c)The commercial money bail system does not improve rates of appearance in court or enhance public safety. It has a coercive effect on people unable to make bail, who are more likely to plead guilty to crimes that they may not have committed in order to get out of jail.
(d)Fewer than 10 insurance companies are behind the vast majority of bail bonds being issued by bail bond agents in the United States. Bail insurers are increasingly part of larger global companies. They collect hundreds of millions of dollars a year and face virtually no risk. By comparison, auto insurers in California average losses of 74 percent. Unlike auto insurance, the risk for bail insurers is completely disconnected from the losses they cover.
(e)For-profit bail insurers are surety companies, but their profits are different than other types of surety insurance. In 2015, the top 100 general surety bond writers had direct losses averaging 13.2 percent. But surety insurers who cover bail bonds have losses that are minimal, sometimes almost nonexistent, and according to industry sources often recouped.
(f)One large bail insurer has publicly boasted that it sustained no losses at all in 2014 or 2015. Another smaller bail insurer has publicly stated that it has not paid on any losses for 17 years.
(g)In 2015, 63 percent of people in California jails were either awaiting trial or sentencing. In 2016, that climbed to 66 percent. As compared with the rest of the country, California has relied on pretrial detention at much higher rates than other states.
(h)Californias existing pretrial detention practices allow a persons wealth, rather than the persons likelihood success on pretrial release, determine whether the person will remain in jail before the persons case is resolved.
(i)While unnecessary pretrial detention has been found to increase the likelihood that some defendants will commit new crimes, appropriate pretrial release can reduce recidivism.
SEC. 2.Section 1824 is added to the Insurance Code, to read:1824.(a)The Department of Insurance shall conduct a study and, no later than July 1, 2019, make recommendations regarding insurers who provide coverage to bail licensees. Specifically, the report shall provide an analysis of both of the following:
(1)The relationship between risk to insurers and rates charged.
(2)A comparison of the risk and rates analyzed pursuant to paragraph (1) and the risk and rates of automobile insurers in California.
(b)(1)A report to be submitted pursuant to subdivision (a) shall be submitted in compliance with Section 9795 of the Government Code.
(2)Pursuant to Section 10231.5 of the Government Code, this section is repealed on January 1, 2023.
|
Date
|
Status
|
|---|---|
| Jun 27, 2018 | June 27 set for second hearing canceled at the request of author. |
| Jun 20, 2018 | June 20 set for first hearing canceled at the request of author. |
| Jun 11, 2018 | Referred to Com. on INS. |
| May 29, 2018 | In Assembly. Read first time. Held at Desk. |
| May 29, 2018 | Read third time. Passed. (Ayes 27. Noes 11.) Ordered to the Assembly. |
| May 25, 2018 | From committee: Do pass. (Ayes 5. Noes 2.) (May 25). |
| May 23, 2018 | Set for hearing May 25. |
| May 22, 2018 | May 22 hearing: Placed on APPR. suspense file. |
| May 14, 2018 | Set for hearing May 22. |
| May 1, 2018 | Read second time and amended. Re-referred to Com. on APPR. |
| Apr 30, 2018 | From committee: Do pass as amended and re-refer to Com. on APPR. (Ayes 8. Noes 0.) (April 25). |
| Apr 6, 2018 | Set for hearing April 24. |
| Apr 4, 2018 | Re-referred to Com. on INS. |
| Mar 21, 2018 | From committee with author's amendments. Read second time and amended. Re-referred to Com. on RLS. |
| Jan 24, 2018 | Referred to Com. on RLS. |
| Jan 16, 2018 | From printer. May be acted upon on or after February 15. |
| Jan 12, 2018 | Introduced. Read first time. To Com. on RLS. for assignment. To print. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| May 29, 2018 | Senate 3rd Reading SB898 Hertzberg et al. | Senate Floor |
Passed |
|
| May 25, 2018 | Do pass | Senate Standing Committee on Appropriations |
Passed |
|
| May 22, 2018 | Placed on suspense file | Senate Standing Committee on Appropriations |
Passed |
|
| Apr 25, 2018 | Do pass as amended, but first amend, and re-refer to the Committee on [Appropriations] | Senate Standing Committee on Insurance |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
Date of Hearing: June 27, 2018
ASSEMBLY COMMITTEE ON INSURANCE
Tom Daly, Chair
SBPCA Bill Id:SB 898
Author:(Hertzberg) – As Amended Ver:May 1, 2018
SENATE VOTE: 27-11
SUBJECT: Bail: surety insurers
SUMMARY: Requires bail documents to be translated into specific languages and bail sureties to submit data to the Department of Insurance (DOI). Specifically, this bill:
- States legislative findings regarding the current bail system in California.
- Requires a bail agent to submit the agent's contract with a surety when filing a notice of appointment with the DOI.
- Requires a bail agent to translate the terms and conditions of its bail contract or supporting documents into five languages (Spanish, Chinese, Tagalog, Vietnamese, and Korean) and post those translations on its website.
- Requires a bail agent to provide bail documents in five languages (Spanish, Chinese, Tagalog, Vietnamese, and Korean).
- Requires a bail agent to provide a notice of the availability of translated documents before negotiating or executing a bail contract.
- Requires the notice to include the same text in each of the five specified languages.
- Requires a bail agent to provide the following during the negotiation of a bail contract:
(a) The bail contract and supporting documents in plain, understandable English.
(b) Upon request, the bail contract and supporting documents translated into Spanish, Chinese, Tagalog, Vietnamese, or Korean.
(c) True and correct copies of the bail contract and supporting documents executed after negotiation.
- Requires a bail contract shall disclose the name of the insurer providing surety and a contact for the Department of Insurance for complaints.
- Specifies that the English language version of the contract is the official version.
- Provides that a person who knowingly misrepresents information in documents required to be translated by this bill is engaging in an unfair insurance practice and is subject to penalties.
- Delays implementation of the new translation requirements until January 1, 2020.
- Requires a bail surety to report the following information to commissioner, the Judicial Council, and the Attorney General on a quarterly basis:
(a) The number of bail bonds written in the state, itemized by county and bail agent.
(b) The total face value of the bail bonds written in the state, itemized by county and bail agent.
(c) The total gross premium collected by the surety insurer’s appointed bail agents, itemized by county and bail agent.
(d) The net premium remitted to the surety insurer, itemized by county and bail agent.
(e) The identification of all bail agents appointed by the surety insurer to conduct business in California, including name, license number, and locations, as well as the total number of bail agents appointed by the surety insurer in California.
(f) The identification of all of the surety insurer’s pending bail agent appointments, including name, license number, and locations, as well as the total number of the surety insurer’s pending bail agent appointments in California.
(g) A description of a disciplinary action, including, but not limited to, termination and restriction on activities, taken by the surety insurer against an appointed bail agent. The description shall include the identification of the agent subject to disciplinary action, the reason for the disciplinary action, and the terms and duration of the disciplinary action.
(h) A description of a notice of forfeiture letter relating to a California defendant received by the surety insurer. The description shall include the defendant’s name, court location, criminal case number, bond number, amount paid, and entity paying the forfeiture, itemized by county and bail agent.
(i) A description of a surrender or arrest pursuant to Section 1300 or 1301 of the Penal Code. The description shall include the defendant’s name, booking number, criminal case number, bond number, bail amount, court location, and all documentation related to the return of premium pursuant to Section 2090 of Title 10 of the California Code of Regulations.
- Requires a bail surety to submit the following documents to the commissioner, the Judicial Council, and the Attorney General on an annual basis:
(a) Current copies of any procedures used by the surety insurer relating to the screening, selection, and appointment process for licensed bail agents.
(b) Current copies of any standard bail agent producer or subproducer underwriting agreements used by the surety insurer.
(c) Current copies of bail agent producer policies, guidelines, procedures, rules, manuals, or similar documents used or issued by the surety insurer relating to any of the following:
(A) Bail underwriting rules.
(B) Company ethics and bail agent conduct.
(C) Forfeiture process.
(D) Financial reporting procedures.
(E) Rules and protocols regarding surrendering a defendant to jail.
(F) Credit bail process.
(G) Collateral retention.
EXISTING LAW:
- Establishes a comprehensive system to regulate insurers, including sureties, and the sale of insurance in California.
- Establishes a comprehensive system to regulate property/casualty insurance rates.
- Permits a court to release an arrestee after the arrestee posts bail in the form of a bail bond issued by a surety.
- Requires individuals transacting bail to be licensed by the Department of Insurance.
FISCAL EFFECT: According to the Senate Appropriations Committee:
This bill will result in additional workload for CDI to review all bail contracts for accuracy of translation at an estimated to cost to the Insurance Fund of $29,000 in FY 2018-19 and $126,000 in FY 2019-20. There may be unknown potential revenue from civil penalties imposed.
COMMENTS:
- Purpose. According to the author, there is little information available about the surety insurers who underwrite bail bonds in California. Bail contracts contain complex provisions detailing installment plans, property liens, co-signing by family and friends, invasive surveillance, and variable costs. The author points to a UCLA School of Law study in 2017 that revealed that the industry enjoys unfettered power over their customers, who lack protections. According to the study, “We examined more than 400 bail bond company websites across the 58 counties to find that fewer than 15% of companies provide copies of their agreements online for review prior to signing." The author cites one large bail insurer that has publicly boasted that it sustained no losses at all in 2014 or 2015, and another smaller bail insurer has publicly stated that it did not pay any losses for 17 years. This bill would require bail documents to be translated into five key languages and allow the Department of Insurance to collect data from bail sureties to better inform policy deliberations regarding California's bail system.
- Bail. Once a person is arrested on a criminal charge and booked into a jail, the question is whether the accused remains in custody. Depending on many factors, an accused may be released to await court dates on his or her “own recognizance,” or “bail” will be set. If bail is set, that means a specific amount of money, usually in the form of a bail bond, is required to be paid to the courts in order to secure the appearance of the accused in court. Bail is usually determined by a “schedule” or the accused can have a bail hearing in front of a judge. The bail schedule has pre-set amounts for a particular crime. If a bail hearing is warranted, a judge determines the amount of the bail bond. If an accused does not wish to pay the full amount ordered by the court for release, or cannot afford the full amount, the accused may seek the services of a bail agent. Under existing law, a bail agent must be solicited for bail directly by the arrestee, the arrestee’s attorney of record, or an adult friend or family member. The bail agent may post bail for the accused as a guarantee for the person’s appearance at mandated court hearings and for release from custody.
In California, a bail agent is a person licensed and regulated by the department and will post the bond for the accused. A bail agent works with one or more bail surety companies, which essentially operate as an insurer backing the bail bond. In this instance, the bail agent takes responsibility for the accused making all court appearances and if the accused fails to appear, the bail agent will be the party responsible to pay the court the full amount of the bail bond.
Bail bonds may be negotiated in several ways. Most commonly, a bail agent charges eight or ten percent of the bail bond, commonly referred to as premium. This is the bail agent’s commission. The accused does not get any of this money back unless the bail agent chooses to rebate monies back to the accused. For example, on a $25,000 bail, the ten percent premium paid to the bail agent is $2,500. In turn, the bail agent must pay the surety a percentage of the $2,500 based on the bail agent's contract with the surety insurer involved. Collateral may take many forms, including a lien on house or a car. When all appearances are made and the case resolved, the money provided to the court for bail will go back to the party that paid – either the accused or the bail agent. If the accused fails to appear for any court appearance at any time, that money is forfeited to the court and a warrant is issued for the arrest of the person.
- Suggested Amendments. The author should consider accepting the following amendments:
- Remove the findings and declarations.
- Remove the requirement that a bail agent submit their contract with the surety when submitting a notice of appointment.
- Add a requirement for the Insurance Commissioner to study the profitability of bail sureties and bail agents and report the findings to the Legislature, Attorney General and Judicial Council.
- Require bail agents that have translated bail documents into languages other than the five required by the bill, to make those translations available on the same terms as the mandatory languages.
- Eliminate the requirement for a bail surety to report required information to the Attorney General and Judicial Council.
- Permit the Insurance Commissioner to provide data reported by bail sureties to the Attorney General or Judicial Council upon request.
- Specify that certain data elements be reported annually (instead of quarterly) and that those data elements must be reported on April 1 of the following year.
- Remove the requirement to report bail agents appointed by each surety and any pending appointments.
- Eliminate the requirement to report forfeiture data itemized by bail agent and specify that the source of payment on a forfeiture must only be provided if it is available.
- Specify that when reporting data on surrenders, a bail surety must only provide documentation required by DOI regulations.
- Require that the annual submission of bail surety documents begin on July 1, 2019.
- Remove the requirement to submit information regarding bail underwriting.
- Require a bail surety, following the initial submission, to only report any documents that have changed since the prior submission.
- Provide that the information provided by bail sureties under this bill is confidential and not subject to disclosure under the Public Records Act, subpoena, and inadmissible in a civil proceeding.
REGISTERED SUPPORT / OPPOSITION:
Support
California Labor Federation
Department of Insurance
Ella Baker Center for Human Rights
Opposition
None received.
Analysis Prepared by: Paul Riches / INS. / (916) 319-2086
Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | SB |
THIRD READING
Bill No: SB 898
:
SENATE INSURANCE COMMITTEE: 8-0, 4/25/18
AYES: Glazer, Hernandez, Hueso, Lara, Mitchell, Newman, Portantino, Roth
NO VOTE RECORDED: Gaines, Berryhill, Galgiani, Moorlach, Morrell
SENATE APPROPRIATIONS COMMITTEE: 5-2, 5/25/18
AYES: Lara, Beall, Bradford, Hill, Wiener
NOES: Bates, Nielsen
DIGEST:
This bill requires bail agents to translate their contracts into five non-English languages and requires them to post the English version and translations online, and requires bail agents and bail companies to submit specified information and documents to the California Department of Insurance (CDI), Judicial Council, and Attorney General.
Existing law:
- Requires a bail company to be licensed and regulated as an insurer by CDI.
- Requires a company to execute a bail bond through a bail agent and to hold a portion of the commission in a “build-up fund” (BUF) for the purpose of paying losses arising from bonds written by that agent.
- Provides that a violation of the statutory provisions that specifically apply to bail agents (including those added by this bill) may be prosecuted as a crime punishable by no more than one year in jail or prison, a fine not exceeding $10,000, or both.
This bill:
- Makes findings and declarations related to the commercial bail industry and California’s use of pretrial detention.
- Requires a bail agent to file with CDI a copy of any contract to transact bail on a company’s behalf and provides that the contract be made available to any California court and other persons, as specified.
- Requires a bail agent, beginning on January 1, 2020, to post the terms and conditions of the consumer contracts online.
- Requires bail agents, beginning on January 1, 2020, to translate their contracts into Spanish, Chinese, Tagalog, Vietnamese, and Korean, to provide certain notices when or before the contract is executed, and to post the translated contracts online.
- Requires a bail company to submit certain information and documents, annually or quarterly as specified, to CDI, Judicial Council, and the Attorney General.
A bail bond is a contract between a bail company and the court. The court releases the accused and the company agrees to pay the full bail amount if the accused fails to appear at required court appearances. The most recent data specific to California shows that companies wrote 176,000 bonds in 2013 with a total face value of $4.08 billion. In a single transaction, there are at least three separate contracts involved: the bail bond (between the company and the court), the agreement to transact bail between the agent and the company, and the purchase agreement between the consumer and the company.
Consumers primarily interact with a bail agent who will underwrite and issue the bond on behalf of the company. Bond premiums run between 7 to 10% of the bail amount. The company collects about 10 to 15% which it uses to pay operating costs, premium tax, and other expenses, and places around 5% in a BUF specific to each agent. The agent keeps about 80% of the premium. The BUF accumulates over time and may be used to satisfy forfeited bonds; the company will release the remaining BUF assets to the agent when the appointment is terminated.
An agent may work with more than one company, but each company must separately appoint the agent and notify CDI. Agents must indemnify the company against losses related to the transaction (usually out of the BUF). This bill requires a bail agent to submit a copy of the agent-company agreement to CDI.
Because the bond gives the accused the power to trigger substantial liabilities on the part of the company, the purchase contract signed by the accused and any co-signers often contains provisions designed to ensure the recovery of the accused (if they fail to appear), avoid forfeiture of the bond, or cover related losses. With large bonds, co-signers may be required to execute a deed on their own property as collateral subject to foreclosure if the bond is forfeited.
These contracts are often executed under urgent and dire circumstances. Many provisions might be difficult to understand, especially for consumers who do not speak English. This bill, beginning January 1, 2020, requires agents to post the contracts online, as well as translate and post their contracts in Spanish, Chinese, Tagalog, Vietnamese, and Korean.
Since most activity related to bail bonds is handled by agents in a decentralized fashion, little data on the California market is available. This bill requires a company to submit to CDI, the Attorney General, and the Judicial Council relevant information and documents about bail bonds and industry practices.
FISCAL EFFECT: Appropriation: Fiscal Com.: Local:
According to the Senate Appropriations Committee, this bill will result in additional workload for CDI to review all bail contracts for accuracy of translation at an estimated to cost to the Insurance Fund of $29,000 in FY 2018-19 and $126,000 in FY 2019-20. There may be unknown potential revenue from civil penalties imposed.
There may also be unknown costs to the General Fund related to the potential prosecution and incarceration of violators. The proposed 2018-19 per capita cost to house a person in a state prison is $80,729 annually, with an annual marginal rate per inmate of between $10,000 and $12,000. The average contract-prison rate cost per inmate is over $30,000 annually. The actual costs would depend on how many defendants are sentenced to prison for these violations.
Additionally, there may be unknown, potentially significant workload cost to the Trial Court Trust Fund from pressures on the court to adjudicate charges brought against defendants who violate the provisions of this bill. While the courts are not funded on a workload basis, an increase in workload could result in delayed court services and would put pressure to fund additional staff and resources.
American Civil Liberties Union of California
California Department of Insurance
California Labor Federation
Ella Baker Center for Human Rights
OPPOSITION: (Verified 5/25/18)
Golden State Bail Agents Association
ARGUMENTS IN SUPPORT: The California Labor Federation argues that bail insurer contracts contain exploitive terms including payday lender type installment plans, property liens, co-signing by family and friends, invasive surveillance, and unpredictable costs. The lack of transparency, oversight, and review of these practices can have devastating impacts on low-income families.
ARGUMENTS IN OPPOSITION: The Golden State Bail Agents Association (GSBAA) argues that roughly 90% of licensees are employees of a bail agency and the bill places an unreasonable burden on employees. GSBAA suggests that CDI provide model forms in non-English languages (similar to those provided by the Department of Business Oversight for mortgage terms as required by Civil Code §1632.5) and that CDI collect and post the purchase contracts. GSBAA also argues that there is no good reason why the same annual and quarterly reports must be sent to three different agencies; CDI should receive them and make the information available on request to agencies and members of the public.
5/26/18 15:20:25
**** END ****
SENATE COMMITTEE ON APPROPRIATIONS
Senator Ricardo Lara, Chair
2017 - 2018 Regular Session
SB 898 (Hertzberg) - Bail: surety insurers
Version: May 1, 2018 | Policy Vote: INS. 8 - 0 |
Urgency: No | Mandate: Yes |
Hearing Date: May 22, 2018 | Consultant: Debra Cooper |
This bill meets the criteria for referral to the Suspense File.
Bill Summary:
SB 898 would require a surety insurer to report specified information, such as the number and total face value of bail bonds written in the state, to the Insurance Commissioner, the Judicial Council, and the Attorney General on a quarterly and annual basis and would specify the requirements that a bail licensee must follow regarding translation of bail contracts in five specified languages.
Fiscal Impact:
- Additional workload for the Department of Insurance (CDI) to review all bail contracts for accuracy of translation is estimated to cost $29,000 in FY 2018-19 and $126,000 in FY 2019-20. (Insurance Fund)
- Unknown, potential increase in state costs for longer commitments to state prison for persons found guilty of violating the provisions of this bill. The proposed 2018-19 per capita cost to house a person in a state prison is $80,729 annually, with an annual marginal rate per inmate of between $10,000 and $12,000. The average contract-prison rate cost per inmate is over $30,000 annually. The actual costs would depend on how many defendants are sentenced to prison for these violations. (GF)
- Unknown, potentially significant workload cost pressures to the court to adjudicate charges brought against defendants who violate the provisions of this bill. While the courts are not funded on a workload basis, an increase in workload could result in delayed court services and would put pressure on the General Fund to fund additional staff and resources. (GF*)
- Unknown potential revenue from civil penalties imposed on bail licensees for knowingly misrepresenting information provided in a translated document.
*Trial Court Trust Fund
Background:
When arrested or held in pretrial custody, a person accused of a crime has the right to be released on bail (except under certain circumstances, such as when the alleged crime is very serious or they are being held on another charge). The accused, or sometimes a friend or family member, may secure release by posting cash or a property bond; however, many lack the assets and must rely on a bail bond issued by a commercial bail company (if not released on their own recognizance or if charges are not filed or they are dropped before they are released). In order to secure a bond, the accused, and possibly a co-signor must indemnify the bail company against losses resulting from the transaction. The court will accept a bail bond from an admitted insurer in lieu of a full cash deposit and release the accused.
Bonds are a contract between a bail company and the court. Bonds are surety contracts, the surety promises to cover a third-party’s costs if the consumer breaks a promise or fails to perform a legal or contractual duty. Surety companies are highly regulated by CDI as insurers. Bail companies are surety companies that specialize in bail.
Bail agents typically work as independent contractors and may work with more than one bail company. Each company must separately appoint the agent to represent it in bail bond transactions and notify CDI. Consumers primarily interact with a bail agent who is appointed to represent the bail company in the transaction. Bail agents are required to sign an indemnity agreement that covers the bail company’s losses related to the transaction. The arrangement motivates the agent to take a personal role to avoid losses. For their efforts, agents receive the bulk of the premium.
Bail and other types of bonds are often referred to as forms of “surety insurance,” but surety and insurance are really cousins within a family of risk mitigation tools. Although issued by insurers, surety bonds (and bail bonds especially) differ from insurance policies in design and purpose. Insurance could be said to help innocent parties recover from losses through a cooperative effort where every participant contributes a little to help an unfortunate few. Surety arrangements are designed to insulate innocent parties (including the surety) from paying for losses caused by those who have broken a promise or obligation.
Proposed Law:
This bill would:
- Make various Legislative findings and declarations related to the commercial bail industry and California’s use of pretrial detention;
- Require a notice of appointment executed by a surety insurer filed with the commissioner to include a copy of any contract agreed upon by the surety insurer and the applicant to execute undertakings of bail and to solicit and negotiate those undertakings of bail and a copy of the updated agreement if a contract is amended or superseded. The contract shall also be made, upon request, available to a California court or the officer in charge of a jail in which an arrested person is held in custody;
- Require a surety insurer transacting bail in California to report specified information regarding the insurer’s business operations during a calendar quarter to the commissioner, the Judicial Council, and the Attorney General within 30 days of the end of that calendar quarter;
- Require a surety insurer transacting bail in California to annually submit specified documents to the commissioner, the Judicial Council, and the Attorney General;
Require the following provisions to become operative on January 1, 2020:
- Require a bail licensee to post on its Internet Web site, in English, Spanish, Chinese, Tagalog, Vietnamese, and Korean, the terms and conditions of bail contracts or supporting documents utilized by the licensee;
- Require a bail licensee, before negotiating or executing a bail contract, to provide an arrestee, or a person purporting to act on behalf of an arrestee, a written notice indicating the availability of bail contract documents translated into Spanish, Chinese, Tagalog, Vietnamese, and Korean;
- Specify what the bail licensee must provide to an arrestee or a person purporting to act on behalf of an arrestee during the negotiation of a bail contract;
- Specify that the English version of a bail contract or supporting documents shall be the official version and that a document translated into a language other than English shall contain a disclosure statement in both that language and English stating that the English version is the official version and the translated version is for informational purposes only;
- Provide that an insurer that knowingly misrepresents information provided in a language other than English shall be subject to administrative sanctions.
Related Legislation:
AB 1406 (Gordon, 2015) would have established an assessment on bail bonds to pay for increased enforcement of bail agents and authorize the Insurance Commissioner to distribute grants to local district attorneys. This bill was held in the Assembly Appropriations Committee.
AB 2449 (Eggman, 2016) also would have established an assessment on bail bonds to pay for increased enforcement of bail agents and authorize the Insurance Commissioner to distribute grants to local district attorneys. This bill was held in the Assembly Insurance Committee.
Staff Comments:
Existing law makes any violation of the Insurance Code that pertains to governing bail agents a potential crime. The fiscal impact of penalties resulting from this bill cannot be known with certainty, as the actual impact will be dependent on numerous factors, including, but not limited to, judicial and prosecutorial discretion, the criminal history of the defendant, and the factors unique to each case. To the extent even one additional defendant is committed to state prison as a result of this bill, state incarceration costs would surpass the Suspense File threshold. Additionally, as the crime created by this bill is punishable with the potential for incarceration, certain rights to the defendants are attached to the proceedings, including the right to a jury trial and the right to counsel (at public expense if the defendants are unable to afford the costs of representation) which could lead to lengthier court proceedings.
-- END --
SENATE COMMITTEE ON
Senator Steven Glazer, Chair
2017 - 2018 Regular
Bill No: Hearing Date: April 25, 2018
Author: | |||
Version: | Amended | ||
Urgency: | Fiscal: | ||
Consultant: | |||
Subject:
SUMMARY
This bill makes finding and declarations about the criminal justice system and bail companies; requires bail agents to translate their contracts in at least three, but no more than five, of the most common languages spoken in the county and post their consumer contracts online; and requires the California Department of Insurance (CDI) to compare the risks assumed and rates charged by surety companies to those of auto insurers.
DIGEST
Existing law
- Requires that a person arrested for an alleged crime be granted release on bail except for certain serious offenses.
- Permits an arrested person, or someone acting on their behalf, to satisfy the bail requirement by posting a bail bond with the court.
- Establishes a regulatory structure to oversee the commercial bail industry and requires bail companies to be licensed as an insurer by CDI.
- Requires bail companies to execute bail bonds through bail agents and to hold a portion of their commission in a separate build-up fund for the purpose of paying losses arising from bonds written by that agent.
- Authorizes CDI to adopt regulations governing bail licensees and provides that violations of the statutory provisions applied to bail agents (Insurance Code Section 1800 through 1823) and CDI’s regulations may be considered a crime punishable by no more than one year in jail or prison, a fine not exceeding $10,000, or both.
- Prohibits surety companies from charging rates that are excessive, inadequate, or unfairly discriminatory and requires that they obtain prior approval from the Insurance Commissioner before charging those rates.
This bill
- Makes findings and declarations related to the commercial bail industry and California’s use of pretrial detention.
- Requires bail agents to post the terms and conditions of their consumer contracts online; a violation is punishable up to one year in jail and a $10,000 fine.
- Requires bail agents to translate their contracts into not fewer than three or more than five of the most common non-English languages spoken in the county where the contract is issued; a violation is punishable up to one year in jail and a $10,000 fine.
- Requires CDI to make recommendations by July 1, 2019, regarding bail companies, including an analysis of the relationship between the risk to the bail company and the rate charged, and a comparison of that risk to those assumed by of auto insurers, and sunsets this provision on January 1, 2023.
COMMENTS
- Purpose of the bill According to the author, there is little information available about the insurers who underwrite bail bonds in California despite how highly concentrated the for-profit bail industry is. Bail insurer contracts contain exploitative terms including payday lender type installment plans, property liens, co-signing by family and friends, invasive surveillance, and unpredictable costs. However, they are not subject to the same regulations that payday lenders are.
The author points to a UCLA School of Law study in 2017 that revealed that the industry enjoys unfettered power over their customers, who lack protections. According to the study, “We examined more than 400 bail bond company websites across the 58 counties to find that fewer than 15% of companies provide copies of their agreements online for review prior to signing. In fact, one large bail insurer has publicly boasted that it sustained no losses at all in 2014 or 2015, and another smaller bail insurer has publicly stated that it did not pay any losses for 17 years.
SB 898 would require CDI to study the bail insurance market as it relates to the relationship between the risk assumed by the insurer and the rates charged for coverage. It also requires each bail licensee to post the terms and conditions of its bail contracts online and to translate the terms and conditions of each bail contract into not fewer than 3 of the most common non-English languages spoken in the county in which the contract is issued.
- Background When arrested or held in pretrial custody, a person accused of a crime (“the accused”) has the right to be released on bail except under certain circumstances, such as when the alleged crime is very serious or they are being held on another charge. The accused, or sometimes a friend or family member, may secure release by posting cash or a property bond, but most lack the assets and must rely on a bail bond issued by a commercial bail company (if not released on their own recognizance or if charges are not filed or they are dropped before they are released). In order to secure a bond, the accused, and possibly a co-signor must indemnify the bail company against losses resulting from the transaction (in this role, the accused and co-signors are referred to as “indemnitors”). The court will accept a bail bond from an admitted insurer in lieu of a full cash deposit and release the accused.
The bail amount is set by the arrest warrant or by a schedule. Bail schedules are set by the county courts according to their own process. Schedules can vary widely among the counties; for example, the bail requirement for first degree robbery is $25,000 in Fresno County but $100,000 in Imperial County.
Concerns have been raised that California’s pretrial detention system, including the use of commercial bail, unfairly discriminates against the poor and minority communities. Last year, the Pretrial Detention Reform Workgroup, appointed by the Chief Justice of the California Supreme Court, issued an October 2017 report that includes recommendations to improve the pretrial system (“Pretrial Detention Reform Workgroup”). There have been several legislative efforts this session related to the bail requirement, but this is the first proposal this session to address the regulation of the bail industry. The Insurance Commissioner held a hearing on the bail industry in January 2017.
This bill makes findings and declarations that the commercial money bail system does not improve rates of appearance in court or enhance public safety, restate statistics regarding the percentage of people in jail awaiting trial or sentencing, that existing pretrial detention practices allow a person’s wealth to determine whether or not they remain in jail, and others. These statements involve subject areas not normally within the jurisdiction of this committee; however, since they do not relate to the substantive provisions of the bill, they did not warrant a double-referral to the Committee on Public Safety.
The Bond. The bond is a contract between a bail company and the court. The court releases the accused and the bail company agrees to pay the full amount if the accused fails to appear at required court appearances. The bail company becomes fully committed as soon as the accused is released and remains so until the case is resolved and the bond exonerated. The court may exonerate the bond for other reasons such as when the accused is returned to custody or if charges are dropped. Unlike a one-year homeowners’ insurance policy where a policyholder can cancel the policy half-way through and receive a refund on the unearned premium, the obligations of a bond are not divisible. Once the accused is freed, the bail company remains exposed until the court says otherwise and is not obligated to refund any portion of the premium once the accused is freed even if the case is dropped moments thereafter.
When the accused fails to appear, the bail company (represented by the agent) has at least 180 days to recover and return the fugitive before the forfeiture becomes subject to a motion for summary judgment. The court may also vacate the forfeiture under other conditions, such as the death or disability of the accused.
The Bail Company. Bonds are surety contracts, the surety promises to cover a third-party’s costs if the consumer breaks a promise or fails to perform a legal or contractual duty. Surety companies are highly regulated by CDI as insurers. Bail companies are surety companies that specialize in bail.
Proposition 103 prohibits bail companies from charge “excessive rates” and requires bail companies to receive approval from the Insurance Commissioner prior to charging at those rates. The commissioner may also review existing rates and order a rate increase or reduction. Bond premiums run between 7 to 10% of the bail amounts. Lower rates are available to some consumers; for example, some bail companies offer lower rates to military veterans, union members, defendants who have secured a private attorney, or consumers who can provide adequate collateral. The bail company collects about 10 to 15% which it uses to pay operating costs, premium tax, and other expenses, and places around 5% in a “build-up fund” (BUF), specific to each agent. The agent keeps about 80% of the premium. The BUF accumulates over time and may be used to satisfy forfeited bonds; when the agent’s appointment is terminated, the bail company will release the remaining BUF assets to the agent.
The Surety and Fidelity Association serves as a statistical agent for its members and collects industry-wide data from its members (data from nonmembers is not included). According to the association, in 2016 bail companies wrote a total face value of $16.6 billion in bail bonds. Not including losses subsequently recovered through the consumer indemnity agreements (via collateral or otherwise), bail companies paid about $7 million in directly incurred losses (paid out of the bail companies) and about $103.8 million in gross withdrawals made from BUFs.
Relatively little data is available regarding the practices of bail agents and bail companies relative to the California market. In order to obtain specific information, CDI may have to examine the bail companies individually. In 2014, CDI individually examined 17 bail companies and collected information for the years 2011, 2012, and 2013. During that period, CDI found that:
- Bail companies wrote 229,000 bail bonds in 2011, 212,000 in 2012, and 176,000 in 2013.
- The total face value of the bonds declined from $4.66 billion in 2011, to $4.58 billion in 2012, to $4.08 billion in 2013.
- Of the 17 sureties, 13 bail companies reported gross premium collected. Those bail companies averaged about $308 million per year in gross premium, but bail agents only remitted to the bail companies about $29 million per year.
What is not known, and may not even be tracked, is the value of assets recovered from the collateral and other means of recovery from the indemnitors. Insurers “recover” the bulk of the losses from all of its policyholders by incorporating anticipated losses into its rates. This findings and declarations in this bill cite a 74% loss ratio for auto insurers, but that figure includes losses paid from premium dollars specifically set aside in reserve accounts for just that purpose (similar to the BUF). Since the BUF accounts are “owned” by bail agents, losses paid from those accounts would not be attributed to the bail company even though they would be analogous to losses normally reported by insurers and other types of surety companies.
To fairly compare the level of risk assumed by an insurer versus a surety of any kind, it may be argued that the analysis should include the value of the assets recovered from indemnitors as well (this would be analogous to the ways an insurer might recover losses including the portion of the premium paid out of a claims reserve fund, reinsurance agreements, subrogation, etc.). For example, the 2016 losses paid by surety companies nationally include $7 million for losses directly incurred and $103 million from the BUF withdrawals, but those numbers do not include assets recovered from indemnitors. (Other forms of surety companies do not use a BUF and will naturally report these losses as directly incurred where bail companies would not.)
On the other hand, it may be argued that comparing the face value of a bond to the face value of an insurance policy overstates the risks associated with the bond. A $300,000 bail bond secured by a $300,000 home does not present the same level or type of risk as the insurer that issues the $300,000 fire insurance policy on that home. If a fire burns down the home, the insurer loses the full amount; if the accused skips bail, the bail company and agent only lose what cannot be collected from the collateral.
Bail Agents. Bail agents typically work as independent contractors and may work with more than one bail company. Each company must separately appoint the agent to represent it in bail bond transactions and notify CDI.
Consumers primarily interact with a bail agent who is appointed to represent the bail company in the transaction. Bail agents are required to sign an indemnity agreement that covers the bail company’s losses related to the transaction. The arrangement motivates the agent to take a personal role to avoid losses. For their efforts, agents receive the bulk of the premium. They may also may provide rebates to the consumer.
Initially, the agent will collect information necessary to underwrite the bond and that will be helpful to track down the accused if they fail to appear (relevant addresses; names and contact information for associates, employers, family members; automobile description, etc.). The agent may also determine that the purchaser must post collateral, secure a co-signer, and agree to other terms designed to expedite fugitive recovery, or refuse to issue the bond.
Most bail bonds are co-signed by a close friend or family member. When large bail bonds are involved, co-signers may be required to execute a deed on their own property as collateral subject to foreclosure if the bond must be paid. This provides resources to cover losses, but also incentivizes co-signers to ensure that the accused makes appearances or to cooperate in fugitive recovery.
Once the bond is issued, agents play a central role in enforcing the indemnity agreement. They monitor compliance with bond terms, direct fugitive recovery, defend against the forfeiture, etc. These costs are passed on to the indemnitors.
The author points to a report by the UCLA School of Law Criminal Justice Reform Clinic prepared to support of money bail reform in California. The report points to “20 problems with bail bond contracts that violate common law notions of fairness and justice.” These issues include concerns that agents have broad leeway to return the accused to jail; the accused, friends, and family may be forced to sacrifice privacy rights; and contracts may force family and friends to surrender their loved ones to jail.
This bill would require all agents to post their contracts online. Existing law would make a violation a crime punishable up to one year in jail and a $10,000 fine.
Surety and Insurance. Bail and other types of bonds are often referred to as forms of “surety insurance,” but surety and insurance are really cousins within a family of risk mitigation tools. Although issued by insurers, surety bonds (and bail bonds especially) differ from insurance policies in design and purpose. Insurance could be said to help innocent parties recover from losses through a cooperative effort where every participant contributes a little to help an unfortunate few. Surety arrangements are designed to insulate innocent parties (including the surety) from paying for losses caused by those who have broken a promise or obligation. In particular, three distinctions may be helpful when considering this bill.
For one, surety bonds do not involve a true transfer of risk from the insured (but does assume the risk of a third party, such as the court). The surety redirects losses back to the consumer via indemnity agreements; the surety only absorbs losses when all else fails. The bail bond consumer isn’t purchasing protection against loss (like an insurance policy), but borrowing the surety’s verified credit.
Secondly, surety agreements cover events intentionally triggered by the consumer, such as when the accused fails to appear on purpose. In contrast, insurance does not cover intentional losses: a homeowner’s insurance policy will not pay on fire damage that the homeowner intentionally caused.
A third distinction is particularly relevant to ratemaking because insurance and surety arrangements use different mechanisms to absorb losses. Insurance premiums include a portion that covers actuarially anticipated losses and all policyholders contribute to pay for losses caused by the less fortunate members of the risk pool. It’s a sort all-for-one, one-for-all system and the larger the pool, the more predictable the losses. On the other hand, surety arrangements are meant to insulate uninvolved parties from related losses and only involve a handful of participants. Statistically, establishing risk-based system for bail bonds would require the bail company to provide some reasonable method of predicting whether a specific individual will trigger a loss, rather than assuming probable losses over a class of individuals.
Bail companies and insurers also differ in the way they process information. Insurers directly handle claims allowing for the centralized collection and reporting of losses and other data. Since most activity related to bail bonds is handled by agents in a decentralized fashion, far less industry-wide data is available.
- Support The Ella Baker Center for Human Rights state that as policing practices result in disproportionately high rates of arrest of low-income people of color, it is the families with the least wealth and income that are injured by the predatory practices of the bail industry. The industry uses a family crisis to leverage families into fees or payment plans that they cannot afford, forcing them to choose between the immediate safety and liberty of their loved one, and the family’s long term well-being.
- Opposition The Golden State Bail Agents Association (GSBAA) explains that more than half of the bail agencies in California are small businesses owned by women and minorities. Many bail agents are fluent in Spanish, the most common foreign language in California, and there is no evidence of a translation problem. GSBAA also points out that the penalty is not commensurate with the offence and that bail agents are the only insurance licensees that can be charged with felonies for mere regulatory violations.
- Concerns Representatives of bail companies have not taken a position on the bill but have expressed concerns about the bill. The American Bail Coalition comments that the legislative declarations are, “in parts inaccurate,” and “unnecessarily raise issues not touched or concerned with this legislation.” Tokio Marine, a bail company, suggests that the bill makes comparisons to the “auto insurance and general surety industry that are out of context.”
- Suggested Amendments In order to address the issues raised, the committee may wish to consider the following amendments.
Findings and Declarations. When making allegations related to the risks assumed and losses experienced by insurers, bail companies, and other sureties, the author primarily relies on a 2017 report by Color of Change and the American Civil Liberties Union Campaign for Smart Justice titled Selling Off Our Freedom: How insurance corporations have taken over our bail system. In several instances, the report includes additional context and clarifying information. Amendments would attribute the allegations to the report.
Posting and Translating Contracts. Nearly all contracts issued by licensees regulated by CDI include CDI’s contact information. The committee may wish to consider amendments that impose the same requirement on indemnity contracts.
In its current form, the bill would more likely require agents to translate their contract into language that may not be needed. Amendments would require that the contracts be posted in English, as well as Spanish, Chinese, Tagalog, Vietnamese, and Korean (the five most frequently spoken non-English languages in the state).
The amendments would also require that, during contract negotiations, the consumer be provided with a copy of the contracts and any supporting documents. Consistent with similar approaches applied to other licensees, they also deem the English version to be the official version for legal purposes.
Amendments would also restate an existing Insurance Code provision that subjects an insurer that misrepresents information provided in another language other than English to the penalties provided in the Unfair Trade Practices Act, $5,000 per violation except that willful violations may be subject to a penalty up to $10,000. (The agent remains subject to the criminal penalties and $10,000 fine for violations of the other provisions.)
Lastly, the amendments would provide that these new provisions, relating to the posting of contracts and translations, would be deferred until January 1, 2020.
New Reporting Requirements. The Pretrial Detention Reform Workgroup notes that beyond basic licensing information, relatively little statewide data are available on the bail industry’s operations in California. Perhaps one of the most daunting challenges of addressing comprehensive bail industry reform has been the lack of information about the industry. Amendments would replace the proposed study with a requirement that bail companies report or submit the following to CDI, the Judicial Council, and the Attorney General:
- On a quarterly bases: the number of bail bonds written, total face value, total gross premium, and the net premium remitted to the surety, by county and agent; the identification of bail agents and related information; the identification of pending appointments and related information; a description of disciplinary actions taken by the bail company against bail agents and related information; a description of any notice of forfeiture letters and related information; and a description of any surrenders and relevant arrests and related information and documents.
- On an annual basis: copies of procedures related to the selection of agents; copies of the bail company-bail agent contracts; and copies of any agent document related to the rules and procedures governing underwriting, ethics, forfeiture, financial reporting, surrendering defendants, credit bail, and collateral retention.
Amendments would also require bail companies to submit to CDI copies of contracts as they are executed or revised. These contracts shall also be made available to the court or someone interested in the case as determined by Penal Code Section 1269b.
- Prior and Related Legislation AB 1406 (Gordon, 2015), held in the Assembly Appropriations Committee, and AB 2449 (Eggman, 2016), held in the Assembly Insurance Committee, would have established an assessment on bail bonds to pay for increased enforcement of bail agents and authorize the Insurance Commissioner to distribute grants to local district attorneys. CDI argues that it lacks the resources to properly oversee bail agents.
POSITIONS (Positions do not reflect the suggested amendments.)
Support
Ella Baker Center for Human Rights
Oppose
Golden State Bail Agents Association
-- END --
Discussed in Hearing
View Older Hearings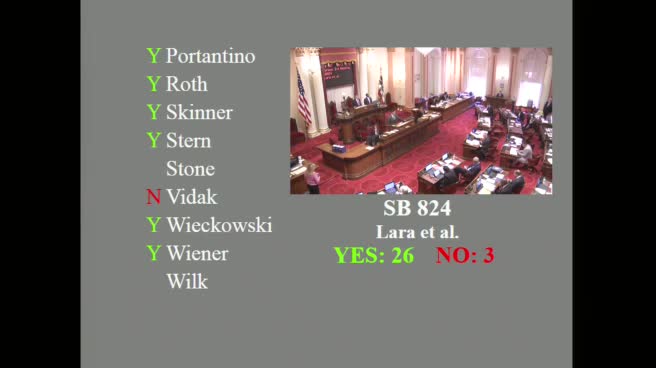
Bill Author
Bill Co-Author(s):