SR 113
- Session Year: 2017-2018
- House: Senate
- Latest Version Date: 2018-06-13
WHEREAS, On June 6, 1978, Proposition 13, officially titled the Peoples Initiative to Limit Property Taxation, was overwhelmingly approved by Californias voters, establishing a 1-percent property tax cap and a two-thirds vote requirement for taxes approved by the Legislature, as well as local special taxes; and
WHEREAS, Prior to the adoption of Proposition 13, Californias raging inflation had sent property tax bills in California soaring so high that some seniors on fixed incomes were forced to sell their homes, despite having paid off their mortgages, because they could no longer afford the property tax; and
WHEREAS, Prior to the adoption of Proposition 13, property tax assessments showed wider divergences than assessment disparities under the current acquisition-value system; and
WHEREAS, Prior to the adoption of Proposition 13, renters saw their rents increase when landlords saw their property taxes increase at a rapid rate; and
WHEREAS, With the approval of Proposition 13, real property values were adjusted to a base value equal to the 1976 assessed value of real property, thereby introducing an objective standard upon which real property would be taxed and ending the previous subjective standard for assessment that led to the property tax abuses that occurred in the 1960s and 1970s; and
WHEREAS, With the passage of Proposition 13, taxpayers, for the first time, were provided a measure of certainty with respect to their property taxes; and
WHEREAS, According to the nonpartisan Legislative Analysts Office, property tax revenue has increased at an average annual rate of 7.3 percent since 1979, a faster rate than personal income growth, and overall property tax revenue has increased by 1000 percent over that time; and
WHEREAS, In the 40 years following the passage of Proposition 13, a family who has owned their home 10 years has saved an average of $60,000 on property taxes, proving that every property owner benefits from these protections; and
WHEREAS, In the landmark case Nordlinger v. Hahn, the United States Supreme Court ruled nearly unanimously to uphold Proposition 13s acquisition-based system under the equal protection clause; and
WHEREAS, Proposition 13 has led to revenue stability for local governments, which have seen a nearly $40 billion increase in revenue since 1978; and
WHEREAS, The concept of revenue volatility surrounding both income and sales tax revenue to the state and local governments is a major flaw in Californias tax system; however, Proposition 13 has rendered Californias property taxes a stable and predictable source of public revenue even during economic downturns and has provided a major benefit to local governments in California; and
WHEREAS, To that end, in the last three-year recession, property tax was the only major revenue category to show a revenue increase, mainly because of Proposition 13s 1-percent cap; and
WHEREAS, This stability is important for local government in light of Californias ongoing unfunded pension liability crisis, and the fact that property tax revenue represents 60 percent of a municipalitys average annual revenue; and
WHEREAS, Proposition 13 does not create inequity between different classes of property, as the assessed valuation of commercial and business property has increased at a faster average annual rate than residential property; and
WHEREAS, Since the passage of Proposition 13, various polls continue to show that a split-roll alternative which would alter the existing system so that one or more categories of nonresidential property on the local assessment roll would not be subject to the acquisition value system established by Proposition 13, is not as popular as the current system; and
WHEREAS, Increased property taxes would be a disincentive for first-time homebuyers and would stand as a barrier to growth of our housing market; and
WHEREAS, Proposition 13 incited a nationwide tax revolt at the state and local level; within five years of passage, nearly one-half of the 50 states imposed a similar limitation on governments ability to raise revenue, and nearly all of these tax-limitation measures remain the law of the land today; and
WHEREAS, Proposition 13 has become a nationwide symbol for taxpayer revolt and for citizens exercising control and power over their governance; and
WHEREAS, Proposition 13 remains just as popular with voters today as it was when it was approved, with numerous recent surveys citing over 60 percent support; and
WHEREAS, Wednesday, June 6, 2018, marks the 40th year following the voters approval of Proposition 13; now, therefore, be it
Resolved by the Senate of the State of California, That the Senate, in recognition of the impact Proposition 13 has had on the State of California, formally commemorates Wednesday, June 6, 2018, as the 40th anniversary date of Proposition 13; and be it further
Resolved, That the Senate reaffirms its support for Proposition 13 and the benefit that it provides to individual homeowners and to the states overall economy; and be it further
Resolved, That the Secretary of the Senate transmit copies of this resolution to the Governor, and to the author for appropriate distribution.
|
Date
|
Status
|
|---|---|
| Aug 15, 2018 | August 15 hearing: Failed passage in committee. (Ayes 2. Noes 3.) |
| Aug 10, 2018 | Set for hearing August 15. |
| Aug 8, 2018 | August 8 hearing postponed by committee. |
| Aug 2, 2018 | Set for hearing August 8. |
| Jun 20, 2018 | Re-referred to Com. on GOV. & F. |
| Jun 13, 2018 | Introduced. Referred to Com. on RLS. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Aug 15, 2018 | [08-15-2018] hearing: Motion to Reconsider. [Reconsideration Granted.] | Senate Standing Committee on Governance and Finance |
Passed |
|
| Aug 15, 2018 | Be adopted. Ordered to third reading | Senate Standing Committee on Governance and Finance |
Failed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
SENATE COMMITTEE ON GOVERNANCE AND FINANCE
Senator Mike McGuire, Chair
2017 - 2018 Regular
Bill No: | SR 113 | Hearing Date: | 8/15/18 |
Author: | Gaines | Tax Levy: | No |
Version: | 6/13/18 | Fiscal: | No |
Consultant: | Grinnell | ||
The 40th Anniversary Of Proposition 13
Commemorates the 40th Anniversary of Proposition 13.
Background
Before Proposition 13 (1978), the Legislature could generally enact new taxes or increase existing taxes by majority vote. Proposition 13 instead required that any changes in state taxes for the purpose of increasing revenues receive approval by 2/3 vote of both houses of the Legislature to be enacted. Proposition 26 (2010) subsequently modified the definition to apply the 2/3 requirement to bills that “results in any taxpayer paying a higher tax.”
Prior to 1978, local agencies could enact taxes by ordinance. Proposition 13 amended the Constitution to require a 2/3 vote of the electorate to enact a local special tax. Proposition 62 (1986) prohibited local agencies from imposing general taxes without majority approval of local voters, and clarified the 2/3 vote necessary to impose special taxes. Proposition 218 (1996) extended those vote thresholds to charter cities and required local agencies’ to obtain voter approval to levy new assessments, fees, and taxes, which was subsequently limited by Proposition 26.
Cities, counties, and special districts could generally set property tax rates on property within its jurisdiction without an aggregate cap before Proposition 13. State law required assessors to revalue property annually; however, in practice, assessors usually reassessed all the homes in one neighborhood every three to five years. Local agencies received property tax revenue resulting from the appropriate property tax rate fixed by the local agency.
Proposition 13 reformed property tax assessment in the following ways:
- Limited the maximum amount of any ad valorem tax on real property at 1% of full cash value as shown on the 1975-76 tax bill.
- Set a property’s assessed value at its purchase price, and precluded assessors from reassessing property unless it was newly constructed, or changed ownership.
- Capped the growth in assessed value to 2% per year.
- Provided that the Legislature allocates property tax revenue “according to law.”
Proposed Law
Senate Resolution 113 commemorates the 40th anniversary of Proposition 13. The measure contains several statements regarding the state’s property tax system before the initiative, its benefits for taxpayers and local agencies, as well as taxpayer support for Proposition 13, among others. The resolution states the Legislature’s reaffirmation of its support for Proposition 13 and the benefit it provides to individual homeowners and the state’s overall economy
State Revenue Impact
No estimate.
Comments
1. Purpose of the bill. According to the author, “There can be no denying that Proposition 13 has led to property tax stability for all property owners while at the same time increasing property tax revenue. Homeowners now know when they buy their home just how much they will be paying in property taxes over 5, 20, or 40 years, and local governments know just how much revenue they will bring in. The facts bear this out, which explains why Proposition 13 continues to maintain a 60 percent approval rate according to the Public Policy Institute of California. For example, In the 40 years following the passage of Proposition 13, a family who has owned their home 10 years has saved an average of $60,000 and local governments have seen a nearly $40 billion increase in revenue since 1978. Proposition 13 is entitled to a well-deserved 40th anniversary celebration.”
2. Yes, but. Proposition 13 may be the most significant initiative ever enacted by California’s voters: its changes reshaped fundamental aspects of California governance and public finance. However, SR 113 celebrates the initiative from a specific point-of-view, and includes adjectives, phrases, and causal connections that may not reflect the views of the entire Legislature, including a statement reaffirming the Senate’s support for the initiative. Should the Committee wish to amend SR 113 to celebrate the initiative’s more complicated history as described below, it can also amend it by deleting or altering some of its findings, such as:
- While inflation and property tax bills increased prior to Proposition 13’s enactment, are the adjectives “raging” and “soaring,” accurate?
- While revenue stability is certainly beneficial for local agencies, wouldn’t cities, counties, and special districts have an easier time meeting their pension obligations with the increased revenues derived from annual fair market value reassessment instead of acquisition cost valuation?
- The resolution reaffirms the Legislature’s support for the measure, and its benefit to homeowners and the state’s economy. While homeowners have certainly benefitted from Proposition 13, no empirical data shows that it produced a net benefit for the state’s economy. Given the initiative’s more nuanced and complicated effects described below, should the Legislature instead recognize the anniversary of the initiative’s enactment, and its significance and effect on California’s system of governance and public finance without declaring its support or characterizing it as a benefit to the economy?
3. The rest of the story. Enacted in 1978, Proposition 13 remains controversial today. California property owners pay less property tax, and enjoy the additional benefits of increased certainty due to the initiative’s limitations on assessed value growth and reassessments. Additionally, the initiative increased legislative vote requirements to raise or enact new taxes, and required voter approval when local agencies seek to raise taxes, likely contributing to a lower tax burden for Californians. However, enacting Proposition 13 did not occur without tradeoffs. Economists and academics have researched the measure’s legacy copiously, and their findings include that the initiative:
- Shifted the burden of financing public services from property taxes onto other revenue streams, with undesirable consequences;
- Transferred significant authority to the state, including the power to allocate property tax revenues;
- Led to significant differences in property taxes paid by taxpayers based on when they purchased property; and
- Created considerable distortions and inequities in the housing market.
Proposition 13 reduced local agency revenues. However, the state ameliorated much of the revenue loss, and local agencies found other ways to finance public services. Proposition 13 resulted in a property tax revenue loss of 51% in the first year after enactment, but the state assumed health and human services programs from the counties, shifted property taxes from schools to local agencies, and provided a $2.7 billion bailout to local agencies in 1978. Local agencies took other steps, such as relying more on sales, utility, and hotel taxes. Local agencies also increased or imposed new fees and charges, which did not for the most part require voter approval until Proposition 218 (1996), thereby shifting the burden of financing public services away from property taxes. Sometimes, costs were aligned with services; for example, housing developers now pay significant fees for infrastructure, permitting, and environmental review, which they attempt to pass on to homebuyers. Other fees did not bear such a relationship, such as the 48% increase in revenues from library fines, garbage collection fees, and sewer charges between 1979 and 1983. Local agencies often became more entrepreneurial, using redevelopment until it was recently eliminated to capture property tax increments, making land-use decisions based on sales tax revenue consequences instead of sound land use practices, and offering economic incentives to businesses that generate significant sales tax revenue to locate in its jurisdiction, such as big-box stores and auto dealerships.[1]
The initiative also fundamentally changed California’s state-local fiscal relationship. Proposition 13 changed a long standing tradition that began in 1910 with a constitutional amendment known as the "Separation of Sources," which provided that the property tax would be used for local purposes and state taxes would be used for state purposes. Although state taxes were revised in the 1930s, this doctrine remained until 1978 when Prop. 13 set a maximum tax rate with no ability for communities to raise the rate. Additionally, Proposition 13 required that property tax revenues be allocated “according to law,” meaning that the Legislature would determine how property tax revenues would be allocated among local agencies in a county levying a property tax. Previously, each local jurisdiction set the property tax rate within its jurisdiction. The Legislature decided to freeze current allocations within a county, locking in each agency’s share of the property tax regardless of future changes in demographics or service demand (AB 8, Greene, 1979); these allocation shares have been mostly fixed for the last 39 years. Proposition 13 also laid the foundation for the Legislature to shift property tax revenues from local agencies to schools in 1992-93, 1993-94, 2004-05, and 2005-06 to meet the state’s public education spending obligations under Proposition 98 (1988).
Prior to Proposition 13, voters in communities were able to increase the amount of property tax levied for schools by a majority vote. Although the state had enacted changes to partially address school funding inequalities due to disparities in the property tax wealth of districts, taxpayers could still choose to enhance funding for their local schools before the enactment of the initiative. Proposition 13 transferred the responsibility of communities to support their schools to the state. Since the enactment of Propositions 13 and 98 (1988), the state is responsible for all new investment in K-14 education, with the exception of voter-approved parcel taxes and general obligation bonds to fund school facilities.
Before Proposition 13 the state finance system was made up of taxes on wealth (property tax), income (personal and corporate income tax) and transactions (sales tax), with each providing an approximately equal share of the total cost of public services over a long period of time. Proposition 13 increased the reliance on the income tax since it assumed the responsibility for funding the schools. At the same time, local agencies increased the reliance on the sales tax in order to support local services. The net result was a highly volatile tax system at the state level and a local finance system dependent primarily on transactions (sales and use tax, utility user taxes, and transient occupancy taxes). The property tax makes up a smaller share of tax revenue today than it did before Proposition 13.
While Proposition 13 reduced taxes, it caused distortive and inequitable tax consequences for many California taxpayers. Under Proposition 13, the date a taxpayer purchased a property sets a taxpayer’s property tax more so than its actual market value by locking in a property’s assessed valuation until ownership changes or the property is newly constructed. Property owners have a significant incentive not to move residences, because a new home’s purchase price determines its property taxes, which could exceed the taxes determined by the original property’s factored base year value. While Propositions 60 (1988) and 90 (1990) allow disabled taxpayers or those over the age of 55 to transfer base year values to properties of equal or lesser value than the original property, Proposition 13’s “lock-in” effect leads taxpayers to make different decisions on housing due to tax implications, distorting the function of a normal market. Additionally, locking in assessed valuations leads to taxpayers owning homes of the same market value paying vastly different property tax amount. As a result, newer homebuyers bear a proportionally larger share of the burden for financing public services than longer term residents.
4. On subsidiarity. Proposition 13 is often regarded mostly as a change in tax policy. However, by shifting control of property tax allocation from local agencies to the state, and limiting local revenue raising ability, the initiative and changes that followed fundamentally altered the relationship between citizens and their government, empowering the state to the detriment of local agencies. Before Proposition 13, local agencies exercised “home rule” powers over local revenue sources: local taxes paid for local services, with some state intrusions. Voters chose their priorities when selecting officials to lead these local agencies, who set local tax rates, and then voters held officials accountable at the next election. Today, cities, counties, and special districts have little flexibility to raise revenues due to the initiative’s limitation on property tax rates and the 2/3 vote threshold for enacting new or higher special taxes. Researchers state that Proposition 13 and subsequent legislative action severely undercut local home rule powers by establishing a fiduciary relationship on the part of the state toward local agencies.[2] Counties particularly are reliant on state funding and must implement state programs as legal subdivisions of the state. Researchers add that any policy discussions between state and local agencies have deteriorated as a result, describing the fiscal relationship that evolved between state and local agencies as “a zero-sum political atmosphere in which fiscal considerations dominate intergovernmental policymaking.”[3]
5. Another try. The Committee previously defeated resolutions celebrating the 39th Anniversary of Proposition 13 (SR 39, Morrell, 2017), the 36th Anniversary of Proposition 13 (SR 41, Morrell, 2014), the 35th Anniversary (SCR 25, Wyland, 2013), and the former Committee on Revenue and Taxation, a predecessor to this Committee, defeated a resolution celebrating the 30th Anniversary (SCR 116, Harman, 2008). SR 113 has excluded some of the legislative findings and declarations contained in those resolutions, while adding some new ones.
Support and Opposition
(8/6/18)
Support: Howard Jarvis Taxpayers Association.
Opposition: Unknown.
-- END --
SENATE COMMITTEE ON GOVERNANCE AND FINANCE
Senator Mike McGuire, Chair
2017 - 2018 Regular
Bill No: | SR 113 | Hearing Date: | 8/8/18 |
Author: | Gaines | Tax Levy: | No |
Version: | 6/13/18 | Fiscal: | No |
Consultant: | Grinnell | ||
The 40th Anniversary Of Proposition 13
Commemorates the 40th Anniversary of Proposition 13.
Background
Before Proposition 13 (1978), the Legislature could generally enact new taxes or increase existing taxes by majority vote. Proposition 13 instead required that any changes in state taxes for the purpose of increasing revenues receive approval by 2/3 vote of both houses of the Legislature to be enacted. Proposition 26 (2010) subsequently modified the definition to apply the 2/3 requirement to bills that “results in any taxpayer paying a higher tax.”
Prior to 1978, local agencies could enact taxes by ordinance. Proposition 13 amended the Constitution to require a 2/3 vote of the electorate to enact a local special tax. Proposition 62 (1986) prohibited local agencies from imposing general taxes without majority approval of local voters, and clarified the 2/3 vote necessary to impose special taxes. Proposition 218 (1996) extended those vote thresholds to charter cities and required local agencies’ to obtain voter approval to levy new assessments, fees, and taxes, which was subsequently limited by Proposition 26.
Cities, counties, and special districts could generally set property tax rates on property within its jurisdiction without an aggregate cap before Proposition 13. State law required assessors to revalue property annually; however, in practice, assessors usually reassessed all the homes in one neighborhood every three to five years. Local agencies received property tax revenue resulting from the appropriate property tax rate fixed by the local agency.
Proposition 13 reformed property tax assessment in the following ways:
- Limited the maximum amount of any ad valorem tax on real property at 1% of full cash value as shown on the 1975-76 tax bill.
- Set a property’s assessed value at its purchase price, and precluded assessors from reassessing property unless it was newly constructed, or changed ownership.
- Capped the growth in assessed value to 2% per year.
- Provided that the Legislature allocates property tax revenue “according to law.”
Proposed Law
Senate Resolution 113 commemorates the 40th anniversary of Proposition 13. The measure contains several statements regarding the state’s property tax system before the initiative, its benefits for taxpayers and local agencies, as well as taxpayer support for Proposition 13, among others. The resolution states the Legislature’s reaffirmation of its support for Proposition 13 and the benefit it provides to individual homeowners and the state’s overall economy
State Revenue Impact
No estimate.
Comments
1. Purpose of the bill. SR 113 celebrates the 40th Anniversary of Proposition 13, which fundamentally changed California’s tax policy by capping property tax rates, limiting reassessment of property only when newly constructed or ownership changes, caps annual growth of assessed valuation to 2% per year, required a 2/3 vote for local special tax increases and for the Legislature to increase state taxes.
2. Yes, but. Proposition 13 may be the most significant initiative ever enacted by California’s voters: its changes reshaped fundamental aspects of California governance and public finance. However, SR 113 celebrates the initiative from a specific point-of-view, and includes adjectives, phrases, and causal connections that may not reflect the views of the entire Legislature, including a statement reaffirming the Senate’s support for the initiative. Should the Committee wish to amend SR 113 to celebrate the initiative’s more complicated history as described below, it can also amend it by deleting or altering some of its findings, such as:
- While inflation and property tax bills increased prior to Proposition 13’s enactment, are the adjectives “raging” and “soaring,” accurate?
- While revenue stability is certainly beneficial for local agencies, wouldn’t cities, counties, and special districts have an easier time meeting their pension obligations with the increased revenues derived from annual fair market value reassessment instead of acquisition cost valuation?
- The resolution reaffirms the Legislature’s support for the measure, and its benefit to homeowners and the state’s economy. While homeowners have certainly benefitted from Proposition 13, no empirical data shows that it produced a net benefit for the state’s economy. Given the initiative’s more nuanced and complicated effects described below, should the Legislature instead recognize the anniversary of the initiative’s enactment, and its significance and effect on California’s system of governance and public finance without declaring its support or characterizing it as a benefit to the economy?
3. The rest of the story. Enacted in 1978, Proposition 13 remains controversial today. California property owners pay less property tax, and enjoy the additional benefits of increased certainty due to the initiative’s limitations on assessed value growth and reassessments. Additionally, the initiative increased legislative vote requirements to raise or enact new taxes, and required voter approval when local agencies seek to raise taxes, likely contributing to a lower tax burden for Californians. However, enacting Proposition 13 did not occur without tradeoffs. Economists and academics have researched the measure’s legacy copiously, and their findings include that the initiative:
- Shifted the burden of financing public services from property taxes onto other revenue streams, with undesirable consequences;
- Transferred significant authority to the state, including the power to allocate property tax revenues;
- Led to significant differences in property taxes paid by taxpayers based on when they purchased property; and
- Created considerable distortions and inequities in the housing market.
Proposition 13 reduced local agency revenues. However, the state ameliorated much of the revenue loss, and local agencies found other ways to finance public services. Proposition 13 resulted in a property tax revenue loss of 51% in the first year after enactment, but the state assumed health and human services programs from the counties, shifted property taxes from schools to local agencies, and provided a $2.7 billion bailout to local agencies in 1978. Local agencies took other steps, such as relying more on sales, utility, and hotel taxes. Local agencies also increased or imposed new fees and charges, which did not for the most part require voter approval until Proposition 218 (1996), thereby shifting the burden of financing public services away from property taxes. Sometimes, costs were aligned with services; for example, housing developers now pay significant fees for infrastructure, permitting, and environmental review, which they attempt to pass on to homebuyers. Other fees did not bear such a relationship, such as the 48% increase in revenues from library fines, garbage collection fees, and sewer charges between 1979 and 1983. Local agencies often became more entrepreneurial, using redevelopment until it was recently eliminated to capture property tax increments, making land-use decisions based on sales tax revenue consequences instead of sound land use practices, and offering economic incentives to businesses that generate significant sales tax revenue to locate in its jurisdiction, such as big-box stores and auto dealerships.[1]
The initiative also fundamentally changed California’s state-local fiscal relationship. Proposition 13 changed a long standing tradition that began in 1910 with a constitutional amendment known as the "Separation of Sources," which provided that the property tax would be used for local purposes and state taxes would be used for state purposes. Although state taxes were revised in the 1930s, this doctrine remained until 1978 when Prop. 13 set a maximum tax rate with no ability for communities to raise the rate. Additionally, Proposition 13 required that property tax revenues be allocated “according to law,” meaning that the Legislature would determine how property tax revenues would be allocated among local agencies in a county levying a property tax. Previously, each local jurisdiction set the property tax rate within its jurisdiction. The Legislature decided to freeze current allocations within a county, locking in each agency’s share of the property tax regardless of future changes in demographics or service demand (AB 8, Greene, 1979); these allocation shares have been mostly fixed for the last 39 years. Proposition 13 also laid the foundation for the Legislature to shift property tax revenues from local agencies to schools in 1992-93, 1993-94, 2004-05, and 2005-06 to meet the state’s public education spending obligations under Proposition 98 (1988).
Prior to Proposition 13, voters in communities were able to increase the amount of property tax levied for schools by a majority vote. Although the state had enacted changes to partially address school funding inequalities due to disparities in the property tax wealth of districts, taxpayers could still choose to enhance funding for their local schools before the enactment of the initiative. Proposition 13 transferred the responsibility of communities to support their schools to the state. Since the enactment of Propositions 13 and 98 (1988), the state is responsible for all new investment in K-14 education, with the exception of voter-approved parcel taxes and general obligation bonds to fund school facilities.
Before Proposition 13 the state finance system was made up of taxes on wealth (property tax), income (personal and corporate income tax) and transactions (sales tax), with each providing an approximately equal share of the total cost of public services over a long period of time. Proposition 13 increased the reliance on the income tax since it assumed the responsibility for funding the schools. At the same time, local agencies increased the reliance on the sales tax in order to support local services. The net result was a highly volatile tax system at the state level and a local finance system dependent primarily on transactions (sales and use tax, utility user taxes, and transient occupancy taxes). The property tax makes up a smaller share of tax revenue today than it did before Proposition 13.
While Proposition 13 reduced taxes, it caused distortive and inequitable tax consequences for many California taxpayers. Under Proposition 13, the date a taxpayer purchased a property sets a taxpayer’s property tax more so than its actual market value by locking in a property’s assessed valuation until ownership changes or the property is newly constructed. Property owners have a significant incentive not to move residences, because a new home’s purchase price determines its property taxes, which could exceed the taxes determined by the original property’s factored base year value. While Propositions 60 (1988) and 90 (1990) allow disabled taxpayers or those over the age of 55 to transfer base year values to properties of equal or lesser value than the original property, Proposition 13’s “lock-in” effect leads taxpayers to make different decisions on housing due to tax implications, distorting the function of a normal market. Additionally, locking in assessed valuations leads to taxpayers owning homes of the same market value paying vastly different property tax amount. As a result, newer homebuyers bear a proportionally larger share of the burden for financing public services than longer term residents.
4. On subsidiarity. Proposition 13 is often regarded mostly as a change in tax policy. However, by shifting control of property tax allocation from local agencies to the state, and limiting local revenue raising ability, the initiative and changes that followed fundamentally altered the relationship between citizens and their government, empowering the state to the detriment of local agencies. Before Proposition 13, local agencies exercised “home rule” powers over local revenue sources: local taxes paid for local services, with some state intrusions. Voters chose their priorities when selecting officials to lead these local agencies, who set local tax rates, and then voters held officials accountable at the next election. Today, cities, counties, and special districts have little flexibility to raise revenues due to the initiative’s limitation on property tax rates and the 2/3 vote threshold for enacting new or higher special taxes. Researchers state that Proposition 13 and subsequent legislative action severely undercut local home rule powers by establishing a fiduciary relationship on the part of the state toward local agencies.[2] Counties particularly are reliant on state funding and must implement state programs as legal subdivisions of the state. Researchers add that any policy discussions between state and local agencies have deteriorated as a result, describing the fiscal relationship that evolved between state and local agencies as “a zero-sum political atmosphere in which fiscal considerations dominate intergovernmental policymaking.”[3]
5. Another try. The Committee previously defeated resolutions celebrating the 39th Anniversary of Proposition 13 (SR 39, Morrell, 2017), the 36th Anniversary of Proposition 13 (SR 41, Morrell, 2014), the 35th Anniversary (SCR 25, Wyland, 2013), and the former Committee on Revenue and Taxation, a predecessor to this Committee, defeated a resolution celebrating the 30th Anniversary (SCR 116, Harman, 2008). SR 113 has excluded some of the legislative findings and declarations contained in those resolutions, while adding some new ones.
Support and Opposition
(8/6/18)
Support: Howard Jarvis Taxpayers Association.
Opposition: Unknown.
-- END --
Discussed in Hearing
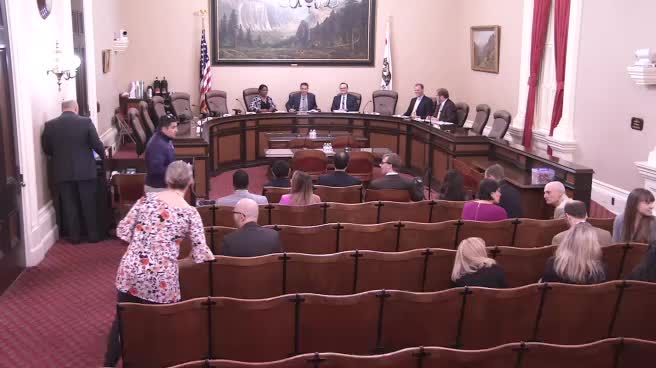 13MIN
Senate Standing Committee on Governance and Finance
Bill Author
Bill Co-Author(s):