AB 2822: California State Auditor: high-risk local government agency audit program.
- Session Year: 2017-2018
- House: Assembly
- Latest Version Date: 2018-09-18
Existing law establishes the California State Auditors Office, headed by the appointed California State Auditor and under the direction of the Milton Marks Little Hoover Commission on California State Government Organization and Economy, with specified duties that include, among others, conducting financial and performance audits as directed by statute. Existing law authorizes the auditor to establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency that he or she identifies as at high risk for fraud or waste, among other things. Existing law authorizes the auditor to consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency to identify local governments that are at high risk.
This bill would additionally authorize the California State Auditor to review publicly available information to identify local governments that are at high risk.
This bill would incorporate additional changes to Section 8546.10 of the Government Code proposed by SB 1293 to be operative only if this bill and SB 1293 are enacted and this bill is enacted last.
Existing law establishes the California State Auditors Office, headed by the appointed California State Auditor and under the direction of the Milton Marks Little Hoover Commission on California State Government Organization and Economy, with specified duties that include, among others, conducting financial and performance audits as directed by statute. Existing law authorizes the auditor to establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency that he or she identifies as at high risk for fraud or waste, among other things. Existing law authorizes the auditor to consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency to identify local governments that are at high risk.
This bill would additionally authorize the California State Auditor to review publicly available information to identify local governments that are at high risk.
This bill would incorporate additional changes to Section 8546.10 of the Government Code proposed by SB 1293 to be operative only if this bill and SB 1293 are enacted and this bill is enacted last.
Existing law establishes the California State Auditors Office, headed by the appointed California State Auditor and under the direction of the Milton Marks Little Hoover Commission on California State Government Organization and Economy, with specified duties that include, among others, conducting financial and performance audits as directed by statute. Existing law authorizes the auditor to establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency that he or she identifies as at high risk for fraud or waste, among other things. Existing law authorizes the auditor to consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency to identify local governments that are at high risk.
This bill would additionally authorize the California State Auditor to review publicly available information to identify local governments that are at high risk.
This bill would incorporate additional changes to Section 8546.10 of the Government Code proposed by SB 1293 to be operative only if this bill and SB 1293 are enacted and this bill is enacted last.
Existing law establishes the California State Auditors Office, headed by the appointed California State Auditor and under the direction of the Milton Marks Little Hoover Commission on California State Government Organization and Economy, with specified duties that include, among others, conducting financial and performance audits as directed by statute. Existing law authorizes the auditor to establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency that he or she identifies as at high risk for fraud or waste, among other things. Existing law requires the auditor to notify the Joint Legislative Audit Committee (JLAC) when he or she identifies a local government as at high risk and requires an audit conducted pursuant to the program to be approved by JLAC. authorizes the auditor to consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency to identify local governments that are at high risk.
This bill would remove the requirement for an audit conducted pursuant to the high-risk local government agency audit program to be approved by JLAC, and would instead authorize the auditor to conduct an audit under the program, unless before the expiration of a specified 30-day notice period, JLAC adopts a motion directing the auditor to delay or cease commencing audit work. The bill would also require the auditor to notify any local government agency that he or she identifies as at high risk. additionally authorize the California State Auditor to review publicly available information to identify local governments that are at high risk.
Existing law establishes the California State Auditors Office, headed by the appointed California State Auditor and under the direction of the Milton Marks Little Hoover Commission on California State Government Organization and Economy, with specified duties that include, among others, conducting financial and performance audits as directed by statute. Existing law authorizes the auditor to establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency that he or she identifies as at high risk for fraud or waste, among other things. Existing law requires the auditor to notify the Joint Legislative Audit Committee (JLAC) when he or she identifies a local government as at high risk and requires an audit conducted pursuant to the program to be approved by JLAC.
This bill would remove the requirement for an audit conducted pursuant to the high-risk local government agency audit program to be approved by JLAC, and would instead authorize the auditor to conduct an audit under the program, unless before the expiration of a specified 30-day notice period, JLAC adopts a motion directing the auditor to delay or cease commencing audit work. The bill would also require the auditor to notify any local government agency that he or she identifies as at high risk.
(a)The California State Auditor may establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, whether created by the California Constitution or otherwise, that the California State Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
(b)In addition to identifying a local government agency as high risk on the basis of weaknesses identified in audit and investigative reports produced by the office, the California State Auditor may review publicly available information and consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high risk.
(c)The California State Auditors Office shall be responsible for the state costs associated with the high-risk local government agency audit program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from the Joint Legislative Audit Committee.
(d)(1)The California State Auditor shall notify the Joint Legislative Audit Committee whenever he or she identifies a local government as at high risk.
(2)The California State Auditor shall provide the Joint Legislative Audit Committee, at a public hearing of the committee, an annual update of all audits in progress.
(3)If a local government agency has taken significant corrective measures for deficiencies identified by the California State Auditor, that agency shall be removed from the high-risk local government agency audit program.
(e)Notwithstanding the requirements of Section 10231.5, if the California State Auditor establishes the program provided for in this section and the California State Auditor determines that a local agency is at high risk, the California State Auditor shall issue audit reports at least once every two years with recommendations for improvement in such a local government so identified.
(f)Audits conducted pursuant to this section shall be approved by the Joint Legislative Audit Committee.
SEC. 1.5.Section 8546.10 of the Government Code is amended to read:8546.10.(a)The California State Auditor may establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, whether created by the California Constitution or otherwise, that the California State Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
(b)In addition to identifying a local government agency as high risk on the basis of weaknesses identified in audit and investigative reports produced by the office, the California State Auditor may review publicly available information and consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high risk.
(c)The California State Auditors Office shall be responsible for the state costs associated with the high-risk local government agency audit program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from the Joint Legislative Audit Committee.
(d)(1)The California State Auditor shall notify the Joint Legislative Audit Committee whenever he or she identifies a local government as at high risk.
(2)The California State Auditor shall provide the Joint Legislative Audit Committee, at a public hearing of the committee, an annual update of all audits in progress.
(3)If a local government agency has taken significant corrective measures for deficiencies identified by the California State Auditor, that agency shall be removed from the high-risk local government agency audit program.
(e)Notwithstanding the requirements of Section 10231.5, if the California State Auditor establishes the program provided for in this section and the California State Auditor determines that a local government agency is at high risk, the California State Auditor shall issue audit reports at least once every three years with recommendations for improvement in the local government so identified.
(f)Audits conducted pursuant to this section shall be approved by the Joint Legislative Audit Committee.
(g)(1)The California State Auditor may conduct an initial assessment at a local government agency prior to conducting an audit, during which he or she may gather any publicly available information from a local government agency and any additional information, including any interviews, that the local government agency is willing to provide, for the purpose of identifying whether or not it is a high-risk local government agency.
(2)Before beginning an initial assessment at a local government agency, the California State Auditor shall notify the Joint Legislative Audit Committee in writing which local government agency will be assessed.
SEC. 2.Section 1.5 of this bill incorporates amendments to Section 8546.10 of the Government Code proposed by both this bill and Senate Bill 1293. That section of this bill shall only become operative if (1) both bills are enacted and become effective on or before January 1, 2019, (2) each bill amends Section 8546.10 of the Government Code, and (3) this bill is enacted after Senate Bill 1293, in which case Section 1 of this bill shall not become operative.
(a)The California State Auditor may establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, whether created by the California Constitution or otherwise, that the California State Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
(b)In addition to identifying a local government agency as high risk on the basis of weaknesses identified in audit and investigative reports produced by the office, the California State Auditor may review publicly available information and consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high risk.
(c)The California State Auditors Office shall be responsible for the state costs associated with the high-risk local government agency audit program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from the Joint Legislative Audit Committee.
(d)(1)The California State Auditor shall notify the Joint Legislative Audit Committee whenever he or she identifies a local government as at high risk.
(2)The California State Auditor shall provide the Joint Legislative Audit Committee, at a public hearing of the committee, an annual update of all audits in progress.
(3)If a local government agency has taken significant corrective measures for deficiencies identified by the California State Auditor, that agency shall be removed from the high-risk local government agency audit program.
(e)Notwithstanding the requirements of Section 10231.5, if the California State Auditor establishes the program provided for in this section and the California State Auditor determines that a local agency is at high risk, the California State Auditor shall issue audit reports at least once every two years with recommendations for improvement in such a local government so identified.
(f)Audits conducted pursuant to this section shall be approved by the Joint Legislative Audit Committee.
SEC. 1.5.Section 8546.10 of the Government Code is amended to read:8546.10.(a)The California State Auditor may establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, whether created by the California Constitution or otherwise, that the California State Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
(b)In addition to identifying a local government agency as high risk on the basis of weaknesses identified in audit and investigative reports produced by the office, the California State Auditor may review publicly available information and consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high risk.
(c)The California State Auditors Office shall be responsible for the state costs associated with the high-risk local government agency audit program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from the Joint Legislative Audit Committee.
(d)(1)The California State Auditor shall notify the Joint Legislative Audit Committee whenever he or she identifies a local government as at high risk.
(2)The California State Auditor shall provide the Joint Legislative Audit Committee, at a public hearing of the committee, an annual update of all audits in progress.
(3)If a local government agency has taken significant corrective measures for deficiencies identified by the California State Auditor, that agency shall be removed from the high-risk local government agency audit program.
(e)Notwithstanding the requirements of Section 10231.5, if the California State Auditor establishes the program provided for in this section and the California State Auditor determines that a local government agency is at high risk, the California State Auditor shall issue audit reports at least once every three years with recommendations for improvement in the local government so identified.
(f)Audits conducted pursuant to this section shall be approved by the Joint Legislative Audit Committee.
(g)(1)The California State Auditor may conduct an initial assessment at a local government agency prior to conducting an audit, during which he or she may gather any publicly available information from a local government agency and any additional information, including any interviews, that the local government agency is willing to provide, for the purpose of identifying whether or not it is a high-risk local government agency.
(2)Before beginning an initial assessment at a local government agency, the California State Auditor shall notify the Joint Legislative Audit Committee in writing which local government agency will be assessed.
SEC. 2.Section 1.5 of this bill incorporates amendments to Section 8546.10 of the Government Code proposed by both this bill and Senate Bill 1293. That section of this bill shall only become operative if (1) both bills are enacted and become effective on or before January 1, 2019, (2) each bill amends Section 8546.10 of the Government Code, and (3) this bill is enacted after Senate Bill 1293, in which case Section 1 of this bill shall not become operative.
(a)The California State Auditor may establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, whether created by the California Constitution or otherwise, that the California State Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
(b)In addition to identifying a local government agency as high risk on the basis of weaknesses identified in audit and investigative reports produced by the office, the California State Auditor may review publicly available information and consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high risk.
(c)The California State Auditors Office shall be responsible for the state costs associated with the high-risk local government agency audit program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from the Joint Legislative Audit Committee.
(d)(1)The California State Auditor shall notify the Joint Legislative Audit Committee whenever he or she identifies a local government as at high risk.
(2)The California State Auditor shall provide the Joint Legislative Audit Committee, at a public hearing of the committee, an annual update of all audits in progress.
(3)If a local government agency has taken significant corrective measures for deficiencies identified by the California State Auditor, that agency shall be removed from the high-risk local government agency audit program.
(e)Notwithstanding the requirements of Section 10231.5, if the California State Auditor establishes the program provided for in this section and the California State Auditor determines that a local agency is at high risk, the California State Auditor shall issue audit reports at least once every two years with recommendations for improvement in such a local government so identified.
(f)Audits conducted pursuant to this section shall be approved by the Joint Legislative Audit Committee.
SEC. 1.5.Section 8546.10 of the Government Code is amended to read:8546.10.(a)The California State Auditor may establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, whether created by the California Constitution or otherwise, that the California State Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
(b)In addition to identifying a local government agency as high risk on the basis of weaknesses identified in audit and investigative reports produced by the office, the California State Auditor may review publicly available information and consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high risk.
(c)The California State Auditors Office shall be responsible for the state costs associated with the high-risk local government agency audit program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from the Joint Legislative Audit Committee.
(d)(1)The California State Auditor shall notify the Joint Legislative Audit Committee whenever he or she identifies a local government as at high risk.
(2)The California State Auditor shall provide the Joint Legislative Audit Committee, at a public hearing of the committee, an annual update of all audits in progress.
(3)If a local government agency has taken significant corrective measures for deficiencies identified by the California State Auditor, that agency shall be removed from the high-risk local government agency audit program.
(e)Notwithstanding the requirements of Section 10231.5, if the California State Auditor establishes the program provided for in this section and the California State Auditor determines that a local government agency is at high risk, the California State Auditor shall issue audit reports at least once every two three years with recommendations for improvement in such a the local government so identified.
(f)Audits conducted pursuant to this section shall be approved by the Joint Legislative Audit Committee.
(g)(1)The California State Auditor may conduct an initial assessment at a local government agency prior to conducting an audit, during which he or she may gather any publicly available information from a local government agency and any additional information, including any interviews, that the local government agency is willing to provide, for the purpose of identifying whether or not it is a high-risk local government agency.
(2)Before beginning an initial assessment at a local government agency, the California State Auditor shall notify the Joint Legislative Audit Committee in writing which local government agency will be assessed.
SEC. 2.Section 1.5 of this bill incorporates amendments to Section 8546.10 of the Government Code proposed by both this bill and Senate Bill 1293. That section of this bill shall only become operative if (1) both bills are enacted and become effective on or before January 1, 2019, (2) each bill amends Section 8546.10 of the Government Code, and (3) this bill is enacted after Senate Bill 1293, in which case Section 1 of this bill shall not become operative.
(a)The California State Auditor may establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, whether created by the California Constitution or otherwise, that the California State Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
(b)In addition to identifying a local government agency as high risk on the basis of weaknesses identified in audit and investigative reports produced by the office, the California State Auditor may review publicly available information and consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high risk.
(c)The California State Auditors Office shall be responsible for the state costs associated with the high-risk local government agency audit program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from the Joint Legislative Audit Committee.
(d)(1)(A)The California State Auditor shall notify the local government agency and the Joint Legislative Audit Committee whenever he or she identifies a local government as at high risk.
(B)The California State Auditor is authorized to conduct an audit of a local government agency pursuant to this section on and after the first day after 30 calendar days of continuous session of the Legislature after the date on which the notification is transmitted to the Joint Legislative Audit Committee, unless, before the expiration of the 30-day period, the Joint Legislative Audit Committee adopts a motion directing the auditor to delay or cease commencing audit work.(2)The California State Auditor shall provide the Joint Legislative Audit Committee, at a public hearing of the committee, an annual update of all audits in progress.
(3)If a local government agency has taken significant corrective measures for deficiencies identified by the California State Auditor, that agency shall be removed from the high-risk local government agency audit program.
(e)Notwithstanding the requirements of Section 10231.5, if the California State Auditor establishes the program provided for in this section and the California State Auditor determines that a local agency is at high risk, the California State Auditor shall issue audit reports at least once every two years with recommendations for improvement in such a local government so identified.
(f)Audits conducted pursuant to this section shall be approved by the Joint Legislative Audit Committee.
(a)The California State Auditor may establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, whether created by the California Constitution or otherwise, that the California State Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
(b)In addition to identifying a local government agency as high risk on the basis of weaknesses identified in audit and investigative reports produced by the office, the California State Auditor may consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high risk.
(c)The California State Auditors Office shall be responsible for the state costs associated with the high-risk local government agency audit program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from the Joint Legislative Audit Committee.
(d)(1)(A)The California State Auditor shall notify the local government agency and the Joint Legislative Audit Committee whenever he or she identifies a local government as at high risk.
(B)The California State Auditor is authorized to conduct an audit of a local government agency pursuant to this section on and after the first day after 30 calendar days of continuous session of the Legislature after the date on which the notification is transmitted to the Joint Legislative Audit Committee, unless, before the expiration of the 30-day period, the Joint Legislative Audit Committee adopts a motion directing the auditor to delay or cease commencing audit work.
(2)The California State Auditor shall provide the Joint Legislative Audit Committee, at a public hearing of the committee, an annual update of all audits in progress.
(3)If a local government agency has taken significant corrective measures for deficiencies identified by the California State Auditor, that agency shall be removed from the high-risk local government agency audit program.
(e)Notwithstanding the requirements of Section 10231.5, if the California State Auditor establishes the program provided for in this section and the California State Auditor determines that a local agency is at high risk, the California State Auditor shall issue audit reports at least once every two years with recommendations for improvement in such a local government so identified.
(f)Audits conducted pursuant to this section shall be approved by the Joint Legislative Audit Committee.|
Date
|
Status
|
|---|---|
| Sep 18, 2018 | Chaptered by Secretary of State - Chapter 498, Statutes of 2018. |
| Sep 18, 2018 | Approved by the Governor. |
| Sep 7, 2018 | Enrolled and presented to the Governor at 2:30 p.m. |
| Aug 29, 2018 | Senate amendments concurred in. To Engrossing and Enrolling. |
| Aug 27, 2018 | In Assembly. Concurrence in Senate amendments pending. May be considered on or after August 29 pursuant to Assembly Rule 77. |
| Aug 27, 2018 | Read third time. Passed. Ordered to the Assembly. |
| Aug 23, 2018 | Read second time. Ordered to third reading. |
| Aug 22, 2018 | Read third time and amended. Ordered to second reading. |
| Aug 7, 2018 | Read second time. Ordered to third reading. |
| Aug 6, 2018 | From committee: Be ordered to second reading pursuant to Senate Rule 28.8. |
| Jun 26, 2018 | From committee: Do pass and re-refer to Com. on APPR. (Ayes 12. Noes 0.) (June 26). Re-referred to Com. on APPR. |
| May 17, 2018 | Referred to Com. on G.O. |
| Apr 26, 2018 | In Senate. Read first time. To Com. on RLS. for assignment. |
| Apr 26, 2018 | Read third time. Passed. Ordered to the Senate. |
| Apr 19, 2018 | Read second time. Ordered to Consent Calendar. |
| Apr 18, 2018 | From committee: Do pass. To Consent Calendar. (Ayes 15. Noes 0.) (April 18). |
| Apr 11, 2018 | From committee: Do pass and re-refer to Com. on APPR. with recommendation: To Consent Calendar. (Ayes 6. Noes 0.) (April 11). Re-referred to Com. on APPR. |
| Apr 5, 2018 | Re-referred to Com. on A. & A.R. |
| Apr 4, 2018 | From committee chair, with author's amendments: Amend, and re-refer to Com. on A. & A.R. Read second time and amended. |
| Mar 8, 2018 | Referred to Com. on A. & A.R. |
| Feb 17, 2018 | From printer. May be heard in committee March 19. |
| Feb 16, 2018 | Read first time. To print. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Aug 29, 2018 | AB 2822 OBERNOLTE Concurrence in Senate Amendments | Assembly Floor |
Passed |
|
| Aug 27, 2018 | Assembly 3rd Reading AB2822 Obernolte By Cannella | Senate Floor |
Passed |
|
| Jun 26, 2018 | Do pass, but first be re-referred to the Committee on [Appropriations] | Senate Standing Committee on Governmental Organization |
Passed |
|
| Apr 26, 2018 | AB 2822 OBERNOLTE Consent Calendar Second Day Regular Session | Assembly Floor |
Passed |
|
| Apr 18, 2018 | Do pass. To Consent Calendar. | Assembly Standing Committee on Appropriations |
Passed |
|
| Apr 11, 2018 | Do pass and be re-referred to the Committee on [Appropriations] with recommendation: To Consent Calendar | Assembly Standing Committee on Accountability and Administrative Review |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
CONCURRENCE IN SENATE AMENDMENTS
CSA1 Bill Id:AB 2822
Author:(Obernolte)
As Amended Ver:August 22, 2018
Majority vote
ASSEMBLY: | 74-0 | (April 26, 2018) | SENATE: | 39-0 | (August 27, 2018) |
Original Committee Reference: A. & A.R.
SUMMARY: Allows the California State Auditor (Auditor) to review publicly available information when identifying local government agencies that are high risk under the Auditor's high-risk local government agency audit program (program).
The Senate amendments make technical changes to avoid chaptering conflicts with SB 1293 (Lara) of the current legislative session, a related bill.
EXISTING LAW:
- Allows the Auditor to establish a high-risk local audit program.
- Specifies the information to use when the Auditor assesses if an entity is high risk.
- Specifies that the Auditor is responsible for the state costs of conducting the program.
- Requires the Auditor to notify the Joint Legislative Audit Committee (JLAC) when the Auditor identifies an entity as high risk.
- Requires JLAC approval prior to an audit of an entity.
FISCAL EFFECT: According to the Senate Appropriations Committee, pursuant to Senate Rule 28.8, negligible state costs.
COMMENTS: This bill allows the Auditor to use publicly available information when determining if a local government is considered high risk under the program.
Current law specifies that when determining risk of a local entity, the Auditor can use weaknesses identified in its audit and investigative reports, and through consultation with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency.
A recent opinion from the Legislative Counsel of California, the nonpartisan public agency that drafts legislative proposals and prepares legal opinions for the Legislature, found concerns related to the authority in the program.
This bill provides clarification to the existing program. Explicitly adding the public information requirement could allow the Auditor to learn about and assess possible risks based on various sources like media reports and information on local entities' web sites.
RELATED LEGISLATION: SB 1293, which is pending in the Senate, allows, after first notifying JLAC, the Auditor to conduct initial assessments when determining if an entity is high risk under the program.
Analysis Prepared by: Scott Herbstman / A. & A.R. / (916) 319-3600 FN: 0004730
Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | AB |
THIRD READING
Bill No: AB 2822
: in Senate
SENATE GOVERNMENTAL ORG. COMMITTEE: 12-0, 6/26/18
AYES: Wilk, Bradford, Cannella, Gaines, Galgiani, Glazer, Hill, Hueso, Lara, Portantino, Vidak, Wiener
NO VOTE RECORDED: Dodd
SENATE APPROPRIATIONS COMMITTEE: Senate Rule 28.8
ASSEMBLY FLOOR: 74-0, 4/26/18 (Consent) - See last page for vote
DIGEST:
This bill authorizes the California State Auditor (Auditor) to review publicly available information to identify local governments that are at high risk.
Senate Floor Amendments of 8/22/18 add chaptering out language to avoid potential conflicts with provisions of SB 1293 (Lara) of the current legislative session.
Existing law:
- Establishes the Auditor’s Office headed by the Auditor, with specified duties that includes, among others, conducting financial and performance audits as directed by statute and other government audits as requested by the Joint Legislative Audit Committee (JLAC).
- Authorizes the Auditor to establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, that the Auditor identifies as being at high-risk for the potential waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
- Authorizes the Auditor to consult with the State Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high-risk.
- Provides that the Auditor’s office shall be responsible for the state costs associated with the high-risk local government agency audit program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from JLAC.
This bill authorizes the Auditor to review publicly available information to identify local governments that are at high risk.
Background
Purpose of the bill. According to the author, “the High-Risk Local Government Agency Audit Program is an important tool for the State Auditor to help keep an eye out for potential fraud, waste, abuse, or fiscal mismanagement in local entities. AB 2822 will help clarify that the Auditor has the express authority to use publically available information in order to determine which local entities may need to be audited.”
High-risk local government agency audit program. AB 187 (Lara, Chapter 451, Statutes of 2011) authorized the Auditor to establish the high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency that the Auditor identifies as being at high-risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
In implementing the program, the Auditor worked with cities, counties, special districts, and others which resulted in California State Regulations Sections 61100-61149, establishing a 10-step process for the program. The initial assessment of that process includes using publicly available information, establishing formal contact with the local agency, holding an entrance conference to discuss risk factors, visiting the local agency, and holding an initial assessment closeout meeting.
Once the initial five steps are completed, the Auditor will either cease their work if he or she believes the local agency is not at high-risk, or, the Auditor will submit an audit proposal to JLAC for the committee’s consideration. While audits conducted under the high-risk local government agency audit program must be approved by JLAC, a recent opinion from Legislative Counsel has left room for interpretation whether current law authorizes the initial assessment portion of the process to include on-site reviews.
Related/Prior Legislation
AB 2729 (Muratsuchi, 2018) authorizes the Auditor to conduct an initial assessment at a local government agency as a part of the high-risk local government agency audit program, and requires the Auditor to notify JLAC in writing which agency will be assessed. (Held in the Senate Appropriations Committee)
SB 1293 (Lara, 2018) authorizes the Auditor to gather information from a local government agency as part of conducting an initial assessment in identifying a high-risk local government agency, prior to receiving approval from JLAC. (Pending on the Assembly Floor)
SB 187 (Lara, Chapter 451, Statutes of 2011) authorized the Auditor to establish a Program to identify, audit, and issue reports on any local government agency, including any city, county, or special district.
FISCAL EFFECT: Appropriation: Fiscal Com.: Local:
None received
OPPOSITION: (Verified 8/22/18)
None received
ASSEMBLY FLOOR: 74-0, 4/26/18
AYES: Acosta, Aguiar-Curry, Arambula, Baker, Berman, Bigelow, Bloom, Bonta, Brough, Burke, Caballero, Calderon, Carrillo, Cervantes, Chau, Chávez, Chen, Chiu, Choi, Chu, Cooley, Cooper, Cunningham, Dahle, Daly, Eggman, Flora, Frazier, Friedman, Gallagher, Eduardo Garcia, Gipson, Gloria, Gonzalez Fletcher, Gray, Grayson, Harper, Holden, Irwin, Jones-Sawyer, Kalra, Kamlager-Dove, Kiley, Lackey, Levine, Limón, Low, Maienschein, Mathis, Mayes, McCarty, Medina, Melendez, Mullin, Muratsuchi, Nazarian, Obernolte, O'Donnell, Patterson, Quirk, Quirk-Silva, Reyes, Rubio, Salas, Santiago, Steinorth, Mark Stone, Thurmond, Ting, Voepel, Waldron, Weber, Wood, Rendon
NO VOTE RECORDED: Travis Allen, Fong, Cristina Garcia, Rodriguez
8/23/18 16:15:31
**** END ****
Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | AB |
THIRD READING
Bill No: AB 2822
:
SENATE GOVERNMENTAL ORG. COMMITTEE: 12-0, 6/26/18
AYES: Wilk, Bradford, Cannella, Gaines, Galgiani, Glazer, Hill, Hueso, Lara, Portantino, Vidak, Wiener
NO VOTE RECORDED: Dodd
SENATE APPROPRIATIONS COMMITTEE: Senate Rule 28.8
ASSEMBLY FLOOR: 74-0, 4/26/18 (Consent) - See last page for vote
DIGEST:
This bill authorizes the California State Auditor (Auditor) to review publicly available information to identify local governments that are at high risk.
Existing law:
- Establishes the Auditor’s Office headed by the Auditor, with specified duties that includes, among others, conducting financial and performance audits as directed by statute and other government audits as requested by the Joint Legislative Audit Committee (JLAC).
- Authorizes the Auditor to establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, that the Auditor identifies as being at high-risk for the potential waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
- Authorizes the Auditor to consult with the State Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high-risk.
- Provides that the Auditor’s office shall be responsible for the state costs associated with the high-risk local government agency audit program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from JLAC.
This bill authorizes the Auditor to review publicly available information to identify local governments that are at high risk.
Background
Purpose of the bill. According to the author, “the High-Risk Local Government Agency Audit Program is an important tool for the State Auditor to help keep an eye out for potential fraud, waste, abuse, or fiscal mismanagement in local entities. AB 2822 will help clarify that the Auditor has the express authority to use publically available information in order to determine which local entities may need to be audited.”
High-risk local government agency audit program. AB 187 (Lara, Chapter 451, Statutes of 2011) authorized the Auditor to establish the high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency that the Auditor identifies as being at high-risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
In implementing the program, the Auditor worked with cities, counties, special districts, and others which resulted in California State Regulations Sections 61100-61149, establishing a 10-step process for the program. The initial assessment of that process includes using publicly available information, establishing formal contact with the local agency, holding an entrance conference to discuss risk factors, visiting the local agency, and holding an initial assessment closeout meeting.
Once the initial five steps are completed, the Auditor will either cease their work if he or she believes the local agency is not at high-risk, or, the Auditor will submit an audit proposal to JLAC for the committee’s consideration. While audits conducted under the high-risk local government agency audit program must be approved by JLAC, a recent opinion from Legislative Counsel has left room for interpretation whether current law authorizes the initial assessment portion of the process to include on-site reviews.
Related/Prior Legislation
AB 2729 (Muratsuchi, 2018) authorizes the Auditor to conduct an initial assessment at a local government agency as a part of the high-risk local government agency audit program, and requires the Auditor to notify JLAC in writing which agency will be assessed. (Pending in the Senate Appropriations Committee)
SB 1293 (Lara, 2018) authorizes the Auditor to gather information from a local government agency as part of conducting an initial assessment in identifying a high-risk local government agency, prior to receiving approval from JLAC. (Pending in the Assembly Appropriations Committee)
SB 187 (Lara, Chapter 451, Statutes of 2011) authorized the Auditor to establish a Program to identify, audit, and issue reports on any local government agency, including any city, county, or special district.
FISCAL EFFECT: Appropriation: Fiscal Com.: Local:
None received
None received
ASSEMBLY FLOOR: 74-0, 4/26/18
AYES: Acosta, Aguiar-Curry, Arambula, Baker, Berman, Bigelow, Bloom, Bonta, Brough, Burke, Caballero, Calderon, Carrillo, Cervantes, Chau, Chávez, Chen, Chiu, Choi, Chu, Cooley, Cooper, Cunningham, Dahle, Daly, Eggman, Flora, Frazier, Friedman, Gallagher, Eduardo Garcia, Gipson, Gloria, Gonzalez Fletcher, Gray, Grayson, Harper, Holden, Irwin, Jones-Sawyer, Kalra, Kamlager-Dove, Kiley, Lackey, Levine, Limón, Low, Maienschein, Mathis, Mayes, McCarty, Medina, Melendez, Mullin, Muratsuchi, Nazarian, Obernolte, O'Donnell, Patterson, Quirk, Quirk-Silva, Reyes, Rubio, Salas, Santiago, Steinorth, Mark Stone, Thurmond, Ting, Voepel, Waldron, Weber, Wood, Rendon
NO VOTE RECORDED: Travis Allen, Fong, Cristina Garcia, Rodriguez
8/8/18 10:50:52
**** END ****
SENATE COMMITTEE ON GOVERNMENTAL ORGANIZATION
Senator Bill Dodd
Chair
2017 - 2018 Regular
Bill No: AB Hearing Date: 6/26/2018
Author: | Obernolte | ||
Version: | Amended | ||
Urgency: | Fiscal: | ||
Consultant: | |||
SUBJECT:
DIGEST: This bill authorizes the California State Auditor (Auditor) to review publicly available information to identify local governments that are at high risk.
ANALYSIS:
Existing law:
- Establishes the Auditor’s Office headed by the Auditor, with specified duties that includes, among others, conducting financial and performance audits as directed by statute and other government audits as requested by the Joint Legislative Audit Committee (JLAC).
- Authorizes the Auditor to establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, that the Auditor identifies as being at high-risk for the potential waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
- Authorizes the Auditor to consult with the State Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high-risk.
- Provides that the Auditor’s office shall be responsible for the state costs associated with the high-risk local government agency audit program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from JLAC.
- Provides that if a local government agency has taken significant corrective measures for deficiencies identified by the Auditor, that agency shall be removed from the high-risk local government agency audit program.
- Requires the Auditor to notify JLAC whenever he or she identifies a local government as high-risk.
- Requires that audits conducted pursuant to those provisions be approved by JLAC.
This bill authorizes the Auditor to review publicly available information to identify local governments that are at high risk.
Background
Purpose of the bill. According to the author, “the High-Risk Local Government Agency Audit Program is an important tool for the State Auditor to help keep an eye out for potential fraud, waste, abuse, or fiscal mismanagement in local entities. AB 2822 will help clarify that the Auditor has the express authority to use publically available information in order to determine which local entities may need to be audited.”
High-risk local government agency audit program. AB 187 (Lara, Chapter 451, Statutes of 2011) authorized the Auditor to establish the high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency that the Auditor identifies as being at high-risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
In implementing the program, the Auditor worked with cities, counties, special districts, and others which resulted in California State Regulations Sections 61100-61149, establishing a 10-step process for the program. The initial assessment of that process includes using publicly available information, establishing formal contact with the local agency, holding an entrance conference to discuss risk factors, visiting the local agency, and holding an initial assessment closeout meeting.
Once the initial five steps are completed, the Auditor will either cease their work if he or she believes the local agency is not at high-risk, or, the Auditor will submit an audit proposal to JLAC for the committee’s consideration. While audits conducted under the high-risk local government agency audit program must be approved by JLAC, a recent opinion from Legislative Counsel has left room for interpretation whether current law authorizes the initial assessment portion of the process to include on-site reviews.
Competing bills. It is important to note that this committee unanimously approved a bill on this same subject earlier this year. SB 1293 (Lara) clarifies that the Auditor may first conduct an initial assessment, during which he or she may gather information from a local government agency for the purposes of identifying it as a high-risk local government agency. Because this bill codifies what the Auditor may review in identifying high-risk local governments, it can be argued that this bill contradicts the intent of SB 1293. That bill is pending in the Assembly Accountability & Administrative Review Committee.
Additionally, this committee will be considering AB 2729 (Muratsuchi), which authorizes the Auditor to conduct an initial assessment at a local government agency, and requires the Auditor to notify JLAC in writing which agency will be assessed. Additionally, AB 2729 provides that the Auditor may gather any publicly available information during an initial assessment which is the intent of this bill.
Prior/Related Legislation
AB 2729 (Muratsuchi, 2018) authorizes the Auditor to conduct an initial assessment at a local government agency as a part of the high-risk local government agency audit program, and requires the Auditor to notify JLAC in writing which agency will be assessed. (Pending in the Senate Governmental Organization Committee)
SB 1293 (Lara, 2018) authorizes the Auditor to gather information from a local government agency as part of conducting an initial assessment in identifying a high-risk local government agency, prior to receiving approval from JLAC. (Pending referral in the Assembly Accountability and Administrative Review Committee)
AB 32 (Rodriguez, Chapter 606, Statutes of 2017) set a recruitment process for Auditor candidates by requiring JLAC to conduct a comprehensive search before it selects three qualified individuals for the position to be forwarded to the Governor to appoint one of the three as the Auditor.
SB 187 (Lara, Chapter 451, Statutes of 2011) authorized the Auditor to establish a Program to identify, audit, and issue reports on any local government agency, including any city, county, or special district.
SB 1437 (Speier, Chapter 251, Statutes of 2004) authorized the Auditor to establish a high-risk government agency audit program for the purpose of identifying, auditing, and issuing reports on any state agency that the Auditor identified as high-risk for the potential of waste, fraud, abuse, and mismanagement, or that has major challenges associated with its economy, efficiency, or effectiveness.
SB 37 (Maddy, Chapter 251, Statutes of 1993) created the Bureau of State Audits under the direction of the Little Hoover Commission, and moved many of the duties and powers of the Officer of Auditor General to the Bureau of State Audits.
FISCAL EFFECT: Appropriation: No Fiscal Com.: Yes Local: No
SUPPORT:
None received
OPPOSITION:
None received
Date of Hearing: April 18, 2018
ASSEMBLY COMMITTEE ON APPROPRIATIONS
Lorena Gonzalez Fletcher, Chair
ABPCA Bill Id:AB 2822
Author:(Obernolte) – As Amended Ver:April 4, 2018
Policy Committee: | Accountability and Administrative Review | Vote: | 6 - 0 |
|
| ||
|
|
Urgency: No State Mandated Local Program: No Reimbursable: No
SUMMARY:
This bill clarifies that the California State Auditor (Auditor) may review publicly available information to identify local government agencies that are high risk under the Auditor's high-risk local government agency audit program.
FISCAL EFFECT:
Negligible state fiscal impact.
COMMENTS:
Purpose. According to the author, the program “is an important tool for the State Auditor to help keep an eye out for potential fraud, waste, abuse, or fiscal mismanagement in local entities.” This bill clarifies the Auditor’s authority to use publically available information to determine local entities that may need to be audited.
Background. Current law authorizes the State Auditor to establish a high-risk local government agency audit program to identify, audit, and issue reports on any local government agency that the Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness. Current law specifies the Auditor, when determining risk of a local entity, can use weaknesses identified in its audit and investigative reports and consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency.
A recent opinion from the Legislative Counsel of California found concerns related to the authority in the program. This bill clarifies the Auditor’s authority by explicitly adding public information to the list of sources the Auditor may use to identify local governments as high risk under the program.
Related Legislation. AB 2729 (Muratsuchi), of the 2017-18 Legislative Session, establishes additional requirements for the high-risk local audit program. It is pending hearing in the Accountability and Administrative Review Committee
Prior Legislation. AB 187 (Lara), Chapter 451 Statutes of 2011, allows the Auditor to establish a high-risk local audit program and specifies how it is to operate.
Analysis Prepared by: Jennifer Swenson / APPR. / (916) 319-2081
Date of Hearing: April 11, 2018
ASSEMBLY COMMITTEE ON ACCOUNTABILITY AND ADMINISTRATIVE REVIEW
Susan Talamantes Eggman, Chair
ABPCA Bill Id:AB 2822 (
Author:Obernolte) – As Amended Ver:April 4, 2018
SUBJECT: California State Auditor: high-risk local government agency audit program
SUMMARY: Allows the California State Auditor (Auditor) to review publicly available information when identifying local government agencies that are high risk under the Auditor's high-risk local government agency audit program (program).
EXISTING LAW:
- Allows the Auditor to establish a high-risk local audit program.
- Specifies the information to use when the Auditor assesses if an entity is high risk.
- Specifies that the Auditor is responsible for the state costs of conducting the program.
- Requires the Auditor to notify the Joint Legislative Audit Committee (JLAC) when the Auditor identifies an entity as high risk.
- Requires JLAC approval prior to an audit of an entity.
FISCAL EFFECT: Unknown
COMMENTS: This bill allows the Auditor to use publicly available information when determining if a local government is considered high risk under the program.
Current law specifies that when determining risk of a local entity, the Auditor can use weaknesses identified in its audit and investigative reports, and through consultation with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency.
A recent opinion from the Legislative Counsel of California, the nonpartisan public agency that drafts legislative proposals and prepares legal opinions for the Legislature, found concerns related to the authority in the program.
This bill provides clarification to the existing program. Explicitly adding the public information requirement could allow the Auditor to learn about and assess possible risks based on various sources like media reports and information on local entities' web sites.
According to the author, the program "is an important tool for the State Auditor to help keep an eye out for potential fraud, waste, abuse, or fiscal mismanagement in local entities. AB 2822 will help clarify that the Auditor has the express authority to use publically available information in order to determine which local entities may need to be audited."
.
PRIOR LEGISLATION: AB 187 (Lara), Chapter 451 of 2011, allows the Auditor to establish a high-risk local audit program and specifies how it operates.
RELATED LEGISLATION: AB 2729 (Muratsuchi), which is pending in this committee, establishes additional requirements for the high-risk local audit program.
REGISTERED SUPPORT / OPPOSITION:
Support
None on file
Opposition
None on file
Analysis Prepared by: Scott Herbstman / A. & A.R. / (916) 319-3600
Discussed in Hearing
View Older Hearings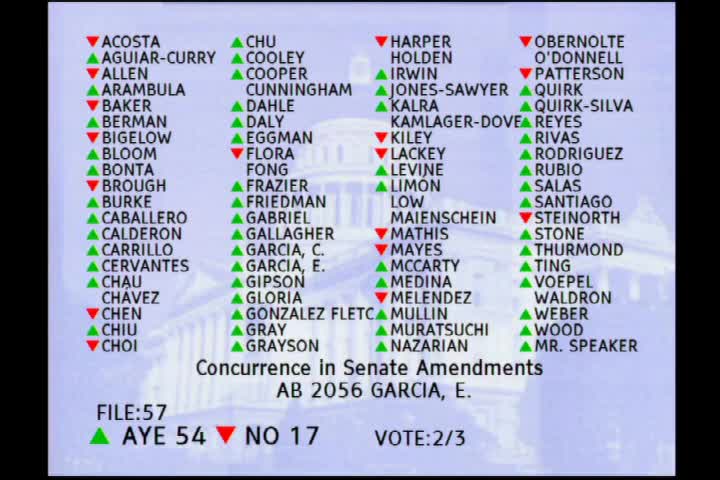
Bill Author
Bill Co-Author(s):