SB 1115: Property taxation: welfare exemption: low income housing.
- Session Year: 2017-2018
- House: Senate
- Latest Version Date: 2018-09-22
The California Constitution authorizes the Legislature to exempt from taxation, in whole or in part, property that is used exclusively for religious, hospital, or charitable purposes, and is owned or held in trust by a nonprofit entity. Pursuant to this constitutional authority, existing law partially exempts from property taxation property used exclusively for rental housing and related facilities, if specified criteria are met, including, except in the case of a limited partnership in which the managing general partner is a nonprofit corporation eligible for the exemption, that 90% or more of the occupants of the property are lower income households whose rents do not exceed the rent limits prescribed by a specified law. Existing law limits the total exemption amount allowed to a taxpayer, with respect to a single property or multiple properties for any fiscal year on the sole basis of the application of this criterion, to $10,000,000 of tax.
This bill would increase the total exemption amount allowed from $10,000,000 to $20,000,000 in assessed value with respect to lien dates occurring on and after January 1, 2019. The bill would require any outstanding qualified ad valorem property tax in excess of the $10,000,000 limitation, and related interest or penalty, which was levied or imposed on and after January 1, 2017, and before January 1, 2019, with respect to qualified property for which a qualified claim was filed, to be canceled to the extent that the amount canceled does not result in a total assessed value exemption amount in excess of $20,000,000 being allowed to a qualified taxpayer with respect to a single property or multiple properties for any fiscal year. The bill would, on and after January 1, 2019, prohibit an escape assessment from being levied on qualified property if that amount would be subject to cancellation pursuant to this bill.
By adding to the duties of local tax officials, this bill would impose a state-mandated local program.
The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement.
This bill would provide that, if the Commission on State Mandates determines that the bill contains costs mandated by the state, reimbursement for those costs shall be made pursuant to the statutory provisions noted above.
Existing law requires the state to reimburse local agencies annually for certain property tax revenues lost as a result of any exemption or classification of property for purposes of ad valorem property taxation.
This bill would provide that, notwithstanding those provisions, no appropriation is made and the state shall not reimburse local agencies for property tax revenues lost by them pursuant to the bill.
The California Constitution authorizes the Legislature to exempt from taxation, in whole or in part, property that is used exclusively for religious, hospital, or charitable purposes, and is owned or held in trust by a nonprofit entity. Pursuant to this constitutional authority, existing law partially exempts from property taxation property used exclusively for rental housing and related facilities, if specified criteria are met, including, except in the case of a limited partnership in which the managing general partner is a nonprofit corporation eligible for the exemption, that 90% or more of the occupants of the property are lower income households whose rents do not exceed the rent limits prescribed by a specified law. Existing law limits the total exemption amount allowed to a taxpayer, with respect to a single property or multiple properties for any fiscal year on the sole basis of the application of this criterion, to $10,000,000 of tax.
This bill would increase the total exemption amount allowed from $10,000,000 to $20,000,000 in assessed value with respect to lien dates occurring on and after January 1, 2019. The bill would require any outstanding qualified ad valorem property tax in excess of the $10,000,000 limitation, and related interest or penalty, which was levied or imposed on and after January 1, 2017, and before January 1, 2019, with respect to qualified property for which a qualified claim was filed, to be canceled to the extent that the amount canceled does not result in a total assessed value exemption amount in excess of $20,000,000 being allowed to a qualified taxpayer with respect to a single property or multiple properties for any fiscal year. The bill would, on and after January 1, 2019, prohibit an escape assessment from being levied on qualified property if that amount would be subject to cancellation pursuant to this bill.
By adding to the duties of local tax officials, this bill would impose a state-mandated local program.
The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement.
This bill would provide that, if the Commission on State Mandates determines that the bill contains costs mandated by the state, reimbursement for those costs shall be made pursuant to the statutory provisions noted above.
Existing law requires the state to reimburse local agencies annually for certain property tax revenues lost as a result of any exemption or classification of property for purposes of ad valorem property taxation.
This bill would provide that, notwithstanding those provisions, no appropriation is made and the state shall not reimburse local agencies for property tax revenues lost by them pursuant to the bill.
The California Constitution authorizes the Legislature to exempt from taxation, in whole or in part, property that is used exclusively for religious, hospital, or charitable purposes, and is owned or held in trust by a nonprofit entity. Pursuant to this constitutional authority, existing law partially exempts from property taxation property used exclusively for rental housing and related facilities, if specified criteria are met, including, except in the case of a limited partnership in which the managing general partner is a nonprofit corporation eligible for the exemption, that 90% or more of the occupants of the property are lower income households whose rents do not exceed the rent limits prescribed by a specified law. Existing law limits the total exemption amount allowed to a taxpayer, with respect to a single property or multiple properties for any fiscal year on the sole basis of the application of this criterion, to $10,000,000 of tax.
This bill would delete the $10,000,000 limitation increase the total exemption amount allowed from $10,000,000 to $20,000,000 in assessed value with respect to lien dates occurring on and after January 1, 2019. The bill would require any outstanding qualified ad valorem property tax in excess of the $10,000,000 limitation, and related interest or penalty, which was levied or imposed on and after January 1, 2017, and before January 1, 2019, with respect to qualified property for which a qualified claim was filed, to be canceled. canceled to the extent that the amount canceled does not result in a total assessed value exemption amount in excess of $20,000,000 being allowed to a qualified taxpayer with respect to a single property or multiple properties for any fiscal year. The bill would, on and after January 1, 2019, prohibit an escape assessment from being levied on qualified property if that amount would be subject to cancellation pursuant to this bill.
By adding to the duties of local tax officials, this bill would impose a state-mandated local program.
The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement.
This bill would provide that, if the Commission on State Mandates determines that the bill contains costs mandated by the state, reimbursement for those costs shall be made pursuant to the statutory provisions noted above.
Existing law requires the state to reimburse local agencies annually for certain property tax revenues lost as a result of any exemption or classification of property for purposes of ad valorem property taxation.
This bill would provide that, notwithstanding those provisions, no appropriation is made and the state shall not reimburse local agencies for property tax revenues lost by them pursuant to the bill.
The California Constitution authorizes the Legislature to exempt from taxation, in whole or in part, property that is used exclusively for religious, hospital, or charitable purposes, and is owned or held in trust by a nonprofit entity. Pursuant to this constitutional authority, existing law partially exempts from property taxation property used exclusively for rental housing and related facilities, if specified criteria are met, including, except in the case of a limited partnership in which the managing general partner is a nonprofit corporation eligible for the exemption, that 90% or more of the occupants of the property are lower income households whose rents do not exceed the rent limits prescribed by a specified law. Existing law limits the total exemption amount allowed to a taxpayer, with respect to a single property or multiple properties for any fiscal year on the sole basis of the application of this criterion, to $10,000,000 of tax.
This bill would delete the $10,000,000 limitation with respect to lien dates occurring on and after January 1, 2019. The bill would require any outstanding qualified ad valorem property tax in excess of the $10,000,000 limitation, and related interest or penalty, which was levied or imposed on and after January 1, 2017, and before January 1, 2019, with respect to qualified property for which a qualified claim was filed, to be canceled. The bill would, on and after January 1, 2019, prohibit an escape assessment from being levied on qualified property if that amount would be subject to cancellation pursuant to this bill.
By adding to the duties of local tax officials, this bill would impose a state-mandated local program.
The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement.
This bill would provide that, if the Commission on State Mandates determines that the bill contains costs mandated by the state, reimbursement for those costs shall be made pursuant to the statutory provisions noted above.
Existing law requires the state to reimburse local agencies annually for certain property tax revenues lost as a result of any exemption or classification of property for purposes of ad valorem property taxation.
This bill would provide that, notwithstanding those provisions, no appropriation is made and the state shall not reimburse local agencies for property tax revenues lost by them pursuant to the bill.
The California Constitution authorizes the Legislature to exempt from taxation, in whole or in part, property that is used exclusively for religious, hospital, or charitable purposes, and is owned or held in trust by a nonprofit entity. Pursuant to this constitutional authority, existing law partially exempts from property taxation property used exclusively for rental housing and related facilities, if specified criteria are met, including, except in the case of a limited partnership in which the managing general partner is a nonprofit corporation eligible for the exemption, that 90% or more of the occupants of the property are lower income households whose rents do not exceed the rent limits prescribed by a specified law. Existing law limits the total exemption amount allowed to a taxpayer, with respect to a single property or multiple properties for any fiscal year on the sole basis of the application of this criterion, to $10,000,000 of tax.
This bill would delete the $10,000,000 limitation with respect to lien dates occurring on and after January 1, 2019. The bill would require any outstanding qualified ad valorem property tax in excess of the $10,000,000 limitation, and related interest or penalty, which was levied or imposed on and after January 1, 2017, and before January 1, 2019, with respect to qualified property for which a qualified claim was filed, to be canceled. The bill would, on and after January 1, 2019, prohibit an escape assessment from being levied on qualified property if that amount would be subject to cancellation pursuant to this bill.
By adding to the duties of local tax officials, this bill would impose a state-mandated local program.
The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement.
This bill would provide that, if the Commission on State Mandates determines that the bill contains costs mandated by the state, reimbursement for those costs shall be made pursuant to the statutory provisions noted above.
Existing law requires the state to reimburse local agencies annually for certain property tax revenues lost as a result of any exemption or classification of property for purposes of ad valorem property taxation.
This bill would provide that, notwithstanding those provisions, no appropriation is made and the state shall not reimburse local agencies for property tax revenues lost by them pursuant to the bill.
(a)Property used exclusively for religious, hospital, scientific, or charitable purposes owned and operated by community chests, funds, foundations, limited liability companies, or corporations organized and operated for religious, hospital, scientific, or charitable purposes is exempt from taxation, including ad valorem taxes to pay the interest and redemption charges on any indebtedness approved by the voters prior to July 1, 1978, or any bonded indebtedness for the acquisition or improvement of real property approved on or after July 1, 1978, by two-thirds of the votes cast by the voters voting on the proposition, if:
(1)The owner is not organized or operated for profit. However, in the case of hospitals, the organization shall not be deemed to be organized or operated for profit if, during the immediately preceding fiscal year, operating revenues, exclusive of gifts, endowments, and grants-in-aid, did not exceed operating expenses by an amount equivalent to 10 percent of those operating expenses. As used herein, operating expenses include depreciation based on cost of replacement and amortization of, and interest on, indebtedness.
(2)No part of the net earnings of the owner inures to the benefit of any private shareholder or individual.
(3)The property is used for the actual operation of the exempt activity, and does not exceed an amount of property reasonably necessary to the accomplishment of the exempt purpose.
(A)For the purposes of determining whether the property is used for the actual operation of the exempt activity, consideration shall not be given to use of the property for either or both of the following described activities if that use is occasional:
(i)The owner conducts fundraising activities on the property and the proceeds derived from those activities are not unrelated business taxable income, as defined in Section 512 of the Internal Revenue Code, of the owner and are used to further the exempt activity of the owner.
(ii)The owner permits any other organization that meets all of the requirements of this subdivision, other than ownership of the property, to conduct fundraising activities on the property and the proceeds derived from those activities are not unrelated business taxable income, as defined in Section 512 of the Internal Revenue Code, of the organization, are not subject to the tax on unrelated business taxable income that is imposed by Section 511 of the Internal Revenue Code, and are used to further the exempt activity of the organization.
(B)For purposes of subparagraph (A):
(i)Occasional use means use of the property on an irregular or intermittent basis by the qualifying owner or any other qualifying organization described in clause (ii) of subparagraph (A) that is incidental to the primary activities of the owner or the other organization.
(ii)Fundraising activities means both activities involving the direct solicitation of money or other property and the anticipated exchange of goods or services for money between the soliciting organization and the organization or person solicited.
(C)Subparagraph (A) shall have no application in determining whether paragraph (3) has been satisfied unless the owner of the property and any other organization using the property as provided in subparagraph (A) have filed with the assessor a valid organizational clearance certificate issued pursuant to Section 254.6.
(D)For the purposes of determining whether the property is used for the actual operation of the exempt activity, consideration shall not be given to the use of the property for meetings conducted by any other organization if the meetings are incidental to the other organizations primary activities, are not fundraising meetings or activities as defined in subparagraph (B), are held no more than once per week, and the other organization and its use of the property meet all other requirements of paragraphs (1) to (5), inclusive, of this subdivision. The owner or the other organization also shall file with the assessor a copy of a valid, unrevoked letter or ruling from the Internal Revenue Service or the Franchise Tax Board stating that the other organization, or the national organization of which it is a local chapter or affiliate, qualifies as an exempt organization under Section 501(c)(3) or 501(c)(4) of the Internal Revenue Code or Section 23701d, 23701f, or 23701w.
(E)Nothing in subparagraph (A), (B), (C), or (D) shall be construed to either enlarge or restrict the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(4)The property is not used or operated by the owner or by any other person so as to benefit any officer, trustee, director, shareholder, member, employee, contributor, or bondholder of the owner or operator, or any other person, through the distribution of profits, payment of excessive charges or compensations, or the more advantageous pursuit of their business or profession.
(5)The property is not used by the owner or members thereof for fraternal or lodge purposes, or for social club purposes except where that use is clearly incidental to a primary religious, hospital, scientific, or charitable purpose.
(6)The property is irrevocably dedicated to religious, charitable, scientific, or hospital purposes and upon the liquidation, dissolution, or abandonment of the owner will not inure to the benefit of any private person except a fund, foundation, or corporation organized and operated for religious, hospital, scientific, or charitable purposes.
(7)The property, if used exclusively for scientific purposes, is used by a foundation or institution that, in addition to complying with the foregoing requirements for the exemption of charitable organizations in general, has been chartered by the Congress of the United States (except that this requirement shall not apply when the scientific purposes are medical research), and whose objects are the encouragement or conduct of scientific investigation, research, and discovery for the benefit of the community at large.
The exemption provided for herein shall be known as the welfare exemption. This exemption shall be in addition to any other exemption now provided by law, and the existence of the exemption provision in paragraph (2) of subdivision (a) of Section 202 shall not preclude the exemption under this section for museum or library property. Except as provided in subdivision (e), this section shall not be construed to enlarge the college exemption.
(b)Property used exclusively for school purposes of less than collegiate grade and owned and operated by religious, hospital, or charitable funds, foundations, limited liability companies, or corporations, which property and funds, foundations, limited liability companies, or corporations meet all of the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(c)Property used exclusively for nursery school purposes and owned and operated by religious, hospital, or charitable funds, foundations, limited liability companies, or corporations, which property and funds, foundations, limited liability companies, or corporations meet all the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(d)Property used exclusively for a noncommercial educational FM broadcast station or an educational television station, and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations meeting all of the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(e)Property used exclusively for religious, charitable, scientific, or hospital purposes and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations or educational institutions of collegiate grade, as defined in Section 203, which property and funds, foundations, limited liability companies, corporations, or educational institutions meet all of the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section. As to educational institutions of collegiate grade, as defined in Section 203, the requirements of paragraph (6) of subdivision (a) shall be deemed to be met if both of the following are met:
(1)The property of the educational institution is irrevocably dedicated in its articles of incorporation to charitable and educational purposes, to religious and educational purposes, or to educational purposes.
(2)The articles of incorporation of the educational institution provide for distribution of its property upon its liquidation, dissolution, or abandonment to a fund, foundation, or corporation organized and operated for religious, hospital, scientific, charitable, or educational purposes meeting the requirements for exemption provided by Section 203 or this section.
(f)Property used exclusively for housing and related facilities for elderly or handicapped families and financed by, including, but not limited to, the federal government pursuant to Section 202 of Public Law 86-372 (12 U.S.C. Sec. 1701q), as amended, Section 231 of Public Law 73-479 (12 U.S.C. Sec. 1715v), Section 236 of Public Law 90-448 (12 U.S.C. Sec. 1715z), or Section 811 of Public Law 101-625 (42 U.S.C. Sec. 8013), and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations meeting all of the requirements of this section shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
The amendment of this paragraph made by Chapter 1102 of the Statutes of 1984 does not constitute a change in, but is declaratory of, existing law. However, no refund of property taxes shall be required as a result of this amendment for any fiscal year prior to the fiscal year in which the amendment takes effect.
Property used exclusively for housing and related facilities for elderly or handicapped families at which supplemental care or services designed to meet the special needs of elderly or handicapped residents are not provided, or that is not financed by the federal government pursuant to Section 202 of Public Law 86-372 (12 U.S.C. Sec. 1701q), as amended, Section 231 of Public Law 73-479 (12 U.S.C. Sec. 1715v), Section 236 of Public Law 90-448 (12 U.S.C. Sec. 1715z), or Section 811 of Public Law 101-625 (42 U.S.C. Sec. 8013), shall not be entitled to exemption pursuant to this subdivision unless the property is used for housing and related facilities for low- and moderate-income elderly or handicapped families. Property that would otherwise be exempt pursuant to this subdivision, except that it includes some housing and related facilities for other than low- or moderate-income elderly or handicapped families, shall be entitled to a partial exemption. The partial exemption shall be equal to that percentage of the value of the property that is equal to the percentage that the number of low- and moderate-income elderly and handicapped families represents of the total number of families occupying the property.
As used in this subdivision, low and moderate income has the same meaning as the term persons and families of low or moderate income as defined by Section 50093 of the Health and Safety Code.
(g)(1)Property used exclusively for rental housing and related facilities and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations, including limited partnerships in which the managing general partner is an eligible nonprofit corporation or eligible limited liability company, meeting all of the requirements of this section, or by veterans organizations, as described in Section 215.1, meeting all the requirements of paragraphs (1) to (7), inclusive, of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section and shall be entitled to a partial exemption equal to that percentage of the value of the property that is equal to the percentage that the number of units serving lower income households represents of the total number of residential units in any year in which any of the following criteria applies:
(A)The acquisition, rehabilitation, development, or operation of the property, or any combination of these factors, is financed with tax-exempt mortgage revenue bonds or general obligation bonds, or is financed by local, state, or federal loans or grants and the rents of the occupants who are lower income households do not exceed those prescribed by deed restrictions or regulatory agreements pursuant to the terms of the financing or financial assistance.
(B)The owner of the property is eligible for and receives low-income housing tax credits pursuant to Section 42 of the Internal Revenue Code of 1986, as added by Public Law 99-514.
(C)In the case of a claim, other than a claim with respect to property owned by a limited partnership in which the managing general partner is an eligible nonprofit corporation, that is filed for the 200001 fiscal year or any fiscal year thereafter, 90 percent or more of the occupants of the property are lower income households whose rent does not exceed the rent prescribed by Section 50053 of the Health and Safety Code. The total exemption amount allowed under this subdivision to a taxpayer, with respect to a single property or multiple properties for any fiscal year on the sole basis of the application of this subparagraph, may not exceed twenty million dollars ($20,000,000) in assessed value.
(D)(i)The property was previously purchased and owned by the Department of Transportation pursuant to a consent decree requiring housing mitigation measures relating to the construction of a freeway and is now solely owned by an organization that qualifies as an exempt organization under Section 501(c)(3) of the Internal Revenue Code.
(ii)This subparagraph shall not apply to property owned by a limited partnership in which the managing partner is an eligible nonprofit corporation.
(2)In order to be eligible for the exemption provided by this subdivision, the owner of the property shall do both of the following:
(A)(i)For any claim filed for the 200001 fiscal year or any fiscal year thereafter, certify and ensure, subject to the limitation in clause (ii), that there is an enforceable and verifiable agreement with a public agency, a recorded deed restriction, or other legal document that restricts the projects usage and that provides that the units designated for use by lower income households are continuously available to or occupied by lower income households, subject to the exception in clause (iii), at rents that do not exceed those prescribed by Section 50053 of the Health and Safety Code, or, to the extent that the terms of federal, state, or local financing or financial assistance conflicts with Section 50053, rents that do not exceed those prescribed by the terms of the financing or financial assistance.
(ii)In the case of a limited partnership in which the managing general partner is an eligible nonprofit corporation, the restriction and provision specified in clause (i) shall be contained in an enforceable and verifiable agreement with a public agency, or in a recorded deed restriction to which the limited partnership certifies.
(iii)(I)In the case of an owner of property that is eligible for and receives a low-income housing tax credit pursuant to Section 42 of the Internal Revenue Code, relating to low-income housing credit, a unit shall continue to be treated as occupied by a lower income household if the occupants were lower income households on the lien date in the fiscal year in which their occupancy of the unit commenced and the unit continues to be rent restricted, notwithstanding an increase in the income of the occupants of the unit to 140 percent of area median income, adjusted for family size. However, the unit shall cease to be treated as a lower income unit if the income of the occupants of the unit increases above 140 percent of area median income, adjusted for family size.
(II)This clause shall only be operative from the 201819 fiscal year through the 202728 fiscal year.
(B)Certify that the funds that would have been necessary to pay property taxes are used to maintain the affordability of, or reduce rents otherwise necessary for, the units occupied by lower income households.
(3)As used in this subdivision:
(A)Lower income households has the same meaning as the term lower income households as defined by Section 50079.5 of the Health and Safety Code.
(B)Related facilities means any managers units and any and all common area spaces that are included within the physical boundaries of the rental housing development, including, but not limited to, common area space, walkways, balconies, patios, clubhouse space, meeting rooms, laundry facilities, and parking areas, except any portions of the overall development that are nonexempt commercial space.
(C)(i)Units serving lower income households shall mean units that are occupied by lower income households at an affordable rent, as defined in Section 50053 of the Health and Safety Code or, to the extent that the terms of federal, state, or local financing or financial assistance conflicts with Section 50053, rents that do not exceed those prescribed by the terms of the financing or financial assistance. Units reserved for lower income households at an affordable rent that are temporarily vacant due to tenant turnover or repairs shall be counted as occupied.
(ii)(I)Units serving lower income households shall also mean units specified in clause (iii) of subparagraph (A) of paragraph (2).
(II)This clause shall only be operative from the 201819 fiscal year through the 202728 fiscal year.
(h)Property used exclusively for an emergency or temporary shelter and related facilities for homeless persons and families and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations meeting all of the requirements of this section shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section. Property that otherwise would be exempt pursuant to this subdivision, except that it includes housing and related facilities for other than an emergency or temporary shelter, shall be entitled to a partial exemption.
As used in this subdivision, emergency or temporary shelter means a facility that would be eligible for funding pursuant to Chapter 11 (commencing with Section 50800) of Part 2 of Division 31 of the Health and Safety Code.
(i)Property used exclusively for housing and related facilities for employees of religious, charitable, scientific, or hospital organizations that meet all the requirements of subdivision (a) and owned and operated by funds, foundations, limited liability companies, or corporations that meet all the requirements of subdivision (a) shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section to the extent the residential use of the property is institutionally necessary for the operation of the organization.
(j)For purposes of this section, charitable purposes include educational purposes. For purposes of this subdivision, educational purposes means those educational purposes and activities for the benefit of the community as a whole or an unascertainable and indefinite portion thereof, and do not include those educational purposes and activities that are primarily for the benefit of an organizations shareholders. Educational activities include the study of relevant information, the dissemination of that information to interested members of the general public, and the participation of interested members of the general public.
(k)In the case of property used exclusively for the exempt purposes specified in this section, owned and operated by limited liability companies that are organized and operated for those purposes, the State Board of Equalization shall adopt regulations to specify the ownership, organizational, and operational requirements for those companies to qualify for the exemption provided by this section.
(l)The amendments made by Chapter 354 of the Statutes of 2004 shall apply with respect to lien dates occurring on and after January 1, 2005.
(m)The amendments made by Chapter 836 of the Statutes of 2016 shall apply with respect to lien dates occurring on and after January 1, 2017.
(n)The amendments made by the act adding this subdivision shall apply with respect to lien dates occurring on and after January 1, 2019.
(o)Notwithstanding Section 20 or any other law, the State Board of Equalization is responsible for administering the welfare exemption provided by this section, except where the law places responsibility for administering that exemption with the county assessor.
SEC. 2.Section 214.19 is added to the Revenue and Taxation Code, to read:214.19.(a)For purposes of this section:
(1)Total exemption amount limitation means the assessed value exemption amount limitation with respect to a single property or multiple properties that is specified in subparagraph (C) of paragraph (1) of subdivision (g) of Section 214, as that section read before January 1, 2019.
(2)(A)Qualified property means property used exclusively for rental housing and related facilities where 90 percent or more of the occupants of the property are lower income households whose rent does not exceed the rent prescribed by Section 50053 of the Health and Safety Code and that qualifies for exemption under Section 214 on the sole basis of this criteria as specified in subparagraph (C) of paragraph (1) of subdivision (g) of Section 214.
(B)Qualified property does not include property owned by a limited partnership in which the managing general partner is an eligible nonprofit organization, as described in subparagraph (C) of paragraph (1) of subdivision (g) of Section 214.
(3)Qualified taxpayer means a taxpayer subject to the total exemption amount limitation.
(4)Qualified claim means a claim for exemption that was filed for a qualified property with the assessor on and after January 1, 2017, and before January 1, 2019, for which the assessor granted a partial exemption.
(5)Qualified ad valorem tax in excess of the total exemption amount limitation, and related interest or penalty means that ad valorem tax levied to a qualified taxpayer on qualified property with respect to a single property or multiple properties that does not exceed twenty million dollars ($20,000,000) in assessed value and any interest or penalty imposed with regard to that portion of assessed value that was in excess of the assessed value exemption amount limitation.
(b)(1)Any outstanding qualified ad valorem tax in excess of the total exemption amount limitation, and related interest or penalty, which was levied or imposed on and after January 1, 2017, and before January 1, 2019, with respect to a qualified property for which a qualified claim was filed, shall be canceled to the extent that the amount canceled does not result in a total assessed value exemption amount in excess of twenty million dollars ($20,000,000) being allowed to a qualified taxpayer with respect to a single property or multiple properties that are qualified property for any fiscal year.
(2)On or after January 1, 2019, an escape assessment shall not be levied on qualified property if that amount would be subject to cancellation under paragraph (1).
SEC. 3.The Legislature finds and declares that Section 2 of this act fulfills a statewide public purpose because it addresses Californias serious shortage of affordable, decent, safe, and sanitary housing for persons and families of low income by providing necessary property tax relief for certain tax-exempt organizations so that these tax-exempt organizations can provide affordable housing for persons and families of low income.
SEC. 4.If the Commission on State Mandates determines that this act contains costs mandated by the state, reimbursement to local agencies and school districts for those costs shall be made pursuant to Part 7 (commencing with Section 17500) of Division 4 of Title 2 of the Government Code.
SEC. 5.Notwithstanding Section 2229 of the Revenue and Taxation Code, no appropriation is made by this act and the state shall not reimburse any local agency for any property tax revenues lost by it pursuant to this act.
(a)Property used exclusively for religious, hospital, scientific, or charitable purposes owned and operated by community chests, funds, foundations, limited liability companies, or corporations organized and operated for religious, hospital, scientific, or charitable purposes is exempt from taxation, including ad valorem taxes to pay the interest and redemption charges on any indebtedness approved by the voters prior to July 1, 1978, or any bonded indebtedness for the acquisition or improvement of real property approved on or after July 1, 1978, by two-thirds of the votes cast by the voters voting on the proposition, if:
(1)The owner is not organized or operated for profit. However, in the case of hospitals, the organization shall not be deemed to be organized or operated for profit if, during the immediately preceding fiscal year, operating revenues, exclusive of gifts, endowments, and grants-in-aid, did not exceed operating expenses by an amount equivalent to 10 percent of those operating expenses. As used herein, operating expenses include depreciation based on cost of replacement and amortization of, and interest on, indebtedness.
(2)No part of the net earnings of the owner inures to the benefit of any private shareholder or individual.
(3)The property is used for the actual operation of the exempt activity, and does not exceed an amount of property reasonably necessary to the accomplishment of the exempt purpose.
(A)For the purposes of determining whether the property is used for the actual operation of the exempt activity, consideration shall not be given to use of the property for either or both of the following described activities if that use is occasional:
(i)The owner conducts fundraising activities on the property and the proceeds derived from those activities are not unrelated business taxable income, as defined in Section 512 of the Internal Revenue Code, of the owner and are used to further the exempt activity of the owner.
(ii)The owner permits any other organization that meets all of the requirements of this subdivision, other than ownership of the property, to conduct fundraising activities on the property and the proceeds derived from those activities are not unrelated business taxable income, as defined in Section 512 of the Internal Revenue Code, of the organization, are not subject to the tax on unrelated business taxable income that is imposed by Section 511 of the Internal Revenue Code, and are used to further the exempt activity of the organization.
(B)For purposes of subparagraph (A):
(i)Occasional use means use of the property on an irregular or intermittent basis by the qualifying owner or any other qualifying organization described in clause (ii) of subparagraph (A) that is incidental to the primary activities of the owner or the other organization.
(ii)Fundraising activities means both activities involving the direct solicitation of money or other property and the anticipated exchange of goods or services for money between the soliciting organization and the organization or person solicited.
(C)Subparagraph (A) shall have no application in determining whether paragraph (3) has been satisfied unless the owner of the property and any other organization using the property as provided in subparagraph (A) have filed with the assessor a valid organizational clearance certificate issued pursuant to Section 254.6.
(D)For the purposes of determining whether the property is used for the actual operation of the exempt activity, consideration shall not be given to the use of the property for meetings conducted by any other organization if the meetings are incidental to the other organizations primary activities, are not fundraising meetings or activities as defined in subparagraph (B), are held no more than once per week, and the other organization and its use of the property meet all other requirements of paragraphs (1) to (5), inclusive, of this subdivision. The owner or the other organization also shall file with the assessor a copy of a valid, unrevoked letter or ruling from the Internal Revenue Service or the Franchise Tax Board stating that the other organization, or the national organization of which it is a local chapter or affiliate, qualifies as an exempt organization under Section 501(c)(3) or 501(c)(4) of the Internal Revenue Code or Section 23701d, 23701f, or 23701w.
(E)Nothing in subparagraph (A), (B), (C), or (D) shall be construed to either enlarge or restrict the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(4)The property is not used or operated by the owner or by any other person so as to benefit any officer, trustee, director, shareholder, member, employee, contributor, or bondholder of the owner or operator, or any other person, through the distribution of profits, payment of excessive charges or compensations, or the more advantageous pursuit of their business or profession.
(5)The property is not used by the owner or members thereof for fraternal or lodge purposes, or for social club purposes except where that use is clearly incidental to a primary religious, hospital, scientific, or charitable purpose.
(6)The property is irrevocably dedicated to religious, charitable, scientific, or hospital purposes and upon the liquidation, dissolution, or abandonment of the owner will not inure to the benefit of any private person except a fund, foundation, or corporation organized and operated for religious, hospital, scientific, or charitable purposes.
(7)The property, if used exclusively for scientific purposes, is used by a foundation or institution that, in addition to complying with the foregoing requirements for the exemption of charitable organizations in general, has been chartered by the Congress of the United States (except that this requirement shall not apply when the scientific purposes are medical research), and whose objects are the encouragement or conduct of scientific investigation, research, and discovery for the benefit of the community at large.
The exemption provided for herein shall be known as the welfare exemption. This exemption shall be in addition to any other exemption now provided by law, and the existence of the exemption provision in paragraph (2) of subdivision (a) of Section 202 shall not preclude the exemption under this section for museum or library property. Except as provided in subdivision (e), this section shall not be construed to enlarge the college exemption.
(b)Property used exclusively for school purposes of less than collegiate grade and owned and operated by religious, hospital, or charitable funds, foundations, limited liability companies, or corporations, which property and funds, foundations, limited liability companies, or corporations meet all of the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(c)Property used exclusively for nursery school purposes and owned and operated by religious, hospital, or charitable funds, foundations, limited liability companies, or corporations, which property and funds, foundations, limited liability companies, or corporations meet all the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(d)Property used exclusively for a noncommercial educational FM broadcast station or an educational television station, and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations meeting all of the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(e)Property used exclusively for religious, charitable, scientific, or hospital purposes and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations or educational institutions of collegiate grade, as defined in Section 203, which property and funds, foundations, limited liability companies, corporations, or educational institutions meet all of the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section. As to educational institutions of collegiate grade, as defined in Section 203, the requirements of paragraph (6) of subdivision (a) shall be deemed to be met if both of the following are met:
(1)The property of the educational institution is irrevocably dedicated in its articles of incorporation to charitable and educational purposes, to religious and educational purposes, or to educational purposes.
(2)The articles of incorporation of the educational institution provide for distribution of its property upon its liquidation, dissolution, or abandonment to a fund, foundation, or corporation organized and operated for religious, hospital, scientific, charitable, or educational purposes meeting the requirements for exemption provided by Section 203 or this section.
(f)Property used exclusively for housing and related facilities for elderly or handicapped families and financed by, including, but not limited to, the federal government pursuant to Section 202 of Public Law 86-372 (12 U.S.C. Sec. 1701q), as amended, Section 231 of Public Law 73-479 (12 U.S.C. Sec. 1715v), Section 236 of Public Law 90-448 (12 U.S.C. Sec. 1715z), or Section 811 of Public Law 101-625 (42 U.S.C. Sec. 8013), and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations meeting all of the requirements of this section shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
The amendment of this paragraph made by Chapter 1102 of the Statutes of 1984 does not constitute a change in, but is declaratory of, existing law. However, no refund of property taxes shall be required as a result of this amendment for any fiscal year prior to the fiscal year in which the amendment takes effect.
Property used exclusively for housing and related facilities for elderly or handicapped families at which supplemental care or services designed to meet the special needs of elderly or handicapped residents are not provided, or that is not financed by the federal government pursuant to Section 202 of Public Law 86-372 (12 U.S.C. Sec. 1701q), as amended, Section 231 of Public Law 73-479 (12 U.S.C. Sec. 1715v), Section 236 of Public Law 90-448 (12 U.S.C. Sec. 1715z), or Section 811 of Public Law 101-625 (42 U.S.C. Sec. 8013), shall not be entitled to exemption pursuant to this subdivision unless the property is used for housing and related facilities for low- and moderate-income elderly or handicapped families. Property that would otherwise be exempt pursuant to this subdivision, except that it includes some housing and related facilities for other than low- or moderate-income elderly or handicapped families, shall be entitled to a partial exemption. The partial exemption shall be equal to that percentage of the value of the property that is equal to the percentage that the number of low- and moderate-income elderly and handicapped families represents of the total number of families occupying the property.
As used in this subdivision, low and moderate income has the same meaning as the term persons and families of low or moderate income as defined by Section 50093 of the Health and Safety Code.
(g)(1)Property used exclusively for rental housing and related facilities and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations, including limited partnerships in which the managing general partner is an eligible nonprofit corporation or eligible limited liability company, meeting all of the requirements of this section, or by veterans organizations, as described in Section 215.1, meeting all the requirements of paragraphs (1) to (7), inclusive, of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section and shall be entitled to a partial exemption equal to that percentage of the value of the property that is equal to the percentage that the number of units serving lower income households represents of the total number of residential units in any year in which any of the following criteria applies:
(A)The acquisition, rehabilitation, development, or operation of the property, or any combination of these factors, is financed with tax-exempt mortgage revenue bonds or general obligation bonds, or is financed by local, state, or federal loans or grants and the rents of the occupants who are lower income households do not exceed those prescribed by deed restrictions or regulatory agreements pursuant to the terms of the financing or financial assistance.
(B)The owner of the property is eligible for and receives low-income housing tax credits pursuant to Section 42 of the Internal Revenue Code of 1986, as added by Public Law 99-514.
(C)In the case of a claim, other than a claim with respect to property owned by a limited partnership in which the managing general partner is an eligible nonprofit corporation, that is filed for the 200001 fiscal year or any fiscal year thereafter, 90 percent or more of the occupants of the property are lower income households whose rent does not exceed the rent prescribed by Section 50053 of the Health and Safety Code. The total exemption amount allowed under this subdivision to a taxpayer, with respect to a single property or multiple properties for any fiscal year on the sole basis of the application of this subparagraph, may not exceed twenty million dollars ($20,000,000) in assessed value.
(D)(i)The property was previously purchased and owned by the Department of Transportation pursuant to a consent decree requiring housing mitigation measures relating to the construction of a freeway and is now solely owned by an organization that qualifies as an exempt organization under Section 501(c)(3) of the Internal Revenue Code.
(ii)This subparagraph shall not apply to property owned by a limited partnership in which the managing partner is an eligible nonprofit corporation.
(2)In order to be eligible for the exemption provided by this subdivision, the owner of the property shall do both of the following:
(A)(i)For any claim filed for the 200001 fiscal year or any fiscal year thereafter, certify and ensure, subject to the limitation in clause (ii), that there is an enforceable and verifiable agreement with a public agency, a recorded deed restriction, or other legal document that restricts the projects usage and that provides that the units designated for use by lower income households are continuously available to or occupied by lower income households, subject to the exception in clause (iii), at rents that do not exceed those prescribed by Section 50053 of the Health and Safety Code, or, to the extent that the terms of federal, state, or local financing or financial assistance conflicts with Section 50053, rents that do not exceed those prescribed by the terms of the financing or financial assistance.
(ii)In the case of a limited partnership in which the managing general partner is an eligible nonprofit corporation, the restriction and provision specified in clause (i) shall be contained in an enforceable and verifiable agreement with a public agency, or in a recorded deed restriction to which the limited partnership certifies.
(iii)(I)In the case of an owner of property that is eligible for and receives a low-income housing tax credit pursuant to Section 42 of the Internal Revenue Code, relating to low-income housing credit, a unit shall continue to be treated as occupied by a lower income household if the occupants were lower income households on the lien date in the fiscal year in which their occupancy of the unit commenced and the unit continues to be rent restricted, notwithstanding an increase in the income of the occupants of the unit to 140 percent of area median income, adjusted for family size. However, the unit shall cease to be treated as a lower income unit if the income of the occupants of the unit increases above 140 percent of area median income, adjusted for family size.
(II)This clause shall only be operative from the 201819 fiscal year through the 202728 fiscal year.
(B)Certify that the funds that would have been necessary to pay property taxes are used to maintain the affordability of, or reduce rents otherwise necessary for, the units occupied by lower income households.
(3)As used in this subdivision:
(A)Lower income households has the same meaning as the term lower income households as defined by Section 50079.5 of the Health and Safety Code.
(B)Related facilities means any managers units and any and all common area spaces that are included within the physical boundaries of the rental housing development, including, but not limited to, common area space, walkways, balconies, patios, clubhouse space, meeting rooms, laundry facilities, and parking areas, except any portions of the overall development that are nonexempt commercial space.
(C)(i)Units serving lower income households shall mean units that are occupied by lower income households at an affordable rent, as defined in Section 50053 of the Health and Safety Code or, to the extent that the terms of federal, state, or local financing or financial assistance conflicts with Section 50053, rents that do not exceed those prescribed by the terms of the financing or financial assistance. Units reserved for lower income households at an affordable rent that are temporarily vacant due to tenant turnover or repairs shall be counted as occupied.
(ii)(I)Units serving lower income households shall also mean units specified in clause (iii) of subparagraph (A) of paragraph (2).
(II)This clause shall only be operative from the 201819 fiscal year through the 202728 fiscal year.
(h)Property used exclusively for an emergency or temporary shelter and related facilities for homeless persons and families and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations meeting all of the requirements of this section shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section. Property that otherwise would be exempt pursuant to this subdivision, except that it includes housing and related facilities for other than an emergency or temporary shelter, shall be entitled to a partial exemption.
As used in this subdivision, emergency or temporary shelter means a facility that would be eligible for funding pursuant to Chapter 11 (commencing with Section 50800) of Part 2 of Division 31 of the Health and Safety Code.
(i)Property used exclusively for housing and related facilities for employees of religious, charitable, scientific, or hospital organizations that meet all the requirements of subdivision (a) and owned and operated by funds, foundations, limited liability companies, or corporations that meet all the requirements of subdivision (a) shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section to the extent the residential use of the property is institutionally necessary for the operation of the organization.
(j)For purposes of this section, charitable purposes include educational purposes. For purposes of this subdivision, educational purposes means those educational purposes and activities for the benefit of the community as a whole or an unascertainable and indefinite portion thereof, and do not include those educational purposes and activities that are primarily for the benefit of an organizations shareholders. Educational activities include the study of relevant information, the dissemination of that information to interested members of the general public, and the participation of interested members of the general public.
(k)In the case of property used exclusively for the exempt purposes specified in this section, owned and operated by limited liability companies that are organized and operated for those purposes, the State Board of Equalization shall adopt regulations to specify the ownership, organizational, and operational requirements for those companies to qualify for the exemption provided by this section.
(l)The amendments made by Chapter 354 of the Statutes of 2004 shall apply with respect to lien dates occurring on and after January 1, 2005.
(m)The amendments made by Chapter 836 of the Statutes of 2016 shall apply with respect to lien dates occurring on and after January 1, 2017.
(n)The amendments made by the act adding this subdivision shall apply with respect to lien dates occurring on and after January 1, 2019.
(o)Notwithstanding Section 20 or any other law, the State Board of Equalization is responsible for administering the welfare exemption provided by this section, except where the law places responsibility for administering that exemption with the county assessor.
SEC. 2.Section 214.19 is added to the Revenue and Taxation Code, to read:214.19.(a)For purposes of this section:
(1)Total exemption amount limitation means the assessed value exemption amount limitation with respect to a single property or multiple properties that is specified in subparagraph (C) of paragraph (1) of subdivision (g) of Section 214, as that section read before January 1, 2019.
(2)(A)Qualified property means property used exclusively for rental housing and related facilities where 90 percent or more of the occupants of the property are lower income households whose rent does not exceed the rent prescribed by Section 50053 of the Health and Safety Code and that qualifies for exemption under Section 214 on the sole basis of this criteria as specified in subparagraph (C) of paragraph (1) of subdivision (g) of Section 214.
(B)Qualified property does not include property owned by a limited partnership in which the managing general partner is an eligible nonprofit organization, as described in subparagraph (C) of paragraph (1) of subdivision (g) of Section 214.
(3)Qualified taxpayer means a taxpayer subject to the total exemption amount limitation.
(4)Qualified claim means a claim for exemption that was filed for a qualified property with the assessor on and after January 1, 2017, and before January 1, 2019, for which the assessor granted a partial exemption.
(5)Qualified ad valorem tax in excess of the total exemption amount limitation, and related interest or penalty means that ad valorem tax levied to a qualified taxpayer on qualified property with respect to a single property or multiple properties that does not exceed twenty million dollars ($20,000,000) in assessed value and any interest or penalty imposed with regard to that portion of assessed value that was in excess of the assessed value exemption amount limitation.
(b)(1)Any outstanding qualified ad valorem tax in excess of the total exemption amount limitation, and related interest or penalty, which was levied or imposed on and after January 1, 2017, and before January 1, 2019, with respect to a qualified property for which a qualified claim was filed, shall be canceled to the extent that the amount canceled does not result in a total assessed value exemption amount in excess of twenty million dollars ($20,000,000) being allowed to a qualified taxpayer with respect to a single property or multiple properties that are qualified property for any fiscal year.
(2)On or after January 1, 2019, an escape assessment shall not be levied on qualified property if that amount would be subject to cancellation under paragraph (1).
SEC. 3.The Legislature finds and declares that Section 2 of this act fulfills a statewide public purpose because it addresses Californias serious shortage of affordable, decent, safe, and sanitary housing for persons and families of low income by providing necessary property tax relief for certain tax-exempt organizations so that these tax-exempt organizations can provide affordable housing for persons and families of low income.
SEC. 4.If the Commission on State Mandates determines that this act contains costs mandated by the state, reimbursement to local agencies and school districts for those costs shall be made pursuant to Part 7 (commencing with Section 17500) of Division 4 of Title 2 of the Government Code.
SEC. 5.Notwithstanding Section 2229 of the Revenue and Taxation Code, no appropriation is made by this act and the state shall not reimburse any local agency for any property tax revenues lost by it pursuant to this act.
(a)Property used exclusively for religious, hospital, scientific, or charitable purposes owned and operated by community chests, funds, foundations, limited liability companies, or corporations organized and operated for religious, hospital, scientific, or charitable purposes is exempt from taxation, including ad valorem taxes to pay the interest and redemption charges on any indebtedness approved by the voters prior to July 1, 1978, or any bonded indebtedness for the acquisition or improvement of real property approved on or after July 1, 1978, by two-thirds of the votes cast by the voters voting on the proposition, if:
(1)The owner is not organized or operated for profit. However, in the case of hospitals, the organization shall not be deemed to be organized or operated for profit if, during the immediately preceding fiscal year, operating revenues, exclusive of gifts, endowments, and grants-in-aid, did not exceed operating expenses by an amount equivalent to 10 percent of those operating expenses. As used herein, operating expenses include depreciation based on cost of replacement and amortization of, and interest on, indebtedness.
(2)No part of the net earnings of the owner inures to the benefit of any private shareholder or individual.
(3)The property is used for the actual operation of the exempt activity, and does not exceed an amount of property reasonably necessary to the accomplishment of the exempt purpose.
(A)For the purposes of determining whether the property is used for the actual operation of the exempt activity, consideration shall not be given to use of the property for either or both of the following described activities if that use is occasional:
(i)The owner conducts fundraising activities on the property and the proceeds derived from those activities are not unrelated business taxable income, as defined in Section 512 of the Internal Revenue Code, of the owner and are used to further the exempt activity of the owner.
(ii)The owner permits any other organization that meets all of the requirements of this subdivision, other than ownership of the property, to conduct fundraising activities on the property and the proceeds derived from those activities are not unrelated business taxable income, as defined in Section 512 of the Internal Revenue Code, of the organization, are not subject to the tax on unrelated business taxable income that is imposed by Section 511 of the Internal Revenue Code, and are used to further the exempt activity of the organization.
(B)For purposes of subparagraph (A):
(i)Occasional use means use of the property on an irregular or intermittent basis by the qualifying owner or any other qualifying organization described in clause (ii) of subparagraph (A) that is incidental to the primary activities of the owner or the other organization.
(ii)Fundraising activities means both activities involving the direct solicitation of money or other property and the anticipated exchange of goods or services for money between the soliciting organization and the organization or person solicited.
(C)Subparagraph (A) shall have no application in determining whether paragraph (3) has been satisfied unless the owner of the property and any other organization using the property as provided in subparagraph (A) have filed with the assessor a valid organizational clearance certificate issued pursuant to Section 254.6.
(D)For the purposes of determining whether the property is used for the actual operation of the exempt activity, consideration shall not be given to the use of the property for meetings conducted by any other organization if the meetings are incidental to the other organizations primary activities, are not fundraising meetings or activities as defined in subparagraph (B), are held no more than once per week, and the other organization and its use of the property meet all other requirements of paragraphs (1) to (5), inclusive, of this subdivision. The owner or the other organization also shall file with the assessor a copy of a valid, unrevoked letter or ruling from the Internal Revenue Service or the Franchise Tax Board stating that the other organization, or the national organization of which it is a local chapter or affiliate, qualifies as an exempt organization under Section 501(c)(3) or 501(c)(4) of the Internal Revenue Code or Section 23701d, 23701f, or 23701w.
(E)Nothing in subparagraph (A), (B), (C), or (D) shall be construed to either enlarge or restrict the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(4)The property is not used or operated by the owner or by any other person so as to benefit any officer, trustee, director, shareholder, member, employee, contributor, or bondholder of the owner or operator, or any other person, through the distribution of profits, payment of excessive charges or compensations, or the more advantageous pursuit of their business or profession.
(5)The property is not used by the owner or members thereof for fraternal or lodge purposes, or for social club purposes except where that use is clearly incidental to a primary religious, hospital, scientific, or charitable purpose.
(6)The property is irrevocably dedicated to religious, charitable, scientific, or hospital purposes and upon the liquidation, dissolution, or abandonment of the owner will not inure to the benefit of any private person except a fund, foundation, or corporation organized and operated for religious, hospital, scientific, or charitable purposes.
(7)The property, if used exclusively for scientific purposes, is used by a foundation or institution that, in addition to complying with the foregoing requirements for the exemption of charitable organizations in general, has been chartered by the Congress of the United States (except that this requirement shall not apply when the scientific purposes are medical research), and whose objects are the encouragement or conduct of scientific investigation, research, and discovery for the benefit of the community at large.
The exemption provided for herein shall be known as the welfare exemption. This exemption shall be in addition to any other exemption now provided by law, and the existence of the exemption provision in paragraph (2) of subdivision (a) of Section 202 shall not preclude the exemption under this section for museum or library property. Except as provided in subdivision (e), this section shall not be construed to enlarge the college exemption.
(b)Property used exclusively for school purposes of less than collegiate grade and owned and operated by religious, hospital, or charitable funds, foundations, limited liability companies, or corporations, which property and funds, foundations, limited liability companies, or corporations meet all of the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(c)Property used exclusively for nursery school purposes and owned and operated by religious, hospital, or charitable funds, foundations, limited liability companies, or corporations, which property and funds, foundations, limited liability companies, or corporations meet all the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(d)Property used exclusively for a noncommercial educational FM broadcast station or an educational television station, and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations meeting all of the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(e)Property used exclusively for religious, charitable, scientific, or hospital purposes and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations or educational institutions of collegiate grade, as defined in Section 203, which property and funds, foundations, limited liability companies, corporations, or educational institutions meet all of the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section. As to educational institutions of collegiate grade, as defined in Section 203, the requirements of paragraph (6) of subdivision (a) shall be deemed to be met if both of the following are met:
(1)The property of the educational institution is irrevocably dedicated in its articles of incorporation to charitable and educational purposes, to religious and educational purposes, or to educational purposes.
(2)The articles of incorporation of the educational institution provide for distribution of its property upon its liquidation, dissolution, or abandonment to a fund, foundation, or corporation organized and operated for religious, hospital, scientific, charitable, or educational purposes meeting the requirements for exemption provided by Section 203 or this section.
(f)Property used exclusively for housing and related facilities for elderly or handicapped families and financed by, including, but not limited to, the federal government pursuant to Section 202 of Public Law 86-372 (12 U.S.C. Sec. 1701q), as amended, Section 231 of Public Law 73-479 (12 U.S.C. Sec. 1715v), Section 236 of Public Law 90-448 (12 U.S.C. Sec. 1715z), or Section 811 of Public Law 101-625 (42 U.S.C. Sec. 8013), and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations meeting all of the requirements of this section shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
The amendment of this paragraph made by Chapter 1102 of the Statutes of 1984 does not constitute a change in, but is declaratory of, existing law. However, no refund of property taxes shall be required as a result of this amendment for any fiscal year prior to the fiscal year in which the amendment takes effect.
Property used exclusively for housing and related facilities for elderly or handicapped families at which supplemental care or services designed to meet the special needs of elderly or handicapped residents are not provided, or that is not financed by the federal government pursuant to Section 202 of Public Law 86-372 (12 U.S.C. Sec. 1701q), as amended, Section 231 of Public Law 73-479 (12 U.S.C. Sec. 1715v), Section 236 of Public Law 90-448 (12 U.S.C. Sec. 1715z), or Section 811 of Public Law 101-625 (42 U.S.C. Sec. 8013), shall not be entitled to exemption pursuant to this subdivision unless the property is used for housing and related facilities for low- and moderate-income elderly or handicapped families. Property that would otherwise be exempt pursuant to this subdivision, except that it includes some housing and related facilities for other than low- or moderate-income elderly or handicapped families, shall be entitled to a partial exemption. The partial exemption shall be equal to that percentage of the value of the property that is equal to the percentage that the number of low- and moderate-income elderly and handicapped families represents of the total number of families occupying the property.
As used in this subdivision, low and moderate income has the same meaning as the term persons and families of low or moderate income as defined by Section 50093 of the Health and Safety Code.
(g)(1)Property used exclusively for rental housing and related facilities and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations, including limited partnerships in which the managing general partner is an eligible nonprofit corporation or eligible limited liability company, meeting all of the requirements of this section, or by veterans organizations, as described in Section 215.1, meeting all the requirements of paragraphs (1) to (7), inclusive, of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section and shall be entitled to a partial exemption equal to that percentage of the value of the property that is equal to the percentage that the number of units serving lower income households represents of the total number of residential units in any year in which any of the following criteria applies:
(A)The acquisition, rehabilitation, development, or operation of the property, or any combination of these factors, is financed with tax-exempt mortgage revenue bonds or general obligation bonds, or is financed by local, state, or federal loans or grants and the rents of the occupants who are lower income households do not exceed those prescribed by deed restrictions or regulatory agreements pursuant to the terms of the financing or financial assistance.
(B)The owner of the property is eligible for and receives low-income housing tax credits pursuant to Section 42 of the Internal Revenue Code of 1986, as added by Public Law 99-514.
(C)In the case of a claim, other than a claim with respect to property owned by a limited partnership in which the managing general partner is an eligible nonprofit corporation, that is filed for the 200001 fiscal year or any fiscal year thereafter, 90 percent or more of the occupants of the property are lower income households whose rent does not exceed the rent prescribed by Section 50053 of the Health and Safety Code. The total exemption amount allowed under this subdivision to a taxpayer, with respect to a single property or multiple properties for any fiscal year on the sole basis of the application of this subparagraph, may not exceed ten twenty million dollars ($10,000,000) ($20,000,000) in assessed value.
(D)(i)The property was previously purchased and owned by the Department of Transportation pursuant to a consent decree requiring housing mitigation measures relating to the construction of a freeway and is now solely owned by an organization that qualifies as an exempt organization under Section 501(c)(3) of the Internal Revenue Code.
(ii)This subparagraph shall not apply to property owned by a limited partnership in which the managing partner is an eligible nonprofit corporation.
(2)In order to be eligible for the exemption provided by this subdivision, the owner of the property shall do both of the following:
(A)(i)For any claim filed for the 200001 fiscal year or any fiscal year thereafter, certify and ensure, subject to the limitation in clause (ii), that there is an enforceable and verifiable agreement with a public agency, a recorded deed restriction, or other legal document that restricts the projects usage and that provides that the units designated for use by lower income households are continuously available to or occupied by lower income households, subject to the exception in clause (iii), at rents that do not exceed those prescribed by Section 50053 of the Health and Safety Code, or, to the extent that the terms of federal, state, or local financing or financial assistance conflicts with Section 50053, rents that do not exceed those prescribed by the terms of the financing or financial assistance.
(ii)In the case of a limited partnership in which the managing general partner is an eligible nonprofit corporation, the restriction and provision specified in clause (i) shall be contained in an enforceable and verifiable agreement with a public agency, or in a recorded deed restriction to which the limited partnership certifies.
(iii)(I)In the case of an owner of property that is eligible for and receives a low-income housing tax credit pursuant to Section 42 of the Internal Revenue Code, relating to low-income housing credit, a unit shall continue to be treated as occupied by a lower income household if the occupants were lower income households on the lien date in the fiscal year in which their occupancy of the unit commenced and the unit continues to be rent restricted, notwithstanding an increase in the income of the occupants of the unit to 140 percent of area median income, adjusted for family size. However, the unit shall cease to be treated as a lower income unit if the income of the occupants of the unit increases above 140 percent of area median income, adjusted for family size.
(II)This clause shall only be operative from the 201819 fiscal year through the 202728 fiscal year.
(B)Certify that the funds that would have been necessary to pay property taxes are used to maintain the affordability of, or reduce rents otherwise necessary for, the units occupied by lower income households.
(3)As used in this subdivision:
(A)Lower income households has the same meaning as the term lower income households as defined by Section 50079.5 of the Health and Safety Code.
(B)Related facilities means any managers units and any and all common area spaces that are included within the physical boundaries of the rental housing development, including, but not limited to, common area space, walkways, balconies, patios, clubhouse space, meeting rooms, laundry facilities, and parking areas, except any portions of the overall development that are nonexempt commercial space.
(C)(i)Units serving lower income households shall mean units that are occupied by lower income households at an affordable rent, as defined in Section 50053 of the Health and Safety Code or, to the extent that the terms of federal, state, or local financing or financial assistance conflicts with Section 50053, rents that do not exceed those prescribed by the terms of the financing or financial assistance. Units reserved for lower income households at an affordable rent that are temporarily vacant due to tenant turnover or repairs shall be counted as occupied.
(ii)(I)Units serving lower income households shall also mean units specified in clause (iii) of subparagraph (A) of paragraph (2).
(II)This clause shall only be operative from the 201819 fiscal year through the 202728 fiscal year.
(h)Property used exclusively for an emergency or temporary shelter and related facilities for homeless persons and families and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations meeting all of the requirements of this section shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section. Property that otherwise would be exempt pursuant to this subdivision, except that it includes housing and related facilities for other than an emergency or temporary shelter, shall be entitled to a partial exemption.
As used in this subdivision, emergency or temporary shelter means a facility that would be eligible for funding pursuant to Chapter 11 (commencing with Section 50800) of Part 2 of Division 31 of the Health and Safety Code.
(i)Property used exclusively for housing and related facilities for employees of religious, charitable, scientific, or hospital organizations that meet all the requirements of subdivision (a) and owned and operated by funds, foundations, limited liability companies, or corporations that meet all the requirements of subdivision (a) shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section to the extent the residential use of the property is institutionally necessary for the operation of the organization.
(j)For purposes of this section, charitable purposes include educational purposes. For purposes of this subdivision, educational purposes means those educational purposes and activities for the benefit of the community as a whole or an unascertainable and indefinite portion thereof, and do not include those educational purposes and activities that are primarily for the benefit of an organizations shareholders. Educational activities include the study of relevant information, the dissemination of that information to interested members of the general public, and the participation of interested members of the general public.
(k)In the case of property used exclusively for the exempt purposes specified in this section, owned and operated by limited liability companies that are organized and operated for those purposes, the State Board of Equalization shall adopt regulations to specify the ownership, organizational, and operational requirements for those companies to qualify for the exemption provided by this section.
(l)The amendments made by Chapter 354 of the Statutes of 2004 shall apply with respect to lien dates occurring on and after January 1, 2005.
(m)The amendments made by the act adding this subdivision Chapter 836 of the Statutes of 2016 shall apply with respect to lien dates occurring on and after January 1, 2017.
(n)The amendments made by the act adding this subdivision shall apply with respect to lien dates occurring on and after January 1, 2019.
(n)(o)Notwithstanding Section 20 or any other law, the State Board of Equalization is responsible for administering the welfare exemption provided by this section, except where the law places responsibility for administering that exemption with the county assessor.
SEC. 2.Section 214.18 is added to the Revenue and Taxation Code, to read:214.18.SEC. 2.Section 214.19 is added to the Revenue and Taxation Code, to read:214.19.(a)For purposes of this section:
(1)Total exemption amount limitation means the assessed value exemption amount limitation with respect to a single property or multiple properties that is specified in subparagraph (C) of paragraph (1) of subdivision (g) of Section 214, as that section read before January 1, 2019.
(2)(A)Qualified property means property used exclusively for rental housing and related facilities where 90 percent or more of the occupants of the property are lower income households whose rent does not exceed the rent prescribed by Section 50053 of the Health and Safety Code and that qualifies for exemption under Section 214 on the sole basis of this criteria as specified in subparagraph (C) of paragraph (1) of subdivision (g) of Section 214.
(B)Qualified property does not include property owned by a limited partnership in which the managing general partner is an eligible nonprofit organization, as described in subparagraph (C) of paragraph (1) of subdivision (g) of Section 214.
(3)Qualified taxpayer means a taxpayer subject to the total exemption amount limitation.
(4)Qualified claim means a claim for exemption that was filed for a qualified property with the assessor on and after January 1, 2017, and before January 1, 2019, for which the assessor granted a partial exemption.
(5)Qualified ad valorem tax in excess of the total exemption amount limitation, and related interest or penalty means that portion of ad valorem tax levied to a qualified taxpayer on qualified property with respect to a single property or multiple properties, properties that does not exceed twenty million dollars ($20,000,000) in assessed value and any interest or penalty imposed with regard to that portion of tax. assessed value that was in excess of the assessed value exemption amount limitation.
(b)(1)Any outstanding qualified ad valorem tax in excess of the total exemption amount limitation, and related interest or penalty, which was levied or imposed on and after January 1, 2017, and before January 1, 2019, with respect to a qualified property for which a qualified claim was filed, shall be canceled. canceled to the extent that the amount canceled does not result in a total assessed value exemption amount in excess of twenty million dollars ($20,000,000) being allowed to a qualified taxpayer with respect to a single property or multiple properties that are qualified property for any fiscal year.
(2)On or after January 1, 2019, an escape assessment shall not be levied on qualified property if that amount would be subject to cancellation under paragraph (1).
SEC. 3.The Legislature finds and declares that Section 2 of this act fulfills a statewide public purpose because it addresses Californias serious shortage of affordable, decent, safe, and sanitary housing for persons and families of low income by providing necessary property tax relief for certain tax-exempt organizations so that these tax-exempt organizations can provide affordable housing for persons and families of low income.
SEC. 4.If the Commission on State Mandates determines that this act contains costs mandated by the state, reimbursement to local agencies and school districts for those costs shall be made pursuant to Part 7 (commencing with Section 17500) of Division 4 of Title 2 of the Government Code.
SEC. 5.Notwithstanding Section 2229 of the Revenue and Taxation Code, no appropriation is made by this act and the state shall not reimburse any local agency for any property tax revenues lost by it pursuant to this act.
(a)Property used exclusively for religious, hospital, scientific, or charitable purposes owned and operated by community chests, funds, foundations, limited liability companies, or corporations organized and operated for religious, hospital, scientific, or charitable purposes is exempt from taxation, including ad valorem taxes to pay the interest and redemption charges on any indebtedness approved by the voters prior to July 1, 1978, or any bonded indebtedness for the acquisition or improvement of real property approved on or after July 1, 1978, by two-thirds of the votes cast by the voters voting on the proposition, if:
(1)The owner is not organized or operated for profit. However, in the case of hospitals, the organization shall not be deemed to be organized or operated for profit if, during the immediately preceding fiscal year, operating revenues, exclusive of gifts, endowments, and grants-in-aid, did not exceed operating expenses by an amount equivalent to 10 percent of those operating expenses. As used herein, operating expenses include depreciation based on cost of replacement and amortization of, and interest on, indebtedness.
(2)No part of the net earnings of the owner inures to the benefit of any private shareholder or individual.
(3)The property is used for the actual operation of the exempt activity, and does not exceed an amount of property reasonably necessary to the accomplishment of the exempt purpose.
(A)For the purposes of determining whether the property is used for the actual operation of the exempt activity, consideration shall not be given to use of the property for either or both of the following described activities if that use is occasional:
(i)The owner conducts fundraising activities on the property and the proceeds derived from those activities are not unrelated business taxable income, as defined in Section 512 of the Internal Revenue Code, of the owner and are used to further the exempt activity of the owner.
(ii)The owner permits any other organization that meets all of the requirements of this subdivision, other than ownership of the property, to conduct fundraising activities on the property and the proceeds derived from those activities are not unrelated business taxable income, as defined in Section 512 of the Internal Revenue Code, of the organization, are not subject to the tax on unrelated business taxable income that is imposed by Section 511 of the Internal Revenue Code, and are used to further the exempt activity of the organization.
(B)For purposes of subparagraph (A):
(i)Occasional use means use of the property on an irregular or intermittent basis by the qualifying owner or any other qualifying organization described in clause (ii) of subparagraph (A) that is incidental to the primary activities of the owner or the other organization.
(ii)Fundraising activities means both activities involving the direct solicitation of money or other property and the anticipated exchange of goods or services for money between the soliciting organization and the organization or person solicited.
(C)Subparagraph (A) shall have no application in determining whether paragraph (3) has been satisfied unless the owner of the property and any other organization using the property as provided in subparagraph (A) have filed with the assessor a valid organizational clearance certificate issued pursuant to Section 254.6.
(D)For the purposes of determining whether the property is used for the actual operation of the exempt activity, consideration shall not be given to the use of the property for meetings conducted by any other organization if the meetings are incidental to the other organizations primary activities, are not fundraising meetings or activities as defined in subparagraph (B), are held no more than once per week, and the other organization and its use of the property meet all other requirements of paragraphs (1) to (5), inclusive, of this subdivision. The owner or the other organization also shall file with the assessor a copy of a valid, unrevoked letter or ruling from the Internal Revenue Service or the Franchise Tax Board stating that the other organization, or the national organization of which it is a local chapter or affiliate, qualifies as an exempt organization under Section 501(c)(3) or 501(c)(4) of the Internal Revenue Code or Section 23701d, 23701f, or 23701w.
(E)Nothing in subparagraph (A), (B), (C), or (D) shall be construed to either enlarge or restrict the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(4)The property is not used or operated by the owner or by any other person so as to benefit any officer, trustee, director, shareholder, member, employee, contributor, or bondholder of the owner or operator, or any other person, through the distribution of profits, payment of excessive charges or compensations, or the more advantageous pursuit of their business or profession.
(5)The property is not used by the owner or members thereof for fraternal or lodge purposes, or for social club purposes except where that use is clearly incidental to a primary religious, hospital, scientific, or charitable purpose.
(6)The property is irrevocably dedicated to religious, charitable, scientific, or hospital purposes and upon the liquidation, dissolution, or abandonment of the owner will not inure to the benefit of any private person except a fund, foundation, or corporation organized and operated for religious, hospital, scientific, or charitable purposes.
(7)The property, if used exclusively for scientific purposes, is used by a foundation or institution that, in addition to complying with the foregoing requirements for the exemption of charitable organizations in general, has been chartered by the Congress of the United States (except that this requirement shall not apply when the scientific purposes are medical research), and whose objects are the encouragement or conduct of scientific investigation, research, and discovery for the benefit of the community at large.
The exemption provided for herein shall be known as the welfare exemption. This exemption shall be in addition to any other exemption now provided by law, and the existence of the exemption provision in paragraph (2) of subdivision (a) of Section 202 shall not preclude the exemption under this section for museum or library property. Except as provided in subdivision (e), this section shall not be construed to enlarge the college exemption.
(b)Property used exclusively for school purposes of less than collegiate grade and owned and operated by religious, hospital, or charitable funds, foundations, limited liability companies, or corporations, which property and funds, foundations, limited liability companies, or corporations meet all of the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(c)Property used exclusively for nursery school purposes and owned and operated by religious, hospital, or charitable funds, foundations, limited liability companies, or corporations, which property and funds, foundations, limited liability companies, or corporations meet all the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(d)Property used exclusively for a noncommercial educational FM broadcast station or an educational television station, and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations meeting all of the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(e)Property used exclusively for religious, charitable, scientific, or hospital purposes and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations or educational institutions of collegiate grade, as defined in Section 203, which property and funds, foundations, limited liability companies, corporations, or educational institutions meet all of the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section. As to educational institutions of collegiate grade, as defined in Section 203, the requirements of paragraph (6) of subdivision (a) shall be deemed to be met if both of the following are met:
(1)The property of the educational institution is irrevocably dedicated in its articles of incorporation to charitable and educational purposes, to religious and educational purposes, or to educational purposes.
(2)The articles of incorporation of the educational institution provide for distribution of its property upon its liquidation, dissolution, or abandonment to a fund, foundation, or corporation organized and operated for religious, hospital, scientific, charitable, or educational purposes meeting the requirements for exemption provided by Section 203 or this section.
(f)Property used exclusively for housing and related facilities for elderly or handicapped families and financed by, including, but not limited to, the federal government pursuant to Section 202 of Public Law 86-372 (12 U.S.C. Sec. 1701q), as amended, Section 231 of Public Law 73-479 (12 U.S.C. Sec. 1715v), Section 236 of Public Law 90-448 (12 U.S.C. Sec. 1715z), or Section 811 of Public Law 101-625 (42 U.S.C. Sec. 8013), and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations meeting all of the requirements of this section shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
The amendment of this paragraph made by Chapter 1102 of the Statutes of 1984 does not constitute a change in, but is declaratory of, existing law. However, no refund of property taxes shall be required as a result of this amendment for any fiscal year prior to the fiscal year in which the amendment takes effect.
Property used exclusively for housing and related facilities for elderly or handicapped families at which supplemental care or services designed to meet the special needs of elderly or handicapped residents are not provided, or that is not financed by the federal government pursuant to Section 202 of Public Law 86-372 (12 U.S.C. Sec. 1701q), as amended, Section 231 of Public Law 73-479 (12 U.S.C. Sec. 1715v), Section 236 of Public Law 90-448 (12 U.S.C. Sec. 1715z), or Section 811 of Public Law 101-625 (42 U.S.C. Sec. 8013), shall not be entitled to exemption pursuant to this subdivision unless the property is used for housing and related facilities for low- and moderate-income elderly or handicapped families. Property that would otherwise be exempt pursuant to this subdivision, except that it includes some housing and related facilities for other than low- or moderate-income elderly or handicapped families, shall be entitled to a partial exemption. The partial exemption shall be equal to that percentage of the value of the property that is equal to the percentage that the number of low- and moderate-income elderly and handicapped families represents of the total number of families occupying the property.
As used in this subdivision, low and moderate income has the same meaning as the term persons and families of low or moderate income as defined by Section 50093 of the Health and Safety Code.
(g)(1)Property used exclusively for rental housing and related facilities and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations, including limited partnerships in which the managing general partner is an eligible nonprofit corporation or eligible limited liability company, meeting all of the requirements of this section, or by veterans organizations, as described in Section 215.1, meeting all the requirements of paragraphs (1) to (7), inclusive, of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section and shall be entitled to a partial exemption equal to that percentage of the value of the property that is equal to the percentage that the number of units serving lower income households represents of the total number of residential units in any year in which any of the following criteria applies:
(A)The acquisition, rehabilitation, development, or operation of the property, or any combination of these factors, is financed with tax-exempt mortgage revenue bonds or general obligation bonds, or is financed by local, state, or federal loans or grants and the rents of the occupants who are lower income households do not exceed those prescribed by deed restrictions or regulatory agreements pursuant to the terms of the financing or financial assistance.
(B)The owner of the property is eligible for and receives low-income housing tax credits pursuant to Section 42 of the Internal Revenue Code of 1986, as added by Public Law 99-514.
(C)In the case of a claim, other than a claim with respect to property owned by a limited partnership in which the managing general partner is an eligible nonprofit corporation, that is filed for the 200001 fiscal year or any fiscal year thereafter, 90 percent or more of the occupants of the property are lower income households whose rent does not exceed the rent prescribed by Section 50053 of the Health and Safety Code.
(D)(i)The property was previously purchased and owned by the Department of Transportation pursuant to a consent decree requiring housing mitigation measures relating to the construction of a freeway and is now solely owned by an organization that qualifies as an exempt organization under Section 501(c)(3) of the Internal Revenue Code.
(ii)This subparagraph shall not apply to property owned by a limited partnership in which the managing partner is an eligible nonprofit corporation.
(2)In order to be eligible for the exemption provided by this subdivision, the owner of the property shall do both of the following:
(A)(i)For any claim filed for the 200001 fiscal year or any fiscal year thereafter, certify and ensure, subject to the limitation in clause (ii), that there is an enforceable and verifiable agreement with a public agency, a recorded deed restriction, or other legal document that restricts the projects usage and that provides that the units designated for use by lower income households are continuously available to or occupied by lower income households, subject to the exception in clause (iii), at rents that do not exceed those prescribed by Section 50053 of the Health and Safety Code, or, to the extent that the terms of federal, state, or local financing or financial assistance conflicts with Section 50053, rents that do not exceed those prescribed by the terms of the financing or financial assistance.
(ii)In the case of a limited partnership in which the managing general partner is an eligible nonprofit corporation, the restriction and provision specified in clause (i) shall be contained in an enforceable and verifiable agreement with a public agency, or in a recorded deed restriction to which the limited partnership certifies.
(iii)(I)In the case of an owner of property that is eligible for and receives a low-income housing tax credit pursuant to Section 42 of the Internal Revenue Code, relating to low-income housing credit, a unit shall continue to be treated as occupied by a lower income household if the occupants were lower income households on the lien date in the fiscal year in which their occupancy of the unit commenced and the unit continues to be rent restricted, notwithstanding an increase in the income of the occupants of the unit to 140 percent of area median income, adjusted for family size. However, the unit shall cease to be treated as a lower income unit if the income of the occupants of the unit increases above 140 percent of area median income, adjusted for family size.
(II)This clause shall only be operative from the 201819 fiscal year through the 202728 fiscal year.
(B)Certify that the funds that would have been necessary to pay property taxes are used to maintain the affordability of, or reduce rents otherwise necessary for, the units occupied by lower income households.
(3)As used in this subdivision:
(A)Lower income households has the same meaning as the term lower income households as defined by Section 50079.5 of the Health and Safety Code.
(B)Related facilities means any managers units and any and all common area spaces that are included within the physical boundaries of the rental housing development, including, but not limited to, common area space, walkways, balconies, patios, clubhouse space, meeting rooms, laundry facilities, and parking areas, except any portions of the overall development that are nonexempt commercial space.
(C)(i)Units serving lower income households shall mean units that are occupied by lower income households at an affordable rent, as defined in Section 50053 of the Health and Safety Code or, to the extent that the terms of federal, state, or local financing or financial assistance conflicts with Section 50053, rents that do not exceed those prescribed by the terms of the financing or financial assistance. Units reserved for lower income households at an affordable rent that are temporarily vacant due to tenant turnover or repairs shall be counted as occupied.
(ii)(I)Units serving lower income households shall also mean units specified in clause (iii) of subparagraph (A) of paragraph (2).
(II)This clause shall only be operative from the 201819 fiscal year through the 202728 fiscal year.
(h)Property used exclusively for an emergency or temporary shelter and related facilities for homeless persons and families and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations meeting all of the requirements of this section shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section. Property that otherwise would be exempt pursuant to this subdivision, except that it includes housing and related facilities for other than an emergency or temporary shelter, shall be entitled to a partial exemption.
As used in this subdivision, emergency or temporary shelter means a facility that would be eligible for funding pursuant to Chapter 11 (commencing with Section 50800) of Part 2 of Division 31 of the Health and Safety Code.
(i)Property used exclusively for housing and related facilities for employees of religious, charitable, scientific, or hospital organizations that meet all the requirements of subdivision (a) and owned and operated by funds, foundations, limited liability companies, or corporations that meet all the requirements of subdivision (a) shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section to the extent the residential use of the property is institutionally necessary for the operation of the organization.
(j)For purposes of this section, charitable purposes include educational purposes. For purposes of this subdivision, educational purposes means those educational purposes and activities for the benefit of the community as a whole or an unascertainable and indefinite portion thereof, and do not include those educational purposes and activities that are primarily for the benefit of an organizations shareholders. Educational activities include the study of relevant information, the dissemination of that information to interested members of the general public, and the participation of interested members of the general public.
(k)In the case of property used exclusively for the exempt purposes specified in this section, owned and operated by limited liability companies that are organized and operated for those purposes, the State Board of Equalization shall adopt regulations to specify the ownership, organizational, and operational requirements for those companies to qualify for the exemption provided by this section.
(l)The amendments made by Chapter 354 of the Statutes of 2004 shall apply with respect to lien dates occurring on and after January 1, 2005.
(m)The amendments made by Chapter 836 of the Statutes of 2016 shall apply with respect to lien dates occurring on and after January 1, 2017.
(n)The amendments made by the act adding this subdivision shall apply with respect to lien dates occurring on and after January 1, 2019.
SEC. 2.Section 214.18 is added to the Revenue and Taxation Code, to read:214.18.(a)For purposes of this section:
(1)Total exemption amount limitation means the exemption amount limitation with respect to a single property or multiple properties that is specified in subparagraph (C) of paragraph (1) of subdivision (g) of Section 214, as that section read before January 1, 2019.
(2)(A) Qualified property means property used exclusively for rental housing and related facilities where 90 percent or more of the occupants of the property are lower income households whose rent does not exceed the rent prescribed by Section 50053 of the Health and Safety Code and that qualifies for exemption under Section 214 on the sole basis of this criteria as specified in subparagraph (C) of paragraph (1) of subdivision (g) of Section 214.
(B)Qualified property does not include property owned by a limited partnership in which the managing general partner is an eligible nonprofit organization, as described in subparagraph (C) of paragraph (1) of subdivision (g) of Section 214.
(3)Qualified taxpayer means a taxpayer subject to the total exemption amount limitation.
(4)Qualified claim means a claim for exemption that was filed for a qualified property with the assessor on and after January 1, 2017, and before January 1, 2019, for which the assessor granted a partial exemption.
(5)Qualified ad valorem tax in excess of the total exemption amount limitation, and related interest or penalty means that portion of ad valorem tax levied to a qualified taxpayer on qualified property with respect to a single property or multiple properties, and any interest or penalty imposed with regard to that portion of tax.
(b)(1)Any outstanding qualified ad valorem tax in excess of the total exemption amount limitation, and related interest or penalty, which was levied or imposed on and after January 1, 2017, and before January 1, 2019, with respect to a qualified property for which a qualified claim was filed, shall be canceled.
(2)On or after January 1, 2019, an escape assessment shall not be levied on qualified property if that amount would be subject to cancellation under paragraph (1).
SEC. 3.The Legislature finds and declares that Section 2 of this act fulfills a statewide public purpose because it addresses Californias serious shortage of affordable, decent, safe, and sanitary housing for persons and families of low or moderate income, including the elderly and handicapped, income by providing necessary property tax relief for certain tax-exempt organizations so that these tax-exempt organizations can provide affordable housing for persons and families of low or moderate income.
SEC. 4.If the Commission on State Mandates determines that this act contains costs mandated by the state, reimbursement to local agencies and school districts for those costs shall be made pursuant to Part 7 (commencing with Section 17500) of Division 4 of Title 2 of the Government Code.
SEC. 5.Notwithstanding Section 2229 of the Revenue and Taxation Code, no appropriation is made by this act and the state shall not reimburse any local agency for any property tax revenues lost by it pursuant to this act.
(a)Property used exclusively for religious, hospital, scientific, or charitable purposes owned and operated by community chests, funds, foundations, limited liability companies, or corporations organized and operated for religious, hospital, scientific, or charitable purposes is exempt from taxation, including ad valorem taxes to pay the interest and redemption charges on any indebtedness approved by the voters prior to July 1, 1978, or any bonded indebtedness for the acquisition or improvement of real property approved on or after July 1, 1978, by two-thirds of the votes cast by the voters voting on the proposition, if:
(1)The owner is not organized or operated for profit. However, in the case of hospitals, the organization shall not be deemed to be organized or operated for profit if, during the immediately preceding fiscal year, operating revenues, exclusive of gifts, endowments, and grants-in-aid, did not exceed operating expenses by an amount equivalent to 10 percent of those operating expenses. As used herein, operating expenses include depreciation based on cost of replacement and amortization of, and interest on, indebtedness.
(2)No part of the net earnings of the owner inures to the benefit of any private shareholder or individual.
(3)The property is used for the actual operation of the exempt activity, and does not exceed an amount of property reasonably necessary to the accomplishment of the exempt purpose.
(A)For the purposes of determining whether the property is used for the actual operation of the exempt activity, consideration shall not be given to use of the property for either or both of the following described activities if that use is occasional:
(i)The owner conducts fundraising activities on the property and the proceeds derived from those activities are not unrelated business taxable income, as defined in Section 512 of the Internal Revenue Code, of the owner and are used to further the exempt activity of the owner.
(ii)The owner permits any other organization that meets all of the requirements of this subdivision, other than ownership of the property, to conduct fundraising activities on the property and the proceeds derived from those activities are not unrelated business taxable income, as defined in Section 512 of the Internal Revenue Code, of the organization, are not subject to the tax on unrelated business taxable income that is imposed by Section 511 of the Internal Revenue Code, and are used to further the exempt activity of the organization.
(B)For purposes of subparagraph (A):
(i)Occasional use means use of the property on an irregular or intermittent basis by the qualifying owner or any other qualifying organization described in clause (ii) of subparagraph (A) that is incidental to the primary activities of the owner or the other organization.
(ii)Fundraising activities means both activities involving the direct solicitation of money or other property and the anticipated exchange of goods or services for money between the soliciting organization and the organization or person solicited.
(C)Subparagraph (A) shall have no application in determining whether paragraph (3) has been satisfied unless the owner of the property and any other organization using the property as provided in subparagraph (A) have filed with the assessor a valid organizational clearance certificate issued pursuant to Section 254.6.
(D)For the purposes of determining whether the property is used for the actual operation of the exempt activity, consideration shall not be given to the use of the property for meetings conducted by any other organization if the meetings are incidental to the other organizations primary activities, are not fundraising meetings or activities as defined in subparagraph (B), are held no more than once per week, and the other organization and its use of the property meet all other requirements of paragraphs (1) to (5), inclusive, of this subdivision. The owner or the other organization also shall file with the assessor a copy of a valid, unrevoked letter or ruling from the Internal Revenue Service or the Franchise Tax Board stating that the other organization, or the national organization of which it is a local chapter or affiliate, qualifies as an exempt organization under Section 501(c)(3) or 501(c)(4) of the Internal Revenue Code or Section 23701d, 23701f, or 23701w.
(E)Nothing in subparagraph (A), (B), (C), or (D) shall be construed to either enlarge or restrict the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(4)The property is not used or operated by the owner or by any other person so as to benefit any officer, trustee, director, shareholder, member, employee, contributor, or bondholder of the owner or operator, or any other person, through the distribution of profits, payment of excessive charges or compensations, or the more advantageous pursuit of their business or profession.
(5)The property is not used by the owner or members thereof for fraternal or lodge purposes, or for social club purposes except where that use is clearly incidental to a primary religious, hospital, scientific, or charitable purpose.
(6)The property is irrevocably dedicated to religious, charitable, scientific, or hospital purposes and upon the liquidation, dissolution, or abandonment of the owner will not inure to the benefit of any private person except a fund, foundation, or corporation organized and operated for religious, hospital, scientific, or charitable purposes.
(7)The property, if used exclusively for scientific purposes, is used by a foundation or institution that, in addition to complying with the foregoing requirements for the exemption of charitable organizations in general, has been chartered by the Congress of the United States (except that this requirement shall not apply when the scientific purposes are medical research), and whose objects are the encouragement or conduct of scientific investigation, research, and discovery for the benefit of the community at large.
The exemption provided for herein shall be known as the welfare exemption. This exemption shall be in addition to any other exemption now provided by law, and the existence of the exemption provision in paragraph (2) of subdivision (a) of Section 202 shall not preclude the exemption under this section for museum or library property. Except as provided in subdivision (e), this section shall not be construed to enlarge the college exemption.
(b)Property used exclusively for school purposes of less than collegiate grade and owned and operated by religious, hospital, or charitable funds, foundations, limited liability companies, or corporations, which property and funds, foundations, limited liability companies, or corporations meet all of the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(c)Property used exclusively for nursery school purposes and owned and operated by religious, hospital, or charitable funds, foundations, limited liability companies, or corporations, which property and funds, foundations, limited liability companies, or corporations meet all the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(d)Property used exclusively for a noncommercial educational FM broadcast station or an educational television station, and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations meeting all of the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
(e)Property used exclusively for religious, charitable, scientific, or hospital purposes and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations or educational institutions of collegiate grade, as defined in Section 203, which property and funds, foundations, limited liability companies, corporations, or educational institutions meet all of the requirements of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section. As to educational institutions of collegiate grade, as defined in Section 203, the requirements of paragraph (6) of subdivision (a) shall be deemed to be met if both of the following are met:
(1)The property of the educational institution is irrevocably dedicated in its articles of incorporation to charitable and educational purposes, to religious and educational purposes, or to educational purposes.
(2)The articles of incorporation of the educational institution provide for distribution of its property upon its liquidation, dissolution, or abandonment to a fund, foundation, or corporation organized and operated for religious, hospital, scientific, charitable, or educational purposes meeting the requirements for exemption provided by Section 203 or this section.
(f)Property used exclusively for housing and related facilities for elderly or handicapped families and financed by, including, but not limited to, the federal government pursuant to Section 202 of Public Law 86-372 (12 U.S.C. Sec. 1701q), as amended, Section 231 of Public Law 73-479 (12 U.S.C. Sec. 1715v), Section 236 of Public Law 90-448 (12 U.S.C. Sec. 1715z), or Section 811 of Public Law 101-625 (42 U.S.C. Sec. 8013), and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations meeting all of the requirements of this section shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section.
The amendment of this paragraph made by Chapter 1102 of the Statutes of 1984 does not constitute a change in, but is declaratory of, existing law. However, no refund of property taxes shall be required as a result of this amendment for any fiscal year prior to the fiscal year in which the amendment takes effect.
Property used exclusively for housing and related facilities for elderly or handicapped families at which supplemental care or services designed to meet the special needs of elderly or handicapped residents are not provided, or that is not financed by the federal government pursuant to Section 202 of Public Law 86-372 (12 U.S.C. Sec. 1701q), as amended, Section 231 of Public Law 73-479 (12 U.S.C. Sec. 1715v), Section 236 of Public Law 90-448 (12 U.S.C. Sec. 1715z), or Section 811 of Public Law 101-625 (42 U.S.C. Sec. 8013), shall not be entitled to exemption pursuant to this subdivision unless the property is used for housing and related facilities for low- and moderate-income elderly or handicapped families. Property that would otherwise be exempt pursuant to this subdivision, except that it includes some housing and related facilities for other than low- or moderate-income elderly or handicapped families, shall be entitled to a partial exemption. The partial exemption shall be equal to that percentage of the value of the property that is equal to the percentage that the number of low- and moderate-income elderly and handicapped families represents of the total number of families occupying the property.
As used in this subdivision, low and moderate income has the same meaning as the term persons and families of low or moderate income as defined by Section 50093 of the Health and Safety Code.
(g)(1)Property used exclusively for rental housing and related facilities and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations, including limited partnerships in which the managing general partner is an eligible nonprofit corporation or eligible limited liability company, meeting all of the requirements of this section, or by veterans organizations, as described in Section 215.1, meeting all the requirements of paragraphs (1) to (7), inclusive, of subdivision (a), shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section and shall be entitled to a partial exemption equal to that percentage of the value of the property that is equal to the percentage that the number of units serving lower income households represents of the total number of residential units in any year in which any of the following criteria applies:
(A)The acquisition, rehabilitation, development, or operation of the property, or any combination of these factors, is financed with tax-exempt mortgage revenue bonds or general obligation bonds, or is financed by local, state, or federal loans or grants and the rents of the occupants who are lower income households do not exceed those prescribed by deed restrictions or regulatory agreements pursuant to the terms of the financing or financial assistance.
(B)The owner of the property is eligible for and receives low-income housing tax credits pursuant to Section 42 of the Internal Revenue Code of 1986, as added by Public Law 99-514.
(C)In the case of a claim, other than a claim with respect to property owned by a limited partnership in which the managing general partner is an eligible nonprofit corporation, that is filed for the 200001 fiscal year or any fiscal year thereafter, 90 percent or more of the occupants of the property are lower income households whose rent does not exceed the rent prescribed by Section 50053 of the Health and Safety Code. The total exemption amount allowed under this subdivision to a taxpayer, with respect to a single property or multiple properties for any fiscal year on the sole basis of the application of this subparagraph, may not exceed ten million dollars ($10,000,000) in assessed value.
(D)(i)The property was previously purchased and owned by the Department of Transportation pursuant to a consent decree requiring housing mitigation measures relating to the construction of a freeway and is now solely owned by an organization that qualifies as an exempt organization under Section 501(c)(3) of the Internal Revenue Code.
(ii)This subparagraph shall not apply to property owned by a limited partnership in which the managing partner is an eligible nonprofit corporation.
(2)In order to be eligible for the exemption provided by this subdivision, the owner of the property shall do both of the following:
(A)(i)For any claim filed for the 200001 fiscal year or any fiscal year thereafter, certify and ensure, subject to the limitation in clause (ii), that there is an enforceable and verifiable agreement with a public agency, a recorded deed restriction, or other legal document that restricts the projects usage and that provides that the units designated for use by lower income households are continuously available to or occupied by lower income households, subject to the exception in clause (iii), at rents that do not exceed those prescribed by Section 50053 of the Health and Safety Code, or, to the extent that the terms of federal, state, or local financing or financial assistance conflicts with Section 50053, rents that do not exceed those prescribed by the terms of the financing or financial assistance.
(ii)In the case of a limited partnership in which the managing general partner is an eligible nonprofit corporation, the restriction and provision specified in clause (i) shall be contained in an enforceable and verifiable agreement with a public agency, or in a recorded deed restriction to which the limited partnership certifies.
(iii)(I)In the case of an owner of property that is eligible for and receives a low-income housing tax credit pursuant to Section 42 of the Internal Revenue Code, relating to low-income housing credit, a unit shall continue to be treated as occupied by a lower income household if the occupants were lower income households on the lien date in the fiscal year in which their occupancy of the unit commenced and the unit continues to be rent restricted, notwithstanding an increase in the income of the occupants of the unit to 140 percent of area median income, adjusted for family size. However, the unit shall cease to be treated as a lower income unit if the income of the occupants of the unit increases above 140 percent of area median income, adjusted for family size.
(II)This clause shall only be operative from the 201819 fiscal year through the 202728 fiscal year.
(B)Certify that the funds that would have been necessary to pay property taxes are used to maintain the affordability of, or reduce rents otherwise necessary for, the units occupied by lower income households.
(3)As used in this subdivision:
(A)Lower income households has the same meaning as the term lower income households as defined by Section 50079.5 of the Health and Safety Code.
(B)Related facilities means any managers units and any and all common area spaces that are included within the physical boundaries of the rental housing development, including, but not limited to, common area space, walkways, balconies, patios, clubhouse space, meeting rooms, laundry facilities, and parking areas, except any portions of the overall development that are nonexempt commercial space.
(C)(i)Units serving lower income households shall mean units that are occupied by lower income households at an affordable rent, as defined in Section 50053 of the Health and Safety Code or, to the extent that the terms of federal, state, or local financing or financial assistance conflicts with Section 50053, rents that do not exceed those prescribed by the terms of the financing or financial assistance. Units reserved for lower income households at an affordable rent that are temporarily vacant due to tenant turnover or repairs shall be counted as occupied.
(ii)(I)Units serving lower income households shall also mean units specified in clause (iii) of subparagraph (A) of paragraph (2).
(II)This clause shall only be operative from the 201819 fiscal year through the 202728 fiscal year.
(h)Property used exclusively for an emergency or temporary shelter and related facilities for homeless persons and families and owned and operated by religious, hospital, scientific, or charitable funds, foundations, limited liability companies, or corporations meeting all of the requirements of this section shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section. Property that otherwise would be exempt pursuant to this subdivision, except that it includes housing and related facilities for other than an emergency or temporary shelter, shall be entitled to a partial exemption.
As used in this subdivision, emergency or temporary shelter means a facility that would be eligible for funding pursuant to Chapter 11 (commencing with Section 50800) of Part 2 of Division 31 of the Health and Safety Code.
(i)Property used exclusively for housing and related facilities for employees of religious, charitable, scientific, or hospital organizations that meet all the requirements of subdivision (a) and owned and operated by funds, foundations, limited liability companies, or corporations that meet all the requirements of subdivision (a) shall be deemed to be within the exemption provided for in subdivision (b) of Section 4 and Section 5 of Article XIII of the California Constitution and this section to the extent the residential use of the property is institutionally necessary for the operation of the organization.
(j)For purposes of this section, charitable purposes include educational purposes. For purposes of this subdivision, educational purposes means those educational purposes and activities for the benefit of the community as a whole or an unascertainable and indefinite portion thereof, and do not include those educational purposes and activities that are primarily for the benefit of an organizations shareholders. Educational activities include the study of relevant information, the dissemination of that information to interested members of the general public, and the participation of interested members of the general public.
(k)In the case of property used exclusively for the exempt purposes specified in this section, owned and operated by limited liability companies that are organized and operated for those purposes, the State Board of Equalization shall adopt regulations to specify the ownership, organizational, and operational requirements for those companies to qualify for the exemption provided by this section.
(l)The amendments made by Chapter 354 of the Statutes of 2004 shall apply with respect to lien dates occurring on and after January 1, 2005.
(m)The amendments made by the act adding this subdivision Chapter 836 of the Statutes of 2016 shall apply with respect to lien dates occurring on and after January 1, 2017.
(n)The amendments made by the act adding this subdivision shall apply with respect to lien dates occurring on and after January 1, 2019.
SEC. 2.Section 214.18 is added to the Revenue and Taxation Code, to read:214.18.(a)For purposes of this section:
(1)Total exemption amount limitation means the exemption amount limitation with respect to a single property or multiple properties that is specified in subparagraph (C) of paragraph (1) of subdivision (g) of Section 214, as that section read before January 1, 2019.
(2)(A) Qualified property means property used exclusively for rental housing and related facilities where 90 percent or more of the occupants of the property are lower income households whose rent does not exceed the rent prescribed by Section 50053 of the Health and Safety Code and that qualifies for exemption under Section 214 on the sole basis of this criteria as specified in subparagraph (C) of paragraph (1) of subdivision (g) of Section 214.
(B)Qualified property does not include property owned by a limited partnership in which the managing general partner is an eligible nonprofit organization, as described in subparagraph (C) of paragraph (1) of subdivision (g) of Section 214.
(3)Qualified taxpayer means a taxpayer subject to the total exemption amount limitation.
(4)Qualified claim means a claim for exemption that was filed for a qualified property with the assessor on and after January 1, 2017, and before January 1, 2019, for which the assessor granted a partial exemption.
(5)Qualified ad valorem tax in excess of the total exemption amount limitation, and related interest or penalty means that portion of ad valorem tax levied to a qualified taxpayer on qualified property with respect to a single property or multiple properties, and any interest or penalty imposed with regard to that portion of tax.
(b)(1)Any outstanding qualified ad valorem tax in excess of the total exemption amount limitation, and related interest or penalty, which was levied or imposed on and after January 1, 2017, and before January 1, 2019, with respect to a qualified property for which a qualified claim was filed, shall be canceled.
(2)On or after January 1, 2019, an escape assessment shall not be levied on qualified property if that amount would be subject to cancellation under paragraph (1).
SEC. 3.The Legislature finds and declares that Section 2 of this act fulfills a statewide public purpose because it addresses Californias serious shortage of affordable, decent, safe, and sanitary housing for persons and families of low or moderate income, including the elderly and handicapped, by providing necessary property tax relief for certain tax-exempt organizations so that these tax-exempt organizations can provide affordable housing for persons and families of low or moderate income.
SEC. 4.If the Commission on State Mandates determines that this act contains costs mandated by the state, reimbursement to local agencies and school districts for those costs shall be made pursuant to Part 7 (commencing with Section 17500) of Division 4 of Title 2 of the Government Code.
SEC. 5.Notwithstanding Section 2229 of the Revenue and Taxation Code, no appropriation is made by this act and the state shall not reimburse any local agency for any property tax revenues lost by it pursuant to this act.
|
Date
|
Status
|
|---|---|
| Sep 22, 2018 | Chaptered by Secretary of State. Chapter 694, Statutes of 2018. |
| Sep 22, 2018 | Approved by the Governor. |
| Sep 10, 2018 | Enrolled and presented to the Governor at 4 p.m. |
| Aug 30, 2018 | Assembly amendments concurred in. (Ayes 39. Noes 0.) Ordered to engrossing and enrolling. |
| Aug 30, 2018 | Ordered to special consent calendar. |
| Aug 29, 2018 | In Senate. Concurrence in Assembly amendments pending. |
| Aug 29, 2018 | Read third time. Passed. Ordered to the Senate. |
| Aug 21, 2018 | Read second time. Ordered to third reading. |
| Aug 20, 2018 | Read second time and amended. Ordered to second reading. |
| Aug 16, 2018 | From committee: Do pass as amended. (Ayes 12. Noes 0.) (August 16). |
| Aug 8, 2018 | August 8 set for first hearing. Placed on suspense file. |
| Jul 3, 2018 | Read second time and amended. Re-referred to Com. on APPR. |
| Jul 2, 2018 | From committee: Do pass as amended and re-refer to Com. on APPR. (Ayes 9. Noes 0.) (June 25). |
| Jun 7, 2018 | Referred to Com. on REV. & TAX. |
| May 31, 2018 | In Assembly. Read first time. Held at Desk. |
| May 31, 2018 | Read third time. Passed. (Ayes 39. Noes 0.) Ordered to the Assembly. |
| May 29, 2018 | Ordered to special consent calendar. |
| May 25, 2018 | Read second time. Ordered to third reading. |
| May 18, 2018 | Set for hearing May 25. |
| Apr 16, 2018 | April 16 hearing: Placed on APPR. suspense file. |
| Apr 9, 2018 | Set for hearing April 16. |
| Apr 4, 2018 | From committee: Do pass and re-refer to Com. on APPR. (Ayes 6. Noes 0.) (April 4). Re-referred to Com. on APPR. |
| Mar 21, 2018 | Set for hearing April 4. |
| Feb 22, 2018 | Referred to Com. on GOV. & F. |
| Feb 14, 2018 | From printer. May be acted upon on or after March 16. |
| Feb 13, 2018 | Introduced. Read first time. To Com. on RLS. for assignment. To print. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Aug 30, 2018 | Unfinished Business SB1115 Hill Concurrence | Senate Floor |
Passed |
|
| Aug 29, 2018 | SB 1115 Hill Senate Third Reading By BERMAN | Assembly Floor |
Passed |
|
| Aug 16, 2018 | Do pass as amended. | Assembly Standing Committee on Appropriations |
Passed |
|
| Jun 25, 2018 | Do pass as amended and be re-referred to the Committee on [Appropriations] | Assembly Standing Committee on Revenue and Taxation |
Passed |
|
| May 31, 2018 | Special Consent SB1115 | Senate Floor |
Passed |
|
| May 25, 2018 | Do pass | Senate Standing Committee on Appropriations |
Passed |
|
| Apr 16, 2018 | Placed on suspense file | Senate Standing Committee on Appropriations |
Passed |
|
| Apr 4, 2018 | Do pass, but first be re-referred to the Committee on [Appropriations] | Senate Standing Committee on Governance and Finance |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | SB |
UNFINISHED BUSINESS
Bill No: SB 1115
:
SENATE GOVERNANCE & FIN. COMMITTEE: 6-0, 4/4/18
AYES: McGuire, Nguyen, Beall, Hernandez, Lara, Moorlach
NO VOTE RECORDED: Hertzberg
SENATE APPROPRIATIONS COMMITTEE: 7-0, 5/25/18
AYES: Lara, Bates, Beall, Bradford, Hill, Nielsen, Wiener
SENATE FLOOR: 39-0, 5/31/18
AYES: Allen, Anderson, Atkins, Bates, Beall, Berryhill, Bradford, Cannella, De León, Dodd, Fuller, Gaines, Galgiani, Glazer, Hernandez, Hertzberg, Hill, Hueso, Jackson, Lara, Leyva, McGuire, Mitchell, Monning, Moorlach, Morrell, Newman, Nguyen, Nielsen, Pan, Portantino, Roth, Skinner, Stern, Stone, Vidak, Wieckowski, Wiener, Wilk
ASSEMBLY FLOOR: 80-0, 8/29/18 - See last page for vote
DIGEST:
This bill increases the current cap on the value for purposes of the welfare exemption from property tax for non-publicly financed affordable housing.
Assembly Amendments
delete the elimination of the cap, instead increasing it from $10 million in value to $20 million, and make a technical change.
Existing law:
- Provides that all property is taxable unless explicitly exempted by the Constitution or federal law (California Constitution, Article XIII).
- Allows the Legislature to exempt property used for charitable purposes, and owned by non-profit entities organized and operated for charitable purposes, such as universities, hospitals, and libraries (California Constitution, Article XIII, Sections Four and Five). The Legislature enacted this exemption, commonly known as the “welfare exemption.”
- Limits the maximum amount of any ad valorem tax on real property at 1% of full cash value, and directs assessors to only reappraise property when newly constructed, or when ownership changes (Proposition 13, 1978).
- Allows the welfare exemption for rental housing when the housing is financed by tax-exempt mortgage revenue bonds; general obligation bonds; federal, state, or local grants; or federal low-income housing tax credits, pursuant to specific requirements.
- Allows, additionally, non-publicly financed affordable housing to be exempt if:
- The property is managed solely by a non-profit organization, specifically excluding limited partnerships, and
- 90% of occupants are of low- or very-low income.
- The property is enforceably restricted for low-income housing, and rents do not exceed those prescribed in deed restrictions, and
- The property owner certifies that funds that would have been used to pay property taxes are used to maintain the affordability of the units or reduce rents.
- Caps the non-publicly financed exemption at $10 million in value statewide per owner.
This bill:
- Increases from $10 million to $20 million the cap on valuation for non-publicly financed housing owned and operated by a non-profit organization for purposes of the welfare exemption from property tax.
- Applies this change to lien dates on or after January 1, 2019.
- Provides a process for taxpayers to file a claim to have any outstanding taxes or escape assessments cancelled.
- Makes legislative findings and declarations supporting its purposes.
Background
Prior to 1999, rental housing owners could claim a welfare exemption from property tax for low-income housing if 20% of the property’s residents were low-income. After the Los Angeles Housing Project investigated some of the city’s worst housing projects, they discovered that tax exempt property owners were not providing basic maintenance to housing that qualified them for the exemption from property tax. Responding to the investigation, the Legislature enacted AB 1559 (Wiggins, Chapter 927, Statutes of 1999), which repealed the occupancy test, instead requiring owners to receive public financing in the forms listed above for the project to claim the welfare exemption, in addition to the above requirements. However, AB 1559 revoked the exemption for many worthy properties that weren’t publicly financed, so the Legislature subsequently enacted AB 659 (Wiggins, Chapter 601, Statutes of 2000), which further refined the law to:
- Reenact the occupancy threshold, but increased to 90%,
- Cap the exemption amount to $20,000 in tax for all properties the taxpayer owns in the state, and
- Require the property be managed solely by a non-profit organization, specifically excluding limited partnerships, to be eligible for the exemption.
Since 2000, the value of housing increased, compelling some non-profits to pay taxes on amounts that exceeded the $20,000 cap, and discouraging them from acquiring rental housing in the hopes of preserving existing affordable units in their areas. In response, the Legislature enacted SB 996 (Hill, Chapter 836, Statutes of 2016), which:
- Quintupled the cap, and revised it to instead apply to the property’s value, not the tax paid, with the new threshold at $10 million of assessed value,
- Created a process for taxpayers to file a claim to cancel any outstanding taxes or escape assessments due on values that exceeded the previous cap, and
- Required property owners claiming the welfare exemption to provide specified information regarding the household income of and the rent charged to an occupant of an exempt unit.
However, charities still must pay tax on any amount of value that exceeds the $10 million cap, which applies to all of its properties statewide. As a result, the cap deters charities that want to construct or acquire additional affordable housing, especially those in areas of the state with higher housing values.
FISCAL EFFECT: Appropriation: Fiscal Com.: Local:
According to the Assembly Appropriations Committee:
- Unknown property tax revenue losses because of the exemption cap modification. Any property tax revenue losses will lead to increased General Fund Proposition 98 spending equal to roughly half of the local revenue losses.
- Potential, but likely modest, reimbursable costs for local county officials related to the assessment process. It is unlikely any local agency will submit a claim to the Commission on State Mandates for reimbursement.
AIDS Healthcare Foundation
Irvine Community Land Trust
San Mateo County Board of Supervisors
St. Francis Center
OPPOSITION: (Verified 8/21/18)
None received
ARGUMENTS IN SUPPORT: According to the author, “According to the author, “Four out of the five metropolitan areas with the least affordable rental markets nationwide continue to be in California. California continues to have a very serious shortage of affordable housing. SB 1115 will aid non-profits and religious organizations by eliminating the property tax exemption cap on their affordable housing properties. It will aid them by providing property tax relief to certain non-profits so that these tax-exempt organizations can continue to provide more affordable housing for low income people and families. By removing the property tax exemption cap – charities in my district can continue to purchase,
rehab and provide more affordable, safe and dignified housing to my district’s most neediest families.”
ASSEMBLY FLOOR: 80-0, 8/29/18
AYES: Acosta, Aguiar-Curry, Travis Allen, Arambula, Baker, Berman, Bigelow, Bloom, Bonta, Brough, Burke, Caballero, Calderon, Carrillo, Cervantes, Chau, Chávez, Chen, Chiu, Choi, Chu, Cooley, Cooper, Cunningham, Dahle, Daly, Eggman, Flora, Fong, Frazier, Friedman, Gabriel, Gallagher, Cristina Garcia, Eduardo Garcia, Gipson, Gloria, Gonzalez Fletcher, Gray, Grayson, Harper, Holden, Irwin, Jones-Sawyer, Kalra, Kamlager-Dove, Kiley, Lackey, Levine, Limón, Low, Maienschein, Mathis, Mayes, McCarty, Medina, Melendez, Mullin, Muratsuchi, Nazarian, Obernolte, O'Donnell, Patterson, Quirk, Quirk-Silva, Reyes, Rivas, Rodriguez, Rubio, Salas, Santiago, Steinorth, Mark Stone, Thurmond, Ting, Voepel, Waldron, Weber, Wood, Rendon
8/30/18 9:30:33
**** END ****
SENATE THIRD READING
STR Bill Id:
Author:(Hill)
As Amended Ver:August 20, 2018
Majority vote
SENATE VOTE: 39-0
Committee | Votes | Ayes | Noes |
Revenue & Taxation | 9-0 | Burke, Mathis, Chu, Gray, Mullin, Quirk, Rivas, Ting, Voepel | |
Appropriations | 12-0 | Gonzalez Fletcher, Bloom, Bonta, Calderon, Carrillo, Chau, Eggman, Friedman, Eduardo Garcia, Nazarian, Quirk, Reyes |
|
SUMMARY: Property taxation: welfare exemption: low income housing
SUMMARY: Increases the statewide welfare exemption cap from $10 million to $20 million in assessed value applicable to certain low-income rental housing owned and operated by non-profit organizations not receiving government financing or tax credits. Specifically, this bill:
- Increases from $10 million to $20 million the welfare exemption cap that limits the total exemption amount allowed to non-publicly financed rental housing owned and operated by non-profit organizations for low-income households whose rent does not exceed specified amounts.
- Requires any outstanding qualified ad valorem tax in excess of the "total exemption amount limitation" (taxes levied on assessed values between $10 million and $20 million), and related interest or penalty, which was levied or imposed on and after January 1, 2017, and before January 1, 2019, to be canceled if a qualified taxpayer files a "qualified claim" on "qualified property".
- Prohibits, on and after January 1, 2019, an escape assessment from being levied on qualified property if that amount would be subject to cancellation.
- Defines a "qualified taxpayer" as a taxpayer subject to the total exemption amount limitation.
- Defines "total exemption amount limitation" as the assessed value exemption amount limitation with respect to a single property or multiple properties that is specified in Revenue and Taxation Code (R&TC) Section 214(g)(1)(C) as it read before January 1, 2019. This amount is $10 million in assessed value.
- Defines a "qualified claim" as a claim for exemption that was filed for a qualified property with the assessor on and after January 1, 2017, and before January 1, 2019, for which the assessor granted a partial exemption.
- Defines a "qualified property" as property used exclusively for rental housing and related facilities where 90% or more of the occupants of the property are lower income households as prescribed by Health and Safety Code (HSC) Section 50053, and that qualifies for exemption under RTC Section 214(g)(1)(C).
- Excludes from a "qualified property" property owned by a limited partnership in which the managing general partner is an eligible nonprofit organization.
- Makes findings and declarations related to the cancellation of qualified outstanding ad valorem tax.
- Provides that if the Commission on State Mandates determines that this bill contains costs mandated by the state, reimbursement for those costs will be made as required by statute.
- Provides that no appropriation is made by this act and that no reimbursement is required of any local agency for any property tax revenues lost.
- Applies with respect to lien dates occurring on and after January 1, 2019.
EXISTING LAW:
- Authorizes the Legislature to exempt from taxation, in whole or in part, property used exclusively for religious, hospital, or charitable purposes, as specified. (California Constitution Article XIII, Section 4(b).) The Legislature has implemented this "welfare exemption" in RTC Section 214.
- Exempts low-income rental housing owned and operated by nonprofit organizations, including limited partnerships in which the managing general partner is an eligible nonprofit corporation, as specified.
- Defines "low-income" as households at 80% of area median income (AMI) adjusted for family size.
- Grants a partial welfare exemption, equal to the percentage of units serving lower income households as defined in HSC Section 50053, to property used exclusively for rental housing and operated by nonprofit organizations, as specified, under either of the following conditions:
- The project is publicly financed with tax-exempt mortgage revenue bonds, general obligation bonds, grants, or low-income housing tax credits (LIHTCs); or,
- In the case of non-publicly financed affordable rental housing, 90% of units are affordable for lower income households with the nonprofit organization limited to an exemption of the first $10 million in assessed value.
- Requires organizations seeking the welfare exemption to do the following:
- File an enforceable and verifiable agreement with a public agency or other restriction, as specified, that provides that the units designated for use by lower income households are continuously available to or occupied by lower income households; and,
- Certify that the funds that would have been used to pay property taxes are used to maintain the affordability of, or reduce rents otherwise necessary for, the units occupied by lower income households.
- Requires, in the case of non-publicly financed low-income rental housing, a claim for the welfare exemption to be accompanied by a confidential affidavit, not subject to public disclosure, including a list of units occupied by lower income households for which the exemption is claimed, and the following non-personally identifiable information about the occupants:
- The actual household income of the occupant;
- The maximum rent that may be charged to the occupant; and,
- The actual rent charged to the occupant.
FISCAL EFFECT: According to the Assembly Appropriations Committee:
- Unknown property tax revenue losses because of the exemption cap modification. Any property tax revenue losses will lead to increased General Fund Proposition 98 spending equal to roughly half of the local revenue losses.
- Potential, but likely modest, reimbursable costs for local county officials related to the assessment process. It is unlikely any local agency will submit a claim to the Commission on State Mandates for reimbursement.
COMMENTS:
- The author has provided the following statement in support of this bill:
SB 1115 will aid nonprofits and religious organizations that provide affordable housing by eliminating the property tax exemption cap. Specifically it will help one noble charity in my district from day 1.
Nonprofits that do not receive any tax subsidies or grants from the State or federal government and provide affordable housing to low income families have a cap placed on the amount of property tax that may be exempted annually.
There are only 75 different properties in California owned by 25 nonprofits that are currently being reported to the Board of Equalization by the County Assessors that are subject to this cap. There is only one that is over the cap and it is in my district. With the ever-rising home prices in the Bay Area – this cap will continue to be an issue for this charity as they continue to do an outstanding job in private fundraising to provide more affordable housing for my constituents.
- The Saint Francis Center, which is the non-profit organization referenced above, in support of this bill explains the following:
Recently, Saint Francis Center was able to locate and purchase (off-market) a 25-unit apartment building in downtown Redwood City. We are so happy to add these units to serve our mission of assisting low-income families desperately in need of housing. However, with this purchase, we are now over the $10 million cap established with SB 996 and are subject to property taxes, though this building will, like all of our buildings, be 100% dedicated to extremely low, very low and low-income families…This bill will give much needed relief to nonprofits working diligently to provide dignified, safe, clean and affordable housing to extremely low and very-low income families.
- The County of San Mateo Board of Supervisors states in support of this bill:
With the median price of a single family home in San Mateo County topping $1.315 million and the average rent for a two-bedroom apartment at $3,453 per month, it has become vitally important to preserve and protect the County's affordable housing stock.
To this end, and to help non-profits that do private fundraising exclusively to provide affordable housing in extremely high rent and high property value areas such as our County, it is important to provide them with property tax relief so that these funds can be reinvested in the maintenance, operations and expansion of their housing services. The Saint Francis Center is one such example….The Saint Francis Center provides 87 units of affordable housing and, serves an estimated 435 extremely low-income residents, and goes the extra mile by providing much needed nutrition, clothing and educational assistance to the residents.
- Committee Staff Comments:
- The low-income rental housing property tax exemption: To qualify for the welfare exemption, the rental property must be financed with tax-exempt mortgage revenue bonds or general obligation bonds; local, state, or federal loans or grants; or low-income housing tax credits. Rental properties without government financing may also qualify for the exemption, but under more restrictive conditions. The rental property must be solely owned by a nonprofit organization (limited partnerships with a nonprofit organization serving as the managing general partner are ineligible) and lower income households must comprise 90% or more of its occupants. Additionally, there is a statewide cap on the total amount of exempt property from which a nonprofit organization may benefit, limited to the first $10 million of assessed value with respect to a single property or multiple properties for any fiscal year. Counties annually provide information to the BOE to track this limitation statewide.
- Background: Prior to 2000, nonprofit organizations that own rental housing could generally claim the welfare exemption merely on an "occupancy test" basis, which was 20% of the property's occupants were low income. After the Los Angeles Housing Project investigated some of the city's worst housing projects, they discovered abuse of the welfare exemption that enabled owners of substandard housing properties to benefit from this property tax exemption. Allegations were made that substandard housing owners were partnering with nonprofit organizations in a limited partnership as a ruse to obtain the welfare exemption, or were creating their own nonprofit organizations for the sole purpose of holding their properties. In response, AB 1559 (Wiggins), Chapter 927, Statutes of 1999, repealed the occupancy test and instead required owners to receive government financing or income tax credits to qualify for the welfare exemption as such properties would at least be subject to some level of government oversight, presumably resulting in less fraud and higher quality housing for tenants. AB 1559 also imposed more stringent documentation standards to substantiate that the rental housing is dedicated to low-income housing.
- Why was the exemption cap created? The reforms set forth by AB 1559 inadvertently resulted in revocation of the welfare exemption from otherwise deserving nonprofit organizations that had been providing affordable rental housing without government support. In response, AB 659 (Wiggins), Chapter 601, Statutes of 2000, reinstated the welfare exemption for non-publicly financed rental housing with the restrictions provided for in existing law today. First, limited partnerships were banned. Second, the lower income occupancy test basis was restored, but increased from a 20% to 90% threshold. Third, the exemption cap was created. The intent of the cap was to limit the tax benefit bestowed on "bad actors" who might still qualify for the welfare exemption by creating shell nonprofit organizations.
- What does this bill do? This bill has two main parts. First, this bill increases the exemption cap to the first $20 million in assessed value applicable to nonprofit organizations that own low-income rental housing. Second, this bill allows counties to cancel outstanding taxes on such property levied or imposed between January 1, 2017 and January 1, 2019.
- The exemption cap is unique: No other property eligible for the welfare exemption is subject to any exemption cap limiting the amount of the exemption provided. Additionally, no other property eligible for other types of exemptions (e.g., church, college, museum) is subject to any cap.
- Has the exemption cap been effective? Since its creation, few organizations have exceeded the cap. Most affordable housing projects receive government financing or tax credits. Those nonprofit organizations that have been impacted, or potentially impacted, have sought legislative intervention to increase the cap or to exclude the specific property from the cap. Committee staff notes that it appears the other safeguards (prohibiting limited partnerships and more stringent documentation) have proven effective. The exemption cap, however, has financially harmed those few nonprofits able to privately raise funds to provide housing and earn the support of their local community.
- Exemption cap monitoring statistics: According to data from BOE, which monitors the statewide exemption cap on behalf of county assessors, 26 nonprofit organizations in California provide affordable rental housing without government assistance. These 26 organizations own 76 properties of various types (single-family residences, multifamily residences, and apartment complexes) located across 11 counties.
- Increasing rather than eliminating the cap: As property values continue to rise across California, it is possible that more and more properties may become impacted by the cap, especially in areas with high costs of living such as the San Francisco Bay Area. While eliminating the cap would allow nonprofit organizations able to privately raise funds to acquire and operate more affordable housing units without fear of breaching the cap, increasing the cap allows the Legislature to review this exemption periodically as necessary.
- On the horizon – nonprofits addressing the homelessness challenge: Some nonprofits are stepping into addressing the homelessness crisis arguing that the greatest challenge for housing development is not in the market or near-market rate sector, but rather at the extremely low income and very low income. As such, these nonprofits are beginning to rehabilitate hotels and motels in urban areas and preparing to embark on other expanded housing efforts aimed at those persons with the greatest need - the homeless. These nonprofit entities are concerned that the modest exemption cap of $10 million in value will thwart this effort to use private dollars to assist in the homelessness crisis and associated threat to public health.
Analysis Prepared by: Rose Marie Kinnee / REV. & TAX. / (916) 319-2098 FN: 0004502
Date of Hearing: August 8, 2018
ASSEMBLY COMMITTEE ON APPROPRIATIONS
Lorena Gonzalez Fletcher, Chair
SBPCA Bill Id:SB 1115
Author:(Hill) – As Amended Ver:July 3, 2018
Policy Committee: | Revenue and Taxation | Vote: | 9 - 0 |
|
| ||
|
|
Urgency: No State Mandated Local Program: Yes Reimbursable: Yes
SUMMARY:
This bill eliminates the property tax welfare cap that limits the welfare exemption for certain nonprofit-owned low-income housing projects to the first $10 million in assessed value. This bill also cancels outstanding taxes on such properties levied or imposed between January 1, 2017, and January 1, 2019.
FISCAL EFFECT:
- Unknown property tax revenue losses because of the elimination of the $10 million cap. Based on data from the Board of Equalization (BOE) and statements from the author, only one property is likely to meet the $10 million cap in the near future. However, future revenue losses will grow as existing properties subject to the cap eventually exceed $10 million in assessed value or as new projects are purchased or constructed. Any property tax revenue losses will lead to increased General Fund Proposition 98 spending equal to roughly half of the local revenue losses.
- Potential, but likely modest, reimbursable costs for local county officials related to the assessment process. It is unlikely any local agency will submit a claim to the Commission on State Mandates for reimbursement.
COMMENTS:
- Background. Property owned by nonprofit entities organized and operated for charitable purposes may be exempt from property taxation. This “welfare exemption” includes nonprofit-owned low-income housing if the housing is financed in a specified manner, the property is restricted for low-income housing, rents do not exceed certain levels, and funds that would have been used to pay property taxes are used to maintain the affordability of the units or reduce rents.
- Exemption cap. The welfare exemption applies differently based on whether a project receives government assistance or is privately financed. Nonprofit-owned low-income rental housing receiving government financing or low-income housing tax credits are allowed an unlimited exemption, whereas similar properties that do not receive such financing or tax credits are allowed an exemption for up to $10 million in assessed value. This cap, which was $2 million prior to SB 996 (Hill), Chapter 836, Statutes of 2016, was established in 1999 following an investigation that found that some tax-exempt property owners were not providing basic maintenance for their housing projects.
- Purpose. According to the author, the current welfare exemption cap will continue to be an issue for charities and nonprofits in high-cost areas such as the Bay Area. The Saint Francis Center, who has recently purchased a 25-unit apartment building in Redwood City and is now facing the $10 million cap, notes that SB 1115 will give much needed relief to nonprofits working to provide dignified, safe, clean, and affordable housing to low-income families.
Analysis Prepared by: Luke Reidenbach / APPR. / (916) 319-2081
Date of Hearing: June 25, 2018
ASSEMBLY COMMITTEE ON REVENUE AND TAXATION
Autumn R. Burke, Chairwoman
SBPCA Bill Id:SB 1115
Author:(Hill) – As Introduced Ver:February 13, 2018
Majority vote. Fiscal committee.
SENATE VOTE: 39-0
SUBJECT: Property taxation: welfare exemption: low income housing
SUMMARY: Eliminates the $10 million in assessed value statewide welfare exemption cap that applies to certain low-income rental housing owned and operated by non-profit organizations not receiving government financing or tax credits. Specifically, this bill:
- Eliminates the welfare exemption cap that limits the total exemption amount to $10 million in assessed value to non-publicly financed rental housing owned and operated by non-profit organizations for low-income households whose rent does not exceed specified amounts.
- Requires any outstanding qualified ad valorem tax in excess of the "total exemption amount limitation" ($10 million in assessed value), and related interest or penalty, which was levied or imposed on and after January 1, 2017, and before January 1, 2019, to be canceled if a qualified taxpayer files a "qualified claim" on "qualified property".
- Prohibits, on and after January 1, 2019, an escape assessment from being levied on qualified property if that amount would be subject to cancellation.
- Defines a "qualified taxpayer" as a taxpayer subject to the total exemption amount limitation.
- Defines "total exemption amount limitation" as the exemption amount limitation with respect to a single property or multiple properties that is specified in Revenue and Taxation Code (R&TC) Section 214(g)(1)(C) as it read before January 1, 2019. This amount is $10 million in assessed value.
- Defines a "qualified claim" as a claim for exemption that was filed for a qualified property with the assessor on and after January 1, 2017, and before January 1, 2019, for which the assessor granted a partial exemption.
- Defines a "qualified property" as property used exclusively for rental housing and related facilities where 90% or more of the occupants of the property are lower income households as prescribed by Health and Safety Code (H&SC) Section 50053, and that qualifies for exemption under R&TC Section 214(g)(1)(C).
- Excludes from a "qualified property" property owned by a limited partnership in which the managing general partner is an eligible nonprofit organization.
- Makes findings and declarations related to the cancellation of qualified outstanding ad valorem tax.
- Provides that if the Commission on State Mandates determines that this bill contains costs mandated by the state, reimbursement for those costs will be made as required by statute.
- Provides that no appropriation is made by this act and that no reimbursement is required of any local agency for any property tax revenues lost.
- Applies with respect to lien dates occurring on and after January 1, 2019.
EXISTING LAW:
- Authorizes the Legislature to exempt from taxation, in whole or in part, property used exclusively for religious, hospital, or charitable purposes, as specified. (California Constitution Article XIII, Section 4(b).) The Legislature has implemented this "welfare exemption" in R&TC Section 214.
- Exempts low-income rental housing owned and operated by nonprofit organizations, including limited partnerships in which the managing general partner is an eligible nonprofit corporation, as specified. (R&TC Section 214(g).)
- Defines "low-income" as households at 80% of area median income (AMI) adjusted for family size. (R&TC Section 214(g)(2)(C)(i).)
- Grants a partial welfare exemption, equal to the percentage of units serving lower income households as defined in H&SC Section 50053, to property used exclusively for rental housing and operated by nonprofit organizations, as specified, under either of the following conditions:
- The project is publicly financed with tax-exempt mortgage revenue bonds, general obligation bonds, grants, or low-income housing tax credits (LIHTCs); or,
- In the case of non-publicly financed affordable rental housing, 90% of units are affordable for lower income households with the nonprofit organization limited to an exemption of the first $10 million in assessed value.
- Requires organizations seeking the welfare exemption to do the following:
- File an enforceable and verifiable agreement with a public agency or other restriction, as specified, that provides that the units designated for use by lower income households are continuously available to or occupied by lower income households; and,
- Certify that the funds that would have been used to pay property taxes are used to maintain the affordability of, or reduce rents otherwise necessary for, the units occupied by lower income households.
- Requires, in the case of non-publicly financed low-income rental housing, a claim for the welfare exemption to be accompanied by a confidential affidavit, not subject to public disclosure, including a list of units occupied by lower income households for which the exemption is claimed, and the following non-personally identifiable information about the occupants:
- The actual household income of the occupant;
- The maximum rent that may be charged to the occupant; and,
- The actual rent charged to the occupant.
FISCAL EFFECT: According to the State Board of Equalization (BOE), there is no property tax revenue loss based on county assessor data reported to the BOE. However, Committee staff note that one organization will become subject to the cap due to its recent acquisition of a $9.5 million 25-unit apartment building. This information has yet to be reported to the BOE.
COMMENTS:
- The author has provided the following statement in support of this bill:
SB 1115 will aid nonprofits and religious organizations that provide affordable housing by eliminating the property tax exemption cap. Specifically it will help one noble charity in my district from day 1.
Nonprofits that do not receive any tax subsidies or grants from the State or federal government and provide affordable housing to low income families have a cap placed on the amount of property tax that may be exempted annually.
There are only 75 different properties in California owned by 25 nonprofits that are currently being reported to the Board of Equalization by the County Assessors that are subject to this cap. There is only one that is over the cap and it is in my district. With the ever-rising home prices in the Bay Area – this cap will continue to be an issue for this charity as they continue to do an outstanding job in private fundraising to provide more affordable housing for my constituents.
- The Saint Francis Center, which is the non-profit organization referenced above, in support of this bill explains the following:
Recently, Saint Francis Center was able to locate and purchase (off-market) a 25-unit apartment building in downtown Redwood City. We are so happy to add these units to serve our mission of assisting low-income families desperately in need of housing. However, with this purchase, we are now over the $10 million cap established with SB 996 and are subject to property taxes, though this building will, like all of our buildings, be 100% dedicated to extremely low, very low and low-income families…This bill will give much needed relief to nonprofits working diligently to provide dignified, safe, clean and affordable housing to extremely low and very-low income families.
- The County of San Mateo Board of Supervisors states in support of this bill:
With the median price of a single family home in San Mateo County topping $1.315 million and the average rent for a two-bedroom apartment at $3,453 per month, it has become vitally important to preserve and protect the County's affordable housing stock.
To this end, and to help non-profits that do private fundraising exclusively to provide affordable housing in extremely high rent and high property value areas such as our County, it is important to provide them with property tax relief so that these funds can be reinvested in the maintenance, operations and expansion of their housing services. The Saint Francis Center is one such example….The Saint Francis Center provides 87 units of affordable housing and, serves an estimated 435 extremely low-income residents, and goes the extra mile by providing much needed nutrition, clothing and educational assistance to the residents.
- Committee Staff Comments:
- The low-income rental housing property tax exemption: To qualify for the welfare exemption, the rental property must be financed with tax-exempt mortgage revenue bonds or general obligation bonds; local, state, or federal loans or grants; or low-income housing tax credits. Rental properties without government financing may also qualify for the exemption, but under more restrictive conditions. The rental property must be solely owned by a nonprofit organization (limited partnerships with a nonprofit organization serving as the managing general partner are ineligible) and lower income households must comprise 90% or more of its occupants. Additionally, there is a statewide cap on the total amount of exempt property from which a nonprofit organization may benefit, limited to the first $10 million of assessed value with respect to a single property or multiple properties for any fiscal year. Counties annually provide information to the BOE to track this limitation statewide.
- Background: Prior to 2000, nonprofit organizations that own rental housing could generally claim the welfare exemption merely on an "occupancy test" basis, which was 20% of the property's occupants were low income. After the Los Angeles Housing Project investigated some of the city's worst housing projects, they discovered abuse of the welfare exemption that enabled owners of substandard housing properties to benefit from this property tax exemption. Allegations were made that substandard housing owners were partnering with nonprofit organizations in a limited partnership as a ruse to obtain the welfare exemption, or were creating their own nonprofit organizations for the sole purpose of holding their properties. In response, AB 1559 (Wiggins), Chapter 927, Statutes of 1999, repealed the occupancy test and instead required owners to receive government financing or income tax credits to qualify for the welfare exemption as such properties would at least be subject to some level of government oversight, presumably resulting in less fraud and higher quality housing for tenants. AB 1559 also imposed more stringent documentation standards to substantiate that the rental housing is dedicated to low-income housing.
- Why was the exemption cap created? The reforms set forth by AB 1559 inadvertently resulted in revocation of the welfare exemption from otherwise deserving nonprofit organizations that had been providing affordable rental housing without government support. In response, AB 659 (Wiggins), Chapter 601, Statutes of 2000, reinstated the welfare exemption for non-publicly financed rental housing with the restrictions provided for in existing law today. First, limited partnerships were banned. Second, the lower income occupancy test basis was restored, but increased from a 20% to 90% threshold. Third, the exemption cap was created. The intent of the cap was to limit the tax benefit bestowed on "bad actors" who might still qualify for the welfare exemption by creating shell nonprofit organizations.
- What does this bill do? This bill has two main parts. First, this bill eliminates the exemption cap of the first $10 million in assessed value applicable to nonprofit organizations that own low-income rental housing. Second, this bill allows counties to cancel outstanding taxes on such property levied or imposed between January 1, 2017 and January 1, 2019.
- The exemption cap is unique: No other property eligible for the welfare exemption is subject to any exemption cap limiting the amount of the exemption provided. Additionally, no other property eligible for other types of exemptions (e.g., church, college, museum) is subject to any cap.
- Has the exemption cap been effective? Since its creation, few organizations have exceeded the cap. Most affordable housing projects receive government financing or tax credits. Those nonprofit organizations that have been impacted, or potentially impacted, have sought legislative intervention to increase the cap or to exclude the specific property from the cap. Committee staff notes that it appears the other safeguards (prohibiting limited partnerships and more stringent documentation) have proven effective. The exemption cap, however, has financially harmed those few nonprofits able to privately raise funds to provide housing and earn the support of their local community.
- Exemption cap monitoring statistics: According to data from BOE, which monitors the statewide exemption cap on behalf of county assessors, 26 nonprofit organizations in California provide affordable rental housing without government assistance. These 26 organizations own 76 properties of various types (single-family residences, multifamily residences, and apartment complexes) located across 11 counties.
- Eliminates need for future legislation: As property values continue to rise across California, it is possible that more and more properties may become impacted by the cap, especially in areas with high costs of living such as the San Francisco Bay Area. Eliminating the cap would allow nonprofit organizations able to privately raise funds to acquire and operate more affordable housing units without fear of breaching the cap.
- On the horizon – nonprofits addressing the homelessness challenge: Some nonprofits are stepping into addressing the homelessness crisis arguing that the greatest challenge for housing development is not in the market or near-market rate sector, but rather at the extremely low income and very low income. As such, these nonprofits are beginning to rehabilitate hotels and motels in urban areas and preparing to embark on other expanded housing efforts aimed at those persons with the greatest need - the homeless. These nonprofit entities are concerned that the modest exemption cap of $10 million in value will thwart this effort to use private dollars to assist in the homelessness crisis and associated threat to public health.
- Suggested amendment: Committee staff recommends the public purpose statement related to cancelling outstanding taxes be amended to eliminate any confusion with a separate welfare exemption provision for rental housing for elderly and disabled persons (RT&C Section 214(f)) to which neither this bill nor the exemption cap applies:
The Legislature finds and declares that Section 2 of this act fulfills a statewide public purpose because it addresses California’s serious shortage of affordable, decent, safe, and sanitary housing for persons and families of low or moderate income, including the elderly and handicapped, by providing necessary property tax relief for certain tax-exempt organizations so that these tax-exempt organizations can provide affordable housing for persons and families of low or moderate income.
- Related legislation:
- AB 3152 (Chui) would create a new property tax exemption under the welfare exemption for rental housing occupied by moderate-income households in high-cost counties if rents charged are 10% less than fair market rent for that county. AB 3152 was held on the Assembly Committee on Appropriations' Suspense file.
- SB 1056 (Beall) would create a new property tax exemption under the welfare exemption for Community Land Trust owned land intended to be used for future for-sale and rental affordable housing. SB 1056 will be heard by this Committee on
July 2, 2018. - AB 1193 (Gloria), Chapter 756, Statutes of 2017, extended the welfare exemption to units occupied by persons up to 140% of AMI if they were initially income qualified (80% of AMI) when they moved in so long as rent restrictions remain in effect.
- Previous legislation:
- SB 996 (Hill), Chapter 836, Statutes of 2016, effectively increased the cap from $2 million in assessed value ($20,000 in tax) to $10 million in assessed value ($100,000 in tax) and transitioned the measure of the cap from tax dollars to assessed value for administrative ease.
- SB 1284 (Lowenthal), Chapter 524, Statutes of 2008, excluded from the welfare exemption cap specified affordable housing properties acquired by a non-profit organization in Long Beach, as a result of mitigation efforts from the construction of the Century Freeway (I-105) in Los Angeles County.
- AB 659 (Wiggins), Chapter 601, Statutes of 2000, reinstated welfare exemption-eligibility for non-publicly financed low-income rental housing (excluding LPs) and created the welfare exemption cap applicable to this rental housing.
- AB 1559 (Wiggins), Chapter 927, Statutes of 1999, revoked the welfare exemption eligibility from low-income housing if it did not receive governmental financial assistance. AB 1559 also imposed higher documentation standards to substantiate that a rental property is dedicated to low-income housing.
- Related legislation:
REGISTERED SUPPORT / OPPOSITION:
Support
AIDS Healthcare Foundation
California Community Land Trust Network
California Housing Partnership
Irvine Community Land Trust
Saint Francis Center
San Mateo County Board of Supervisors
Opposition
None on file
Analysis Prepared by: Rose Marie Kinnee / REV. & TAX. / (916) 319-2098
Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | SB |
THIRD READING
Bill No: SB 1115
:
SENATE GOVERNANCE & FIN. COMMITTEE: 6-0, 4/4/18
AYES: McGuire, Nguyen, Beall, Hernandez, Lara, Moorlach
NO VOTE RECORDED: Hertzberg
SENATE APPROPRIATIONS COMMITTEE: 7-0, 5/25/18
AYES: Lara, Bates, Beall, Bradford, Hill, Nielsen, Wiener
DIGEST:
This bill eliminates the current cap on the amount of the welfare exemption for non-publicly financed affordable housing.
Existing law:
- Provides that all property is taxable unless explicitly exempted by the Constitution or federal law (California Constitution, Article XIII).
- Allows the Legislature to exempt property used for charitable purposes, and owned by non-profit entities organized and operated for charitable purposes, such as universities, hospitals, and libraries (California Constitution, Article XIII, Sections Four and Five). The Legislature enacted this exemption, commonly known as the “welfare exemption.”
- Limits the maximum amount of any ad valorem tax on real property at 1% of full cash value, and directs assessors to only reappraise property when newly constructed, or when ownership changes (Proposition 13, 1978).
- Allows the welfare exemption for rental housing when the housing is financed by tax-exempt mortgage revenue bonds; general obligation bonds; federal, state, or local grants; or federal low-income housing tax credits, pursuant to specific requirements.
- Allows, additionally, non-publicly financed affordable housing to be exempt if:
- The property is managed solely by a non-profit organization, specifically excluding limited partnerships, and
- 90% of occupants are of low- or very-low income.
- The property is enforceably restricted for low-income housing, and rents do not exceed those prescribed in deed restrictions, and
- The property owner certifies that funds that would have been used to pay property taxes are used to maintain the affordability of the units or reduce rents.
- Caps the non-publicly financed exemption at $10 million in value statewide per owner.
This bill:
- Deletes the current $10 million cap on valuation for non-publicly financed housing owned and operated by a non-profit organization for purposes of the welfare exemption from property tax.
- Applies this change to lien dates on or after January 1, 2019.
- Provides a process for taxpayers to file a claim to have any outstanding taxes or escape assessments cancelled.
- Makes legislative findings and declarations supporting its purposes.
Background
Prior to 1999, rental housing owners could claim a welfare exemption from property tax for low-income housing if 20% of the property’s residents were low-income. After the Los Angeles Housing Project investigated some of the city’s worst housing projects, they discovered that tax exempt property owners were not providing basic maintenance to housing that qualified them for the exemption from property tax. Responding to the investigation, the Legislature enacted AB 1559 (Wiggins, Chapter 927, Statutes of 1999), which repealed the occupancy test, instead requiring owners to receive public financing in the forms listed above for the project to claim the welfare exemption, in addition to the above requirements. However, AB 1559 revoked the exemption for many worthy properties that weren’t publicly financed, so the Legislature subsequently enacted AB 659 (Wiggins, Chapter 601, Statutes of 2000), which further refined the law to:
- Reenact the occupancy threshold, but increased to 90%,
- Cap the exemption amount to $20,000 in tax for all properties the taxpayer owns in the state, and
- Require the property be managed solely by a non-profit organization, specifically excluding limited partnerships, to be eligible for the exemption.
Since 2000, the value of housing increased, compelling some non-profits to pay taxes on amounts that exceeded the $20,000 cap, and discouraging them from acquiring rental housing in the hopes of preserving existing affordable units in their areas. In response, the Legislature enacted SB 996 (Hill, Chapter 836, Statutes of 2016), which:
- Quintupled the cap, and revised it to instead apply to the property’s value, not the tax paid, with the new threshold at $10 million of assessed value,
- Created a process for taxpayers to file a claim to cancel any outstanding taxes or escape assessments due on values that exceeded the previous cap, and
- Required property owners claiming the welfare exemption to provide specified information regarding the household income of and the rent charged to an occupant of an exempt unit.
However, charities still must pay tax on any amount of value that exceeds the $10 million cap, which applies to all of its properties statewide. As a result, the cap deters charities that want to construct or acquire additional affordable housing, especially those in areas of the state with higher housing values.
FISCAL EFFECT: Appropriation: Fiscal Com.: Local:
According to the Senate Appropriations Committee, “The Board of Equalization (BOE) indicates that it would incur minor and absorbable administrative costs to update claim forms, Property Tax Rule 140, and its Assessors’ Handbook. BOE indicates that, based on county assessor data, no organizations currently appear to be over the $10 million current-law cap. However, the bill would lead to a revenue loss over time, as (1) assessed values of organizations’ current holdings exceed $10 million over time (resulting from the annual inflation factor of up to 2 percent), and (2) to the extent organizations acquire or construct additional property that would be subject to the $10 million cap. Lower local property tax revenues lead to increased General Fund Proposition 98 spending by up to roughly 50 percent (the exact amount depends on the specific amount of the annual Proposition 98 guarantee, which in turns depends upon a variety of economic, demographic and budgetary factors). Under the California Constitution, this bill’s imposing of new duties on local county officials related to the real property tax assessment process could be subject to reimbursement by the State. The magnitude of these potential costs is unknown.”
AIDS Healthcare Foundation
Irvine Community Land Trust
San Mateo County Board of Supervisors
St. Francis Center
OPPOSITION: (Verified 5/25/18)
None received
ARGUMENTS IN SUPPORT: According to the author, “According to the author, “Four out of the five metropolitan areas with the least affordable rental markets nationwide continue to be in California. California continues to have a very serious shortage of affordable housing. SB 1115 will aid non-profits and religious organizations by eliminating the property tax exemption cap on their affordable housing properties. It will aid them by providing property tax relief to certain non-profits so that these tax-exempt organizations can continue to provide more affordable housing for low income people and families. By removing the property tax exemption cap – charities in my district can continue to purchase, rehab and provide more affordable, safe and dignified housing to my district’s most neediest families.”
5/26/18 15:26:19
**** END ****
SENATE COMMITTEE ON APPROPRIATIONS
Senator Ricardo Lara, Chair
2017 - 2018 Regular Session
SB 1115 (Hill) - Property taxation: welfare exemption: low income housing
Version: February 13, 2018 | Policy Vote: GOV. & F. 6 - 0 |
Urgency: No | Mandate: Yes |
Hearing Date: April 16, 2018 | Consultant: Robert Ingenito |
This bill meets the criteria for referral to the Suspense File.
Bill Summary:
SB 1115 would eliminate the current exemption cap applicable to non-publicly financed affordable housing.
Fiscal Impact:
- The Board of Equalization (BOE) indicates that it would incur minor and absorbable administrative costs to update claim forms, Property Tax Rule 140, and its Assessors’ Handbook.
- BOE indicates that, based on county assessor data, no organizations currently appear to be over the $10 million current-law cap. However, the bill would lead to a revenue loss over time, as (1) assessed values of organizations’ current holdings exceed $10 million over time (resulting from the annual inflation factor of up to 2 percent), and (2) to the extent organizations acquire or construct additional property that would be subject to the $10 million cap. Lower local property tax revenues lead to increased General Fund Proposition 98 spending by up to roughly 50 percent (the exact amount depends on the specific amount of the annual Proposition 98 guarantee, which in turns depends upon a variety of economic, demographic and budgetary factors).
- Under the California Constitution, this bill’s imposing of new duties on local county officials related to the real property tax assessment process could be subject to reimbursement by the State. The magnitude of these potential costs is unknown.
Background: All property in California is taxable unless explicitly exempted. Specifically, the Legislature may exempt property owned by nonprofit entities organized and operated for charitable purposes, such as universities, hospitals, and libraries (known as the “welfare exemption”). The welfare exemption currently results in $3 billion in annual foregone local property tax revenues.
The welfare exemption includes property used exclusively for rental housing, if (1) specified financing mechanisms finance the housing, (2) the property is restricted for low-income housing, and rents do not exceed specified levels, and (3) the property owner certifies that funds that would have been used to pay property taxes are used to maintain the affordability of the units or reduce rents.
In 1999, the Legislature set a cap equivalent to $2 million in assessed value on statewide holdings for certain low-income rental housing owned and operated by eligible nonprofit organizations. It did so as part of a series of reforms that responded to an investigation that showed tax-exempt property owners were not providing basic maintenance for their housing projects. Thus, the cap was instituted to address the exemption’s misuse as it applied to low-income housing.
As assessed valuation in the State generally rose in the ensuing years, (1) some non-profits were required to pay taxes on property amounts that exceeded the cap, and (2) other groups were discouraged from constructing or acquiring rental housing, especially those regions of the state with higher property values. Other reforms adopted as part of the package, such as making the exemption contingent upon deed restrictions binding rents, and limiting the exemption solely to non-profit organizations owning the units, appear to have succeeded. Consequently, the cap could hinder nonprofit organizations that own, or want to purchase, affordable housing in their communities, and can be especially burdensome for organizations operating statewide. Additionally, no other organizations claiming the welfare exemption (such as hospitals, churches, and universities) are subject to a similar cap.
In response, the Legislature enacted SB 996 (Hill, 2016), which among other things raised the cap from $2 million to $10 million.
Bill Summary: This bill would delete the welfare exemption from property tax’s current $10 million cap on valuation for non-publicly financed housing owned and operated by a non-profit organization. The change would be effective for lien dates on or after January 1, 2019. The bill provides a process for taxpayers to file a claim to have any outstanding taxes or escape assessments cancelled.
Staff Comments: BOE indicates that, for 2016-17, 23 nonprofit organizations (owning a total of 55 low-income rental housing properties across ten counties) received exemptions on property that counted towards the $10 million exemption cap. Three organizations, located in Los Angeles, Marin, and Monterey Counties, exceeded the cap and were partially taxable. BOE has collected partial information thus far for 2017-18; sixteen counties have reported thus far. Of these counties, seven reported that they granted exemptions to properties owned by 22 nonprofit organizations subject to the exemption cap. Of these 22 organizations, none of the organizations exceeded the cap.
The revenue loss resulting from the bill would emerge and grow (1) if organizations acquire more property subject to the cap, or (2) if assessed values over time exceed $10 million due to the application of the annual inflation factor (up to 2 percent). As an example, assuming the full two percent inflation factor, property assessed at $10 million would grow to $20 million in about 37 years. The resulting loss in property tax revenue relative to current law would be about $100,000, half of which could result in increased Proposition 98 General Fund spending.
-- END --
SENATE COMMITTEE ON GOVERNANCE AND FINANCE
Senator Mike McGuire, Chair
2017 - 2018 Regular
Bill No: | SB 1115 | Hearing Date: | 4/4/18 |
Author: | Hill | Tax Levy: | No |
Version: | 2/13/18 | Fiscal: | Yes |
Consultant: | Grinnell | ||
Property taxation: welfare exemption: low income housing
Eliminates the current cap on the amount of the welfare exemption for non-publicly financed affordable housing.
Background
The California Constitution provides that all property is taxable unless explicitly exempted by the Constitution or federal law, but also allows the Legislature to exempt property used for charitable purposes, and owned by non-profit entities organized and operated for charitable purposes, such as universities, hospitals, and libraries. The Legislature enacted this exemption, commonly known as the “welfare exemption.” The welfare exemption has a similar policy genesis as non-profit status for charitable groups: revenues paid in tax to the government divert needed resources away from the organization’s good works. According to the Legislative Analyst’s Office, local agencies statewide forego $3 billion annually in property tax revenues from welfare exempt properties.
The welfare exemption includes property used exclusively for rental housing, if:
- Tax-exempt mortgage revenue bonds; general obligation bonds; federal, state, or local grants; or federal low-income housing tax credits finance the housing,
- The property is enforceably restricted for low-income housing, and rents do not exceed those prescribed in deed restrictions, and
- The property owner certifies that funds that would have been used to pay property taxes are used to maintain the affordability of the units or reduce rents.
Prior to 1999, rental housing owners could claim a welfare exemption from property tax for low-income housing if 20% of the property’s residents were low-income. After the Los Angeles Housing Project investigated some of the city’s worst housing projects, they discovered that tax exempt property owners were not providing basic maintenance to housing that qualified them for the exemption from property tax. Responding to the investigation, the Legislature enacted AB 1559 (Wiggins, 1999), which repealed the occupancy test, instead requiring owners to receive public financing in the forms listed above for the project to claim the welfare exemption, in addition to the above requirements. However, AB 1559 revoked the exemption for many worthy properties that weren’t publicly financed, so the Legislature subsequently enacted AB 659 (Wiggins, 2000), which further refined the law to:
- Reenact the occupancy threshold, but increased to 90%,
- Cap the exemption amount to $20,000 in tax for all properties the taxpayer owns in the state, and
- Require the property be managed solely by a non-profit organization, specifically excluding limited partnerships, to be eligible for the exemption.
Since 2000, the value of housing has increased, compelling some non-profits to pay taxes on amounts that exceed the $20,000 cap, and discouraging other groups from acquiring rental housing in the hopes of preserving existing affordable units in their areas. In response, the Legislature enacted SB 996 (Hill, 2016), which:
- Quintupled the cap, and revised it to instead apply to the property’s value, not the tax paid, with the new threshold at $10 million of assessed value,
- Created a process for taxpayers to file a claim to cancel any outstanding taxes or escape assessments due on values that exceeded the previous cap, and
- Required property owners claiming the welfare exemption to provide specified information regarding the household income of and the rent charged to an occupant of an exempt unit.
However, charities must pay tax on any amount of value that exceeds the $10 million cap, which applies to all of its properties statewide. As a result, the cap deters charities that want to construct or acquire additional affordable housing, especially those in areas of the state with higher housing values. The Saint Francis Center in San Mateo County wants to eliminate the cap, and cancel any taxes paid on valuations above SB 996’s revised cap.
Proposed Law
Senate Bill (SB) 1115 deletes the welfare exemption from property tax’s current $10 million cap on valuation for non-publicly financed housing owned and operated by a non-profit organization. The measure applies this change to lien dates on or after January 1, 2019. The bill provides a process for taxpayers to file a claim to have any outstanding taxes or escape assessments cancelled.
SB 1115 also makes legislative findings and declarations supporting its purposes.
State Revenue Impact
Pending.
Comments
1. Purpose of the bill. According to the author, “Four out of the five metropolitan areas with the least affordable rental markets nationwide continue to be in California. California continues to have a very serious shortage of affordable housing. SB 1115 will aid non-profits and religious organizations by eliminating the property tax exemption cap on their affordable housing properties. It will aid them by providing property tax relief to certain non-profits so that these tax-exempt organizations can continue to provide more affordable housing for low income people and families. By removing the property tax exemption cap – charities in my district can continue to purchase, rehab and provide more affordable, safe and dignified housing to my district’s most neediest families.”
2. As time goes by. When the Legislature set the $20,000 cap in 2000, it was part of a series of reforms that responded to an investigation that showed tax exempt property owners were not providing basic maintenance for its housing projects. Other reforms adopted as part of the package, such as making the exemption contingent upon deed restrictions binding rents, and limiting the exemption solely to non-profit organizations owning the units, should have chased out any potential bad actors over the past seventeen years. BOE monitors the statewide cap, as it receives annual welfare exemption filings filed with assessors, to ensure that owners don’t abuse the public financing requirement by creating shell non-profit organizations. In 2015, BOE reported that few non-profit organizations that own low-income rental housing have exceeded the cap, which the Legislature quintupled that year. BOE reports that no organizations in the state own housing subject to the expanded limit. However, the cap deters non-profit organizations that currently own property subject to the cap, but want to purchase additional affordable housing, as the exemption wouldn’t apply above the $10 million valuation limit. Additionally, the Legislature already disconnected the cap for the Long Beach Affordable Housing Coalition’s purchase of specified properties in Los Angeles County (SB 1284, Lowenthal, 2008). Lastly, no other organizations claiming the welfare exemption are subject to a similar cap, such as hospitals and universities.
3. Information. When the Legislature quintupled the cap in 2015, it required any non-profit organization qualifying for the exemption to provide additional information with their annual claim. The measure required the non-profit organization to annually provide non-personally identifiable information about the occupants which includes the actual household income of the occupant, the maximum rent that may be charged to the occupant, and the actual rent charged to the occupant. As a result, assessors now have more information to ensure that the welfare exemption from property tax for affordable housing is correctly administered.
4. Mandate. The California Constitution requires the state to reimburse local governments for the costs of new or expanded state mandated local programs. Because SB 1115 changes the manner in which assessors value real property, and creates a claim process, Legislative Counsel says that it imposes a new state mandate. The measure states that should the Commission on State Mandates determine that the bill imposes a reimbursable mandate, reimbursement must be made pursuant to existing statutory provisions. Additionally, the bill provides that the state shall not reimburse local agencies for any property tax revenue losses resulting from its expanded welfare exemption.
Support and Opposition
(4/2/18)
Support: St. Francis Center, San Mateo County Board of Supervisors.
Opposition: Unknown.
-- END --
Discussed in Hearing
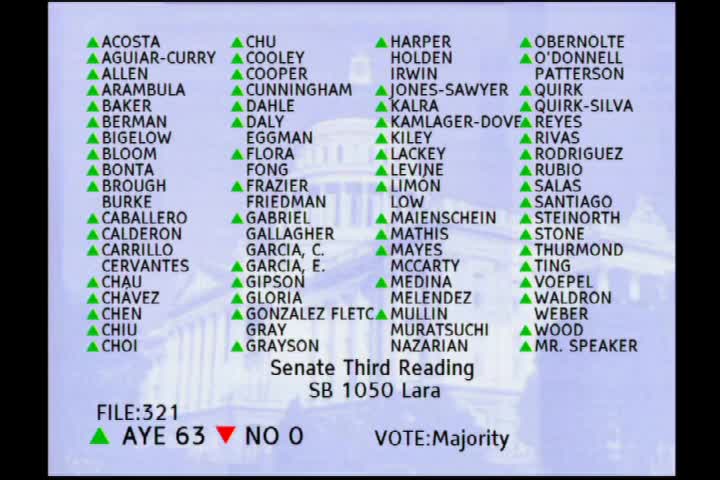 1MIN
Assembly Floor
 1H
Assembly Standing Committee on Appropriations
 2MIN
Senate Standing Committee on Governance and Finance
Bill Author
Bill Co-Author(s):