AB 691: Personal Income Tax Law: credits: pet adoption and medical expenses.
- Session Year: 2025-2026
- House: Assembly
- Latest Version Date: 2025-03-13
Current Status:
Failed
(2025-06-05: From committee: Without further action pursuant to Joint Rule 62(a).)
Introduced
In Committee
Awaiting First Chamber Vote
Passed First Chamber
In Committee
Awaiting Second Chamber Vote
Passed Second Chamber
Enacted
What does this bill do?
The bill creates a temporary California personal income tax credit for people who adopt a pet from a qualifying rescue during tax years 2025 through 2029, covering up to $250 in adoption fees and up to $500 in unreimbursed veterinary costs in the first 12 months after adoption. Each taxpayer may claim the adoption fee credit only once in their life and the medical-expense credit only for one adopted pet (spouses have separate limits); claimants must keep receipts and a sworn declaration for the Franchise Tax Board, which must report annually to the Legislature on credit use.
The summary is provided by generative AI which can make mistakes. For original language, please view the details in the table below.
The Personal Income Tax Law allows various credits against the taxes imposed by that law.
This bill, for taxable years beginning on or after January 1, 2025, and before January 1, 2030, would allow a credit against the taxes imposed by that law for the qualified pet adoption costs, as defined, not to exceed $250, and the qualified pet medical expenses, as defined, not to exceed $500, paid or incurred during the taxable year. The bill would prohibit a claim for qualified pet adoption costs for more than one qualified pet, as defined, during the life of the taxpayer. The bill would additionally prohibit a claim for qualified pet medical expenses with regard to more than one qualified pet during the life of the taxpayer, as provided. In the case of spouses filing a joint return, the bill would apply these restrictions to each spouse separately. The bill would require a taxpayer to provide all information necessary to administer this credit, upon request and in the form and manner provided by the Franchise Tax Board, including, but not limited to, a declaration under penalty of perjury that the taxpayer has not previously claimed the credit. By expanding the scope of the crime of perjury, this bill would impose a state-mandated local program.
Existing law requires any bill authorizing a new tax expenditure to contain, among other things, specific goals that the tax expenditure will achieve, detailed performance indicators, and data collection requirements.
This bill also would include additional information required for any bill authorizing a new tax expenditure.
The California Constitution requires the state to reimburse local agencies and school districts for certain costs mandated by the state. Statutory provisions establish procedures for making that reimbursement.
This bill would provide that no reimbursement is required by this act for a specified reason.
This bill would take effect immediately as a tax levy.
Existing law requires that notice of impending property tax default be published according to specified procedures.This bill would make nonsubstantive changes to this provision.Existing law requires that notice of impending property tax default be published according to specified procedures.
This bill would make nonsubstantive changes to this provision.
(a)For taxable years beginning on or after January 1, 2025, and before January 1, 2030, there shall be allowed as a credit against the net tax, as that term is defined in Section 17039, an amount equal to the following:
(1)The qualified pet adoption costs paid or incurred by the taxpayer during the taxable year, not to exceed two hundred fifty dollars ($250).
(2)The qualified pet medical expenses paid or incurred by the taxpayer during the taxable year, not to exceed five hundred dollars ($500).
(b)For purposes of this section the following definitions shall apply:
(1)Qualified animal rescue organization means a public animal control agency or shelter, humane society shelter, or nonprofit rescue group that is exempt from federal income taxation pursuant to Section 501(c)(3) of the Internal Revenue Code that is domiciled in this state and primarily engaged in rescuing and placing animals in permanent homes.
(2)Qualified pet means a dog, cat, or other companion animal adopted from a qualified animal rescue organization that is not used by the taxpayer in a trade or business or for the production of income.
(3)Qualified pet adoption costs means the costs paid to a qualified animal rescue organization as adoption fees to secure the adoption of qualified pet.
(4)Qualified pet medical expenses means unreimbursed amounts paid for veterinary care, including vaccinations, spaying or neutering, and other necessary medical treatments for a qualified pet in the first 12 months following adoption.
(c)(1)(A)The credit allowed pursuant to paragraph (1) of subdivision (a) shall not be claimed more than once during the life of the taxpayer.
(B)The credit allowed pursuant to paragraph (2) of subdivision (a) shall not be claimed with regard to qualified pet medical expenses for more than one qualified pet during the life of the taxpayer, and shall not exceed five hundred dollars ($500) cumulatively for that qualified pet.
(2)In the case of spouses filing a joint return, the limitations described in paragraph (1) shall apply to each spouse separately.
(d)The taxpayer shall provide, upon request and in the form and manner prescribed by the Franchise Tax Board, all documentation that the Franchise Tax Board determines necessary to administer this section, including, but not limited to, the following:
(1)Receipt or certification from the qualified animal rescue organization specifying the adoption date, pet description, and adoption fee paid.
(2)Receipts or invoices from a licensed veterinarian detailing the expenses incurred within the first 12 months following adoption.
(3)A declaration under penalty of perjury that the taxpayer has not previously claimed the respective credit under this section in any prior taxable year, except as provided in paragraph (2) of subdivision (c).
(e)(1)For purposes complying with Section 41, the Legislature finds and declares the following:
(A)The specific purpose of the credit authorized by this section is to encourage the adoption of pets from rescue organizations.
(B)The performance indicators for the Legislature to use in determining whether the credit achieves its stated goal are the number of taxpayers allowed a credit and the total dollar value of credits allowed.
(2)(A)On or before December 1, 2026, and annually thereafter, the Franchise Tax Board shall submit a report to the Legislature, in compliance with Section 9795 of the Government Code, detailing the number of taxpayers allowed a credit pursuant to this section and the total dollar value of credits allowed.
(B)The disclosure requirements of this paragraph shall be treated as an exception to Section 19542.
(f)This section shall remain operative only until December 1, 2030, and as of that date is repealed.
SEC. 2.No reimbursement is required by this act pursuant to Section 6 of Article XIIIB of the California Constitution because the only costs that may be incurred by a local agency or school district will be incurred because this act creates a new crime or infraction, eliminates a crime or infraction, or changes the penalty for a crime or infraction, within the meaning of Section 17556 of the Government Code, or changes the definition of a crime within the meaning of Section 6 of Article XIIIB of the California Constitution.
SEC. 3.This act provides for a tax levy within the meaning of Article IV of the California Constitution and shall go into immediate effect.
SECTION 1.Section 3353 of the Revenue and Taxation Code is amended to read:3353.Publication shall be made pursuant to Section 6063 of the Government Code in the county. If no newspaper of general circulation is published in the county, then the publication shall be made by posting in three public places in the county. The cost of publication shall be not more than the rate fixed by the board of supervisors for other county advertising.Publication shall be made pursuant to Section 6063 of the Government Code in the county. If no newspaper of general circulation is published in the county, then the publication shall be made by posting in three public places in the county. The cost of publication shall be at no not more than the rate fixed by the board of supervisors for other county advertising.
|
Date
|
Status
|
|---|---|
| Jun 5, 2025 | From committee: Without further action pursuant to Joint Rule 62(a). |
| May 5, 2025 | In committee: Set, final hearing. Held under submission. |
| Apr 21, 2025 | In committee: Set, second hearing. Referred to suspense file. |
| Apr 7, 2025 | In committee: Set, first hearing. Hearing canceled at the request of author. |
| Mar 17, 2025 | Re-referred to Com. on REV. & TAX. |
| Mar 13, 2025 | From committee chair, with author's amendments: Amend, and re-refer to Com. on REV. & TAX. Read second time and amended. |
| Mar 13, 2025 | Referred to Com. on REV. & TAX. |
| Feb 15, 2025 | From printer. May be heard in committee March 17. |
| Feb 14, 2025 | Read first time. To print. |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| Amy's Purpose | ** Support | |
| Best Friends Animal Society | ** Support | |
| California Tax Reform Association | ** Against | |
| City Of La Quinta | ** Support | |
| San Diego Humane Society And Spca | ** Support | |
| Social Compassion In Legislation | ** Support |
Date of Hearing: May 5, 2025
ASSEMBLY COMMITTEE ON REVENUE AND TAXATION
Mike Gipson, Chair
ABPCA Bill Id:AB 691 (
Author:Wallis) – As Amended Ver:March 13, 2025
SUSPENSE
Majority vote. Tax levy. Fiscal committee.
SUBJECT: Personal Income Tax Law: credits: pet adoption and medical expenses
SUMMARY: Allows, under the Personal Income Tax (PIT) Law, a credit of up to $750 for qualified pet adoption costs and qualified pet medical expenses, as specified. Specifically, this bill:
- Allows a credit for taxable years beginning on or after January 1, 2025, and before January 1, 2030, to a taxpayer in an amount equal to the following:
- The "qualified pet adoption costs" paid or incurred by the taxpayer during the taxable year, up to $250; and,
- The "qualified pet medical expenses" paid or incurred by the taxpayer during the taxable year, up to $500.
- Defines the following terms:
- "Qualified pet adoption costs" are the costs paid to a qualified animal rescue organization as adoption fees to secure the adoption of qualified pet;
- "Qualified pet medical expenses" are unreimbursed amounts paid for veterinary care, including vaccinations, spaying or neutering, and other necessary medical treatments for a qualified pet in the first 12 months following adoption;
- "Qualified animal rescue organization" is a public animal control agency or shelter, humane society shelter, or nonprofit rescue group that is exempt from federal income taxation pursuant to Internal Revenue Code (IRC) Section 501(c)(3) that is domiciled in this state and primarily engaged in rescuing and placing animals in permanent homes; and,
- "Qualified pet" is a dog, cat, or other companion animal adopted from a qualified animal rescue organization that is not used by the taxpayer in a trade or business or for the production of income.
- Limits the availability of the credit as follows:
- The adoption credit cannot be claimed more than once during the life of the taxpayer;
- The medical expense credit cannot be claimed with regard to qualified pet medical expenses for more than one qualified pet during the life of the taxpayer, and cannot exceed $500 cumulatively for that qualified pet; and,
- In the case of spouses filing a joint return, the limits described above apply to each spouse separately.
- Requires the taxpayer to provide, upon request and in the form and manner prescribed by the Franchise Tax Board (FTB), all documentation that the FTB determines is necessary to administer this credit, including but not limited to the following:
- Receipt or certification from the qualified animal rescue organization specifying the adoption date, pet description, and adoption fee paid;
- Receipts or invoices from a licensed veterinarian detailing the expenses incurred within the first 12 months following adoption; and,
- A declaration under penalty of perjury that the taxpayer has not previously claimed the respective credit in any prior taxable year, except as otherwise provided.
- Finds and declares the following for the purposes of satisfying the requirements of Revenue and Taxation Code (R&TC) Section 41:
- The specific purpose of the credit is to encourage the adoption of pets from rescue organizations;
- The performance indicators for the Legislature to use in determining whether the credit achieves its stated goal are the number of taxpayers allowed a credit and the total dollar value of credits allowed; and,
- Requires the FTB, on or before December 1, 2026, and annually thereafter, to submit a report to the Legislature detailing the number of taxpayers allowed a credit and the total dollar value of credits allowed.
- Takes immediate effect as a tax levy.
- Sunsets the credit's statutory provisions on December 1, 2030.
EXISTING LAW:
- Allows various tax credits under the PIT Law. These credits are generally designed to encourage socially beneficial behavior or to provide relief to taxpayers who incur specified expenses.
- Requires any bill authorizing a new credit to contain all of the following:
- Specific goals, purposes, and objectives that the tax credit will achieve;
- Detailed performance indicators for the Legislature to use when measuring whether the tax credit meets the goals, purposes, and objectives stated in the bill; and,
- Data collection requirements to enable the Legislature to determine whether the tax credit is meeting, failing to meet, or exceeding those specific goals, purposes, and objectives. The requirements shall include the specific data and baseline measurements to be collected and remitted in each year the credit is in effect, for the Legislature to measure the change in performance indicators, and the specific taxpayers, state agencies, or other entities required to collect and remit data. (R&TC Section 41.)
- Allows a taxpayer to make a contribution to the Prevention of Animal Homelessness and Cruelty Voluntary Tax Contribution Fund on their PIT return, which supports the Pet Lover's Fund grant program. (R&TC Section 18901.9 et seq.)
FISCAL EFFECT: The FTB estimates General Fund revenue losses of $95 million in fiscal year (FY) 2025-26, $60 million in FY 2026-27, and $60 million in FY 2027-28.
COMMENTS:
- The author has provided the following statement in support of this bill:
California desperately needs AB 691 because so many people who’d love to adopt a pet are stopped by the high costs—$50 to $200 just to bring them home, plus $300 or more for vet bills right off the bat—leaving countless dogs and cats stuck in packed shelters, where over 100,000 are put down every year. This bill’s tax credits—up to $250 for adoption fees and $500 for those first vet visits—would make it easier for everyday Californians to say yes to a furry friend, easing the heartbreak of overcrowded shelters and saving lives.
- Writing in support of this bill, Social Compassion in Legislation notes, in part:
The lack of access to affordable veterinary care has contributed to many animals not being spayed or neutered, which has exacerbated the pet overpopulation problem. Meanwhile, it is estimated that our local and state governments spend over $400 million on operating animal shelters. That figure does not include the incalculable millions spent by nonprofit rescue organizations who pull dogs, cats, and various other animals from shelters before they are euthanized in order to save their lives and find them a loving home. Currently, the only ongoing funding for free or low-cost spay and neuter services are the approximately $400,000 granted out annually through the Pet Lover's License Plate Fund for spay and neuter. Much more is needed.
By allowing Californians a modest tax credit when they choose to adopt from our animal shelters rather than buy from a breeder, and for veterinary medical costs, we are supporting our state's animal shelters and pet owners give their beloved pets the medical attention they deserve.
- Writing in opposition to this bill, the California Tax Reform Association notes, in part:
The decision to adopt a pet is a personal decision which is based on many factors, not on the support by the state through tax credits. Since the costs of maintaining pets far exceed the tax credit in this measure, these decisions will always be made independently of the tax incentive. Thus, this tax credit is not a good use of money for the state of California, with losses to education and the general fund. In addition, this measure adds substantial complexity in its need for enforcement and verification to a tax code which is already overly complex to administer fairly.
- Committee Staff Comments:
- What is a "tax expenditure"? Existing law provides various credits, deductions, exclusions, and exemptions for particular taxpayer groups. In the late 1960s, U.S. Treasury officials began arguing that these features of the tax law should be referred to as "expenditures" since they are generally enacted to accomplish some governmental purpose and there is a determinable cost associated with each (in the form of foregone revenues).
As the Department of Finance notes in its annual Tax Expenditure Report, there are several key differences between tax expenditures and direct expenditures. First, tax expenditures are typically reviewed less frequently than direct expenditures. Second, there is generally no control over the amount of revenue losses associated with any given tax expenditure. Finally, it should also be noted that, once enacted, it takes a two-thirds vote to rescind an existing tax expenditure absent a sunset date. This effectively results in a "one-way ratchet" whereby tax expenditures can be conferred by majority vote, but cannot be rescinded, irrespective of their efficacy or cost, without a supermajority vote.
- What problem is this bill attempting to solve? According to the author and supporters, this bill seeks to address overcrowding in animal shelters by encouraging pet adoption and defraying some of the medical costs that might be associated with pet ownership in the first year. While there are likely many causes for this phenomenon, some have suggested that the COVID-19 pandemic and associated recovery played a large role. Animal shelters have seen an uptick in people surrendering or abandoning their pets as work-from-home policies have been curtailed and concerns about the cost of living have risen. According to Shelter Animals Count's 2023 annual analysis report:
In 2023, over 6.5 million animals (3.3 million cats and 3.2 million dogs) entered animal shelters and rescue organizations in the U.S., about the same number as 2022 and up slightly from 2021. Of these, 48% came in as strays, and 25% were surrendered by their owners. Shelters across the country are full, and are now entering their fourth year of having too many animals and not enough adoptions - especially for dogs. Because many shelters and rescues are operating at or over capacity, the number of surrenders and overall intake is likely lower than it would be if space were available.[1]
- An incentive or a reward? Typically, tax credits are provided prospectively as a matter of legislative grace to encourage taxpayers to behave in ways they might not absent a financial incentive. This credit, in turn, is intended to encourage the adoption of pets from rescue organizations. As currently drafted, this bill provides the credit for taxable years beginning on or after January 1, 2025, meaning that taxpayers could benefit from this bill for actions they have already taken without any incentive. The author may wish to amend this bill to allow the credit prospectively, beginning on January 1, 2026.
- Appropriately targeted? The term "taxpayer" includes individuals, fiduciaries, estates, or and partnerships. If the author intends that the credit will only apply to individuals, the term "taxpayer" could be replaced with the term "individual". Additionally, as currently drafted, the credit does not contain income restriction provisions, meaning high-income individuals could receive this benefit while also being able to afford the costs associated with pet adoption. If the author's intent is to incentivize pet adoption among those who may struggle to afford the associated costs, the author may wish to amend this bill to limit the credit based on the taxpayer's annual adjusted gross income.
- Committee's tax expenditure policy: Both R&TC Section 41 and Committee policy require any tax expenditure bill to outline specific goals, purposes, and objectives that the tax expenditure will achieve, along with detailed performance indicators for the Legislature to use when measuring whether the tax expenditure meets those stated goals, purposes, and objectives. A tax expenditure bill will not be eligible for a Committee vote unless it has complied with these requirements. In its current form, this bill states that the credit is to encourage the adoption of pets from rescue organizations.
In addition to the R&TC Section 41 requirements, this Committee's policy also requires that all tax expenditure proposals contain an appropriate sunset provision to be eligible for a vote. According to this policy, an "appropriate sunset provision" means five years, except in the case of a tax expenditure measure providing relief to California veterans, in which case "appropriate sunset provision" shall mean ten years. This bill, as currently drafted, complies with the Committee's policy on sunset dates. - Report timeline: This bill would require the FTB to submit a report to the Legislature detailing the number of taxpayers that receive a credit and the total dollar amount of credits allowed by December 1, 2026. If the author's intent is to review a report that contains complete information for the 2025 taxable year, the FTB recommends that the reporting due date be extended to July 1, 2027. The FTB needs at least six to eight months to complete return processing and to compile the needed data to prepare a report.
- Prior legislation:
- AB 1983 (Maienschein), Chapter 234, Statutes of 2024, authorized the addition of the Prevention of Animal Homelessness and Cruelty Voluntary Tax Contribution Fund on the PIT return.
- AB 514 (Joe Patterson) of the 2023-24 Legislative Session, would have allowed a refundable credit of up to $1,500 for a taxpayer that adopted one or more dogs that previously were in service with a law enforcement agency, as specified. AB 514 was held on this Committee's Suspense File.
- AB 3128 (Chen) of the 2017-18 Legislative Session, would have allowed a credit under the PIT Law for up to 50% of the qualified costs of ownership and maintenance of a service dog, not to exceed $1,500 per taxable year, for qualifying disabled veterans. AB 3128 was held on the Assembly Appropriations Committee's Suspense File.
- AB 2472 (Linder) of the 2015-16 Legislative Session, would have allowed a credit under the PIT Law for up to 50% of the qualified costs of ownership and maintenance of a service dog, not to exceed $1,500 per taxable year, for qualifying disabled veterans. AB 2472 was held on the Assembly Appropriations Committee's Suspense File.
- AB 1983 (Maienschein), Chapter 234, Statutes of 2024, authorized the addition of the Prevention of Animal Homelessness and Cruelty Voluntary Tax Contribution Fund on the PIT return.
- An incentive or a reward? Typically, tax credits are provided prospectively as a matter of legislative grace to encourage taxpayers to behave in ways they might not absent a financial incentive. This credit, in turn, is intended to encourage the adoption of pets from rescue organizations. As currently drafted, this bill provides the credit for taxable years beginning on or after January 1, 2025, meaning that taxpayers could benefit from this bill for actions they have already taken without any incentive. The author may wish to amend this bill to allow the credit prospectively, beginning on January 1, 2026.
REGISTERED SUPPORT / OPPOSITION:
Support
Amy's Purpose
Best Friends Animal Society
City of La Quinta
San Diego Humane Society and SPCA
Social Compassion in Legislation
Opposition
California Tax Reform Association
Analysis Prepared by: Wesley Whitaker / REV. & TAX. / (916) 319-2098
2023 Annual Analysis: Comparing 2023 to 2022, 2021, and 2019, Shelter Animals Count. https://www.shelteranimalscount.org/wp-content/uploads/2024/01/Full-Year-2023-Report.pdf. ↑
Date of Hearing: April 21, 2025
ASSEMBLY COMMITTEE ON REVENUE AND TAXATION
Mike Gipson, Chair
ABPCA Bill Id:AB 691 (
Author:Wallis) – As Amended Ver:March 13, 2025
Majority vote. Tax levy. Fiscal committee.
SUBJECT: Personal Income Tax Law: credits: pet adoption and medical expenses
SUMMARY: Allows, under the Personal Income Tax (PIT) Law, a credit of up to $750 for qualified pet adoption costs and qualified pet medical expenses, as specified. Specifically, this bill:
- Allows a credit for taxable years beginning on or after January 1, 2025, and before January 1, 2030, to a taxpayer in an amount equal to the following:
- The "qualified pet adoption costs" paid or incurred by the taxpayer during the taxable year, up to $250; and,
- The "qualified pet medical expenses" paid or incurred by the taxpayer during the taxable year, up to $500.
- Defines the following terms:
- "Qualified pet adoption costs" are the costs paid to a qualified animal rescue organization as adoption fees to secure the adoption of qualified pet;
- "Qualified pet medical expenses" are unreimbursed amounts paid for veterinary care, including vaccinations, spaying or neutering, and other necessary medical treatments for a qualified pet in the first 12 months following adoption;
- "Qualified animal rescue organization" is a public animal control agency or shelter, humane society shelter, or nonprofit rescue group that is exempt from federal income taxation pursuant to Internal Revenue Code (IRC) Section 501(c)(3) that is domiciled in this state and primarily engaged in rescuing and placing animals in permanent homes; and,
- "Qualified pet" is a dog, cat, or other companion animal adopted from a qualified animal rescue organization that is not used by the taxpayer in a trade or business or for the production of income.
- Limits the availability of the credit as follows:
- The adoption credit cannot be claimed more than once during the life of the taxpayer;
- The medical expense credit cannot be claimed with regard to qualified pet medical expenses for more than one qualified pet during the life of the taxpayer, and cannot exceed $500 cumulatively for that qualified pet; and,
- In the case of spouses filing a joint return, the limits described above apply to each spouse separately.
- Requires the taxpayer to provide, upon request and in the form and manner prescribed by the Franchise Tax Board (FTB), all documentation that the FTB determines is necessary to administer this credit, including but not limited to the following:
- Receipt or certification from the qualified animal rescue organization specifying the adoption date, pet description, and adoption fee paid;
- Receipts or invoices from a licensed veterinarian detailing the expenses incurred within the first 12 months following adoption; and,
- A declaration under penalty of perjury that the taxpayer has not previously claimed the respective credit in any prior taxable year, except as otherwise provided.
- Finds and declares the following for the purposes of satisfying the requirements of Revenue and Taxation Code (R&TC) Section 41:
- The specific purpose of the credit is to encourage the adoption of pets from rescue organizations;
- The performance indicators for the Legislature to use in determining whether the credit achieves its stated goal are the number of taxpayers allowed a credit and the total dollar value of credits allowed; and,
- Requires the FTB, on or before December 1, 2026, and annually thereafter, to submit a report to the Legislature detailing the number of taxpayers allowed a credit and the total dollar value of credits allowed.
- Takes immediate effect as a tax levy.
- Sunsets the credit's statutory provisions on December 1, 2030.
EXISTING LAW:
- Allows various tax credits under the PIT Law. These credits are generally designed to encourage socially beneficial behavior or to provide relief to taxpayers who incur specified expenses.
- Requires any bill authorizing a new credit to contain all of the following:
- Specific goals, purposes, and objectives that the tax credit will achieve;
- Detailed performance indicators for the Legislature to use when measuring whether the tax credit meets the goals, purposes, and objectives stated in the bill; and,
- Data collection requirements to enable the Legislature to determine whether the tax credit is meeting, failing to meet, or exceeding those specific goals, purposes, and objectives. The requirements shall include the specific data and baseline measurements to be collected and remitted in each year the credit is in effect, for the Legislature to measure the change in performance indicators, and the specific taxpayers, state agencies, or other entities required to collect and remit data. (R&TC Section 41.)
- Allows a taxpayer to make a contribution to the Prevention of Animal Homelessness and Cruelty Voluntary Tax Contribution Fund on their PIT return, which supports the Pet Lover's Fund grant program. (R&TC Section 18901.9 et seq.)
FISCAL EFFECT: The FTB estimates General Fund revenue losses of $95 million in fiscal year (FY) 2025-26, $60 million in FY 2026-27, and $60 million in FY 2027-28.
COMMENTS:
- The author has provided the following statement in support of this bill:
California desperately needs AB 691 because so many people who’d love to adopt a pet are stopped by the high costs—$50 to $200 just to bring them home, plus $300 or more for vet bills right off the bat—leaving countless dogs and cats stuck in packed shelters, where over 100,000 are put down every year. This bill’s tax credits—up to $250 for adoption fees and $500 for those first vet visits—would make it easier for everyday Californians to say yes to a furry friend, easing the heartbreak of overcrowded shelters and saving lives.
- Writing in support of this bill, Social Compassion in Legislation notes, in part:
The lack of access to affordable veterinary care has contributed to many animals not being spayed or neutered, which has exacerbated the pet overpopulation problem. Meanwhile, it is estimated that our local and state governments spend over $400 million on operating animal shelters. That figure does not include the incalculable millions spent by nonprofit rescue organizations who pull dogs, cats, and various other animals from shelters before they are euthanized in order to save their lives and find them a loving home. Currently, the only ongoing funding for free or low-cost spay and neuter services are the approximately $400,000 granted out annually through the Pet Lover's License Plate Fund for spay and neuter. Much more is needed.
By allowing Californians a modest tax credit when they choose to adopt from our animal shelters rather than buy from a breeder, and for veterinary medical costs, we are supporting our state's animal shelters and pet owners give their beloved pets the medical attention they deserve.
- Writing in opposition to this bill, the California Tax Reform Association notes, in part:
The decision to adopt a pet is a personal decision which is based on many factors, not on the support by the state through tax credits. Since the costs of maintaining pets far exceed the tax credit in this measure, these decisions will always be made independently of the tax incentive. Thus, this tax credit is not a good use of money for the state of California, with losses to education and the general fund. In addition, this measure adds substantial complexity in its need for enforcement and verification to a tax code which is already overly complex to administer fairly.
- Committee Staff Comments:
- What is a "tax expenditure"? Existing law provides various credits, deductions, exclusions, and exemptions for particular taxpayer groups. In the late 1960s, U.S. Treasury officials began arguing that these features of the tax law should be referred to as "expenditures" since they are generally enacted to accomplish some governmental purpose and there is a determinable cost associated with each (in the form of foregone revenues).
As the Department of Finance notes in its annual Tax Expenditure Report, there are several key differences between tax expenditures and direct expenditures. First, tax expenditures are typically reviewed less frequently than direct expenditures. Second, there is generally no control over the amount of revenue losses associated with any given tax expenditure. Finally, it should also be noted that, once enacted, it takes a two-thirds vote to rescind an existing tax expenditure absent a sunset date. This effectively results in a "one-way ratchet" whereby tax expenditures can be conferred by majority vote, but cannot be rescinded, irrespective of their efficacy or cost, without a supermajority vote.
- What problem is this bill attempting to solve? According to the author and supporters, this bill seeks to address overcrowding in animal shelters by encouraging pet adoption and defraying some of the medical costs that might be associated with pet ownership in the first year. While there are likely many causes for this phenomenon, some have suggested that the COVID-19 pandemic and associated recovery played a large role. Animal shelters have seen an uptick in people surrendering or abandoning their pets as work-from-home policies have been curtailed and concerns about the cost of living have risen. According to Shelter Animals Count's 2023 annual analysis report:
In 2023, over 6.5 million animals (3.3 million cats and 3.2 million dogs) entered animal shelters and rescue organizations in the U.S., about the same number as 2022 and up slightly from 2021. Of these, 48% came in as strays, and 25% were surrendered by their owners. Shelters across the country are full, and are now entering their fourth year of having too many animals and not enough adoptions - especially for dogs. Because many shelters and rescues are operating at or over capacity, the number of surrenders and overall intake is likely lower than it would be if space were available.[1]
- An incentive or a reward? Typically, tax credits are provided prospectively as a matter of legislative grace to encourage taxpayers to behave in ways they might not absent a financial incentive. This credit, in turn, is intended to encourage the adoption of pets from rescue organizations. As currently drafted, this bill provides the credit for taxable years beginning on or after January 1, 2025, meaning that taxpayers could benefit from this bill for actions they have already taken without any incentive. The author may wish to amend this bill to allow the credit prospectively, beginning on January 1, 2026.
- Appropriately targeted? The term "taxpayer" includes individuals, fiduciaries, estates, or and partnerships. If the author intends that the credit will only apply to individuals, the term "taxpayer" could be replaced with the term "individual". Additionally, as currently drafted, the credit does not contain income restriction provisions, meaning high-income individuals could receive this benefit while also being able to afford the costs associated with pet adoption. If the author's intent is to incentivize pet adoption among those who may struggle to afford the associated costs, the author may wish to amend this bill to limit the credit based on the taxpayer's annual adjusted gross income.
- Committee's tax expenditure policy: Both R&TC Section 41 and Committee policy require any tax expenditure bill to outline specific goals, purposes, and objectives that the tax expenditure will achieve, along with detailed performance indicators for the Legislature to use when measuring whether the tax expenditure meets those stated goals, purposes, and objectives. A tax expenditure bill will not be eligible for a Committee vote unless it has complied with these requirements. In its current form, this bill states that the credit is to encourage the adoption of pets from rescue organizations.
In addition to the R&TC Section 41 requirements, this Committee's policy also requires that all tax expenditure proposals contain an appropriate sunset provision to be eligible for a vote. According to this policy, an "appropriate sunset provision" means five years, except in the case of a tax expenditure measure providing relief to California veterans, in which case "appropriate sunset provision" shall mean ten years. This bill, as currently drafted, complies with the Committee's policy on sunset dates. - Report timeline: This bill would require the FTB to submit a report to the Legislature detailing the number of taxpayers that receive a credit and the total dollar amount of credits allowed by December 1, 2026. If the author's intent is to review a report that contains complete information for the 2025 taxable year, the FTB recommends that the reporting due date be extended to July 1, 2027. The FTB needs at least six to eight months to complete return processing and to compile the needed data to prepare a report.
- Prior legislation:
- AB 1983 (Maienschein), Chapter 234, Statutes of 2024, authorized the addition of the Prevention of Animal Homelessness and Cruelty Voluntary Tax Contribution Fund on the PIT return.
- AB 514 (Joe Patterson) of the 2023-24 Legislative Session, would have allowed a refundable credit of up to $1,500 for a taxpayer that adopted one or more dogs that previously were in service with a law enforcement agency, as specified. AB 514 was held on this Committee's Suspense File.
- AB 3128 (Chen) of the 2017-18 Legislative Session, would have allowed a credit under the PIT Law for up to 50% of the qualified costs of ownership and maintenance of a service dog, not to exceed $1,500 per taxable year, for qualifying disabled veterans. AB 3128 was held on the Assembly Appropriations Committee's Suspense File.
- AB 2472 (Linder) of the 2015-16 Legislative Session, would have allowed a credit under the PIT Law for up to 50% of the qualified costs of ownership and maintenance of a service dog, not to exceed $1,500 per taxable year, for qualifying disabled veterans. AB 2472 was held on the Assembly Appropriations Committee's Suspense File.
- AB 1983 (Maienschein), Chapter 234, Statutes of 2024, authorized the addition of the Prevention of Animal Homelessness and Cruelty Voluntary Tax Contribution Fund on the PIT return.
- An incentive or a reward? Typically, tax credits are provided prospectively as a matter of legislative grace to encourage taxpayers to behave in ways they might not absent a financial incentive. This credit, in turn, is intended to encourage the adoption of pets from rescue organizations. As currently drafted, this bill provides the credit for taxable years beginning on or after January 1, 2025, meaning that taxpayers could benefit from this bill for actions they have already taken without any incentive. The author may wish to amend this bill to allow the credit prospectively, beginning on January 1, 2026.
REGISTERED SUPPORT / OPPOSITION:
Support
Amy's Purpose
Best Friends Animal Society
City of La Quinta
San Diego Humane Society and SPCA
Social Compassion in Legislation
Opposition
California Tax Reform Association
Analysis Prepared by: Wesley Whitaker / REV. & TAX. / (916) 319-2098
2023 Annual Analysis: Comparing 2023 to 2022, 2021, and 2019, Shelter Animals Count. https://www.shelteranimalscount.org/wp-content/uploads/2024/01/Full-Year-2023-Report.pdf. ↑
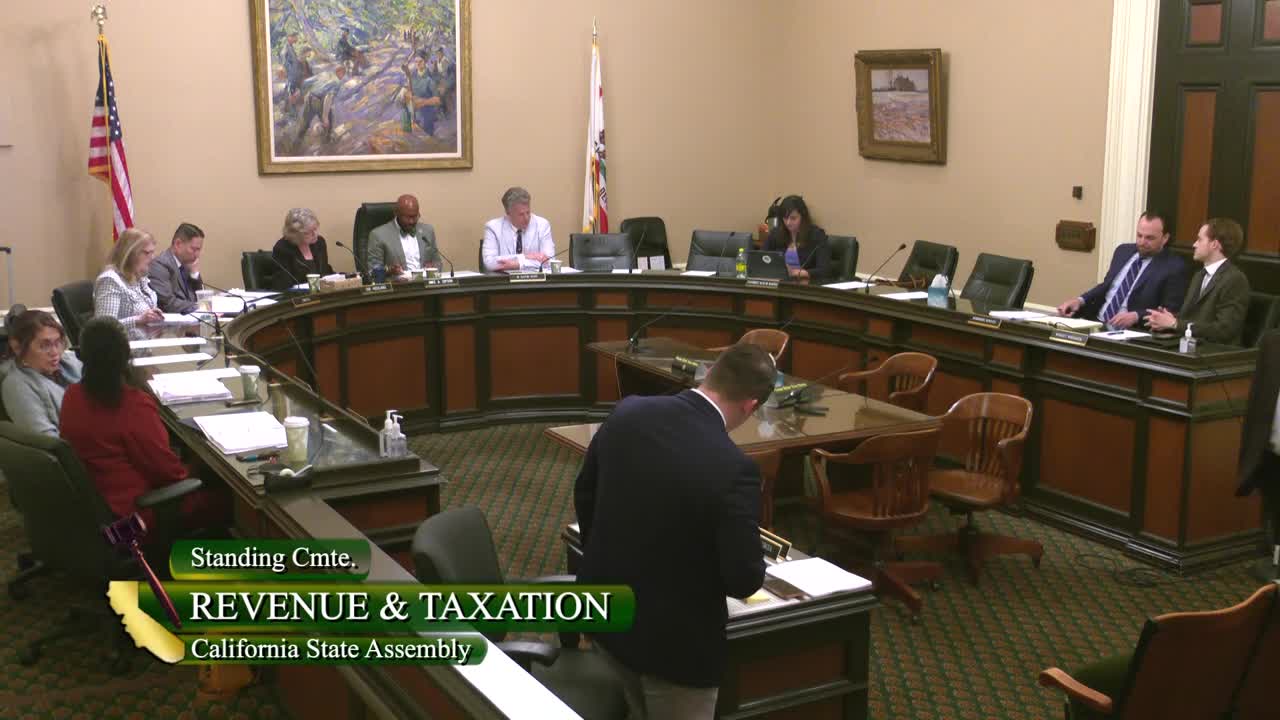
Discussed in Hearing
 5MIN
Assembly Standing Committee on Revenue and Taxation
Bill Author
Bill Co-Author(s):