SCA 4: Property taxation: veterans’ exemption.
- Session Year: 2025-2026
- House: Senate
- Latest Version Date: 2026-04-08
Current Status:
In Progress
(2026-05-14: May 14 hearing: Held in committee and under submission.)
Introduced
In Committee
Awaiting First Chamber Vote
Passed First Chamber
In Committee
Awaiting Second Chamber Vote
Passed Second Chamber
Enacted
What does this bill do?
This proposed constitutional amendment expands property tax breaks for veterans, surviving spouses, and veterans’ parents by adding the U.S. Space Force to the list of qualifying military service, allowing a veteran’s home to get both the veterans and homeowners exemptions, and removing rules that disqualified claimants based on how much property they own. It also lets state lawmakers exempt veterans’ property up to its full value and requires that any increase to the homeowners exemption be matched for the veterans exemption, up to that full-value limit.
The summary is provided by generative AI which can make mistakes. For original language, please view the details in the table below.
The California Constitution declares that all property is taxable and establishes or authorizes various exemptions from tax for real property, including a homeowners exemption in the amount of $7,000 of the full value of a dwelling unless the dwelling receives another real property exemption. If the Legislature increases the homeowners exemption, the California Constitution requires that the Legislature provide a benefit increase to qualified renters comparable to the average increase in benefits to homeowners.
The California Constitution and existing property tax law establish a veterans exemption in the amount of $4,000 for a veteran who meets certain military service requirements requirements, including that the veteran is serving in or has served in and has been discharged under honorable conditions from one of specified branches of the United States military, and generally exempts from property taxation the same value of property of a deceased veterans unmarried spouse and parents. The California Constitution authorizes and existing property tax law establishes a disabled veterans exemption in the amount of $100,000 or $150,000 for the principal place of residence of a veteran or a veterans spouse, including an unmarried surviving spouse, if the veteran, because of an injury incurred in military service, is blind in both eyes, has lost the use of 2 or more limbs, or is totally disabled, as those terms are defined, or if the veteran has, as a result of a service-connected injury or disease, died while on active duty in military service. Existing law prohibits receiving the veterans exemption on property owned by an unmarried person who owns more than $5,000 of property or a married person who owns more than $10,000 of property. Existing law prohibits receiving the deceased veterans exemption on property owned by a deceased veterans unmarried spouse who owns more than $10,000 of property, a deceased veterans unmarried parent who owns more than $5,000 of property, or a deceased veterans married parent who owns more than $10,000 of property.
ThisThis measure would add the United States Space Force to the military branches, the service in which satisfies the veterans exemption military service requirement described above. This measure would allow a dwelling that receives the veterans exemption or the disabled veterans exemption to also receive the homeowners exemption. The measure would authorize the Legislature to exempt property eligible for the veterans exemption in an amount up to the full value of the property. If the Legislature increases the homeowners exemption, the measure would require that the Legislature provide the same increase in the veterans exemption, except as limited by the full value of the property. The bill would remove the above-described prohibitions on a property receiving the veterans or deceased veterans exemption based on the amount of property that a veteran or veterans parent or spouse owns.
The California Constitution declares that all property is taxable and establishes or authorizes various exemptions from tax for real property, including a homeowners exemption in the amount of $7,000 of the full value of a dwelling unless the dwelling receives another real property exemption. If the Legislature increases the homeowners exemption, the California Constitution requires that the Legislature provide a benefit increase to qualified renters comparable to the average increase in benefits to homeowners.
The California Constitution and existing property tax law establish a veterans exemption in the amount of $4,000 for a veteran who meets certain military service requirements and generally exempts from property taxation the same value of property of a deceased veterans unmarried spouse and parents. The California Constitution authorizes and existing property tax law establishes a disabled veterans exemption in the amount of $100,000 or $150,000 for the principal place of residence of a veteran or a veterans spouse, including an unmarried surviving spouse, if the veteran, because of an injury incurred in military service, is blind in both eyes, has lost the use of 2 or more limbs, or is totally disabled, as those terms are defined, or if the veteran has, as a result of a service-connected injury or disease, died while on active duty in military service. Existing law prohibits receiving the veterans exemption on property owned by an unmarried person who owns more than $5,000 of property or a married person who owns more than $10,000 of property. Existing law prohibits receiving the deceased veterans exemption on property owned by a deceased veterans unmarried spouse who owns more than $10,000 of property, a deceased veterans unmarried parent who owns more than $5,000 of property, or a deceased veterans married parent who owns more than $10,000 of property.
This measure would allow a dwelling that receives the veterans exemption or the disabled veterans exemption to also receive the homeowners exemption. The measure would authorize the Legislature to exempt property eligible for the veterans exemption in an amount up to the full value of the property. If the Legislature increases the homeowners exemption, the measure would require that the Legislature provide the same increase in the veterans exemption, except as limited by the full value of the property. The bill would remove the above-described prohibitions on a property receiving the veterans or deceased veterans exemption based on the amount of property that a veteran or veterans parent or spouse owns.
Resolved by the Senate, the Assembly concurring, That the Legislature of the State of California at its 202526 Regular Session, commencing on the second day of December 2024, two-thirds of the membership of each house concurring, hereby proposes to the people of the State of California, that the Constitution of the State be amended as follows:
The following are exempt from property taxation:
(a)Property owned by the State.
(b)Property owned by a local government, except as otherwise provided in Section 11(a).
(c)Bonds issued by the State or a local government in the State.
(d)Property used for libraries and museums that are free and open to the public and property used exclusively for public schools, community colleges, state colleges, and state universities.
(e)Buildings, land, equipment, and securities used exclusively for educational purposes by a nonprofit institution of higher education.
(f)Buildings, land on which they are situated, and equipment used exclusively for religious worship.
(g)Property used or held exclusively for the permanent deposit of human dead or for the care and maintenance of the property or the dead, except when used or held for profit. This property is also exempt from special assessment.
(h)Growing crops.
(i)Fruit and nut trees until four years after the season in which they were planted in orchard form and grape vines until three years after the season in which they were planted in vineyard form.
(j)Immature forest trees planted on lands not previously bearing merchantable timber or planted or of natural growth on lands from which the merchantable original growth timber stand to the extent of 70 percent of all trees over 16 inches in diameter has been removed. Forest trees or timber shall be considered mature at such time after 40 years from the time of planting or removal of the original timber when so declared by a majority vote of a board consisting of a representative from the State Board of Forestry, a representative from the State Board of Equalization, and the assessor of the county in which the trees are located.
The Legislature may supersede the foregoing provisions with an alternative system or systems of taxing or exempting forest trees or timber, including a taxation system not based on property valuation. Any alternative system or systems shall provide for exemption of unharvested immature trees, shall encourage the continued use of timberlands for the production of trees for timber products, and shall provide for restricting the use of timberland to the production of timber products and compatible uses with provisions for taxation of timberland based on the restrictions. Nothing in this paragraph shall be construed to exclude timberland from the provisions of Section 8 of this article.
(k)$7,000 of the full value of a dwelling, as defined by the Legislature, when occupied by an owner as the owners principal residence, unless the dwelling is receiving another real property exemption other than the exemptions under subdivisions (o), (p), and (q) or the exception authorized under subdivision (a) of Section 4. The Legislature may increase the homeowners property tax exemption and may deny it if the owner received state or local aid to pay taxes either in whole or in part, and either directly or indirectly, on the dwelling.
No increase in the homeowners property tax exemption above the amount of $7,000 shall be effective for any fiscal year unless the Legislature increases the rate of state taxes in an amount sufficient to provide the subventions required by Section 25.
If the Legislature increases the homeowners property tax exemption, it shall provide the same increase, except as may be limited by full value, in the amounts of the exemptions under subdivisions (o), (p), and (q), and shall provide increases in benefits to qualified renters, as defined by law, comparable to the average increase in benefits to homeowners, as calculated by the Legislature.
(l)Vessels of more than 50 tons burden in this State and engaged in the transportation of freight or passengers.
(m)Household furnishings and personal effects not held or used in connection with a trade, profession, or business.
(n)Any debt secured by land.
(o)Property, in the amount of $1,000 or in a greater amount that is set forth in statute and does not exceed full value, of a claimant who
(1)is serving in or has served in and has been discharged under honorable conditions from service in the United States Army, Navy, Air Force, Space Force, Marine Corps, Coast Guard, or Revenue Marine (Revenue Cutter) Service; and
(2)served either
(A)in time of war, or
(B)in time of peace in a campaign or expedition for which a medal has been issued by Congress, or
(C)in time of peace and because of a service-connected disability was released from active duty; and
(3)resides in the State on the current lien date.
If the claimant is married and does not own property eligible for the full amount of the exemption, property of the spouse shall be eligible for the unused balance of the exemption.
(p)Property, in the amount of $1,000 or in a greater amount that is set forth in statute and does not exceed full value, of a claimant who
(1)is the unmarried spouse of a deceased veteran who met the service requirement stated in paragraphs (1) and (2) of subsection 3(o), and
(2)is a resident of the State on the current lien date.
(q)Property, in the amount of $1,000 or in a greater amount that is set forth in statute and does not exceed full value, of a claimant who
(1)is the parent of a deceased veteran who met the service requirement stated in paragraphs (1) and (2) of subsection 3(o), and
(2)receives a pension because of the veterans service, and
(3)is a resident of the State on the current lien date.
Either parent of a deceased veteran may claim this exemption.
(r)No individual residing in the State on the effective date of this amendment who would have been eligible for the exemption provided by the previous section 11/4 of this article had it not been repealed shall lose eligibility for the exemption as a result of this amendment.
Resolved by the Senate, the Assembly concurring, That the Legislature of the State of California at its 202526 Regular Session, commencing on the second day of December 2024, two-thirds of the membership of each house concurring, hereby proposes to the people of the State of California, that the Constitution of the State be amended as follows:
The following are exempt from property taxation:
(a)Property owned by the State.
(b)Property owned by a local government, except as otherwise provided in Section 11(a).
(c)Bonds issued by the State or a local government in the State.
(d)Property used for libraries and museums that are free and open to the public and property used exclusively for public schools, community colleges, state colleges, and state universities.
(e)Buildings, land, equipment, and securities used exclusively for educational purposes by a nonprofit institution of higher education.
(f)Buildings, land on which they are situated, and equipment used exclusively for religious worship.
(g)Property used or held exclusively for the permanent deposit of human dead or for the care and maintenance of the property or the dead, except when used or held for profit. This property is also exempt from special assessment.
(h)Growing crops.
(i)Fruit and nut trees until 4 four years after the season in which they were planted in orchard form and grape vines until 3 three years after the season in which they were planted in vineyard form.
(j)Immature forest trees planted on lands not previously bearing merchantable timber or planted or of natural growth on lands from which the merchantable original growth timber stand to the extent of 70 percent of all trees over 16 inches in diameter has been removed. Forest trees or timber shall be considered mature at such time after 40 years from the time of planting or removal of the original timber when so declared by a majority vote of a board consisting of a representative from the State Board of Forestry, a representative from the State Board of Equalization, and the assessor of the county in which the trees are located.
The Legislature may supersede the foregoing provisions with an alternative system or systems of taxing or exempting forest trees or timber, including a taxation system not based on property valuation. Any alternative system or systems shall provide for exemption of unharvested immature trees, shall encourage the continued use of timberlands for the production of trees for timber products, and shall provide for restricting the use of timberland to the production of timber products and compatible uses with provisions for taxation of timberland based on the restrictions. Nothing in this paragraph shall be construed to exclude timberland from the provisions of Section 8 of this article.
(k)$7,000 of the full value of a dwelling, as defined by the Legislature, when occupied by an owner as his the owners principal residence, unless the dwelling is receiving another real property exemption. exemption other than the exemptions under subdivisions (o), (p), and (q) or the exception authorized under subdivision (a) of Section 4. The Legislature may increase this the homeowners property tax exemption and may deny it if the owner received state or local aid to pay taxes either in whole or in part, and either directly or indirectly, on the dwelling.
No increase in this the homeowners property tax exemption above the amount of $7,000 shall be effective for any fiscal year unless the Legislature increases the rate of state taxes in an amount sufficient to provide the subventions required by Section 25.
If the Legislature increases the homeowners property tax exemption, it shall provide the same increase, except as may be limited by full value, in the amounts of the exemptions under subdivisions (o), (p), and (q), and shall provide increases in benefits to qualified renters, as defined by law, comparable to the average increase in benefits to homeowners, as calculated by the Legislature.
(l)Vessels of more than 50 tons burden in this State and engaged in the transportation of freight or passengers.
(m)Household furnishings and personal effects not held or used in connection with a trade, profession, or business.
(n)Any debt secured by land.
(o)Property Property, in the amount of $1,000 or in a greater amount that is set forth in statute and does not exceed full value, of a claimant who
(1)is serving in or has served in and has been discharged under honorable conditions from service in the United States Army, Navy, Air Force, Marine Corps, Coast Guard, or Revenue Marine (Revenue Cutter) Service; and
(2)served either
(i)(A)in time of war, or
(ii)(B)in time of peace in a campaign or expedition for which a medal has been issued by Congress, or
(iii)(C)in time of peace and because of a service-connected disability was released from active duty; and
(3)resides in the State on the current lien date.
An unmarried person who owns property valued at $5,000 or more, or a married person, who, together with the spouse, owns property valued at $10,000 or more, is ineligible for this exemption.If the claimant is married and does not own property eligible for the full amount of the exemption, property of the spouse shall be eligible for the unused balance of the exemption.
(p)Property Property, in the amount of $1,000 or in a greater amount that is set forth in statute and does not exceed full value, of a claimant who
(1)is the unmarried spouse of a deceased veteran who met the service requirement stated in paragraphs (1) and (2) of subsection 3(o), and
(2)does not own property in excess of $10,000, and(3)(2)is a resident of the State on the current lien date.
(q)Property Property, in the amount of $1,000 or in a greater amount that is set forth in statute and does not exceed full value, of a claimant who
(1)is the parent of a deceased veteran who met the service requirement stated in paragraphs (1) and (2) of subsection 3(o), and
(2)receives a pension because of the veterans service, and
(3)is a resident of the State on the current lien date.
Either parent of a deceased veteran may claim this exemption.
An unmarried person who owns property valued at $5,000 or more, or a married person, who, together with the spouse, owns property valued at $10,000 or more, is ineligible for this exemption.(r)No individual residing in the State on the effective date of this amendment who would have been eligible for the exemption provided by the previous section 11/4 of this article had it not been repealed shall lose eligibility for the exemption as a result of this amendment.
|
Date
|
Status
|
|---|---|
| May 14, 2026 | May 14 hearing: Held in committee and under submission. |
| May 8, 2026 | Set for hearing May 14. |
| May 4, 2026 | May 4 hearing: Placed on APPR. suspense file. |
| Apr 24, 2026 | Set for hearing May 4. |
| Apr 21, 2026 | From committee: Be adopted and re-refer to Com. on APPR. with recommendation: To consent calendar. (Ayes 5. Noes 0. Page 3972.) (April 21). Re-referred to Com. on APPR. |
| Apr 21, 2026 | From committee: Be adopted and re-refer to Com. on APPR. with recommendation: To consent calendar. (Ayes 5. Noes 0.) (April 21). Re-referred to Com. on APPR. |
| Apr 9, 2026 | Set for hearing April 21. |
| Apr 8, 2026 | From committee with author's amendments. Read second time and amended. Re-referred to Com. on E. & C.A. |
| Jan 14, 2026 | From committee: Be adopted and re-refer to Com. on E. & C.A. (Ayes 5. Noes 0. Page 3226.) (January 14). Re-referred to Com. on E. & C.A. |
| Jan 6, 2026 | Set for hearing January 14. |
| Jan 5, 2026 | Referred to Coms. on REV. & TAX. and E. & C.A. |
| Feb 20, 2025 | Introduced. Read first time. To Com. on RLS. for assignment. To print. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| May 4, 2026 | Placed on suspense file | Senate Standing Committee on Appropriations |
Passed |
|
| Apr 21, 2026 | Be adopted, but first be re-referred to the Committee on [Appropriations] with recommendation: To Consent Calendar | Senate Standing Committee on Elections and Constitutional Amendments |
Passed |
|
| Jan 14, 2026 | Be adopted, but first be re-referred to the Committee on [Elections and Constitutional Amendments] | Senate Standing Committee on Revenue and Taxation |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| American Legion, Department Of California | ** Support | |
| AMVETS-Department of California | ** Support | |
| California Association Of Realtors | ** Support | |
| California State Board of Equalization | ** Support | |
| California State Commanders Veterans Council | ** Support | |
| Howard Jarvis Taxpayers Association | ** Support | |
| Military Officers Association of America-California Council of Chapters | ** Support | |
| Vietnam Veterans of America-California State Council | ** Support |
SENATE COMMITTEE ON
Senator Sabrina Cervantes, Chair
2025 - 2026 Regular Session
SCA 4 (Archuleta) - Property taxation: veterans’ exemption
Version: | Policy Vote: |
Urgency: | Mandate: |
Hearing Date: | Consultant: |
Bill Summary:
SCA 4, if approved by the voters, would allow additional property tax benefits to taxpayers eligible for the existing disabled veterans’ or veterans’ property tax exemptions, as specified.
Fiscal Impact:
- This measure would result in one-time General Fund costs to the Secretary of State (SOS) in the range of $738,000 to $984,000, likely in 2026-27, for printing and mailing costs to place the measure on the ballot in a statewide election. Actual costs may be higher or lower, depending on the length of required elements and the overall size of the ballot.
- The Board of Equalization (BOE) estimates that this measure’s changes to property tax would result in annual revenue losses of $4.7 million. Reductions in local property tax revenues, in turn, increase General Fund Proposition 98 spending by up to roughly 50 percent (the exact amount depends on the specific amount of the annual Proposition 98 guarantee, which in turn depends upon a variety of economic, demographic and budgetary factors). BOE would likely incur minor General Fund administrative costs.
Background:
Under the California Constitution, all property is taxable unless explicitly exempted. Current exemptions include the Homeowners’ Exemption, the Veterans’ Exemption, and the Disabled Veterans’ Exemption.
Homeowners’ Exemption: The Constitution (1) grants a $7,000 property tax exemption on the assessed value of owner-occupied dwellings, and (2) requires the State to reimburse local governments for the resulting reduction in property tax revenues.
Standard Veterans’ Exemption: This is a $4,000 exemption on the assessed value of real or personal property owned by veterans that were honorably discharged. A surviving spouse or parents may claim the exemption. The exemption, however, is unavailable to veterans who own property valued at $5,000 or more. Because of the property value limitation, few veteran homeowners are eligible to claim the standard exemption. This exemption has also fallen into disuse because at only $4,000, any veteran who owns a home can instead claim the homeowners' exemption of $7,000, which provides greater tax savings.
Disabled Veterans’ Exemption. This is an exemption from the assessed value of a disabled veteran’s principal residence. In order to qualify for the exemption, a veteran must have severe service-related injuries. Qualified veterans include those with service-related (1) loss of vision in both eyes, (2) loss of the use of two or more limbs, or (3) 100 percent disability rating by the VA. Unmarried surviving spouses are eligible for this exemption. The exemption applies instead of other real property exemptions, like the homeowners’ exemption. State law implementing the exemption doesn’t fully exclude the value of a disabled veteran’s property, instead enacting a partial exemption of $100,000 for disabled veteran taxpayers with annual household income of more than $40,000, or $150,000 for income lower than that amount, with each threshold adjusted for inflation by the Department of Industrial Relations using the California Consumer Price Index for all items. The current inflation adjusted value for 2025 is $175,298 for disabled veterans with income of more than $78,718, and $262,950 for those with less than that amount.
Proposed Law:
This measure, if approved by the voters, would do the following:
- Remove a provision in the California Constitution that prevents a taxpayer from claiming the homeowners’ exemption and the disabled veterans’ or veterans’ exemption.
- Require the Legislature to increase the veterans’ exemption if it increases the homeowners’ exemption.
- Make two changes to the veterans’ exemption:
- Delete a provision that limits claiming the veterans’ exemption to only those veterans who own in the aggregate less than $5,000 if the claimant is single, or $10,000 if married.
- Allow the Legislature to provide a greater exemption amount than the current $4,000 one, so long as that amount does not exceed the full value of the property.
Related Legislation:
SB 623 (Archuleta) would make statutory changes to implement SCA 4’s constitutional change to allow eligible taxpayers to also claim both the homeowners’ and either the disabled veterans’ or veterans’ exemption. The measure is currently pending at the Assembly Desk.
Staff Comments:
SOS indicates that printing and mailing costs associated with placing a measure on the statewide ballot are $123,000 per page, depending on the length of the ballot. The fiscal estimates noted above reflect the addition of 6-8 pages in the Voter Information Guide. Actual costs would depend upon the length of the title and summary, analysis by the LAO, proponent and opponent arguments, and text of the proposal.
-- END --
SENATE COMMITTEE ON
ELECTIONS AND CONSTITUTIONAL AMENDMENTS
Senator Sabrina Cervantes, Chair
2025 - 2026 Regular
Bill No: Hearing Date: 4/21/26
Author: | |||
Version: | 4/8/26 | ||
Urgency: | Fiscal: | ||
Consultant: | |||
Subject:
DIGEST
This proposed constitutional amendment would, if approved by the voters, allow an eligible California homeowner to claim the homeowners’ exemption in addition to one or both of the veterans’ exemptions on their property taxes.
ANALYSIS
Existing law contained in Article XIII of the California Constitution provides that all property is taxable but provides several specific exemptions, including:
- The first $7,000 of the full value of dwelling occupied by the owner as the owner’s principal residence. This is called the homeowners’ exemption, and the constitution prohibits claiming it if the homeowner claims another exemption for this property’s taxation.
- The first $1,000 (adjusted to $4,000 in statute) of the value of a property owned by someone serving or who has served in the military and who served:
- In the time of war;
- In time of peace in a campaign or expedition for which Congress issued a medal to the taxpayer; or
- In time of peace and because of a service-connected disability was released from active duty.
This is called the veterans’ exemption. An unmarried surviving spouse or either parent of a deceased qualifying veteran may claim this credit. An unmarried parent who owns property valued at $5,000 or more or a married parent who owns property valued at $10,000 or more is not eligible for this exemption. A surviving spouse may own property up to $10,000 in value and remain eligible. Only California residents are eligible.
- The value of a disabled veteran’s principal place of residence, if the Legislature so chooses. To qualify, the veteran has to have lost two or more limbs, be totally blind, or be totally disabled as a result of a service-connected injury. This disabled veterans’ exemption is available to disabled veteran taxpayers or their unmarried surviving spouses, as specified. State law implementing the exemption does not fully exclude the value of a disabled veteran’s property, but instead adjusts the exemption based on household income.
This measure asks the people of the State of California to amend Article XIII of the California Constitution to:
- Permit a qualifying taxpayer to claim both the homeowners’ exemption and one or both of the veterans’ exemptions.
- Allow the Legislature through statute to increase the current $4,000 amount of the veterans’ exemption to a higher amount, provided it does not exceed the full value of the property.
- Delete the property value limits that make a person ineligible.
- Add the United States Space Force to the list of branches of the military service that make a veteran eligible for the veterans’ exemption.
- Delete obsolete language and make conforming changes.
BACKGROUND
Homeowners’ Exemption. The California Constitution exempts $7,000 in taxable value of a home when it is the principal place of residence of the owner on January 1st of the year the exemption is claimed, unless the taxpayer claims another exemption, such as a veteran’s exemption. State law precludes a property that is rented, vacant, under construction on the lien date, or is a vacation or secondary home. The property must be the taxpayer's true, fixed and permanent home, and principal establishment to which they intend to return if absent.
Once granted, the homeowner’s exemption continues until the taxpayer notifies the assessor of ownership changes. The Constitution allows the Legislature to increase the exemption but requires the Legislature to increase subventions to local agencies backfilling any revenue loss and provide an increase in benefits to qualified renters.
Veterans’ Exemption. The Constitution contains an exemption for veterans, which it defines as someone who is serving, or has served in and has been discharged under honorable conditions from service, in the United States Army, Navy, Air Force, Marine Corps, Coast Guard, or Revenue Marine (Revenue Cutter) Service; and served in any of the following:
- In time of war;
- In time of peace in a campaign or expedition for which a medal has been issued to the veteran by Congress; or
- In time of peace and because of a service-connected disability was released from active duty.
State statute deems 26 wars and four campaigns as qualifying for the veterans' exemptions in statute. Most of the wars and campaigns listed occurred over 100 years ago, dating back to the Revolutionary War. The exemption reduces taxable value by $1,000 (adjusted to $4,000 in statute) for a person qualifying under the above criteria, or their unmarried surviving spouse or either parent of a deceased veteran meeting the service requirements.
The Constitution only allows the exemption for veterans who own property, real or personal, worth less in aggregate than $5,000 if the claimant is single, or $10,000 if married. According to California Board of Equalization, at its peak, from 1956 through 1962, over one million persons received the veterans' exemption. The constitutional restrictions for the exemption have, however, rendered it obsolete, so much so that, only one person received the exemption in 2018-19. This exemption has also fallen into disuse because at only $4,000, any veteran who owns a home can instead claim the homeowners' exemption of $7,000, which provides greater tax savings.
Disabled Veterans’ Exemption. Section 4 of Article XIII allows the Legislature to partially or wholly exempt from property tax the value of a disabled veteran’s principal place of residence if the veteran has lost two or more limbs, is totally blind, or is totally disabled as a result of a service-connected injury. The taxpayer must have served in the United States Army, Navy, Air Force, Space Force, Coast Guard, or Marine Corps and been discharged under conditions other than dishonorable. This disabled veterans’ exemption is available to disabled veteran taxpayers or their unmarried surviving spouses, so long as the surviving spouse receives a U.S. Department of Veterans Affairs determination that the spouse’s death was service-connected. The exemption applies instead of other real property exemptions, like the homeowners’ exemption.
State law implementing the exemption provides a partial exemption of $100,000 for disabled veteran taxpayers with annual household income of more than $40,000, or $150,000 for income less than $40,000, with each threshold adjusted annually for inflation by the Department of Industrial Relations using the California Consumer Price Index for all items. The current inflation adjusted value for 2025 is $175,298 for disabled veterans with income of more than $78,718 and $262,950 for those with less than $78,718.
COMMENTS
- Author’s Statement. Veterans have made significant sacrifices in service to our country. They have put their lives on the line, spent time away from their families, and faced numerous physical and mental challenges in their pursuit of safety and security for our country. Despite all of this, many veterans continue to face difficulties as they transition back to civilian life. One of the biggest challenges veterans face is the financial burden of owning a home. For many veterans, owning a home can be a difficult dream to achieve and maintain. Many veterans struggle to make ends meet despite their service, especially if they are on a fixed income or facing other financial challenges.
In California, the current veterans’ exemption provides veterans and their families with a $4,000 reduction in the taxable value of their property to help ease the financial burden of owning a home. This lifeline can be especially important for veterans who are facing other challenges such as medical bills or disabilities as a result of their service. Unfortunately, the amount of the current veteran exemption has remained the same since its creation, along with limitations on the maximum eligible value of a property owned by a veteran. Furthermore, because the homeowners’ exemption is nearly twice the amount of the veteran exemption at $7,000, most California veteran homeowners choose the homeowners’ exemption, leaving the veterans’ exemption underutilized.
This measure and its companion bill, SB 623 (Archuleta), seek to allow a veteran property owner who qualifies for the veterans’ exemption or the disabled veterans’ exemption to also receive the homeowners’ exemption. These measures will provide much needed tax relief for veterans and their families. In California, we have a proud tradition of supporting our veterans. We recognize the sacrifices that they have made, and we are committed to providing them with the support they need to succeed and stay here in California after their service.
- Arguments in Support. The Howard Jarvis Taxpayers Association writes in support of the bill:
The veterans’ exemption, as currently prescribed in the state Constitution, is effectively obsolete. The veterans’ exemption is not adjusted for inflation. As such, the exemptions value remains the same at $4,000, the equivalent of $40 dollars in real terms, along with the limitations on the maximum total value of property owned by the veteran to remain eligible for the exemption.
Moreover, the homeowners’ property tax exemption is nearly twice the amount of the veteran’s exemption ($7,000 or $70). Both exemptions prohibit application of the other exemption. In other words, it is extremely unlikely that a veteran property owner would claim the veteran's exemption.
There is some disagreement over how many people in the state claim the veteran’s exemption. But the estimates range from zero to two.
RELATED/PRIOR LEGISLATION
SB 623 (Archuleta) makes changes to statute to implement SCA 4’s constitutional change to allow eligible taxpayers to also claim both the homeowners’ as well as either the disabled veterans’ or veterans’ exemption. This bill passed the Senate and is pending action in the Assembly.
SCA 6 (Archuleta) of 2023 was nearly identical to this measure. SCA 6 passed the Senate, but the Assembly took no action on the measure.
PRIOR ACTION
Senate Committee on Governance and Finance: | 5-0 |
POSITIONS
Sponsor: Author
Support: American Legion, Department of California
AMVETS-Department of California
California Association of Realtors
California State Board of Equalization
California State Commanders Veterans Council
Howard Jarvis Taxpayers Association
Military Officers Association of America-California Council of Chapters
Vietnam Veterans of America-California State Council
Oppose: None received.
-- END --
SENATE COMMITTEE ON REVENUE AND TAXATION
Senator Jerry McNerney, Chair
2025 - 2026 Regular
Bill No: | SCA 4 | Hearing Date: | 1/14/26 |
Author: | Archuleta | Tax Levy: |
|
Version: | 2/20/25 | Fiscal: | Yes |
Consultant: | Grinnell | ||
Property taxation: veterans’ exemption
Amends the California Constitution to allow additional property tax benefits for taxpayers eligible for the disabled veterans’ or veterans’ exemptions from property tax.
Background
The California Constitution provides that all property is taxable unless explicitly exempted by the Constitution or federal law. However, Section Three of Article XIII sets forth several property tax exemptions, including:
The Homeowners’ Exemption. The Constitution authorizes a taxpayer to claim a $7,000 exemption to the taxable value of a property when the home is the principal place of residence of the owner on January 1st of the year the exemption is claimed. The homeowners’ exemption may not be claimed if the taxpayer claims another exemption. State law also precludes taxpayers from claiming the homeowners’ exemption for property that is rented, vacant, under construction on the lien date, or that is a vacation or secondary home. The property must be the taxpayer’s true, fixed, and permanent home, and principal establishment to which they intend to return if absent. Once granted, the exemption continues until the taxpayer notifies the assessor or ownership changes. The Constitution allows the Legislature to increase the exemption; however, they must increase subventions to local agencies backfilling any revenue loss and provide an increase in benefits to qualified renters. Unlike other exemptions, Section 25 of Article XIII requires the state to backfill local property tax revenue losses resulting from the exemption.
Veterans’ Exemption. The Constitution contains an exemption for veterans, which the Constitution defines as someone who is serving in, or has served and been discharged under honorable conditions from service in, the United States Army, Navy, Air Force, Marine Corps, Coast Guard, or Revenue Marine (Revenue Cutter) Service; and served in any of the following:
- in time of war,
- in time of peace in a campaign or expedition for which a medal has been issued to the veteran by Congress, or
- in time of peace and because of a service-connected disability was released from active duty.
There are 26 wars and 4 campaigns that qualify for the Veterans’ Exemptions in statute. The majority of the wars and campaigns listed occurred over 100 years ago, dating back to the Revolutionary War. The exemption reduces taxable value by $1,000 (adjusted to $4,000 in statute) for a person qualifying under the above criteria, or their unmarried surviving spouse or parent in the case of a deceased veteran meeting the service requirements.
The Constitution only allows the exemption for veterans who own property, real or personal, worth less in aggregate than $5,000 if the claimant is single, or $10,000 if married. According to the State Board of Equalization (BOE), at its peak, from 1956 through 1962, over one million persons received the veterans’ exemption. However, the constitutional restrictions for the exemption have rendered it obsolete, so much so that no one currently claims it according to BOE. This exemption has also fallen into disuse because at only $4,000, any eligible veteran who owns a home can instead claim the more valuable $7,000 homeowners’ exemption.
Disabled Veterans’ Exemption. Additionally, Section Four of Article XIII allows the Legislature to partially or wholly exempt from property tax the value of a disabled veteran’s principal place of residence if the veteran has lost two or more limbs, is totally blind, or is totally disabled as a result of a service-connected injury. The taxpayer must have served in the United States Army, Navy, Air Force, Space Force, Coast Guard, or Marine Corps and been discharged under conditions other than dishonorable. This disabled veterans’ exemption is available to disabled veteran taxpayers or their unmarried surviving spouses, so long as the surviving spouse receives a U.S. Department of Veterans Affairs determination that the spouse’s death was service connected. The exemption applies instead of other real property exemptions, like the homeowners’ exemption.
The disabled veterans’ exemption authorizes a partial exemption of $100,000 for disabled veteran taxpayers with an annual household income of more than $40,000, or a partial exemption of $150,000 for income lower than $40,000. Each of these threshold amounts are adjusted for inflation by the Department of Industrial Relations using the California Consumer Price Index for all items. The current inflation-adjusted exemption for 2025 is $175,298 for disabled veterans with income above $78,718 and $262,950 for those with income below $78,718.
Seeking to provide additional property tax relief for veterans, including disabled veterans, the author wants to place a constitutional amendment before voters that would allow taxpayers to claim both the homeowners’ and disabled veterans’ exemption, and allow the Legislature to adjust the aggregate value of property a taxpayer can claim to be eligible for the veterans’ exemption as well as the exemption amount.
Proposed Law
Senate Constitutional Amendment 4 places a measure before voters that removes a provision in the California Constitution that prevents a taxpayer from claiming the homeowners’ exemption and the disabled veterans’ or veterans’ exemption, thereby allowing eligible taxpayers to stack the exemptions. SCA 4 also requires the Legislature to increase the veterans’ exemption if it increases the homeowners’ exemption.
The measure also makes two changes to the veterans’ exemption:
- Deletes a provision that limits claiming the veterans’ exemption to only those veterans who own in the aggregate less than $5,000 if the claimant is single, or $10,000 if married.
- Allows the Legislature to provide a greater exemption amount than the current $4,000 one, so long as that amount does not exceed the full value of the property.
SCA 4 also makes technical and conforming changes.
State Revenue Impact
According to BOE, “Granting disabled veterans the homeowners’ exemption would result in an estimated annual revenue loss of $4.7 million (1% property tax rate × $474 million exemption value) to local governments.”
Comments
1. Purpose of the bill. According to the author, “Veterans have made significant sacrifices in service to our country. They have put their lives on the line, spent time away from their families, and faced numerous physical and mental challenges in their pursuit of safety and security for our Country. And yet despite all of this, many veterans continue to face difficulties as they transition back to civilian life. One of the biggest challenges veterans face is the financial burden of owning a home. For many veterans, owning a home can be a difficult dream to achieve and maintain. Many veterans struggle to make ends meet despite their service, especially if they are on a fixed income or facing other financial challenges. In California, the current veterans’ exemption provides veterans and their families with a $4,000 reduction in the taxable value of their property to help ease the financial burden of owning a home. This lifeline can be especially important for veterans who are facing other challenges such as medical bills or disabilities as a result of their service. Unfortunately, the amount of the current veteran exemption has remained the same since its creation, along with limitations on the maximum eligible value of a property owned by a veteran. Furthermore, because the homeowners’ exemption is nearly twice the amount of the veteran exemption at $7,000, most California veteran homeowners choose the homeowners’ exemption, leaving the veterans’ exemption underutilized. SCA 4 and SB 623 seek to allow a veteran property owner who qualifies for the veterans’ exemption or the disabled veterans’ exemption to also receive the homeowners’ exemption. These measures will provide much needed tax relief for veterans and their families. In California, we have a proud tradition of supporting our veterans. We recognize the sacrifices that they have made and we are committed to providing them with the support they need to succeed and stay here in California after their service. SCA 4 and SB 623 exemplifies that commitment and is a way for California to show that we value our veterans and their contributions to our great state.”
2. Who benefits? SCA 4’s changes for the veterans’ exemption should increase the current amount of veterans’ exemption claimants beyond the current number of zero. First, by deleting the asset test, veteran taxpayers owning property with a value of more than $5,000 or $10,000 would qualify. Second, the measure allows the Legislature to increase the exemption amount past the current $4,000, which if set higher than the $7,000 homeowners’ exemption amount, would likely result in more taxpayers claiming the veterans’ exemption instead. Additionally, only veterans who have lost two or more limbs, are totally blind, or totally disabled as a result of a service-connected injury qualify for the disabled veterans’ exemption, while the veterans’ exemption can be claimed by any veteran who served during a specified war or campaign, was issued a medal by Congress during time of peace, or was discharged as a result of a service-connected disability. As a result, SCA 4 could benefit those veterans with service-connected disabilities, but who do not meet the current criteria for the disabled veterans’ exemption. Lastly, SCA 4 directly benefits disabled veterans by allowing them to potentially stack up to three exemptions (disabled veterans’, veterans’, and homeowners’) instead of one.
3. Been a long time. Little guidance exists for the veterans’ exemption because the exemption is functionally obsolete. Additionally, its statutory implementation provisions are outdated. For example, the last war the Legislature added onto the statutory list for veterans’ exemption eligibility was the “Campaign against the Viet Cong and North Vietnamese Communists in South Vietnam, August 5, 1964, to May 8, 1975.” The military forces of the United States have been involved in several other conflicts since (with new ones seemingly occurring every day), and reference to pre-World War II wars and conflicts can likely be pared.
4. Togetherness. SB 623 (Archuleta) makes changes to statute to implement SCA 4’s constitutional change to allow eligible taxpayers to also claim both the homeowners’ as well as either the disabled veterans’ or veterans’ exemption. The Committee will also consider that bill at its January 14, 2026, hearing.
5. Conforming change. In 2022, the Legislature enacted AB 1715 (Muratsuchi), which updated several provisions in state law, including the disabled veterans’ exemption, to include the United States (US) Space Force among the lists of Armed Forces entities. However, the part of the Constitution SCA 4 seeks to amend only refers to the United States Army, Navy, Air Force, Marine Corps, Coast Guard, or Revenue Marine (Revenue Cutter) Service.
6. One way or another. If approved by voters, SCA 4 would allow disabled veterans to also claim the homeowners’ exemption, equal to $7,000 in value or $70 in tax at the 1% rate. Last year, the Senate approved SB 296 (Archuleta), which suspends the current disabled veterans’ basic and low-income exemptions and instead provides a full property tax exemption for the principal residence of a disabled veteran or the surviving unmarried spouse of a qualified veteran. SB 296 provided that its full exemption was in lieu of the veterans’ or homeowners’ exemption, so if both it and SCA 4 are enacted, a disabled veteran could not claim an exemption that exceeds the full value of their property. However, the Assembly Revenue & Taxation Committee held SB 296 on its suspense file.
9. Related legislation. SCA 4 is largely identical to SCA 6 (Archuleta, 2023). The Senate approved that measure, but it died at the Assembly Desk.
10. Double-referred. The Senate Rules Committee ordered a double referral of SCA 4. First, to the Committee on Revenue & Taxation, and second to the Committee on Elections & Constitutional Amendments.
Support and Opposition
(1/8/26)
Support: California State Board of Equalization
Howard Jarvis Taxpayers Association
Opposition: None received.
-- END --
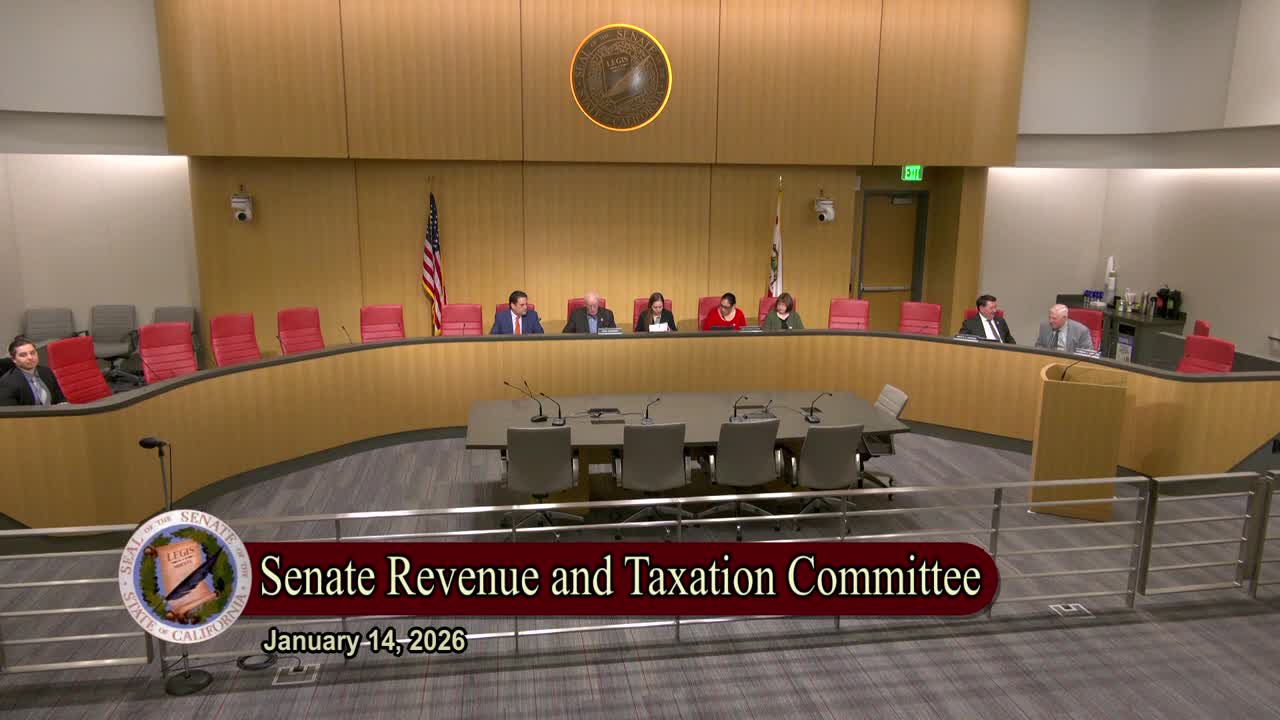
Discussed in Hearing
 6MIN
Senate Standing Committee on Revenue and Taxation
Bill Author