AB 1249: Sales and use taxes: exemption: tax holiday: school supplies.
- Session Year: 2023-2024
- House: Assembly
- Latest Version Date: 2023-02-16
Current Status:
Failed
(2024-02-01: From committee: Filed with the Chief Clerk pursuant to Joint Rule 56.)
Introduced
In Committee
First Chamber
In Committee
Second Chamber
Enacted
What does this bill do?
This bill creates a temporary two-day sales tax holiday each year to lower costs for families and teachers buying qualifying school supplies. It exempts common items under $100 (like pens, notebooks, backpacks, markers, glue, and rulers) and the first $1,000 of the purchase price for personal computers and related electronics. The bill runs from 2024 through 2028, requires the tax agency to report to the Legislature on use of the exemption, and prevents the state from reimbursing local governments for any lost local sales tax revenue.
The summary is provided by generative AI which can make mistakes. For original language, please view the details in the table below.
Existing sales and use tax laws impose taxes on retailers measured by the gross receipts from the sale of tangible personal property sold at retail in this state, or on the storage, use, or other consumption in this state of tangible personal property purchased from a retailer for storage, use, or other consumption in this state, and provides various exemptions from the taxes imposed by those laws.
This bill would, on and after January 1, 2024, and before January 1, 2029, exempt from those taxes the gross receipts from the sale of, and the storage, use, or other consumption of, qualified school supplies, as defined, for the two-day period beginning at 12:01 a.m. on the third Saturday of July of each year and ending at 11:59 p.m. on the following day.
Existing law requires a bill that would authorize a new tax expenditure under the Sales and Use Tax Law to identify specific goals, purposes, and objectives that the tax expenditure will achieve, and detailed performance indicators and data collection requirements for determining whether the tax expenditure achieves these goals, purposes, and objectives.
This bill would make findings specifying the goal, purpose, and objective of the sales and use tax exemption provided by this bill and the performance indicator to be used, and would require, on or before January 10, 2025, the California Department of Tax and Fee Administration to provide a report to the Assembly Revenue and Taxation Committee and the Senate Governance and Finance Committee on the use of the tax exemption.
The Bradley-Burns Uniform Local Sales and Use Tax Law authorizes counties and cities to impose local sales and use taxes in conformity with the Sales and Use Tax Law, and existing laws authorize districts, as specified, to impose transactions and use taxes in accordance with the Transactions and Use Tax Law, which generally conforms to the Sales and Use Tax Law. Amendments to the Sales and Use Tax Law are automatically incorporated into the local tax laws.
Existing law requires the state to reimburse counties and cities for revenue losses caused by the enactment of sales and use tax exemptions.
This bill would provide that, notwithstanding Section 2230 of the Revenue and Taxation Code, no appropriation is made and the state shall not reimburse any local agencies for sales and use tax revenues lost by them pursuant to this bill.
This bill would take effect immediately as a tax levy.
(a)On and after January 1, 2024, and before January 1, 2029, there are exempted from the taxes imposed by this part the gross receipts from the sale of, and the storage, use, or other consumption in this state of, qualified school supplies for the two-day period beginning at 12:01 a.m. on the third Saturday of July of each year and ending at 11:59 p.m. on the following day.
(b)This section shall become inoperative on January 1, 2029, and as of that date is repealed.
(c)For purposes of this section, qualified school supplies means both of the following:
(1)Any of the following items that has a sales price of less than one hundred dollars ($100):
(A)Binders.
(B)Blackboard chalk.
(C)Book bags.
(D)Calculators.
(E)Cellophane tape.
(F)Compasses.
(G)Composition books.
(H)Crayons.
(I)Erasers.
(J)Folders, including expandable, pocket, plastic, and manila folders.
(K)Glue, paste, and paste sticks.
(L)Highlighters.
(M)Index cards.
(N)Index card boxes.
(O)Legal pads.
(P)Lunch boxes.
(Q)Markers, including dry erase markers.
(R)Notebooks.
(S)Paper, including loose leaf ruled notebook, copy, graph, tracing, manila, colored, and construction paper, and poster board.
(T)Pencil boxes and other school supply boxes.
(U)Pencil sharpeners.
(V)Pencils.
(W)Pens.
(X)Protractors.
(Y)Rulers.
(Z)Scissors.
(AA)Writing tablets.
(2)The first one thousand dollars ($1,000) of the total sales price for any of the following electronic items purchased for noncommercial home or personal use:
(A)Personal Computers.
(B)Laptops.
(C)Printers.
(D)Tablets.
(E)Chargers.
(F)Batteries.
(G)Computer mice.
(H)Keyboards.
(I)Laptop cases.
(J)WiFi routers.
SEC. 2.(a)For the purposes of complying with Section 41 of the Revenue and Taxation Code, the Legislature finds and declares the following:
(1)The goal, purpose, or objective of Section 6372 of the Revenue and Taxation Code, as added by this act, hereafter tax exemption, is to relieve the financial burden for families and teachers buying school supplies.
(2)The performance indicator for the Legislature to use when measuring whether the tax exemption meets the goal, purpose, or objective specified in paragraph (1) is the number of sales made that qualified for the tax exemption.
(b)On or before January 10, 2025, the California Department of Tax and Fee Administration shall provide a report to the Assembly Revenue and Taxation Committee and the Senate Governance and Finance Committee on the use of the tax exemption. The report shall be provided in compliance with Section 9795 of the Government Code.
SEC. 3.Notwithstanding Section 2230 of the Revenue and Taxation Code, no appropriation is made by this act and the state shall not reimburse any local agency for any sales and use tax revenues lost by it under this act.
SEC. 4.This act provides for a tax levy within the meaning of Article IV of the California Constitution and shall go into immediate effect.
|
Date
|
Status
|
|---|---|
| Feb 1, 2024 | From committee: Filed with the Chief Clerk pursuant to Joint Rule 56. |
| Jan 31, 2024 | Died pursuant to Art. IV, Sec. 10(c) of the Constitution. |
| May 1, 2023 | In committee: Set, final hearing. Held under submission. |
| Apr 11, 2023 | In committee: Set, second hearing. Referred to REV. & TAX. suspense file. |
| Mar 21, 2023 | In committee: Set, first hearing. Hearing canceled at the request of author. |
| Mar 2, 2023 | Referred to Com. on REV. & TAX. |
| Feb 17, 2023 | From printer. May be heard in committee March 19. |
| Feb 16, 2023 | Read first time. To print. |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| California Federation Of Teachers | ** Against | |
| California Tax Reform Association | * Against | Apr 10, 2023 |
| Howard Jarvis Taxpayers Association | * Support | Apr 10, 2023 |
| Los Angeles County Office Of Education | ** Support |
Date of Hearing: May 1, 2023
ASSEMBLY COMMITTEE ON REVENUE AND TAXATION
Jacqui Irwin, Chair
ABPCA Bill Id:AB 1249 (
Author:Ta) – As Introduced Ver:February 16, 2023
SUSPENSE
Majority vote. Tax levy. Fiscal committee.
SUBJECT: Sales and use taxes: exemption: tax holiday: school supplies
SUMMARY: Provides an exemption under the Sales and Use Tax (SUT) Law for "qualified school supplies" during the two-day period beginning at 12:01 a.m. on the third Saturday of July of each year, and ending at 11:59 p.m. on the following day. Specifically, this bill:
- Defines "qualified school supplies" as:
- Any of the following items that has a sales price of less than $100:
- Binders;
- Blackboard chalk;
- Book bags:
- Calculators;
- Cellophane tape;
- Compasses;
- Composition books;
- Crayons;
- Erasers;
- Folders, including expandable, pocket, plastic, and manila folders;
- Glue, paste, and paste sticks;
- Highlighters;
- Index cards;
- Index card boxes;
- Legal pads;
- Lunch boxes;
- Markers, including dry erase markers;
- Notebooks;
- Paper, including loose leaf ruled notebook, copy, graph, tracing, manila, colored, and construction paper, and poster board;
- Pencil boxes and other school supply boxes;
- Pencil sharpeners;
- Pencils;
- Pens;
- Protractors;
- Rulers;
- Scissors; and,
- Writing tablets; and,
- The first $1,000 of the total sales price for any of the following electronic items purchased for noncommercial home or personal use:
- Personal computers;
- Laptops;
- Printers;
- Tablets;
- Chargers;
- Batteries;
- Computer mice;
- Keyboards;
- Laptop cases; and,
- WiFi routers.
- Any of the following items that has a sales price of less than $100:
- Contains the following statement of findings and declarations to comply with Revenue and Taxation Code (R&TC) Section 41:
- The goal, purpose, or objective of this exemption is to relieve the financial burden for families and teachers buying school supplies; and,
- The performance indicator for the Legislature to use when measuring whether the tax exemption meets the goal, purpose, or objective specified above is the number of sales made that qualified for the tax exemption.
- Requires the California Department of Tax and Fee Administration (CDTFA), by January 10, 2025, to provide a report to the Assembly Revenue and Taxation Committee and the Senate Governance and Finance Committee on the use of the tax exemption. This report shall be provided in compliance with Government Code Section 9795.
- Provides that, notwithstanding existing law, the state shall not reimburse any local agency for any SUT revenues lost as a result of this exemption.
- Takes immediate effect as a tax levy.
- Sunsets on January 1, 2029.
EXISTING LAW:
- Imposes a sales tax on retailers for the privilege of selling tangible personal property (TPP), absent a specific exemption. The tax is based upon the retailer's gross receipts from TPP sales in this state. (R&TC Section 6001 et seq.)
- Imposes a complimentary use tax on the storage, use, or other consumption of TPP generally purchased out-of-state and brought into California. The use tax is imposed on the purchaser; and unless the purchaser pays the use tax to an entity registered to collect California's use tax, the purchaser remains liable for the tax. The use tax is set at the same rate as the state's sales tax and must generally be remitted to the CDTFA. (R&TC Section 6001 et seq.)
- Requires any bill introduced on or after January 1, 2020, that authorizes a SUT exemption, to contain all of the following:
- Specific goals, purposes, and objectives that the tax expenditure will achieve;
- Detailed performance indicators for the Legislature to use when measuring whether the tax expenditure meets the goals, purposes, and objectives stated in the bill; and,
- Specified data collection requirements to enable the Legislature to determine whether the tax expenditure is meeting, failing to meet, or exceeding those specific goals, purposes, and objectives. (R&TC Section 41(a).)
- Specific goals, purposes, and objectives that the tax expenditure will achieve;
FISCAL EFFECT: While a detailed revenue estimate is pending, the CDTFA estimates that annual revenue losses are likely to exceed $150,000 annually.
COMMENTS:
- The author has provided the following statement in support of this bill:
AB 1249 would give a weekend of tax-exempt materials for their children's school supplies. This bill is also helpful to assist our California businesses that have been hurt due to the global pandemic that encouraged people to order items online. Whereas, AB 1249 would encourage the purchase of school supplies during this one weekend before schools start.
- This bill is supported by the Los Angeles County Office of Education, which notes:
School supplies are a necessity. Preparing a child for school can be an additional financial pressure for families struggling to meet all their obligations, and sales tax is a bigger problem for low-income Californians. According to the San Francisco Bay Area Planning and Urban Research Association, California's high sales tax contributes to "structural inequality" because "every consumer pays the same tax rate at the register, but low-income households pay a higher percentage of their income because they have fewer resources to begin with."
- This bill is opposed by the California Federation of Teachers, which notes:
Public education in California is mostly funded through the mechanisms created by Proposition 98. At minimum during test 1 years, the public k-12 and community college system are provided approximately 40 cents for every dollar in revenue from the state personal income tax, the corporate income tax, and the state's sales and use tax.
By creating ways in which the revenue of proposition 98 is lowered due to tax holidays, credits, and other exemptions, the in-class revenue of California's students will carry the burden, accounting for almost half of the lost revenue that will come out of our classrooms.
- Committee Staff Comments:
- What is a "tax expenditure"? Existing law provides various credits, deductions, exclusions, and exemptions for particular taxpayer groups. In the late 1960s, U.S. Treasury officials began arguing that these features of the tax law should be referred to as "expenditures" since they are generally enacted to accomplish some governmental purpose and there is a determinable cost associated with each (in the form of foregone revenues).
- What is a "tax expenditure"? Existing law provides various credits, deductions, exclusions, and exemptions for particular taxpayer groups. In the late 1960s, U.S. Treasury officials began arguing that these features of the tax law should be referred to as "expenditures" since they are generally enacted to accomplish some governmental purpose and there is a determinable cost associated with each (in the form of foregone revenues).
As the Department of Finance notes in its annual Tax Expenditure Report, there are several key differences between tax expenditures and direct expenditures. First, tax expenditures are reviewed less frequently than direct expenditures. Second, there is generally no control over the amount of revenue losses associated with any given tax expenditure. Finally, it should also be noted that, once enacted, it takes a two-thirds vote to rescind an existing tax expenditure absent a sunset date. This effectively results in a "one-way ratchet" whereby tax expenditures can be conferred by majority vote, but cannot be rescinded, irrespective of their efficacy or cost, without a supermajority vote.
- An overview of the SUT Law: The SUT represents the state's third largest source of General Fund (GF) revenues. Nevertheless, the past several decades have seen a dramatic reduction in the state's reliance on the SUT and a corresponding increase in its reliance on personal income tax revenues. In fiscal year (FY) 2023-24, SUT revenues are estimated to comprise only 15.9% of the state's GF revenues, down from nearly 60% in FY 1950-51.
- What accounts for the state's reduced reliance on SUT revenues? The SUT Law was enacted in a very different era. In the 1930s, California's economy was largely dominated by manufacturing, and residents mostly bought and sold tangible goods. Thus, in establishing the base for a new consumption tax, it made sense to impose the tax on sales of TPP, defined as personal property that may be "seen, weighed, measured, felt, or touched." Over the past 80 years, however, California's economy has seen dramatic growth in the service and information sectors, resulting in a significant erosion of the SUT base. For example, the Commission on the 21st Century Economy noted that spending on taxable goods represented 34.6% of personal income in 2008, down from 55.4% in 1980. As a result, tax experts and economists from across the political spectrum argue that California should expand its SUT base.
It could be argued that, while well-intentioned, additional SUT exemptions further erode an already shrinking SUT base. This, in turn, increases fiscal pressures to maintain or even increase California's relatively high SUT rate. High rates arguably promote non-compliance and encourage out-of-state purchases, placing California retailers at a competitive disadvantage. High rates also risk impacting consumer decision-making, which runs counter to widely accepted principles of sound tax policy.
- What would this bill do? This bill would establish a sales tax holiday for "qualified school supplies" during the two-day period beginning on the third Saturday in July. This bill defines "qualified school supplies" to include a wide array of items with a sales price of less than $100, including binders, book bags, calculators, paper, and pens. This bill also includes within the term the first $1,000 for specified electronic items purchased for noncommercial home or personal use, including computers, printers, tablets, and WiFi routers.
- This bill provides a very broad exemption: According to the author, this bill is designed to provide tax relief to parents buying school supplies for their children. The proposed exemption, however, is far broader in scope. Specifically, nothing in this bill requires items to be purchased for use by students. In addition, this exemption is not targeted to low- or even moderate-income consumers, but is available to all purchasers regardless of income. For example, this bill includes within the definition of "qualified school supplies" pens with a sales price of less than $100. Thus, if an individual with no children were to purchase a Waterman fountain pen for $95 during the sales tax holiday, that purchase would be exempt under this bill. In addition, under this bill a commercial office manager could purchase a wide array of office supplies for non-school purposes during this tax holiday. Any effort, however, to limit the sales tax exemption based on the end use of the property would be difficult if not impossible to administer. To assist struggling parents with school-age children, the author may wish to instead create a grant program to provide vouchers to families with incomes below a certain level.
- A burden on retailers: This bill creates a two-day sales tax holiday. The administrative burden on retailers is quite high with short-term exemptions as retailers must change the tax rate for the covered items twice in a single week.
- Policy on tax expenditures: Both R&TC Section 41 and Committee policy require any tax expenditure bill to outline specific goals, purposes, and objectives that the tax expenditure will achieve, along with detailed performance indicators for the Legislature to use when measuring whether the tax expenditure meets those stated goals, purposes, and objectives. A tax expenditure bill will not be eligible for a Committee vote unless it has complied with these requirements. While this bill includes language complying with Section 41, it measures the exemption's efficacy by the number of exempt sales made. The Committee may wish to consider whether overall utilization is a sufficient metric to gauge this bill's goal of defraying the cost of back-to-school products.
In addition to the R&TC Section 41 requirements, this Committee's policy also requires that all tax expenditure proposals contain an appropriate sunset provision to be eligible for a vote. This bill fully complies with this policy. - Prior legislation:
- AB 217 (Valladares), of the 2021-22 Legislative Session, would have provided a sales tax holiday for specified back-to-school products. AB 217 was held on the Assembly Appropriations Committee's Suspense File.
- AB 1007 (Cook), of the 2011-12 Legislative Session, would have provided a sales tax holiday for specified back-to-school products. AB 1007 was held on the Assembly Appropriations Committee's Suspense File.
- AB 548 (Garcia), of the 2005-06 Legislative Session, would have provided a sales tax holiday for specified back-to-school products. AB 548 was held on this Committee's Suspense File.
- AB 1185 (Mountjoy), of the 2001-02 Legislative Session, would have provided a partial sales tax exemption for clothing or footwear sold during a specified annual period. AB 1185 was held on this Committee's Suspense File.
- AB 944 (Cardenas), of the 1999-2000 Legislative Session, would have established a three-day sales tax holiday for specified articles of clothing and footwear purchased for $100 or less. AB 944 was never heard by the Senate Committee on Revenue and Taxation.
- AB 1320 (Ashburn), of the 1999-2000 Legislative Session, would have provided a one-week sales tax holiday for any item of TPP purchased for less than $500. AB 1320 failed passage in this Committee.
- AB 217 (Valladares), of the 2021-22 Legislative Session, would have provided a sales tax holiday for specified back-to-school products. AB 217 was held on the Assembly Appropriations Committee's Suspense File.
- What would this bill do? This bill would establish a sales tax holiday for "qualified school supplies" during the two-day period beginning on the third Saturday in July. This bill defines "qualified school supplies" to include a wide array of items with a sales price of less than $100, including binders, book bags, calculators, paper, and pens. This bill also includes within the term the first $1,000 for specified electronic items purchased for noncommercial home or personal use, including computers, printers, tablets, and WiFi routers.
REGISTERED SUPPORT / OPPOSITION:
Support
Los Angeles County Office of Education
Opposition
California Federation of Teachers
Analysis Prepared by: M. David Ruff / REV. & TAX. / (916) 319-2098
Date of Hearing: April 10, 2023
ASSEMBLY COMMITTEE ON REVENUE AND TAXATION
Jacqui Irwin, Chair
ABPCA Bill Id:AB 1249 (
Author:Ta) – As Introduced Ver:February 16, 2023
Majority vote. Tax levy. Fiscal committee.
SUBJECT: Sales and use taxes: exemption: tax holiday: school supplies
SUMMARY: Provides an exemption under the Sales and Use Tax (SUT) Law for "qualified school supplies" during the two-day period beginning at 12:01 a.m. on the third Saturday of July of each year, and ending at 11:59 p.m. on the following day. Specifically, this bill:
- Defines "qualified school supplies" as:
- Any of the following items that has a sales price of less than $100:
- Binders;
- Blackboard chalk;
- Book bags:
- Calculators;
- Cellophane tape;
- Compasses;
- Composition books;
- Crayons;
- Erasers;
- Folders, including expandable, pocket, plastic, and manila folders;
- Glue, paste, and paste sticks;
- Highlighters;
- Index cards;
- Index card boxes;
- Legal pads;
- Lunch boxes;
- Markers, including dry erase markers;
- Notebooks;
- Paper, including loose leaf ruled notebook, copy, graph, tracing, manila, colored, and construction paper, and poster board;
- Pencil boxes and other school supply boxes;
- Pencil sharpeners;
- Pencils;
- Pens;
- Protractors;
- Rulers;
- Scissors; and,
- Writing tablets; and,
- The first $1,000 of the total sales price for any of the following electronic items purchased for noncommercial home or personal use:
- Personal computers;
- Laptops;
- Printers;
- Tablets;
- Chargers;
- Batteries;
- Computer mice;
- Keyboards;
- Laptop cases; and,
- WiFi routers.
- Any of the following items that has a sales price of less than $100:
- Contains the following statement of findings and declarations to comply with R&TC Section 41:
- The goal, purpose, or objective of this exemption is to relieve the financial burden for families and teachers buying school supplies; and,
- The performance indicator for the Legislature to use when measuring whether the tax exemption meets the goal, purpose, or objective specified above is the number of sales made that qualified for the tax exemption.
- Requires the California Department of Tax and Fee Administration (CDTFA), by January 10, 2025, to provide a report to the Assembly Revenue and Taxation Committee and the Senate Governance and Finance Committee on the use of the tax exemption. This report shall be provided in compliance with Government Code Section 9795.
- Provides that, notwithstanding existing law, the state shall not reimburse any local agency for any SUT revenues lost as a result of this exemption.
- Takes immediate effect as a tax levy.
- Sunsets on January 1, 2029.
EXISTING LAW:
- Imposes a sales tax on retailers for the privilege of selling tangible personal property (TPP), absent a specific exemption. The tax is based upon the retailer's gross receipts from TPP sales in this state. (Revenue and Taxation Code (R&TC) Section 6001 et seq.)
- Imposes a complimentary use tax on the storage, use, or other consumption of TPP generally purchased out-of-state and brought into California. The use tax is imposed on the purchaser; and unless the purchaser pays the use tax to an entity registered to collect California's use tax, the purchaser remains liable for the tax. The use tax is set at the same rate as the state's sales tax and must generally be remitted to the CDTFA. (R&TC Section 6001 et seq.)
- Requires any bill introduced on or after January 1, 2020, that authorizes a SUT exemption, to contain all of the following:
- Specific goals, purposes, and objectives that the tax expenditure will achieve;
- Detailed performance indicators for the Legislature to use when measuring whether the tax expenditure meets the goals, purposes, and objectives stated in the bill; and,
- Specified data collection requirements to enable the Legislature to determine whether the tax expenditure is meeting, failing to meet, or exceeding those specific goals, purposes, and objectives. (R&TC Section 41(a).)
- Specific goals, purposes, and objectives that the tax expenditure will achieve;
FISCAL EFFECT: While a detailed revenue estimate is pending, the CDTFA estimates that annual revenue losses are likely to exceed $150,000 annually.
COMMENTS:
- The author has provided the following statement in support of this bill:
AB 1249 would give a weekend of tax-exempt materials for their children's school supplies. This bill is also helpful to assist our California businesses that have been hurt due to the global pandemic that encouraged people to order items online. Whereas, AB 1249 would encourage the purchase of school supplies during this one weekend before schools start.
- Committee Staff Comments:
- What is a "tax expenditure"? Existing law provides various credits, deductions, exclusions, and exemptions for particular taxpayer groups. In the late 1960s, U.S. Treasury officials began arguing that these features of the tax law should be referred to as "expenditures" since they are generally enacted to accomplish some governmental purpose and there is a determinable cost associated with each (in the form of foregone revenues).
- What is a "tax expenditure"? Existing law provides various credits, deductions, exclusions, and exemptions for particular taxpayer groups. In the late 1960s, U.S. Treasury officials began arguing that these features of the tax law should be referred to as "expenditures" since they are generally enacted to accomplish some governmental purpose and there is a determinable cost associated with each (in the form of foregone revenues).
As the Department of Finance notes in its annual Tax Expenditure Report, there are several key differences between tax expenditures and direct expenditures. First, tax expenditures are reviewed less frequently than direct expenditures. Second, there is generally no control over the amount of revenue losses associated with any given tax expenditure. Finally, it should also be noted that, once enacted, it takes a two-thirds vote to rescind an existing tax expenditure absent a sunset date. This effectively results in a "one-way ratchet" whereby tax expenditures can be conferred by majority vote, but cannot be rescinded, irrespective of their efficacy or cost, without a supermajority vote.
- An overview of the SUT Law: The SUT represents the state's third largest source of General Fund (GF) revenues. Nevertheless, the past several decades have seen a dramatic reduction in the state's reliance on the SUT and a corresponding increase in its reliance on personal income tax revenues. In fiscal year (FY) 2023-24, SUT revenues are estimated to comprise only 15.9% of the state's GF revenues, down from nearly 60% in FY 1950-51.
- What accounts for the state's reduced reliance on SUT revenues? The SUT Law was enacted in a very different era. In the 1930s, California's economy was largely dominated by manufacturing, and residents mostly bought and sold tangible goods. Thus, in establishing the base for a new consumption tax, it made sense to impose the tax on sales of TPP, defined as personal property that may be "seen, weighed, measured, felt, or touched." Over the past 80 years, however, California's economy has seen dramatic growth in the service and information sectors, resulting in a significant erosion of the SUT base. For example, the Commission on the 21st Century Economy noted that spending on taxable goods represented 34.6% of personal income in 2008, down from 55.4% in 1980. As a result, tax experts and economists from across the political spectrum argue that California should expand its SUT base.
It could be argued that, while well-intentioned, additional SUT exemptions further erode an already shrinking SUT base. This, in turn, increases fiscal pressures to maintain or even increase California's relatively high SUT rate. High rates arguably promote non-compliance and encourage out-of-state purchases, placing California retailers at a competitive disadvantage. High rates also risk impacting consumer decision-making, which runs counter to widely accepted principles of sound tax policy.
- What would this bill do? This bill would establish a sales tax holiday for "qualified school supplies" during the two-day period beginning on the third Saturday in July. This bill defines "qualified school supplies" to include a wide array of items with a sales price of less than $100, including binders, book bags, calculators, paper, and pens. This bill also includes within the term the first $1,000 for specified electronic items purchased for noncommercial home or personal use, including computers, printers, tablets, and WiFi routers.
- This bill provides a very broad exemption: According to the author, this bill is designed to provide tax relief to parents buying school supplies for their children. The proposed exemption, however, is far broader in scope. Specifically, nothing in this bill requires items to be purchased for use by students. In addition, this exemption is not targeted to low- or even moderate-income consumers, but is available to all purchasers regardless of income. For example, this bill includes within the definition of "qualified school supplies" pens with a sales price of less than $100. Thus, if an individual with no children were to purchase a Waterman fountain pen for $95 during the sales tax holiday, that purchase would be exempt under this bill. In addition, under this bill a commercial office manager could purchase a wide array of office supplies for non-school purposes during this tax holiday. Any effort, however, to limit the sales tax exemption based on the end use of the property would be difficult if not impossible to administer. To assist struggling parents with school-age children, the author may wish to instead create a grant program to provide vouchers to families with incomes below a certain level.
- A burden on retailers: This bill creates a two-day sales tax holiday. The administrative burden on retailers is quite high with short-term exemptions as retailers must change the tax rate for the covered items twice in a single week.
- Policy on tax expenditures: Both R&TC Section 41 and Committee policy require any tax expenditure bill to outline specific goals, purposes, and objectives that the tax expenditure will achieve, along with detailed performance indicators for the Legislature to use when measuring whether the tax expenditure meets those stated goals, purposes, and objectives. A tax expenditure bill will not be eligible for a Committee vote unless it has complied with these requirements. While this bill includes language complying with Section 41, it measures the exemption's efficacy by the number of exempt sales made. The Committee may wish to consider whether overall utilization is a sufficient metric to gauge this bill's goal of defraying the cost of back-to-school products.
In addition to the R&TC Section 41 requirements, this Committee's policy also requires that all tax expenditure proposals contain an appropriate sunset provision to be eligible for a vote. This bill fully complies with this policy. - Prior legislation:
- AB 217 (Valladares), of the 2021-22 Legislative Session, would have provided a sales tax holiday for specified back-to-school products. AB 217 was held on the Assembly Appropriations Committee's Suspense File.
- AB 1007 (Cook), of the 2011-12 Legislative Session, would have provided a sales tax holiday for specified back-to-school products. AB 1007 was held on the Assembly Appropriations Committee's Suspense File.
- AB 548 (Garcia), of the 2005-06 Legislative Session, would have provided a sales tax holiday for specified back-to-school products. AB 548 was held on this Committee's Suspense File.
- AB 1185 (Mountjoy), of the 2001-02 Legislative Session, would have provided a partial sales tax exemption for clothing or footwear sold during a specified annual period. AB 1185 was held on this Committee's Suspense File.
- AB 944 (Cardenas), of the 1999-2000 Legislative Session, would have established a three-day sales tax holiday for specified articles of clothing and footwear purchased for $100 or less. AB 944 was never heard by the Senate Committee on Revenue and Taxation.
- AB 1320 (Ashburn), of the 1999-2000 Legislative Session, would have provided a one-week sales tax holiday for any item of TPP purchased for less than $500. AB 1320 failed passage in this Committee.
- AB 217 (Valladares), of the 2021-22 Legislative Session, would have provided a sales tax holiday for specified back-to-school products. AB 217 was held on the Assembly Appropriations Committee's Suspense File.
- What would this bill do? This bill would establish a sales tax holiday for "qualified school supplies" during the two-day period beginning on the third Saturday in July. This bill defines "qualified school supplies" to include a wide array of items with a sales price of less than $100, including binders, book bags, calculators, paper, and pens. This bill also includes within the term the first $1,000 for specified electronic items purchased for noncommercial home or personal use, including computers, printers, tablets, and WiFi routers.
REGISTERED SUPPORT / OPPOSITION:
Support
None on file
Opposition
None on file
Analysis Prepared by: M. David Ruff / REV. & TAX. / (916) 319-2098
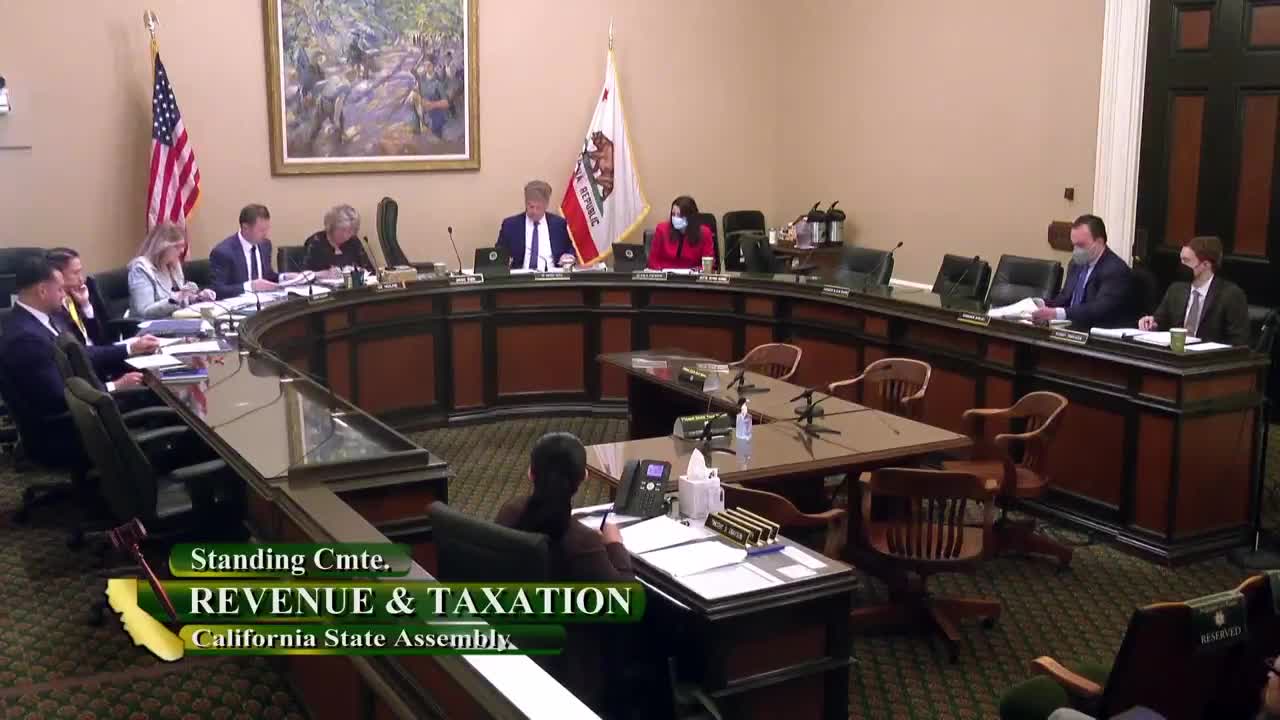
Discussed in Hearing
 5MIN
Assembly Standing Committee on Revenue and Taxation
Bill Author
Bill Co-Author(s):