AB 2131: Minimum franchise tax.
- Session Year: 2017-2018
- House: Assembly
- Latest Version Date: 2018-04-02
Existing law, generally, imposes a minimum franchise tax of $800, except as provided, on every corporation incorporated in this state, qualified to transact intrastate business in this state, or doing business in this state.
This bill would reduce the minimum franchise tax to $400 for taxable years beginning on or after January 1, 2019. 2019, and before January 1, 2024.
This bill would take effect immediately as a tax levy.
Existing law, generally, imposes a minimum franchise tax of $800, except as provided, on every corporation incorporated in this state, qualified to transact intrastate business in this state, or doing business in this state.
This bill would reduce the minimum franchise tax to $400 for taxable years beginning on or after January 1, 2019.
This bill would take effect immediately as a tax levy.
(a)Every corporation described in subdivision (b) shall be subject to the minimum franchise tax specified in subdivision (d) from the earlier of the date of incorporation, qualification, or commencing to do business within this state, until the effective date of dissolution or withdrawal as provided in Section 23331 or, if later, the date the corporation ceases to do business within the limits of this state.
(b)Unless expressly exempted by this part or the California Constitution, subdivision (a) shall apply to each of the following:
(1)Every corporation that is incorporated under the laws of this state.
(2)Every corporation that is qualified to transact intrastate business in this state pursuant to Chapter 21 (commencing with Section 2100) of Division 1 of Title 1 of the Corporations Code.
(3)Every corporation that is doing business in this state.
(c)The following entities are not subject to the minimum franchise tax specified in this section:
(1)Credit unions.
(2)Nonprofit cooperative associations organized pursuant to Chapter 1 (commencing with Section 54001) of Division 20 of the Food and Agricultural Code that have been issued the certificate of the board of supervisors prepared pursuant to Section 54042 of the Food and Agricultural Code. The association shall be exempt from the minimum franchise tax for five consecutive taxable years, commencing with the first taxable year for which the certificate is issued pursuant to subdivision (b) of Section 54042 of the Food and Agricultural Code. This paragraph only applies to nonprofit cooperative associations organized on or after January 1, 1994.
(d)(1)Except as provided in paragraph (2), paragraph (1) of subdivision (f) of Section 23151, paragraph (1) of subdivision (f) of Section 23181, and paragraph (1) of subdivision (c) of Section 23183, corporations subject to the minimum franchise tax shall pay annually to the state a minimum franchise tax of:
(A)Eight hundred dollars ($800) for taxable years beginning before January 1, 2019. 2019, and on or after January 1, 2024.
(B)Four hundred dollars ($400) for taxable years beginning on or after January 1, 2019. 2019, and before January 1, 2024.
(2)The minimum franchise tax shall be twenty-five dollars ($25) for each of the following:
(A)A corporation formed under the laws of this state whose principal business when formed was gold mining, which is inactive and has not done business within the limits of the state since 1950.
(B)A corporation formed under the laws of this state whose principal business when formed was quicksilver mining, which is inactive and has not done business within the limits of the state since 1971, or has been inactive for a period of 24 consecutive months or more.
(3)For purposes of paragraph (2), a corporation shall not be considered to have done business if it engages in business other than mining.
(e)Notwithstanding subdivision (a), for taxable years beginning on or after January 1, 1999, and before January 1, 2000, every qualified new corporation shall pay annually to the state a minimum franchise tax of five hundred dollars ($500) for the second taxable year. This subdivision shall apply to any corporation that is a qualified new corporation and is incorporated on or after January 1, 1999, and before January 1, 2000.
(1)The determination of the gross receipts of a corporation, for purposes of this subdivision, shall be made by including the gross receipts of each member of the commonly controlled group, as defined in Section 25105, of which the corporation is a member.
(2)Gross receipts, less returns and allowances reportable to this state, means the sum of the gross receipts from the production of business income, as defined in subdivision (a) of Section 25120, and the gross receipts from the production of nonbusiness income, as defined in subdivision (d) of Section 25120.
(3)Qualified new corporation means a corporation that is incorporated under the laws of this state or has qualified to transact intrastate business in this state, that begins business operations at or after the time of its incorporation and that reasonably estimates that it will have gross receipts, less returns and allowances, reportable to this state for the taxable year of one million dollars ($1,000,000) or less. Qualified new corporation does not include any corporation that began business operations as a sole proprietorship, a partnership, or any other form of business entity prior to its incorporation. This subdivision shall not apply to any corporation that reorganizes solely for the purpose of reducing its minimum franchise tax.
(4)This subdivision shall not apply to limited partnerships, as defined in Section 17935, limited liability companies, as defined in Section 17941, limited liability partnerships, as described in Section 17948, charitable corporations, as described in Section 23703, regulated investment companies, as defined in Section 851 of the Internal Revenue Code, relating to definition of regulated investment company, real estate investment trusts, as defined in Section 856 of the Internal Revenue Code, relating to definition of real estate investment, real estate mortgage investment conduits, as defined in Section 860D of the Internal Revenue Code, relating to REMIC defined, qualified Subchapter S subsidiaries, as defined in Section 1361(b)(3) of the Internal Revenue Code, relating to treatment of certain wholly owned subsidiaries, or to the formation of any subsidiary corporation, to the extent applicable.
(5)For any taxable year beginning on or after January 1, 1999, and before January 1, 2000, if a corporation has qualified to pay five hundred dollars ($500) for the second taxable year under this subdivision, but in its second taxable year, the corporations gross receipts, as determined under paragraphs (1) and (2), exceed one million dollars ($1,000,000), an additional tax in the amount equal to three hundred dollars ($300) for the second taxable year shall be due and payable by the corporation on the due date of its return, without regard to extension, for that year.
(f)(1)Notwithstanding subdivision (a), every corporation that incorporates or qualifies to do business in this state on or after January 1, 2000, shall not be subject to the minimum franchise tax for its first taxable year.
(2)This subdivision shall not apply to limited partnerships, as defined in Section 17935, limited liability companies, as defined in Section 17941, limited liability partnerships, as described in Section 17948, charitable corporations, as described in Section 23703, regulated investment companies, as defined in Section 851 of the Internal Revenue Code, relating to definition of regulated investment company, real estate investment trusts, as defined in Section 856 of the Internal Revenue Code, relating to definition of real estate investment, real estate mortgage investment conduits, as defined in Section 860D of the Internal Revenue Code, relating to REMIC defined, and qualified Subchapter S subsidiaries, as defined in Section 1361(b)(3) of the Internal Revenue Code, relating to treatment of certain wholly owned subsidiaries, to the extent applicable.
(3)This subdivision shall not apply to any corporation that reorganizes solely for the purpose of avoiding payment of its minimum franchise tax.
(g)Notwithstanding subdivision (a), a domestic corporation, as defined in Section 167 of the Corporations Code, that files a certificate of dissolution in the office of the Secretary of State pursuant to subdivision (b) of Section 1905 of the Corporations Code, prior to its amendment by the act amending this subdivision, and that does not thereafter do business shall not be subject to the minimum franchise tax for taxable years beginning on or after the date of that filing.
(h)The minimum franchise tax imposed by paragraph (1) of subdivision (d) shall not be increased by the Legislature by more than 10 percent during any calendar year.
(i)(1)Notwithstanding subdivision (a), a corporation that is a small business solely owned by a deployed member of the United States Armed Forces shall not be subject to the minimum franchise tax for any taxable year the owner is deployed and the corporation operates at a loss or ceases operation.
(2)The Franchise Tax Board may promulgate regulations as necessary or appropriate to carry out the purposes of this subdivision, including a definition for ceases operation.
(3)For the purposes of this subdivision, all of the following definitions apply:
(A)Deployed means being called to active duty or active service during a period when a Presidential Executive order specifies that the United States is engaged in combat or homeland defense. Deployed does not include either of the following:
(i)Temporary duty for the sole purpose of training or processing.
(ii)A permanent change of station.
(B)Operates at a loss means negative net income as defined in Section 24341.
(C)Small business means a corporation with total income from all sources derived from, or attributable, to attributable to, the state of two hundred fifty thousand dollars ($250,000) or less.
(4)This subdivision shall become inoperative for taxable years beginning on or after January 1, 2018.
SEC. 2.This act provides for a tax levy within the meaning of Article IV of the California Constitution and shall go into immediate effect.
(a)Every corporation described in subdivision (b) shall be subject to the minimum franchise tax specified in subdivision (d) from the earlier of the date of incorporation, qualification, or commencing to do business within this state, until the effective date of dissolution or withdrawal as provided in Section 23331 or, if later, the date the corporation ceases to do business within the limits of this state.
(b)Unless expressly exempted by this part or the California Constitution, subdivision (a) shall apply to each of the following:
(1)Every corporation that is incorporated under the laws of this state.
(2)Every corporation that is qualified to transact intrastate business in this state pursuant to Chapter 21 (commencing with Section 2100) of Division 1 of Title 1 of the Corporations Code.
(3)Every corporation that is doing business in this state.
(c)The following entities are not subject to the minimum franchise tax specified in this section:
(1)Credit unions.
(2)Nonprofit cooperative associations organized pursuant to Chapter 1 (commencing with Section 54001) of Division 20 of the Food and Agricultural Code that have been issued the certificate of the board of supervisors prepared pursuant to Section 54042 of the Food and Agricultural Code. The association shall be exempt from the minimum franchise tax for five consecutive taxable years, commencing with the first taxable year for which the certificate is issued pursuant to subdivision (b) of Section 54042 of the Food and Agricultural Code. This paragraph only applies to nonprofit cooperative associations organized on or after January 1, 1994.
(d)(1)Except as provided in paragraph (2), paragraph (1) of subdivision (f) of Section 23151, paragraph (1) of subdivision (f) of Section 23181, and paragraph (1) of subdivision (c) of Section 23183, corporations subject to the minimum franchise tax shall pay annually to the state a minimum franchise tax of eight hundred dollars ($800). of:
(A)Eight hundred dollars ($800) for taxable years beginning before January 1, 2019.
(B)Four hundred dollars ($400) for taxable years beginning on or after January 1, 2019.
(2)The minimum franchise tax shall be twenty-five dollars ($25) for each of the following:
(A)A corporation formed under the laws of this state whose principal business when formed was gold mining, which is inactive and has not done business within the limits of the state since 1950.
(B)A corporation formed under the laws of this state whose principal business when formed was quicksilver mining, which is inactive and has not done business within the limits of the state since 1971, or has been inactive for a period of 24 consecutive months or more.
(3)For purposes of paragraph (2), a corporation shall not be considered to have done business if it engages in business other than mining.
(e)Notwithstanding subdivision (a), for taxable years beginning on or after January 1, 1999, and before January 1, 2000, every qualified new corporation shall pay annually to the state a minimum franchise tax of five hundred dollars ($500) for the second taxable year. This subdivision shall apply to any corporation that is a qualified new corporation and is incorporated on or after January 1, 1999, and before January 1, 2000.
(1)The determination of the gross receipts of a corporation, for purposes of this subdivision, shall be made by including the gross receipts of each member of the commonly controlled group, as defined in Section 25105, of which the corporation is a member.
(2)Gross receipts, less returns and allowances reportable to this state, means the sum of the gross receipts from the production of business income, as defined in subdivision (a) of Section 25120, and the gross receipts from the production of nonbusiness income, as defined in subdivision (d) of Section 25120.
(3)Qualified new corporation means a corporation that is incorporated under the laws of this state or has qualified to transact intrastate business in this state, that begins business operations at or after the time of its incorporation and that reasonably estimates that it will have gross receipts, less returns and allowances, reportable to this state for the taxable year of one million dollars ($1,000,000) or less. Qualified new corporation does not include any corporation that began business operations as a sole proprietorship, a partnership, or any other form of business entity prior to its incorporation. This subdivision shall not apply to any corporation that reorganizes solely for the purpose of reducing its minimum franchise tax.
(4)This subdivision shall not apply to limited partnerships, as defined in Section 17935, limited liability companies, as defined in Section 17941, limited liability partnerships, as described in Section 17948, charitable organizations, corporations, as described in Section 23703, regulated investment companies, as defined in Section 851 of the Internal Revenue Code, relating to definition of regulated investment company, real estate investment trusts, as defined in Section 856 of the Internal Revenue Code, relating to definition of real estate investment, real estate mortgage investment conduits, as defined in Section 860D of the Internal Revenue Code, relating to REMIC defined, qualified Subchapter S subsidiaries, as defined in Section 1361(b)(3) of the Internal Revenue Code, relating to treatment of certain wholly owned subsidiaries, or to the formation of any subsidiary corporation, to the extent applicable.
(5)For any taxable year beginning on or after January 1, 1999, and before January 1, 2000, if a corporation has qualified to pay five hundred dollars ($500) for the second taxable year under this subdivision, but in its second taxable year, the corporations gross receipts, as determined under paragraphs (1) and (2), exceed one million dollars ($1,000,000), an additional tax in the amount equal to three hundred dollars ($300) for the second taxable year shall be due and payable by the corporation on the due date of its return, without regard to extension, for that year.
(f)(1)Notwithstanding subdivision (a), every corporation that incorporates or qualifies to do business in this state on or after January 1, 2000, shall not be subject to the minimum franchise tax for its first taxable year.
(2)This subdivision shall not apply to limited partnerships, as defined in Section 17935, limited liability companies, as defined in Section 17941, limited liability partnerships, as described in Section 17948, charitable organizations, corporations, as described in Section 23703, regulated investment companies, as defined in Section 851 of the Internal Revenue Code, relating to definition of regulated investment company, real estate investment trusts, as defined in Section 856 of the Internal Revenue Code, relating to definition of real estate investment, real estate mortgage investment conduits, as defined in Section 860D of the Internal Revenue Code, relating to REMIC defined, and qualified Subchapter S subsidiaries, as defined in Section 1361(b)(3) of the Internal Revenue Code, relating to treatment of certain wholly owned subsidiaries, to the extent applicable.
(3)This subdivision shall not apply to any corporation that reorganizes solely for the purpose of avoiding payment of its minimum franchise tax.
(g)Notwithstanding subdivision (a), a domestic corporation, as defined in Section 167 of the Corporations Code, that files a certificate of dissolution in the office of the Secretary of State pursuant to subdivision (b) of Section 1905 of the Corporations Code, prior to its amendment by the act amending this subdivision, and that does not thereafter do business shall not be subject to the minimum franchise tax for taxable years beginning on or after the date of that filing.
(h)The minimum franchise tax imposed by paragraph (1) of subdivision (d) shall not be increased by the Legislature by more than 10 percent during any calendar year.
(i)(1)Notwithstanding subdivision (a), a corporation that is a small business solely owned by a deployed member of the United States Armed Forces shall not be subject to the minimum franchise tax for any taxable year the owner is deployed and the corporation operates at a loss or ceases operation.
(2)The Franchise Tax Board may promulgate regulations as necessary or appropriate to carry out the purposes of this subdivision, including a definition for ceases operation.
(3)For the purposes of this subdivision, all of the following definitions apply:
(A)Deployed means being called to active duty or active service during a period when a Presidential Executive order specifies that the United States is engaged in combat or homeland defense. Deployed does not include either of the following:
(i)Temporary duty for the sole purpose of training or processing.
(ii)A permanent change of station.
(B)Operates at a loss means negative net income as defined in Section 24341.
(C)Small business means a corporation with total income from all sources derived from, or attributable, to the state of two hundred fifty thousand dollars ($250,000) or less.
(4)This subdivision shall become inoperative for taxable years beginning on or after January 1, 2018.
SEC. 2.This act provides for a tax levy within the meaning of Article IV of the California Constitution and shall go into immediate effect.
|
Date
|
Status
|
|---|---|
| May 25, 2018 | In committee: Held under submission. |
| Apr 11, 2018 | In committee: Set, first hearing. Referred to APPR. suspense file. |
| Apr 3, 2018 | Re-referred to Com. on APPR. |
| Apr 2, 2018 | Read second time and amended. |
| Mar 22, 2018 | From committee: Amend, and do pass as amended and re-refer to Com. on APPR. (Ayes 9. Noes 0.) (March 19). |
| Feb 22, 2018 | Referred to Com. on REV. & TAX. |
| Feb 13, 2018 | From printer. May be heard in committee March 15. |
| Feb 12, 2018 | Read first time. To print. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Mar 19, 2018 | Do pass as amended and be re-referred to the Committee on [Appropriations] | Assembly Standing Committee on Revenue and Taxation |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| California Association Of Licensed Investigators | * Support | Mar 19, 2018 |
| California Society Of Enrolled Agents | * Support | Mar 19, 2018 |
| California Tax Reform Association | * Against | Mar 19, 2018 |
| National Federation Of Independent Business | ** Support | Mar 16, 2018 |
Date of Hearing: April 11, 2018
ASSEMBLY COMMITTEE ON APPROPRIATIONS
Lorena Gonzalez Fletcher, Chair
ABPCA Bill Id:AB 2131
Author:(Melendez) – As Amended Ver:April 2, 2018
Policy Committee: | Revenue and Taxation | Vote: | 9 - 0 |
|
| ||
|
|
Urgency: No State Mandated Local Program: No Reimbursable: No
SUMMARY:
This bill reduces the minimum franchise tax (MFT) from $800 to $400 for taxable years beginning on or after January 1, 2019, and before January 1, 2024.
FISCAL EFFECT:
Annual General Fund revenue loss of $270 million in 2018-19, $600 million in 2019-20, and $700 million in 2020-21.
COMMENTS:
- Background. The $800 MFT is the minimum amount of franchise tax that corporations must pay. Generally, corporations doing business in California must pay a franchise tax worth 8.84% of their taxable income. However, that tax cannot be lower than $800, even for corporations with little or no taxable income. Similarly, each limited partnership (LP), limited liability partnership (LLP), and limited liability company (LLC) must pay an “annual tax” equal to the $800 MFT.
The MFT and the annual tax were enacted to ensure that each corporation, LP, LLP, and LLC pay at least a minimum amount of tax for the privilege of conducting business in California. One argument for the MFT and the annual tax is that even if a business earns no income, it still receives certain benefits of its corporate status, such limited liability protection.
- Purpose. According to the author, AB 2131 will provide needed relief to California businesses struggling to pay the MFT. The author argues that the current $800 is a hurdle for many entrepreneurs without the resources to pay.
- Recent legislation. Since the 2009-10 Legislative Session, there have been a significant number of bills to reduce the MFT, and therefore the annual tax, or to create an exception for certain kinds of businesses. Specifically:
- In the 2017-18 Legislative Session, AB 1922 (Fong), which repeals the MFT and AB 2510 (Muratsuchi) which reduces the annual tax for certain microbusinesses, are both pending in the Assembly Committee on Revenue and Taxation. AB 1432 (Melendez), which would have required the California State University’s Center for California Studies to study the business impact of the MFT, and AB 1256 (Brough), which would have reduced the MFT to $100 for certain entities, were both held on this committee’s Suspense File.
- In the 2015-16 Legislative Session, AB 612 (Patterson), which would have reduced the MFT to $400 for certain businesses, and SB 328 (Grove), which would have exempted certain businesses from the MFT, both died in the Assembly Committee on Revenue and Taxation.
- In the 2013-14 Legislative Session, AB 2428 (Patterson), which would have exempted businesses from the MFT for the first five years, AB 2495 (Melendez), which also would have exempted businesses from the MFT for the first five years, and AB 1769 (Debabneh), which would have exempted some businesses from the MFT for the first two years, all died in the Assembly Committee on Revenue and Taxation. Moreover, AB 2466 (Nestande), which would have exempted certain types of businesses from the MFT, was held on this committee’s Suspense File, and SB 641 (Anderson), which would have eliminated the MFT for certain new corporations, was held on the Suspense File of the Senate Appropriations Committee. Finally, AB 1889 (Hagman), Chapter 700, Statutes of 2014, exempts certain small businesses entities from the MFT for up to the first two taxable years.
- In the 2011-12 Legislative Session, AB 166 (Cook), which would have eliminated the MFT altogether, AB 368 (Morrell), which would have reduced the MFT to $400 for certain businesses, AB 821 (Garrick), which would have reduced the MFT to $100 for small business in the first ten years of operation, and AB 1605 (Garrick), which would have reduced the MFT for some business to $99, all died in the Assembly Committee on Revenue and Taxation.
- In the 2009-10 Legislative Session, AB 327 (Garrick), which would have reduced the MFT to $100, and AB 2126 (Garrick), which would have also reduced the MFT to $100, both died in the Assembly Committee on Revenue and Taxation.
Analysis Prepared by: Luke Reidenbach / APPR. / (916) 319-2081
Date of Hearing: March 19, 2018
ASSEMBLY COMMITTEE ON REVENUE AND TAXATION
Autumn R. Burke, Chairwoman
ABPCA Bill Id:AB 2131 (
Author:Melendez) – As Introduced Ver:February 12, 2018
Majority vote. Tax levy. Fiscal committee.
SUBJECT: Minimum franchise tax
SUMMARY: Reduces the minimum franchise tax to $400. Specifically, this bill:
- Provides that, except as otherwise specified, corporations subject to the minimum franchise tax shall pay annually to the state a minimum franchise tax of $400 for taxable years beginning on or after January 1, 2019.
- Makes technical changes.
- Takes effect immediately as a tax levy.
EXISTING LAW:
- Imposes a franchise tax on all corporations doing business in California equal to 8.84% of the taxable income attributable to California. A minimum franchise tax of $800 is imposed on all corporations that are incorporated under the laws of California, qualified to transact intrastate business in California, or are doing business in California.[1] Taxpayers must pay the minimum franchise tax only if it is more than their regular franchise tax liability.
- Provides exceptions with respect to the imposition of the minimum franchise tax. For instance, credit unions and nonprofit organizations are not subject to the minimum franchise tax and a corporation is not subject to the minimum franchise tax for its first taxable year. However, even though a corporation is not subject to the minimum tax in its first taxable year, it will be subject to franchise tax in its first taxable year based on its taxable income.
FISCAL EFFECT: The Franchise Tax Board (FTB) estimates this bill will result in General Fund revenue losses of $270 million in fiscal year (FY) 2018-19, $600 million in FY 2019-20, and $700 million in FY 2020-21.
COMMENTS:
- The author has provided the following statement in support of this bill:
California annually ranks near the bottom of business friendly states due to over-regulation and high tax rates. Small businesses continue to leave the state in search of greener pastures. California currently has the highest Minimum Franchise Tax in the nation. This creates disincentive for entrepreneurs who are contemplating opening a new business or relocating their business to California. The State Legislature should be doing everything in its power to improve our business climate and help get California back to work.
The Legislative Analyst's Office recently reported that reducing the minimum franchise tax would provide tax relief and economic incentive to businesses. Reducing the franchise tax under AB 2131 will ensure small businesses will survive in California and will incentivize them to continue to grow in the state.
- Supporters state that "[o]ne significant hurdle for many entrepreneurs is the California minimum franchise tax of $800 per year. Many consider this a game ender, as they do not have the surplus resources available to pay this annual tax just for the privilege of doing business in California. AB 2131 would provide much needed relief to those struggling to pay this tax by cutting it in half from $800 to $400."
- Committee Staff Comments:
- Minimum Franchise Tax: The minimum franchise tax, the annual tax, and the annual fee were enacted to ensure that all corporations and LLCs pay at least a minimum amount of tax for the privilege of doing business in California, regardless of the businesses income or loss. Thus, the minimum tax is not an "income tax", but rather a tax on the right to exercise the powers granted to a corporation doing business in California. Even when a business earns no income, it still receives the benefits of its corporate status, including the limited liability protection under California law. This bill will reduce the minimum franchise tax for corporations, and reduce the corresponding taxes and fees for partnerships and entities that are taxed as partnerships, such as most LLCs.[2]
- Federal tax reform: The recently enacted Tax Cuts and Jobs Act included two provisions relevant to this bill. First, the corporate tax rate was lowered to 21%. Second, there is now a 20% deduction for certain pass-through entities. Even though the pass-through deduction is disallowed for some service industries, joint filers with income below $315,000 can fully claim the deduction, even those in the otherwise prohibited service industries. One possible result of tax reform is that taxpayers will receive at least $400 in tax benefits, making up the difference between existing law and this bill.
- Inflation: California's minimum franchise tax was increased to $800 in 1990, and has remained at $800 since then. Due to inflation, the cost of the minimum franchise tax has been significantly reduced. The $800 minimum franchise tax in 1990 would cost 1,556.46 in January 2018 dollars.[3] Because the minimum franchise tax is not indexed for inflation, it has functionally been lowered by 2.35% per year. Therefore, the minimum franchise tax has effectively been cut in half since it was imposed in 1990.
- California's business climate: Reducing the minimum franchise tax to $400 may provide a slight benefit to new businesses with taxable income less than $9,039 per year. Taxpayers who are at the margin are likely to receive the intended benefit. Also likely to benefit are sophisticated taxpayers who choose to keep taxable income below the $9,039 threshold. However, for those sophisticated taxpayers, the $400 difference is likely to be relatively insignificant.
According to the U.S. Small Business Administration, Office of Advocacy, in the second quarter of 2015, 41,416 establishments started, generating 114,230 new jobs in California. During that same time, 36,397 establishments exited the market, resulting in 113,480 fewer jobs.[4] The report did not distinguish businesses that went to another state and ceased to do business in California from businesses that ceased to exist. Despite the costs and benefits, California businesses are in relative homeostasis.
Business advocates may argue that California is not a particularly business friendly state, despite access to significant wealth and 39.25 million residents. It is possible, albeit unlikely, that the $400 reduction in the minimum franchise tax will make or break most businesses, taking into consideration total costs to operate. However, for those businesses that are on the edge and will be saved with $400 of relief, the reduction of the minimum franchise tax will successfully accomplish the goal of removing a small obstacle to financial well-being.
- How is a tax expenditure different from a direct expenditure: As the Department of Finance notes in its Tax Expenditure Report, there are several key differences between tax expenditures and direct expenditures. First, once they are put in place, tax expenditures are reviewed less frequently than direct expenditures. Although this creates greater certainty for taxpayers regarding the applicable tax laws (because the tax expenditure will remain on the books for longer periods of time), it may also result in arbitrary tax expenditures that do not serve a public benefit. Second, there is generally no control over the amount of revenue losses associated with any given tax expenditure. Finally, it should also be noted that once enacted it takes a two-thirds vote to rescind an existing tax expenditure absent a sunset date. For this reason, the Committee may wish to include a five-year sunset date for this reduction in the minimum franchise tax, to provide the opportunity for future legislative review.
REGISTERED SUPPORT / OPPOSITION:
Support
National Federation of Independent Business
Opposition
None on file
Analysis Prepared by: Ken Conlan/Carlos Anguiano / REV. & TAX. / (916) 319-2098
According to the FTB, for taxable years beginning on or after January 1, 1997, only a taxpayer with a net income of less than approximately $9,040 pays the minimum franchise tax because the amount of measured tax owed would be less than $800 ($9,039 x 8.84% = $799). ↑
Revenue and Tax Code Section 17935 ↑
Consumer Price Index, Inflation Calculator, Bureau of Labor Statistics, https://www.bls.gov/data/inflation_calculator.htm ↑
https://www.sba.gov/sites/default/files/advocacy/California_1.pdf ↑
Discussed in Hearing
 7MIN
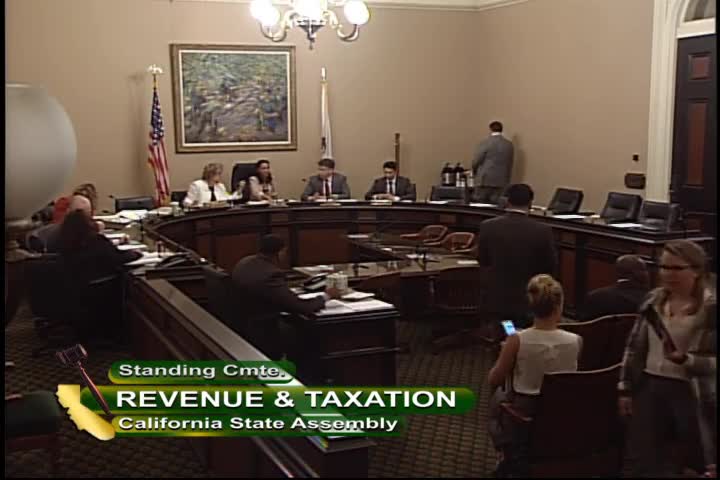
Assembly Standing Committee on Revenue and Taxation
Bill Author
Bill Co-Author(s):