AB 2254: Property tax: exemption:
- Session Year: 2017-2018
- House: Assembly
- Latest Version Date: 2018-02-13
Existing property tax law, pursuant to the authorization of the California Constitution, provides a disabled veterans property tax exemption for the principal place of residence of a veteran, the veterans spouse, or the veteran and veterans spouse jointly, and the unmarried surviving spouse of a veteran, as provided, if the veteran, is blind in both eyes, has lost the use of 2 or more limbs, or is totally disabled as a result of injury or disease incurred in military, or if the veteran has, as a result of a service-connected injury or disease, died while on active duty in military service. Existing law exempts that part of the full value of the residence that does not exceed $100,000, or $150,000, if the household income of the veteran or the unmarried surviving spouse of a veteran does not exceed $40,000, adjusted for inflation, as specified.
This bill, beginning with the 201920 fiscal year and for each fiscal year thereafter, would instead exempt the full value of the principal place of residence of a veteran or veterans spouse and the unmarried surviving spouse of a veteran.
Existing law requires the state to reimburse local agencies annually for certain property tax revenues lost as a result of any exemption or classification of property for purposes of ad valorem property taxation.
This bill would provide that, notwithstanding those provisions, no appropriation is made and the state shall not reimburse local agencies for property tax revenues lost by them pursuant to the bill.
This bill would take effect immediately as a tax levy.
(a)Property that constitutes the principal place of residence of a veteran, that is owned by the veteran, the veterans spouse, or the veteran and the veterans spouse jointly, is exempted from taxation on that part of the full value of the residence that does not exceed one hundred thousand dollars ($100,000), as adjusted for the relevant assessment year as provided in subdivision (h), if the veteran is blind in both eyes, has lost the use of two or more limbs, or if the veteran is totally disabled as a result of injury or disease incurred in military service. The service, is exempted from taxation as follows:
(1)(A)On that part of the full value of the residence that does not exceed one hundred thousand dollars ($100,000), as adjusted for the relevant assessment year as provided in subdivision (h), through the 201819 fiscal year.
(B)The one hundred thousand dollar ($100,000) exemption shall be one hundred fifty thousand dollars ($150,000), as adjusted for the relevant assessment year as provided in subdivision (h), in the case of an eligible veteran whose household income does not exceed the amount of forty thousand dollars ($40,000), as adjusted for the relevant assessment year as provided in subdivision (g).
(2)Beginning with the 201920 fiscal year and for each fiscal year thereafter, the full value of the residence.
(b)(1)For purposes of this section, veteran means either of the following:
(A)A person who is serving in or has served in and has been discharged under other than dishonorable conditions from service in the United States Army, Navy, Air Force, Marine Corps, or Coast Guard, and served either in time of war or in time of peace in a campaign or expedition for which a medal has been issued by Congress, or in time of peace and because of a service-connected disability was released from active duty, and who has been determined by the United States Department of Veterans Affairs to be eligible for federal veterans health and medical benefits.
(B)Any person who would qualify as a veteran pursuant to subparagraph (A) except that he or she has, as a result of a service-connected injury or disease, died while on active duty in military service. The United States Department of Veterans Affairs shall determine whether an injury or disease is service connected.
(2)For purposes of this section, property is deemed to be the principal place of residence of a veteran, disabled as described in subdivision (a), who is confined to a hospital or other care facility, if that property would be that veterans principal place of residence were it not for his or her confinement to a hospital or other care facility, provided that the residence is not rented or leased to a third party. For purposes of this paragraph, a family member who resides at the residence is not a third party.
(c)(1)(A)Property that is owned by, and that constitutes the principal place of residence of, the unmarried surviving spouse of a deceased veteran is exempt from taxation on that part of the full value of the residence that does not exceed one hundred thousand dollars ($100,000), as adjusted for the relevant assessment year as provided in subdivision (h), as provided in subparagraph (B), in the case of a veteran who was blind in both eyes, had lost the use of two or more limbs, or was totally disabled provided that either of the following conditions is met:
(A)(i)The deceased veteran during his or her lifetime qualified for the exemption pursuant to subdivision (a), or would have qualified for the exemption under the laws effective on January 1, 1977, except that the veteran died prior to January 1, 1977.
(B)(ii)The veteran died from a disease that was service connected as determined by the United States Department of Veterans Affairs.
(B)The exemption is in the following amounts:
(i)(I)On that part of the full value of the residence that does not exceed one hundred thousand dollars ($100,000), as adjusted for the relevant assessment year as provided in subdivision (h), through the 201819 fiscal year.
The(II)The one hundred thousand dollar ($100,000) exemption shall be one hundred fifty thousand dollars ($150,000), as adjusted for the relevant assessment year as provided in subdivision (h), in the case of an eligible unmarried surviving spouse whose household income does not exceed the amount of forty thousand dollars ($40,000), as adjusted for the relevant assessment year as provided in subdivision (g).
(ii)Beginning with the 201920 fiscal year and for each fiscal year thereafter, the full value of the residence.
(2)Commencing (A)Beginning with the 199495 fiscal year, to the 201819 fiscal year, inclusive, property that is owned by, and that constitutes the principal place of residence of, the unmarried surviving spouse of a veteran as described in subparagraph (B) of paragraph (1) of subdivision (b) is exempt from taxation on that part of the full value of the residence that does not exceed one hundred thousand dollars ($100,000), as adjusted for the relevant assessment year as provided in subdivision (h). The one hundred thousand dollar ($100,000) exemption shall be one hundred fifty thousand dollars ($150,000), as adjusted for the relevant assessment year as provided in subdivision (h), in the case of an eligible unmarried surviving spouse whose household income does not exceed the amount of forty thousand dollars ($40,000), as adjusted for the relevant assessment year as provided in subdivision (g).
(B)Beginning with the 201920 fiscal year and for each fiscal year thereafter, property that is owned by, and that constitutes the principal place of residence of, the unmarried surviving spouse of a veteran described in subparagraph (B) of paragraph (1) of subdivision (b) is exempt from taxation.
(3)Beginning with the 201213 fiscal year and for each fiscal year thereafter, property is deemed to be the principal place of residence of the unmarried surviving spouse of a deceased veteran, who is confined to a hospital or other care facility, if that property would be the unmarried surviving spouses principal place of residence were it not for his or her confinement to a hospital or other care facility, provided that the residence is not rented or leased to a third party. For purposes of this paragraph, a family member who resides at the residence is not a third party.
(d)As used in this section, property that is owned by a veteran or property that is owned by the veterans unmarried surviving spouse includes all of the following:
(1)Property owned by the veteran with the veterans spouse as a joint tenancy, tenancy in common, or as community property.
(2)Property owned by the veteran or the veterans spouse as separate property.
(3)Property owned with one or more other persons to the extent of the interest owned by the veteran, the veterans spouse, or both the veteran and the veterans spouse.
(4)Property owned by the veterans unmarried surviving spouse with one or more other persons to the extent of the interest owned by the veterans unmarried surviving spouse.
(5)So much That portion of the property of a corporation as that constitutes the principal place of residence of a veteran or a veterans unmarried surviving spouse when the veteran, or the veterans spouse, or the veterans unmarried surviving spouse is a shareholder of the corporation and the rights of shareholding entitle one to the possession of property, legal title to which is owned by the corporation. The exemption provided by this paragraph shall be shown on the local roll and shall reduce the full value of the corporate property. Notwithstanding any law or articles of incorporation or bylaws of a corporation described in this paragraph, any reduction of property taxes paid by the corporation shall reflect an equal reduction in any charges by the corporation to the person who, by reason of qualifying for the exemption, made possible the reduction for the corporation.
(e)For purposes of this section, being blind in both eyes means having a visual acuity of 5/200 or less, or concentric contraction of the visual field to 5 degrees or less; losing the use of a limb means that the limb has been amputated or its use has been lost by reason of ankylosis, progressive muscular dystrophies, or paralysis; and being totally disabled means that the United States Department of Veterans Affairs or the military service from which the veteran was discharged has rated the disability at 100 percent or has rated the disability compensation at 100 percent by reason of being unable to secure or follow a substantially gainful occupation.
(f)An exemption granted to a claimant pursuant to this section shall be in lieu of the veterans exemption provided by subdivisions (o), (p), (q), and (r) of Section 3 of Article XIII of the California Constitution and any other real property tax exemption to which the claimant may be entitled. No other real property tax exemption may be granted to any other person with respect to the same residence for which an exemption has been granted pursuant to this section; provided, that if two or more veterans qualified pursuant to this section coown a property in which they reside, each is entitled to the exemption to the extent of his or her interest.
(g)Commencing on January 1, 2002, and for each assessment year thereafter, until January 1, 2018, the household income limit shall be compounded annually by an inflation factor that is the annual percentage change, measured from February to February of the two previous assessment years, rounded to the nearest one-thousandth of 1 percent, in the California Consumer Price Index for all items, as determined by the California Department of Industrial Relations.
(h)Commencing on January 1, 2006, and for each assessment year thereafter, until January 1, 2018, the exemption amounts set forth in subdivisions (a) and (c) shall be compounded annually by an inflation factor that is the annual percentage change, measured from February to February of the two previous assessment years, rounded to the nearest one-thousandth of 1 percent, in the California Consumer Price Index for all items, as determined by the California Department of Industrial Relations.
(i)The amendments made to this section by the act adding this subdivision Chapter 871 of the Statutes of 2016 shall apply for property tax lien dates for the 201718 fiscal year and for each fiscal year thereafter.
SEC. 2.Notwithstanding Section 2229 of the Revenue and Taxation Code, no appropriation is made by this act and the state shall not reimburse any local agency for any property tax revenues lost by it pursuant to this act.
SEC. 3.This act provides for a tax levy within the meaning of Article IV of the California Constitution and shall go into immediate effect.
REVISIONS: HeadingLine 2.|
Date
|
Status
|
|---|---|
| May 25, 2018 | In committee: Held under submission. |
| Apr 4, 2018 | In committee: Set, first hearing. Referred to suspense file. |
| Mar 20, 2018 | From committee: Do pass and re-refer to Com. on APPR. (Ayes 10. Noes 0.) (March 19). Re-referred to Com. on APPR. |
| Mar 9, 2018 | Coauthors revised. |
| Mar 1, 2018 | Referred to Com. on REV. & TAX. |
| Feb 14, 2018 | From printer. May be heard in committee March 16. |
| Feb 13, 2018 | Read first time. To print. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Mar 19, 2018 | Do pass and be re-referred to the Committee on [Appropriations] | Assembly Standing Committee on Revenue and Taxation |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| National Veterans Foundation | ** Support | Mar 16, 2018 |
Date of Hearing: April 4, 2018
ASSEMBLY COMMITTEE ON APPROPRIATIONS
Lorena Gonzalez Fletcher, Chair
ABPCA Bill Id:AB 2254
Author:(Lackey) – As Introduced Ver:February 13, 2018
Policy Committee: | Revenue and Taxation | Vote: | 10 - 0 |
|
| ||
|
|
Urgency: No State Mandated Local Program: No Reimbursable: No
SUMMARY:
This bill expands the Disabled Veterans’ Exemption by exempting fully from property tax the personal residence of an eligible disabled veteran or his or her unmarried surviving spouse.
FISCAL EFFECT:
- Annual local property tax revenue loss of $91.1 million starting in 2019-20, resulting in General Fund (GF) costs of approximately $45 million as a result of the Proposition 98 guarantee.
- The state does not reimburse local governments for the property tax revenue loss from the Disabled Veterans’ Exemption. Therefore, this bill will result in significant revenue losses for local governments. According to the Board of Equalization (BOE), the counties with the most Disabled Veterans’ Exemption claims are: San Diego (5,868), Riverside (4,316), Los Angeles (2,770), San Bernardino (2,642), and Sacramento (2,518).
COMMENTS:
- Background and purpose. The Disabled Veterans’ Exemption provides a partial property tax exemption for qualified disabled veterans and their spouses, meaning a portion of their home’s assessed value is not included in the calculation of their property tax liability. Prior to 2006, this exemption was $150,000 for low-income disabled veterans and their spouses and $100,000 for all other qualified households. Beginning in 2006, these amounts were adjusted annually for inflation, and today those exemption amounts are $202,060 for qualified low-income disabled veterans and their spouses and $134,706 for all other qualified households.
According to the author, AB 2254 will alleviate the financial strain that veterans experience as a result of their disability. Under this bill, the full value of a disabled veteran’s home is exempt from property tax if the veteran is blind in both eyes, has lost the use of two or more limbs, or is totally disabled as a result of injury or disease incurred in military service.
- Related Legislation. AB 3209 (Frazier), of the 2017-18 Legislative Session, provides a full property tax exemption for eligible disabled veterans but retains the current exemption for windowed spouses. AB 3209 is pending hearing in the Assembly Committee on Revenue and Taxation.
- Recent Legislation. There have been a number of similar efforts to expand the Disabled Veterans’ Exemption:
SB 404 (Stone), of the 2017-18 Legislative Session, would have similarly provided a full exemption. SB 404 was held on the Senate Appropriations Committee’s Suspense File.
SB 1104 (Stone), of the 2015-16 Legislative Session, would have similarly provided a full exemption. SB 1104 was held on the Senate Appropriations Committee’s Suspense File.
AB 1556 (Mathis), of the 2015-16 Legislative Session, would have increased the exemption amount to $2.1 million of assessed value. AB 1556 was held on this committee’s Suspense File.
SB 1183 (Bates), of the 2015-16 Legislative Session, would have increased the exemption amount to $1 million of assessed value. SB 1183 was held on the Senate Appropriations Committee’s Suspense File.
Analysis Prepared by: Luke Reidenbach / APPR. / (916) 319-2081
Date of Hearing: March 19, 2018
ASSEMBLY COMMITTEE ON REVENUE AND TAXATION
Autumn R. Burke, Chairwoman
ABPCA Bill Id:AB 2254 (
Author:Lackey) – As Introduced Ver:February 13, 2018
Majority vote. Tax levy. Fiscal committee.
SUBJECT: Property tax: exemption: disabled veterans
SUMMARY: Exempts fully from property tax the personal residence of a totally disabled veteran or his/her unmarried surviving spouse. Specifically, this bill:
- Removes the existing maximum flat exemption amounts of $100,000 and $150,000 (for low-income persons) beginning with fiscal year (FY) 2019-20 and each FY thereafter.
- Limits the maximum flat exemption amounts of $100,000 /$150,000 for use through FY 2018-19.
- Makes other technical and conforming changes to the disabled veterans' property tax provisions.
- Specifies that no appropriation is made and the state will not reimburse local agencies for property tax revenues lost by them pursuant to this bill.
- Takes effect immediately as a tax levy, but applies beginning with FY 2019-20.
EXISTING LAW:
- Authorizes the Legislature to provide a full or partial exemption from property tax for the home of a veteran who is totally disabled because of injury or disease incurred in military service, or his/her surviving unmarried spouse (called the disabled veterans' exemption). Extends the exemption to include the surviving spouse of a person who died as a result of service-connected injuries while on active military duty. (Article XIII, Section 4, California Constitution.)
- Implements the constitutional authorization by providing a flat exemption amount depending on household income. (Revenue and Taxation Code (R&TC) Section 205.5.)
- The "basic" exemption amount is $100,000, adjusted annually for inflation ($134,706 for FY 2018-19).
- The "low-income" exemption amount is $150,000, adjusted annually for inflation ($202,060 for FY 2018-19). The low-income exemption applies if the veteran's household income does not exceed $40,000, adjusted annually for inflation (below $60,490 for FY 2018-19).
- Defines a "totally disabled veteran" as a veteran who has a disability rating at 100% from the United States Department of Veterans Affairs (USDVA), or the military service from which the veteran was discharged, or has a disability compensation rating at 100% because he/she is unable to secure or follow a substantially gainful occupation.
- Extends the constitutional exemption by statute to the surviving unmarried spouse of a non-100% rated disabled veteran, if the veteran's subsequent death is service-connected, as determined by the USDVA.
- Requires one-time claim filing with the local county assessor to receive the basic exemption.
- Requires annual claim filing to receive the low-income exemption to verify continued income eligibility.
FISCAL EFFECT: The State Board of Equalization (BOE) estimates this bill will result in a statewide annual revenue loss of $91.1 million.
COMMENTS:
- The author has provided the following statement in support of this bill:
According to the U.S. Department of Veterans Affairs, there are currently around 53,000 California veterans who qualify as one hundred percent disabled. Veterans who return home with a full disability have sacrificed their livelihoods to protect our country. The California State Board of Equalization estimates around 45,000 disabled veterans will qualify for the current property tax exemption, which reduces the property tax liability for qualified veterans who, due to a service-connected injury or disease, have been rated one hundred percent disabled or are being compensated at the one hundred percent rate due to lack of employability. Under this legislation, the full value of a disabled veteran's principle place of residence is exempt if the veteran is blind in both eyes, has lost the use of two or more limbs, or is totally disabled as a result of injury or disease incurred in military service. This bill will also apply property tax exemptions to an unmarried widowed spouse of a veteran if he or she has, as a result of a service-connected injury or disease, died while on active duty in military service. Full disability or death prevents a veteran from returning to the workforce with full capabilities or entirely, which inhibits income earning potential, creating a financial strain on the service member and family. This bill will alleviate the financial strain our disabled veterans experience as a result of their impairment incurred while serving our country.
- This bill is supported by the National Veterans Foundation (Foundation), which notes that though current legislation allows for a partial property tax exemption, based on the cost of an average home in California compared to the national average, it is evident that the disabled veterans' exemption is not meeting the severe needs of the current population the exemption intends to serve. The Foundation further states that the rising costs of home prices are driving veterans out of California, and this bill will help ensure veterans stay in California and not be forced to move to other states.
- Committee Staff Comments:
- What are the current disabled veterans' exemption amounts? For FY 2017-18, the basic exemption applied to a home's assessed value is $134,706. For the low-income exemption (household income below $60,490), the exemption increases to $202,060 of assessed value. For some, the current exemption amounts suffice to provide a full exemption. BOE estimates about 21% of homes receiving the basic exemption, and 24% of the homes receiving the low-income exemption, are exempt under current levels.
- How many homeowners receive the disabled veterans' exemption? For FY 2017-18, about 45,000 exemptions were granted to homes owned by eligible disabled veterans or their spouses, with just over 9% of the homes receiving the greater exemption amount for low-income households. To provide a reference point, about 5.1 million homes receive the general homeowners' exemption of $7,000 of assessed value available to any homeowner.
- Statewide average assessed values and home prices: BOE estimates that for FY 2017-18, the statewide average assessed value of homes receiving the homeowners' exemption was about $393,000. The California Association of Realtors® reports the January 2018 statewide median home price was $527,800.
- The scope of the disabled veterans' exemption: This bill would eliminate only the ad valorem property tax imposed on a disabled veteran's home, but not the direct levies, special taxes, and special assessments that might be due on the property and collected via the annual property tax bill.
- Eliminates annual filing requirements for low-income exemption: This bill provides a full exemption to all eligible disabled veterans or their unmarried surviving spouses regardless of household income. This eliminates the need for low-income households to refile annually to verify continued income eligibility.
- The fiscal impact on local governments: The disabled veterans' exemption, unlike the homeowners' exemption, does not require the state to reimburse property tax revenue recipients for the lost tax revenue resulting from the exemption. Additionally, existing law does not require the state to reimburse local governments by an equivalent homeowners' exemption amount ($7,000) to partially mitigate the revenue impact. This bill would most significantly impact those local governments in counties that have a large number of eligible disabled veterans and surviving spouses. The five counties with the greatest number of homes receiving the disabled veterans' exemption in descending order are San Diego, Riverside, Los Angeles, San Bernardino, and Sacramento.
- Related legislation:
- AB 3209 (Frazier), of the 2017-18 Legislative Session, would exempt fully a disabled veteran's home but would retain the current exemption amounts for widowed spouses of disabled veterans and widowed spouses of active duty personnel. AB 3209 is pending referral by the Assembly Rules Committee.
- SB 404 (Stone), of the 2017-18 Legislative Session, would have similarly provided a full exemption. SB 404 was held on the Senate Appropriations Committee’s Suspense File.
- Prior legislation:
- SB 1104 (Stone), of the 2015-16 Legislative Session, would have similarly provided a full exemption. SB 1104 was held on the Senate Appropriations Committee’s Suspense File.
- AB 1556 (Mathis), of the 2015-16 Legislative Session, would have increased the exemption amount to $2.1 million of assessed value. AB 1556 was held on the Assembly Appropriations Committee’s Suspense File.
- SB 1183 (Bates), of the 2015-16 Legislative Session, would have increased the exemption amount to $1 million of assessed value. SB 1183 was held on the Senate Appropriations Committee’s Suspense File.
REGISTERED SUPPORT / OPPOSITION:
Support
National Veterans Foundation
Opposition
None on file
Analysis Prepared by: Rose Marie Kinnee / REV. & TAX. / (916) 319-2098
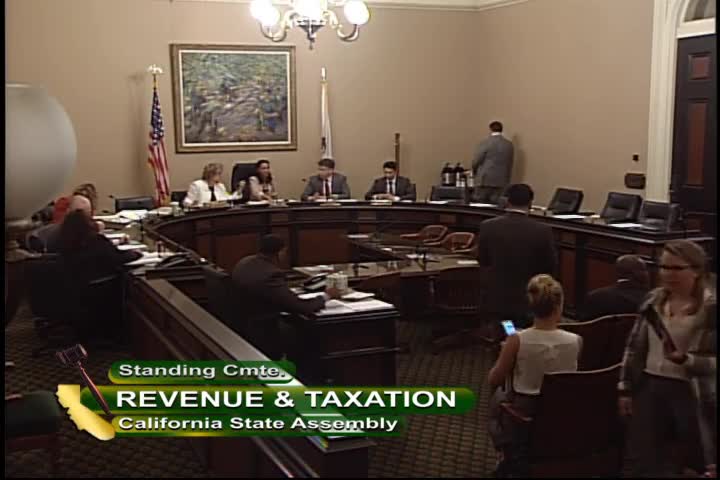
Discussed in Hearing
 8MIN
Assembly Standing Committee on Revenue and Taxation
Bill Author