SB 1293: Income taxation: credits: cannabis: equity applicants and licensees.
- Session Year: 2021-2022
- House: Senate
- Latest Version Date: 2022-06-22
The Control, Regulate and Tax Adult Use of Marijuana Act (AUMA), an initiative measure approved as Proposition 64 at the November 8, 2016, statewide general election, authorizes a person who obtains a state license under AUMA to engage in commercial adult-use cannabis activity pursuant to that license and applicable local ordinances.
The Personal Income Tax Law and the Corporation Tax Law allow various credits against the taxes imposed by those laws.
Existing federal law imposes an income tax upon every corporation, except as specified, and prohibits the allowance of a deduction or credit for any amount paid or incurred during the taxable year in carrying on any trade or business consisting of trafficking in controlled substances, including cannabis.
This bill, under both laws, for taxable years beginning on or after January 1, 2022, and before January 1, 2027, would allow a credit to a cannabis equity applicant or licensee, as defined, licensee who is eligible for a specified fee waiver and deferral program administered by the Department of Cannabis Control, in an amount equal to $10,000.
Existing law requires any bill authorizing a new tax expenditure to contain, among other things, specific goals, purposes, and objectives that the tax expenditure will achieve, detailed performance indicators, and data collection requirements.
This bill would include additional information required for any bill authorizing a new tax expenditure.
This bill would take effect immediately as a tax levy.
The Control, Regulate and Tax Adult Use of Marijuana Act (AUMA), an initiative measure approved as Proposition 64 at the November 8, 2016, statewide general election, authorizes a person who obtains a state license under AUMA to engage in commercial adult-use cannabis activity pursuant to that license and applicable local ordinances.
The Personal Income Tax Law and the Corporation Tax Law allow various credits against the taxes imposed by those laws.
Existing federal law imposes an income tax upon every corporation, except as specified, and prohibits the allowance of a deduction or credit for any amount paid or incurred during the taxable year in carrying on any trade or business consisting of trafficking in controlled substances, including cannabis.
This bill, under both laws, for taxable years beginning on or after January 1, 2022, and before January 1, 2027, would allow a credit to a cannabis equity applicant or licensee, as defined, in an amount equal to the amount of business expenses the equity applicant or licensee could not deduct or claim as a credit for that taxable year under federal law because the amount was disallowed in connection with the trafficking of controlled substances. $10,000.
Existing law requires any bill authorizing a new tax expenditure to contain, among other things, specific goals, purposes, and objectives that the tax expenditure will achieve, detailed performance indicators, and data collection requirements.
This bill would include additional information required for any bill authorizing a new tax expenditure.
This bill would take effect immediately as a tax levy.
The Control, Regulate and Tax Adult Use of Marijuana Act (AUMA), an initiative measure approved as Proposition 64 at the November 8, 2016, statewide general election, authorizes a person who obtains a state license under AUMA to engage in commercial adult-use cannabis activity pursuant to that license and applicable local ordinances.
The Personal Income Tax Law imposes a net tax at specified rates each taxable year on the entire taxable income of every resident of this state. The Corporation Tax Law imposes an income tax upon every corporation not subject to the corporate franchise tax at a specified rate upon its net income derived from sources within this state, except as otherwise provided.The Personal Income Tax Law and the Corporation Tax Law allow various credits against the taxes imposed by those laws.
Existing federal law imposes an income tax upon every corporation, except as specified, and prohibits the allowance of a deduction or credit for any amount paid or incurred during the taxable year in carrying on any trade or business consisting of trafficking in controlled substances, including cannabis.
This bill would state the intent of the Legislature to help equity licensees obtain a personal income or corporate tax credit that would be equal, or in some proportion, to the normal business expenses that they would otherwise have been able to write off on their federal taxes, but for federal law. The bill would make related legislative findings and declarations.This bill, under both laws, for taxable years beginning on or after January 1, 2022, and before January 1, 2027, would allow a credit to a cannabis equity applicant or licensee, as defined, in an amount equal to the amount of business expenses the equity applicant or licensee could not deduct or claim as a credit for that taxable year under federal law because the amount was disallowed in connection with the trafficking of controlled substances.
Existing law requires any bill authorizing a new tax expenditure to contain, among other things, specific goals, purposes, and objectives that the tax expenditure will achieve, detailed performance indicators, and data collection requirements.
This bill would include additional information required for any bill authorizing a new tax expenditure.
This bill would take effect immediately as a tax levy.
The Control, Regulate and Tax Adult Use of Marijuana Act (AUMA), an initiative measure approved as Proposition 64 at the November 8, 2016, statewide general election, authorizes a person who obtains a state license under AUMA to engage in commercial adult-use cannabis activity pursuant to that license and applicable local ordinances.
The Personal Income Tax Law imposes a net tax at specified rates each taxable year on the entire taxable income of every resident of this state. The Corporation Tax Law imposes an income tax upon every corporation not subject to the corporate franchise tax at a specified rate upon its net income derived from sources within this state, except as otherwise provided.
Existing federal law imposes an income tax upon every corporation, except as specified, and prohibits the allowance of a deduction or credit for any amount paid or incurred during the taxable year in carrying on any trade or business consisting of trafficking in controlled substances, including cannabis.
This bill would state the intent of the Legislature to help equity licensees obtain a personal income or corporate tax credit that would be equal, or in some proportion, to the normal business expenses that they would otherwise have been able to write off on their federal taxes, but for federal law. The bill would make related legislative findings and declarations.
The Legislature makes the following findings and declarations:
(a)The War on Drugs has harmed individuals and communities, particularly communities of color.
(b)The Legislature has taken actions to assist individuals and communities harmed by past criminal prohibition related to cannabis as a way of righting past wrongs. And yet, many cannabis businesses owned by equity licensees still struggle to turn a profit and keep their doors open.
(c)The challenge is made worse because federal law under Section 280E of Title 26 of the United States Code does not allow deduction or credit for any amount paid or incurred during the taxable year in carrying on a trade or business that consists of trafficking in controlled substances prohibited by federal or state law. The federal Controlled Substances Act, in turn, lists cannabis as a Schedule I controlled substance.
(d)It is the intent of the Legislature to help equity licensees obtain a personal income or corporate tax credit.
SEC. 2.Section 17053.82 is added to the Revenue and Taxation Code, to read:17053.82.(a)For each taxable year beginning on or after January 1, 2022, and before January 1, 2027, there shall be allowed a credit against the net tax, as defined in Section 17039, to a qualified taxpayer in an amount equal to ten thousand dollars ($10,000).
(b)For purposes of this section, qualified taxpayer means an equity applicant or licensee as defined in subdivision (c) of eligible for the fee waiver and deferral program established pursuant to Section 26249 of the Business and Professions Code. Code, as administered by the Department of Cannabis Control.
(c)On January 1, 2023, and annually thereafter, the Department of Cannabis Control shall provide the Franchise Tax Board with a list of equity applicants and licensees, as defined in subdivision (c) of licensees eligible for the fee waiver and deferral program established pursuant to Section 26249 of the Business and Professions Code, for the purposes of administering this section.
(d)In the case where the credit allowed by this section exceeds the net tax, the excess may be carried over to reduce the net tax in the following taxable year, and succeeding seven years if necessary, until the credit is exhausted.
(e)This section and Section 23682 shall be known and may be cited as the Cannabis Equity Tax Credit.
(f)This section shall remain in effect only until December 1, 2027, and as of that date is repealed.
SEC. 3.Section 23682 is added to the Revenue and Taxation Code, to read:23682.(a)For each taxable year beginning on or after January 1, 2022, and before January 1, 2027, there shall be allowed a credit against the tax, as defined in Section 23036, to a qualified taxpayer in an amount equal to ten thousand dollars ($10,000).
(b)For purposes of this section, qualified taxpayer means an equity applicant or licensee as defined in subdivision (c) of eligible for the fee waiver and deferral program established pursuant to Section 26249 of the Business and Professions Code. Code, as administered by the Department of Cannabis Control.
(c)On January 1, 2023, and annually thereafter, the Department of Cannabis Control shall provide the Franchise Tax Board with a list of equity applicants and licensees, as defined in subdivision (c) of licensees eligible for the fee waiver and deferral program established pursuant to Section 26249 of the Business and Professions Code, for the purposes of administering this section.
(d)In the case where the credit allowed by this section exceeds the tax, the excess may be carried over to reduce the tax in the following taxable year, and succeeding seven years if necessary, until the credit is exhausted.
(e)This section and Section 17053.82 shall be known and may be cited as the Cannabis Equity Tax Credit.
(f)This section shall remain in effect only until December 1, 2027, and as of that date is repealed.
SEC. 4.For the purposes of complying with Section 41 of the Revenue and Taxation Code, with respect to Sections 17053.82 and 23682 of the Revenue and Taxation Code, as added by this act, the Legislature finds and declares all of the following:
(a)The specific goals, purposes, and objectives that the credits will achieve include all of the following:
(1)Provide relief for individuals who are low income or who have directly or indirectly been negatively impacted by past cannabis policies.
(2)Assist cannabis equity applicants and licensees to stay in business or grow their business.
(b)Detailed performance indicators for the Legislature to use in determining whether the credits meet the goals, purposes, and objectives described in subdivision (a) are the number of credits claimed and the total dollar amount of credits claimed.
(c)(1) The Franchise Tax Board shall analyze the performance indicators in subdivision (b) for each taxable year and shall report its findings, findings to the Legislature, on or before July 31, 2023, March 1, 2025, and annually thereafter, thereafter while the credit is operative, in compliance with Section 9795 of the Government Code, to the Legislature. Code.
(2)The disclosure provisions of this paragraph shall be treated as an exception to Section 19542 under Article 2 (commencing with Section 19542) of Chapter 7 of Part 10.2 of Division 2 of the Revenue and Taxation Code.
SEC. 5.This act provides for a tax levy within the meaning of Article IV of the California Constitution and shall go into immediate effect.
The Legislature makes the following findings and declarations:
(a)The War on Drugs has harmed individuals and communities, particularly communities of color.
(b)The Legislature has taken actions to assist individuals and communities harmed by past criminal prohibition related to cannabis as a way of righting past wrongs. And yet, many cannabis businesses owned by equity licensees still struggle to turn a profit and keep their doors open.
(c)The challenge is made worse because federal law under Section 280E of Title 26 of the United States Code does not allow deduction or credit for any amount paid or incurred during the taxable year in carrying on a trade or business that consists of trafficking in controlled substances prohibited by federal or state law. The federal Controlled Substances Act, in turn, lists cannabis as a Schedule I controlled substance.
(d)It is the intent of the Legislature to help equity licensees obtain a personal income or corporate tax credit that would be equal, or in some proportion, to the normal business expenses that they would otherwise have been able to write off on their federal taxes, but for federal law. Doing so will make the business tax structure more fair for licensees that meet the definition of equity and will support cannabis businesses to succeed. credit.
SEC. 2.Section 17053.82 is added to the Revenue and Taxation Code, to read:17053.82.(a)For each taxable year beginning on or after January 1, 2022, and before January 1, 2027, there shall be allowed a credit against the net tax, as defined in Section 17039, to a qualified taxpayer in an amount equal to the amount of business expenses of the taxpayers trade or business that the taxpayer could not deduct or claim as a credit for that taxable year under federal income taxes because the amount was disallowed by Section 280E of the Internal Revenue Code, relating to expenditures in connection with the illegal sale of drugs. ten thousand dollars ($10,000).
(b)For purposes of this section, qualified taxpayer means an equity applicant or licensee as defined in subdivision (c) of Section 26249 of the Business and Professions Code.
(c)On January 1, 2023, and annually thereafter, the Department of Cannabis Control shall provide the Franchise Tax Board with a list of equity applicants and licensees, as defined in subdivision (c) of Section 26249 of the Business and Professions Code, for the purposes of administering this section.
(d)In the case where the credit allowed by this section exceeds the net tax, the excess may be carried over to reduce the net tax in the following taxable year, and succeeding seven years if necessary, until the credit is exhausted.
(e)This section and Section 23682 shall be known and may be cited as the Cannabis Equity Tax Credit.
(f)This section shall remain in effect only until December 1, 2027, and as of that date is repealed.
SEC. 3.Section 23682 is added to the Revenue and Taxation Code, to read:23682.(a)For each taxable year beginning on or after January 1, 2022, and before January 1, 2027, there shall be allowed a credit against the tax, as defined in Section 23036, to a qualified taxpayer in an amount equal to the amount of business expenses of the taxpayers trade or business that the taxpayer could not deduct or claim as a credit for that taxable year under federal income taxes because the amount was disallowed by Section 280E of the Internal Revenue Code, relating to expenditures in connection with the illegal sale of drugs. ten thousand dollars ($10,000).
(b)For purposes of this section, qualified taxpayer means an equity applicant or licensee as defined in subdivision (c) of Section 26249 of the Business and Professions Code.
(c)On January 1, 2023, and annually thereafter, the Department of Cannabis Control shall provide the Franchise Tax Board with a list of equity applicants and licensees, as defined in subdivision (c) of Section 26249 of the Business and Professions Code, for the purposes of administering this section.
(d)In the case where the credit allowed by this section exceeds the tax, the excess may be carried over to reduce the tax in the following taxable year, and succeeding seven years if necessary, until the credit is exhausted.
(e)This section and Section 17053.82 shall be known and may be cited as the Cannabis Equity Tax Credit.
(f)This section shall remain in effect only until December 1, 2027, and as of that date is repealed.
SEC. 4.For the purposes of complying with Section 41 of the Revenue and Taxation Code, with respect to Sections 17053.82 and 23682 of the Revenue and Taxation Code, as added by this act, the Legislature finds and declares all of the following:
(a)The specific goals, purposes, and objectives that the credits will achieve include all of the following:
(1)Provide cannabis equity applicants and licensees the ability to claim a credit for ordinary business deductions and credits from taxable income in the same manner that would otherwise be permitted under federal law but for the fact that cannabis is determined to be a controlled substance under federal law.(2)(1)Provide relief for individuals who are low income or who have directly or indirectly been negatively impacted by past cannabis policies.
(3)(2)Assist cannabis equity applicants and licensees to stay in business or grow their business.
(b)Detailed performance indicators for the Legislature to use in determining whether the credits meet the goals, purposes, and objectives described in subdivision (a) are the number of credits claimed and the total dollar amount of credits claimed.
(c)(1) The Franchise Tax Board shall analyze the performance indicators in subdivision (b) for each taxable year and shall report its findings, on or before July 31, 2023, and annually thereafter, in compliance with Section 9795 of the Government Code, to the Legislature.
(2)The disclosure provisions of this paragraph shall be treated as an exception to Section 19542 under Article 2 (commencing with Section 19542) of Chapter 7 of Part 10.2 of Division 2 of the Revenue and Taxation Code.
SEC. 5.This act provides for a tax levy within the meaning of Article IV of the California Constitution and shall go into immediate effect.
The Legislature makes the following findings and declarations:
(a)The War on Drugs has harmed individuals and communities, particularly communities of color.
(b)The Legislature has taken actions to assist individuals and communities harmed by past criminal prohibition related to cannabis as a way of righting past wrongs. And yet, many cannabis businesses owned by equity licensees still struggle to turn a profit and keep their doors open.
(c)The challenge is made worse because federal law under Section 280E of Title 26 of the United States Code does not allow deduction or credit for any amount paid or incurred during the taxable year in carrying on a trade or business that consists of trafficking in controlled substances prohibited by federal or state law. The federal Controlled Substances Act, in turn, lists cannabis as a Schedule I controlled substance.
(d)It is the intent of the Legislature to help equity licensees obtain a personal income or corporate tax credit that would be equal, or in some proportion, to the normal business expenses that they would otherwise have been able to write off on their federal taxes, but for federal law. Doing so will make the business tax structure more fair for licensees that meet the definition of equity and will support cannabis businesses to succeed.
SEC. 2.Section 17053.82 is added to the Revenue and Taxation Code, to read:17053.82.(a)For each taxable year beginning on or after January 1, 2022, and before January 1, 2027, there shall be allowed a credit against the net tax, as defined in Section 17039, to a qualified taxpayer in an amount equal to the amount of business expenses of the taxpayers trade or business that the taxpayer could not deduct or claim as a credit for that taxable year under federal income taxes because the amount was disallowed by Section 280E of the Internal Revenue Code, relating to expenditures in connection with the illegal sale of drugs.
(b)For purposes of this section, qualified taxpayer means an equity applicant or licensee as defined in subdivision (c) of Section 26249 of the Business and Professions Code.
(c)On January 1, 2023, and annually thereafter, the Department of Cannabis Control shall provide the Franchise Tax Board with a list of equity applicants and licensees, as defined in subdivision (c) of Section 26249 of the Business and Professions Code, for the purposes of administering this section.
(d)In the case where the credit allowed by this section exceeds the net tax, the excess may be carried over to reduce the net tax in the following taxable year, and succeeding years if necessary, until the credit is exhausted.
(e)This section and Section 23682 shall be known and may be cited as the Cannabis Equity Tax Credit.
(f)This section shall remain in effect only until December 1, 2027, and as of that date is repealed.
SEC. 3.Section 23682 is added to the Revenue and Taxation Code, to read:23682.(a)For each taxable year beginning on or after January 1, 2022, and before January 1, 2027, there shall be allowed a credit against the tax, as defined in Section 23036, to a qualified taxpayer in an amount equal to the amount of business expenses of the taxpayers trade or business that the taxpayer could not deduct or claim as a credit for that taxable year under federal income taxes because the amount was disallowed by Section 280E of the Internal Revenue Code, relating to expenditures in connection with the illegal sale of drugs.
(b)For purposes of this section, qualified taxpayer means an equity applicant or licensee as defined in subdivision (c) of Section 26249 of the Business and Professions Code.
(c)On January 1, 2023, and annually thereafter, the Department of Cannabis Control shall provide the Franchise Tax Board with a list of equity applicants and licensees, as defined in subdivision (c) of Section 26249 of the Business and Professions Code, for the purposes of administering this section.
(d)In the case where the credit allowed by this section exceeds the tax, the excess may be carried over to reduce the tax in the following taxable year, and succeeding years if necessary, until the credit is exhausted.
(e)This section and Section 17053.82 shall be known and may be cited as the Cannabis Equity Tax Credit.
(f)This section shall remain in effect only until December 1, 2027, and as of that date is repealed.
SEC. 4.For the purposes of complying with Section 41 of the Revenue and Taxation Code, with respect to Sections 17053.82 and 23682 of the Revenue and Taxation Code, as added by this act, the Legislature finds and declares all of the following:
(a)The specific goals, purposes, and objectives that the credits will achieve include all of the following:
(1)Provide cannabis equity applicants and licensees the ability to claim a credit for ordinary business deductions and credits from taxable income in the same manner that would otherwise be permitted under federal law but for the fact that cannabis is determined to be a controlled substance under federal law.
(2)Provide relief for individuals who are low income or who have directly or indirectly been negatively impacted by past cannabis policies.
(3)Assist cannabis equity applicants and licensees to stay in business or grow their business.
(b)Detailed performance indicators for the Legislature to use in determining whether the credits meet the goals, purposes, and objectives described in subdivision (a) are the number of credits claimed and the total dollar amount of credits claimed.
(c)(1) The Franchise Tax Board shall analyze the performance indicators in subdivision (b) for each taxable year and shall report its findings, on or before July 31, 2023, and annually thereafter, in compliance with Section 9795 of the Government Code, to the Legislature.
(2)The disclosure provisions of this paragraph shall be treated as an exception to Section 19542 under Article 2 (commencing with Section 19542) of Chapter 7 of Part 10.2 of Division 2 of the Revenue and Taxation Code.
SEC. 5.This act provides for a tax levy within the meaning of Article IV of the California Constitution and shall go into immediate effect.
The Legislature makes the following findings and declarations:
(a)The War on Drugs has harmed individuals and communities, particularly communities of color.
(b)The Legislature has taken actions to assist individuals and communities harmed by past criminal prohibition related to cannabis as a way of righting past wrongs. And yet, many cannabis businesses owned by equity licensees still struggle to turn a profit and keep their doors open.
(c)The challenge is made worse because federal law under Section 280E of Title 26 of the United States Code does not allow deduction or credit for any amount paid or incurred during the taxable year in carrying on a trade or business that consists of trafficking in controlled substances prohibited by federal or state law. The federal Controlled Substances Act, in turn, lists cannabis as a Schedule I controlled substance.
(d)It is the intent of the Legislature to help equity licensees obtain a personal income or corporate tax credit that would be equal, or in some proportion, to the normal business expenses that they would otherwise have been able to write off on their federal taxes, but for federal law. Doing so will make the business tax structure more fair for licensees that meet the definition of equity and will support cannabis businesses to succeed.
|
Date
|
Status
|
|---|---|
| Aug 11, 2022 | August 11 hearing: Held in committee and under submission. |
| Aug 11, 2022 | Joint Rule 62(a) suspended. |
| Aug 10, 2022 | August 10 set for first hearing. Placed on suspense file. |
| Aug 3, 2022 | August 3 hearing postponed by committee. |
| Jun 28, 2022 | From committee: Do pass and re-refer to Com. on APPR. (Ayes 14. Noes 0.) (June 28). Re-referred to Com. on APPR. |
| Jun 22, 2022 | Read second time and amended. Re-referred to Com. on B. & P. |
| Jun 21, 2022 | From committee: Do pass as amended and re-refer to Com. on B. & P. (Ayes 9. Noes 2.) (June 20). |
| Jun 13, 2022 | June 13 hearing: Heard for testimony only. |
| Jun 2, 2022 | Referred to Coms. on REV. & TAX. and B. & P. |
| May 26, 2022 | In Assembly. Read first time. Held at Desk. |
| May 25, 2022 | Read third time. Passed. (Ayes 27. Noes 7. Page 3909.) Ordered to the Assembly. |
| May 19, 2022 | From committee: Do pass. (Ayes 5. Noes 2. Page 3791.) (May 19). |
| May 17, 2022 | Set for hearing May 19. |
| May 16, 2022 | May 16 hearing: Placed on APPR suspense file. |
| May 6, 2022 | Set for hearing May 16. |
| May 5, 2022 | From committee: Do pass and re-refer to Com. on APPR. (Ayes 4. Noes 1. Page 3608.) (May 4). Re-referred to Com. on APPR. |
| Apr 28, 2022 | From committee with author's amendments. Read second time and amended. Re-referred to Com. on GOV. & F. |
| Apr 20, 2022 | Set for hearing May 4. |
| Mar 23, 2022 | Re-referred to Com. on GOV. & F. |
| Mar 16, 2022 | From committee with author's amendments. Read second time and amended. Re-referred to Com. on RLS. |
| Mar 2, 2022 | Referred to Com. on RLS. |
| Feb 22, 2022 | From printer. |
| Feb 18, 2022 | Introduced. Read first time. To Com. on RLS. for assignment. To print. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| May 25, 2022 | Senate 3rd Reading SB1293 Bradford | Senate Floor |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
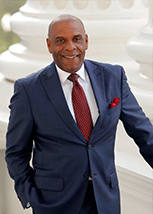
Bill Author
Bill Co-Author(s):