SB 1371: Credit disability insurance: premium payments.
- Session Year: 2015-2016
- House: Senate
- Latest Version Date: 2016-03-28
The California Finance Lenders Law generally provides for the licensure and regulation of finance lenders and brokers by the Commissioner of Business Oversight, and makes a willful violation of its provisions a crime. The law authorizes a licensee to offer credit disability insurance under specified conditions and requires premiums to be made available on a monthly or annual premium basis.
This bill would instead authorize credit disability insurance to be offered on a monthly, annual, or single premium basis. The bill would require, when a monthly premium is offered, the premium rate charged per month to not exceed a pro rata relationship to the annual or single premium.
Under existing law, there is in the State Department of Education a division known as the California State Library. The State Librarian is authorized to give advisory, consultive, and technical assistance with respect to public libraries to librarians and library authorities and assist all other authorities, state and local, in assuming their full responsibility for library services. The department is authorized to contract with counties, cities, or districts within this state, agencies of the state, and agencies of the United States Government for the purpose of providing library services and to establish and operate library service centers.
This bill would, subject to an appropriation of funds for that purpose, require the State Librarian to enter into a contract with an entity to establish and maintain a program of online homework assistance through the public libraries in the state. The program would be required to be made available free of charge to all pupils in the state.
(a)Credit disability insurance written pursuant to Section 22314 shall not provide indemnity against the risk that the borrower will become disabled for a period of less than 14 days. The insurance may provide indemnity for any single period of continuous disability of 14 days or longer, after which the risk may become compensable. The insurance may be offered with retroactive coverage to an earlier date based upon the disability having continued for a period stated in the policy, but if insurance with retroactive coverage is offered, it shall also be offered without retroactive coverage, and the premium rate for each coverage shall be separately stated in writing to the borrower.
(b)If insurance with retroactive coverage is provided, the coverage shall provide for a prorated payment based upon the fraction of the month during which the insured is disabled, provided that the insured is continuously disabled during the waiting period set forth in the policy. If insurance without retroactive coverage is provided, the coverage shall provide for a prorated payment based upon the fraction of the month during which the insured is disabled, after first excluding the elimination period set forth in the policy. For the purpose of this subdivision, a month is any period of 30 consecutive days.
(c)Credit disability insurance, if made available by a licensee, shall be available on a monthly monthly, annual, or annual single premium basis, and basis. When a monthly premium is offered, the premium by the rate charged per month shall not exceed a pro rata relationship to the annual or single premium. Credit disability insurance need not be offered for a period less than the term of the loan to which it is applicable, and no credit disability insurance shall be written for a period in excess of the term of the loan to which it is applicable.
(d)The monthly disability benefit payable with respect to an open-end loan shall not exceed the monthly payment computed pursuant to Section 22453 on the outstanding balance at the time disability is incurred.
This section does not apply to any loan of a bona fide principal amount of ten thousand dollars ($10,000) or more, as determined in accordance with Section 22251.
SECTION 1.Section 19329 is added to the Education Code, to read:19329.Subject to an appropriation of funds for this purpose in the annual Budget Act or other statute, the State Librarian shall enter into a contract with an entity to establish and maintain a program of online homework assistance through the public libraries in the state. The program shall be made available free of charge to all pupils in the state.
SEC. 2.Subject to an appropriation of funds in the annual Budget Act or other statute or the availability of other funds, the sum of three million dollars ($3,000,000) shall be granted annually to the State Librarian for purposes of establishing and maintaining a program of online homework assistance, as set forth in Section 19329 of the Education Code.
Subject to an appropriation of funds for this purpose in the annual Budget Act or other statute, the State Librarian shall enter into a contract with an entity to establish and maintain a program of online homework assistance through the public libraries in the state. The program shall be made available free of charge to all pupils in the state.
SEC. 2.Subject to an appropriation of funds in the annual Budget Act or other statute or the availability of other funds, the sum of three million dollars ($3,000,000) shall be granted annually to the State Librarian for purposes of establishing and maintaining a program of online homework assistance, as set forth in Section 19329 of the Education Code.
|
Date
|
Status
|
|---|---|
| Mar 31, 2016 | Re-referred to Com. on B. & F.I. |
| Jun 20, 2016 | June 20 set for first hearing canceled at the request of author. |
| May 12, 2016 | Referred to Com. on B. & F. |
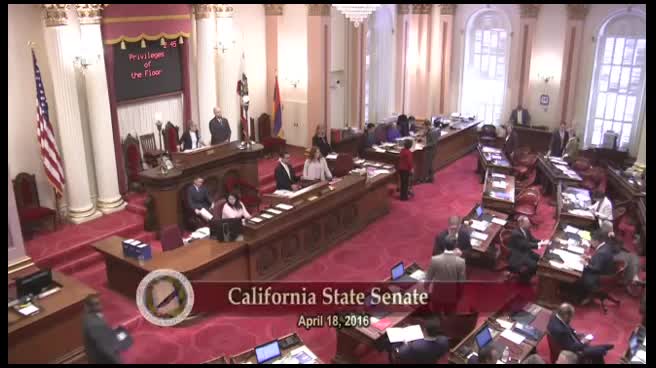
| Apr 18, 2016 | Read third time. Passed. (Ayes 39. Noes 0.) Ordered to the Assembly. |
| Apr 18, 2016 | Read third time. Passed. (Ayes 39. Noes 0. Page 3575.) Ordered to the Assembly. |
| Apr 18, 2016 | In Assembly. Read first time. Held at Desk. |
| Apr 7, 2016 | Read second time. Ordered to third reading. |
| Apr 6, 2016 | From committee: Do pass. (Ayes 7. Noes 0.) (April 6). |
| Apr 6, 2016 | From committee: Do pass. (Ayes 7. Noes 0. Page 3417.) (April 6). |
| Apr 1, 2016 | Set for hearing April 6. |
| Feb 19, 2016 | Introduced. To Com. on RLS. for assignment. To print. |
| Mar 29, 2016 | Withdrawn from committee. |
| Mar 29, 2016 | Re-referred to Com. on RLS. |
| Mar 28, 2016 | From committee with author's amendments. Read second time and amended. Re-referred to Com. on ED. |
| Mar 17, 2016 | March 30 set for first hearing canceled at the request of author. |
| Mar 11, 2016 | Set for hearing March 30. |
| Mar 3, 2016 | Referred to Com. on ED. |
| Feb 22, 2016 | Read first time. |
| Feb 22, 2016 | From printer. May be acted upon on or after March 23. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Apr 18, 2016 | Senate 3rd Reading SB1371 Galgiani | Senate Floor |
Passed |
|
| Apr 6, 2016 | Do pass | Senate Standing Committee on Banking and Financial Institutions |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| California Financial Services Association | ** Support | Apr 18, 2016 |
Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | SB |
THIRD READING
Bill No: SB 1371
:
SENATE BANKING & F.I. COMMITTEE: 7-0, 4/6/16
AYES: Glazer, Vidak, Galgiani, Hall, Hueso, Lara, Morrell
SOURCE: California Financial Services Association
DIGEST: This bill authorizes California Finance Lenders Law (CFLL) licensees to offer credit disability insurance on a single premium basis.
Existing law:
- Defines credit disability insurance as insurance on a debtor (i.e., borrower) to provide indemnity for payments becoming due on a specific loan or other credit transaction while the debtor is disabled as defined in the policy (Financial Code Section 22314 and Insurance Code Section 779.2).
- Authorizes a CFLL licensee to provide credit disability insurance to a borrower with that borrower’s consent but prohibits a CFLL licensee from requiring credit disability insurance as a condition of making a loan (Financial Code Section 22314).
- Provides that credit disability insurance, if made available by a CFLL licensee, shall be available on a monthly or annual premium basis, and further provides that the premium by the month shall not exceed a pro rata relationship to the annual premium (Financial Code Section 22315).
This bill provides that credit disability insurance may be made available by a CFLL licensee to a borrower on a single premium basis (not just on a monthly or annual premium basis, as is allowed under existing law).
Background
Credit disability insurance is commonly offered to installment borrowers as an option at the time of loan origination. Borrowers who opt into this type of insurance do so for the security that the disability insurance policy will cover their loan payments during any period of illness or injury that prevents the borrower from working. As noted above, CFLL lenders may not require these policies as a condition of making a loan to a borrower, but are authorized to offer these types of policies. All credit disability insurance terms and rates must be approved by the California Department of Insurance before being offered to a borrower in connection with a CFLL loan.
According to this bill’s sponsor, the California Financial Services Association (CFSA), the provision of California law that this bill amends dates back to the 1960s. At that time, credit disability insurance was sold either on a monthly or annual premium basis, and most installment loans were one year or less in length. Because most installment loans did not extend beyond one year, credit disability insurance could effectively be sold on a single premium basis through use of an annual premium. States across the country have since updated their laws to expressly authorize the sale of single premium credit disability insurance in connection with multi-year installment loans, but California has not.
Furthermore, California’s Department of Business Oversight has made it clear in an interpretive letter dated December 15, 2015 that, under existing California law, a CFLL licensee is not authorized to offer single premium credit disability insurance in connection with a multi-year installment loan. CFLLs may offer credit disability insurance on a monthly or annual premium basis, but a law change such as the one being sought by this bill’s sponsor is necessary to authorize the sale of credit disability insurance on a single premium basis.
Comments
If this bill is enacted, and a borrower opts into the type of insurance this bill would authorize, that borrower will be issued two checks at the time of loan origination, one made out to them and one made out to the insurer. The check to the insurer will pay the insurance policy in full, and that policy will remain in effect for the life of the loan. The cost of the insurance policy will be added to the borrower’s initial loan balance and be paid back by the borrower over the life of the loan.
This bill’s sponsor notes that single premium insurance benefits both borrowers and lenders. Borrowers are protected against coverage lapses and policy rate increases. Lenders incur lower administrative costs, due to a more streamlined billing process (the insurance premium is paid all at once, rather than on a monthly or annual basis).
FISCAL EFFECT: Appropriation: Fiscal Com.: Local:
California Financial Services Association (source)
None received
ARGUMENTS IN SUPPORT: CFSA is sponsoring this bill to authorize the use of single premium credit disability insurance by CFLL licensees on multi-year installment loans. “California is the only state we are aware of that does not permit a single-premium credit option for credit disability insurance, which is likely due to the fact that when [Section] 22315 was written, most consumer loan contracts were less than 12 months in duration. Enabling a single premium payment option would benefit consumers and lenders. For those consumers who take comfort in having credit disability insurance, SB 1371 will enable them to finance the costs into their loan and avoid any disruption of coverage. Absent a single premium option, those charges may not be included in the loan and consumers must make payments every month in order to avoid a lapse in coverage. For lenders, a single-premium option streamlines the billing process, reducing costs and increasing efficiencies.”
4/8/16 14:09:30
SENATE COMMITTEE ON
BANKING AND FINANCIAL INSTITUTIONS
Senator Steven Glazer, Chair
2015 - 2016 Regular
Bill No: Hearing Date: April 6, 2015
Author: | |||
Version: | Amended | ||
Urgency: | Fiscal: | No | |
Consultant: | |||
Subject: Credit Disability Insurance: premium payments
SUMMARY
Authorizes California Finance Lenders Law (CFLL) licensees to offer credit disability insurance on a single premium basis.
DESCRIPTION
- Provides that credit disability insurance may be made available by a CFLL licensee to a borrower on a single premium basis (not just on a monthly or annual premium basis, as is allowed under existing law).
EXISTING LAW
- Defines credit disability insurance as insurance on a debtor (i.e., borrower) to provide indemnity for payments becoming due on a specific loan or other credit transaction while the debtor is disabled as defined in the policy (Financial Code Section 22314 and Insurance Code Section 779.2).
- Authorizes a CFLL licensee to provide credit disability insurance to a borrower with that borrower’s consent but prohibits a CFLL licensee from requiring credit disability insurance as a condition of making a loan (Financial Code Section 22314).
- Provides that credit disability insurance, if made available by a CFLL licensee, shall be available on a monthly or annual premium basis, and further provides that the premium by the month shall not exceed a pro rata relationship to the annual premium (Financial Code Section 22315).
COMMENTS
- Purpose: This bill is sponsored by the California Financial Services Association (CFSA) to authorize the use of single premium credit disability insurance by CFLL licensees on multi-year installment loans.
- Background: Credit disability insurance is commonly offered to installment borrowers as an option at the time of loan origination. Borrowers who opt into this type of insurance do so for the security that the disability insurance policy will cover their loan payments during any period of illness or injury that prevents the borrower from working. As noted above, CFLL lenders may not require these policies as a condition of making a loan to a borrower, but are authorized to offer these types of policies. All credit disability insurance terms and rates must be approved by the California Department of Insurance before being offered to a borrower in connection with a CFLL loan.
According to this bill’s sponsor, the provision of California law that this bill would amend dates back to the 1960s. At that time, credit disability insurance was sold either on a monthly or annual premium basis, and most installment loans were one year or less in length. Because most installment loans did not extend beyond one year, credit disability insurance could effectively be sold on a single premium basis through use of an annual premium. States across the country have since updated their laws to expressly authorize the sale of single premium credit disability insurance in connection with multi-year installment loans, but California has not.
Furthermore, California’s Department of Business Oversight has made it clear in an interpretive letter dated December 15, 2015 that, under existing California law, a CFLL licensee is not authorized to offer single premium credit disability insurance in connection with a multi-year installment loan. CFLLs may offer credit disability insurance on a monthly or annual premium basis, but a law change such as the one being sought by this bill’s sponsor is necessary to authorize the sale of credit disability insurance on a single premium basis. - Discussion: If this bill is enacted, and a borrower opts into the type of insurance this bill would authorize, that borrower will be issued two checks at the time of loan origination, one made out to them and one made out to the insurer. The check to the insurer will pay the insurance policy in full, and that policy will remain in effect for the life of the loan. The cost of the insurance policy will be added to the borrower’s initial loan balance and be paid back by the borrower over the life of the loan.
This bill’s sponsor notes that single premium insurance benefits both borrowers and lenders. Borrowers are protected against coverage lapses and policy rate increases. Lenders incur lower administrative costs, due to a more streamlined billing process (the insurance premium is paid all at once, rather than on a monthly or annual basis). - Summary of Arguments in Support: CFSA is sponsoring this bill for the reasons stated above. “California is the only state we are aware of that does not permit a single-premium credit option for credit disability insurance, which is likely due to the fact that when [Section] 22315 was written, most consumer loan contracts were less than 12 months in duration. Enabling a single premium payment option would benefit consumers and lenders. For those consumers who take comfort in having credit disability insurance, SB 1371 will enable them to finance the costs into their loan and avoid any disruption of coverage. Absent a single premium option, those charges may not be included in the loan and consumers must make payments every month in order to avoid a lapse in coverage. For lenders, a single-premium option streamlines the billing process, reducing costs and increasing efficiencies.”
- Summary of Arguments in Opposition: None received.
LIST OF REGISTERED SUPPORT/OPPOSITION
Support
California Financial Services Association (sponsor)
Opposition
None received
-- END --
Bill Author
Bill Co-Author(s):