SB 657: Personal Income Tax Law: deferred compensation: exclusions: long-term qualified tuition program.
- Session Year: 2025-2026
- House: Senate
- Latest Version Date: 2025-04-29
Current Status:
Failed
(2026-02-02: Returned to Secretary of Senate pursuant to Joint Rule 56.)
Introduced
In Committee
Awaiting First Chamber Vote
Passed First Chamber
In Committee
Awaiting Second Chamber Vote
Passed Second Chamber
Enacted
The Personal Income Tax Law, in conformity with federal income tax law, generally defines gross income as income from whatever source derived, except as specifically excluded, and provides various exclusions from gross income. Existing law, known as the Golden State Scholarshare Trust Act, establishes the Golden State Scholarshare College Savings Trust (Scholarshare trust), under the administration of the Scholarshare Investment Board, to provide financial aid for postsecondary education costs of participating students. Existing state and federal law generally includes in gross income distributions from a qualified tuition program, as defined to include the Scholarshare trust, except as provided.
Existing federal law, the Consolidated Appropriations Act, 2023, excludes from gross income, for federal income tax purposes, distributions from a qualified tuition program that are made after December 31, 2023, and are paid in a direct trustee-to-trustee transfer to a Roth IRA, as described.
This bill would exempt from gross income distribution made from a long-term qualified tuition program during the taxable years beginning on or after January 1, 2025, and before January 1, 2030, that are paid in a direct trustee-to-trustee transfer to a Roth IRA, and would conform state tax law to those changes relating to federal law, as described above.
Existing law requires a bill authorizing a new tax expenditure to contain, among other things, specific goals, purposes, and objectives the tax expenditure will achieve, detailed performance indicators, and data collection requirements.
This bill would include additional information required for any bill authorizing a new tax expenditure.
This bill would take effect immediately as a tax levy.
The Personal Income Tax Law, in conformity with federal income tax law, generally defines gross income as income from whatever source derived, except as specifically excluded, and provides various exclusions from gross income. Existing law, known as the Golden State Scholarshare Trust Act, establishes the Golden State Scholarshare College Savings Trust (Scholarshare trust), under the administration of the Scholarshare Investment Board, to provide financial aid for postsecondary education costs of participating students. Existing state and federal law generally includes in gross income distributions from a qualified tuition program, as defined to include the Scholarshare trust, except as provided.
Existing federal law, the Consolidated Appropriations Act, 2023, excludes from gross income, for federal income tax purposes, distributions from a qualified tuition program that are made after December 31, 2023, and are paid in a direct trustee-to-trustee transfer to a Roth IRA, as described.
This bill would exempt from gross income distribution made from a long-term qualified tuition program during the taxable years beginning on or after January 1, 2025, and before January 1, 2030, that are paid in a direct trustee-to-trustee transfer to a Roth IRA, and would conform state tax law to those changes relating to federal law, as described above.
Existing law requires a bill authorizing a new tax expenditure to contain, among other things, specific goals, purposes, and objectives the tax expenditure will achieve, detailed performance indicators, and data collection requirements.
This bill would include additional information required for any bill authorizing a new tax expenditure.
This bill would take effect immediately as a tax levy.
(a)For purposes of this section, the following terms have the following meanings as provided in the Golden State Scholarshare Trust Act (Article 19 (commencing with Section 69980) of Chapter 2 of Part 42 of the Education Code):
(1)Beneficiary has the meaning set forth in subdivision (c) of Section 69980 of the Education Code.
(2)Benefit has the meaning set forth in subdivision (d) of Section 69980 of the Education Code.
(3)Participant has the meaning set forth in subdivision (h) of Section 69980 of the Education Code.
(4)Participation agreement has the meaning set forth in subdivision (i) of Section 69980 of the Education Code.
(5)Scholarshare trust has the meaning set forth in subdivision (f) of Section 69980 of the Education Code.
(b)For taxable years beginning on or after January 1, 1998, and before January 1, 2002, except as otherwise provided in subdivision (c), gross income of a beneficiary or a participant does not include any of the following:
(1)Any distribution or earnings under a Scholarshare trust participation agreement, as provided in Article 19 (commencing with Section 69980) of Chapter 2 of Part 42 of the Education Code.
(2)Any contribution to the Scholarshare trust on behalf of a beneficiary shall not be includable as gross income of that beneficiary.
(c)For taxable years beginning on or after January 1, 1998, and before January 1, 2002:
(1)Any distribution under a Scholarshare trust participation agreement shall be includable in the gross income of the distributee in the manner as provided under Section 72 of the Internal Revenue Code, as modified by Section 17085, to the extent not excluded from gross income under this part. For purposes of applying Section 72 of the Internal Revenue Code, the following apply:
(A)All Scholarshare trust accounts of which an individual is a beneficiary shall be treated as one account, except as otherwise provided.
(B)All distributions during a taxable year shall be treated as one distribution.
(C)The value of the participation agreement, income on the participation agreement, and investment in the participation agreement shall be computed as of the close of the calendar year in which the taxable year begins.
(2)A contribution by a for-profit or nonprofit entity, or by a state or local government agency, for the benefit of an owner or employee of that entity or a beneficiary whom the owner or employee has the power to designate, including the owner or employees minor children, shall be included in the gross income of that owner or employee in the year the contribution is made.
(3)For purposes of this subdivision, distribution includes any benefit furnished to a beneficiary under a participation agreement, as provided in Article 19 (commencing with Section 69980) of Chapter 2 of Part 42 of the Education Code.
(4)(A)Paragraph (1) shall not apply to that portion of any distribution that, within 60 days of distribution, is transferred to the credit of another beneficiary under the Scholarshare trust who is a member of the family, as that term is used in Section 529(e)(2) of the Internal Revenue Code, as amended by Section 211 of the Taxpayer Relief Act of 1997 (Public Law 105-34), of the former beneficiary of that Scholarshare trust.
(B)Any change in the beneficiary of an interest in the Scholarshare trust shall not be treated as a distribution for purposes of paragraph (1) if the new beneficiary is a member of the family, as that term is used in Section 529(e)(2) of the Internal Revenue Code, as amended by Section 211 of the Taxpayer Relief Act of 1997 (Public Law 105-34), of the former beneficiary of that Scholarshare trust.
(d)For taxable years beginning on or after January 1, 2002, Sections 529(c) and 529(e) of the Internal Revenue Code, relating to tax treatment of designated beneficiaries and contributors and to other definitions and special rules, respectively, shall apply, except as otherwise provided in Part 11 (commencing with Section 23001) and this part.
(e)(1)The amendments made by Section 302(a)(1) of Division Q of the Consolidated Appropriations Act, 2016 (Public Law 114-113) to Section 529(e) of the Internal Revenue Code, relating to other definitions and special rules, shall apply except as otherwise provided.
(2)The amendments made by Section 302(b)(1) of Division Q of the Consolidated Appropriations Act, 2016 (Public Law 114-113) to Section 529(c)(3) of the Internal Revenue Code, relating to distributions, shall apply, except as otherwise provided.
(3)The amendments made by Section 302(c)(1) of Division Q of the Consolidated Appropriations Act, 2016 (Public Law 114-113) to Section 529(c)(3)(D) of the Internal Revenue Code, relating to special rule for contributions of refunded amounts, shall apply, except as otherwise provided.
(f)(1)The amendments made by Section 11025(a) of the Tax Cuts and Jobs Act (Public Law 115-97) to Section 529(c)(3)(C) of the Internal Revenue Code, relating to change in beneficiaries or programs, shall apply, except as otherwise provided.
(2)(A)The amendments made by Section 11032(a)(1) of the Tax Cuts and Jobs Act (Public Law 115-97) to Section 529(c) of the Internal Revenue Code, relating to tax treatment of designated beneficiaries and contributors, shall not apply, except as otherwise provided.
(B)The amendments made by Section 11032(a)(2) of the Tax Cuts and Jobs Act (Public Law 115-97) to Section 529(e)(3)(A) of the Internal Revenue Code, relating to qualified higher education expenses, shall not apply, except as otherwise provided.
(C)In the case of any distribution made under Section 529(e)(3)(A) of the Internal Revenue Code, as amended by Section 11032(a)(2) of the Tax Cuts and Jobs Act (Public Law 115-97), that would be treated for federal income tax purposes as a qualified higher education expense under Section 529(c)(7) of the Internal Revenue Code, as added by Section 11032(a)(1) of the Tax Cuts and Jobs Act (Public Law 115-97), the amount of that distribution shall, notwithstanding anything in Section 529 of the Internal Revenue Code to the contrary, be includable in the gross income of the distributee in the manner as provided under Section 72 of the Internal Revenue Code.
(D)Any distribution includable in the gross income of a distributee under subparagraph (C) shall not affect the exempt status of the qualified tuition program under Section 529 of the Internal Revenue Code for purposes of this part.
(g)(1)The amendments made by Section 126(a) of Title I of Division T of the Consolidated Appropriations Act, 2023 (Public Law 117-328) to Section 529(c) of the Internal Revenue Code, relating to special rollovers to Roth IRAs from long-term qualified tuition programs, shall apply with respect to distributions made during taxable years beginning on or after January 1, 2025, and before January 1, 2030.
(2)The amendments made by Section 126(c) of Title I of Division T of the Consolidated Appropriations Act, 2023 (Public Law 117-328) to Section 529(d) of the Internal Revenue Code, relating to reporting, shall apply with respect to distributions made in taxable years beginning on or after January 1, 2025, and before January 1, 2030.
(3)For the purpose of complying with Section 41, the Legislature finds and declares the following with respect to the exclusions from income for distributions allowed by this section:
(A)The specific goal that the exclusion will achieve is to conform to federal law to bring tax relief and ease return preparation for taxpayers who transfer funds under this subdivision.
(B)Detailed performance indicators for the Legislature to use in determining whether the exclusion meets the goal described in subparagraph (A) are the number of taxpayers that make the transfer permitted under this subdivision and the average amount of the transfer permitted under this subdivision.(B)There is no available data to collect or report with respect to the exclusion.
(h)(1)For taxable years beginning on or after January 1, 2021, the amendments made by Section 302(a) of Division O of the Further Consolidated Appropriations Act, 2020 (Public Law 116-94) to Section 529(c)(8) of the Internal Revenue Code, relating to distributions for certain expenses associated with registered apprenticeship programs, shall apply.
(2)For taxable years beginning on or after January 1, 2021, the amendments made by Section 302(b)(1) of Division O of the Further Consolidated Appropriations Act, 2020 (Public Law 116-94) to Section 529(c)(9) of the Internal Revenue Code, relating to distributions for qualified education loan repayments, shall apply.
SEC. 2.Section 17140.3 of the Revenue and Taxation Code is amended to read:17140.3.Section 529 of the Internal Revenue Code, relating to qualified state tuition programs, shall apply, except as otherwise provided.
(a)Section 529(a) of the Internal Revenue Code is modified as follows:
(1)By substituting the phrase under this part and Part 11 (commencing with Section 23001) in lieu of the phrase under this subtitle.
(2)By substituting Article 2 (commencing with Section 23731) in lieu of Section 511.
(b)A copy of the report required to be filed with the Secretary of the Treasury under Section 529(d) of the Internal Revenue Code shall be filed with the Franchise Tax Board at the same time and in the same manner as specified in that section.
(c)(1)The amendments made by Section 302(a)(1) of Division Q of the Consolidated Appropriations Act, 2016 (Public Law 114-113) to Section 529(e) of the Internal Revenue Code, relating to other definitions and special rules, shall apply except as otherwise provided.
(2)The amendments made by Section 302(b)(1) of Division Q of the Consolidated Appropriations Act, 2016 (Public Law 114-113) to Section 529(c)(3) of the Internal Revenue Code, relating to distributions, shall apply, except as otherwise provided.
(3)The amendments made by Section 302(c)(1) of Division Q of the Consolidated Appropriations Act, 2016 (Public Law 114-113) to Section 529(c)(3)(D) of the Internal Revenue Code, relating to special rule for contributions of refunded amounts, shall apply, except as otherwise provided.
(d)(1)The amendments made by Section 11025(a) of the Tax Cuts and Jobs Act (Public Law 115-97) to Section 529(c)(3)(C) of the Internal Revenue Code, relating to change in beneficiaries or programs, shall apply, except as otherwise provided.
(2)(A)The amendments made by Section 11032(a)(1) of the Tax Cuts and Jobs Act (Public Law 115-97) to Section 529(c) of the Internal Revenue Code, relating to tax treatment of designated beneficiaries and contributors, shall not apply, except as otherwise provided.
(B)The amendments made by Section 11032(a)(2) of the Tax Cuts and Jobs Act (Public Law 115-97) to Section 529(e)(3)(A) of the Internal Revenue Code, relating to qualified higher education expenses, shall not apply, except as otherwise provided.
(C)In the case of any distribution made under Section 529(e)(3)(A) of the Internal Revenue Code, as amended by Section 11032(a)(2) of the Tax Cuts and Jobs Act (Public Law 115-97), that would be treated for federal income tax purposes as a qualified higher education expense under Section 529(c)(7) of the Internal Revenue Code, as added by Section 11032(a)(1) of the Tax Cuts and Jobs Act (Public Law 115-97), the amount of that distribution shall, notwithstanding anything in Section 529 of the Internal Revenue Code to the contrary, be includable in the gross income of the distributee in the manner as provided under Section 72 of the Internal Revenue Code.
(D)Any distribution includable in the gross income of a distributee under subparagraph (C) shall not affect the exempt status of the qualified tuition program under Section 529 of the Internal Revenue Code for purposes of this part.
(e)(1)The amendments made by Section 126(a) of Title I of Division T of the Consolidated Appropriations Act, 2023 (Public Law 117-328) to Section 529(c) of the Internal Revenue Code, relating to special rollovers to Roth IRAs from long-term qualified tuition programs, shall apply with respect to distributions made during taxable years beginning on or after January 1, 2025, and before January 1, 2030.
(2)The amendments made by Section 126(c) of Title I of Division T of the Consolidated Appropriations Act, 2023 (Public Law 117-328) to Section 529(d) of the Internal Revenue Code, relating to reporting, shall apply with respect to distributions made in taxable years beginning on or after January 1, 2025, and before January 1, 2030.
(3)For the purpose of complying with Section 41, the Legislature finds and declares the following with respect to the exclusions from income for distributions allowed by this section:
(A)The specific goal that the exclusion will achieve is to conform to federal law to bring tax relief and ease return preparation for taxpayers who transfer funds under this subdivision.
(B)Detailed performance indicators for the Legislature to use in determining whether the exclusion meets the goal described in subparagraph (A) are the number of taxpayers that make the transfer permitted under this subdivision and the average amount of the transfer permitted under this subdivision.(B)There is no available data to collect or report with respect to the exclusion.
(f)(1)For taxable years beginning on or after January 1, 2021, the amendments made by Section 302(a) of Division O of the Further Consolidated Appropriations Act, 2020 (Public Law 116-94) to Section 529(c)(8) of the Internal Revenue Code, relating to distributions for certain expenses associated with registered apprenticeship programs, shall apply.
(2)For taxable years beginning on or after January 1, 2021, the amendments made by Section 302(b)(1) of Division O of the Further Consolidated Appropriations Act, 2020 (Public Law 116-94) to Section 529(c)(9) of the Internal Revenue Code, relating to distributions for qualified education loan repayments, shall apply.
SEC. 3.This act provides for a tax levy within the meaning of Article IV of the California Constitution and shall go into immediate effect.
(a)For purposes of this section, the following terms have the following meanings as provided in the Golden State Scholarshare Trust Act (Article 19 (commencing with Section 69980) of Chapter 2 of Part 42 of the Education Code):
(1)Beneficiary has the meaning set forth in subdivision (c) of Section 69980 of the Education Code.
(2)Benefit has the meaning set forth in subdivision (d) of Section 69980 of the Education Code.
(3)Participant has the meaning set forth in subdivision (h) of Section 69980 of the Education Code.
(4)Participation agreement has the meaning set forth in subdivision (i) of Section 69980 of the Education Code.
(5)Scholarshare trust has the meaning set forth in subdivision (f) of Section 69980 of the Education Code.
(b)For taxable years beginning on or after January 1, 1998, and before January 1, 2002, except as otherwise provided in subdivision (c), gross income of a beneficiary or a participant does not include any of the following:
(1)Any distribution or earnings under a Scholarshare trust participation agreement, as provided in Article 19 (commencing with Section 69980) of Chapter 2 of Part 42 of the Education Code.
(2)Any contribution to the Scholarshare trust on behalf of a beneficiary shall not be includable as gross income of that beneficiary.
(c)For taxable years beginning on or after January 1, 1998, and before January 1, 2002:
(1)Any distribution under a Scholarshare trust participation agreement shall be includable in the gross income of the distributee in the manner as provided under Section 72 of the Internal Revenue Code, as modified by Section 17085, to the extent not excluded from gross income under this part. For purposes of applying Section 72 of the Internal Revenue Code, the following apply:
(A)All Scholarshare trust accounts of which an individual is a beneficiary shall be treated as one account, except as otherwise provided.
(B)All distributions during a taxable year shall be treated as one distribution.
(C)The value of the participation agreement, income on the participation agreement, and investment in the participation agreement shall be computed as of the close of the calendar year in which the taxable year begins.
(2)A contribution by a for-profit or nonprofit entity, or by a state or local government agency, for the benefit of an owner or employee of that entity or a beneficiary whom the owner or employee has the power to designate, including the owner or employees minor children, shall be included in the gross income of that owner or employee in the year the contribution is made.
(3)For purposes of this subdivision, distribution includes any benefit furnished to a beneficiary under a participation agreement, as provided in Article 19 (commencing with Section 69980) of Chapter 2 of Part 42 of the Education Code.
(4)(A)Paragraph (1) shall not apply to that portion of any distribution that, within 60 days of distribution, is transferred to the credit of another beneficiary under the Scholarshare trust who is a member of the family, as that term is used in Section 529(e)(2) of the Internal Revenue Code, as amended by Section 211 of the Taxpayer Relief Act of 1997 (Public Law 105-34), of the former beneficiary of that Scholarshare trust.
(B)Any change in the beneficiary of an interest in the Scholarshare trust shall not be treated as a distribution for purposes of paragraph (1) if the new beneficiary is a member of the family, as that term is used in Section 529(e)(2) of the Internal Revenue Code, as amended by Section 211 of the Taxpayer Relief Act of 1997 (Public Law 105-34), of the former beneficiary of that Scholarshare trust.
(d)For taxable years beginning on or after January 1, 2002, Sections 529(c) and 529(e) of the Internal Revenue Code, relating to tax treatment of designated beneficiaries and contributors and to other definitions and special rules, respectively, shall apply, except as otherwise provided in Part 11 (commencing with Section 23001) and this part.
(e)(1)The amendments made by Section 302(a)(1) of Division Q of the Consolidated Appropriations Act, 2016 (Public Law 114-113) to Section 529(e) of the Internal Revenue Code, relating to other definitions and special rules, shall apply except as otherwise provided.
(2)The amendments made by Section 302(b)(1) of Division Q of the Consolidated Appropriations Act, 2016 (Public Law 114-113) to Section 529(c)(3) of the Internal Revenue Code, relating to distributions, shall apply, except as otherwise provided.
(3)The amendments made by Section 302(c)(1) of Division Q of the Consolidated Appropriations Act, 2016 (Public Law 114-113) to Section 529(c)(3)(D) of the Internal Revenue Code, relating to special rule for contributions of refunded amounts, shall apply, except as otherwise provided.
(f)(1)The amendments made by Section 11025(a) of the Tax Cuts and Jobs Act (Public Law 115-97) to Section 529(c)(3)(C) of the Internal Revenue Code, relating to change in beneficiaries or programs, shall apply, except as otherwise provided.
(2)(A)The amendments made by Section 11032(a)(1) of the Tax Cuts and Jobs Act (Public Law 115-97) to Section 529(c) of the Internal Revenue Code, relating to tax treatment of designated beneficiaries and contributors, shall not apply, except as otherwise provided.
(B)The amendments made by Section 11032(a)(2) of the Tax Cuts and Jobs Act (Public Law 115-97) to Section 529(e)(3)(A) of the Internal Revenue Code, relating to qualified higher education expenses, shall not apply, except as otherwise provided.
(C)In the case of any distribution made under Section 529(e)(3)(A) of the Internal Revenue Code, as amended by Section 11032(a)(2) of the Tax Cuts and Jobs Act (Public Law 115-97), that would be treated for federal income tax purposes as a qualified higher education expense under Section 529(c)(7) of the Internal Revenue Code, as added by Section 11032(a)(1) of the Tax Cuts and Jobs Act (Public Law 115-97), the amount of that distribution shall, notwithstanding anything in Section 529 of the Internal Revenue Code to the contrary, be includable in the gross income of the distributee in the manner as provided under Section 72 of the Internal Revenue Code.
(D)Any distribution includable in the gross income of a distributee under subparagraph (C) shall not affect the exempt status of the qualified tuition program under Section 529 of the Internal Revenue Code for purposes of this part.
(g)(1)The amendments made by Section 126(a) of Title I of Division T of the Consolidated Appropriations Act, 2023 (Public Law 117-328) to Section 529(c) of the Internal Revenue Code, relating to special rollovers to Roth IRAs from long-term qualified tuition programs, shall apply with respect to distributions made during taxable years beginning on or after January 1, 2025, and before January 1, 2030.
(2)The amendments made by Section 126(c) of Title I of Division T of the Consolidated Appropriations Act, 2023 (Public Law 117-328) to Section 529(d) of the Internal Revenue Code, relating to reporting, shall apply with respect to distributions made in taxable years beginning on or after January 1, 2025, and before January 1, 2030.
(3)For the purpose of complying with Section 41, the Legislature finds and declares the following with respect to the exclusions from income for distributions allowed by this section:
(A)The specific goal that the exclusion will achieve is to conform to federal law to bring tax relief and ease return preparation for taxpayers who transfer funds under this subdivision.
(B)Detailed performance indicators for the Legislature to use in determining whether the exclusion meets the goal described in subparagraph (A) are the number of taxpayers that make the transfer permitted under this subdivision and the average amount of the transfer permitted under this subdivision.
(g)(h)(1)For taxable years beginning on or after January 1, 2021, the amendments made by Section 302(a) of Division O of the Further Consolidated Appropriations Act, 2020 (Public Law 116-94) to Section 529(c)(8) of the Internal Revenue Code, relating to distributions for certain expenses associated with registered apprenticeship programs, shall apply.
(2)For taxable years beginning on or after January 1, 2021, the amendments made by Section 302(b)(1) of Division O of the Further Consolidated Appropriations Act, 2020 (Public Law 116-94) to Section 529(c)(9) of the Internal Revenue Code, relating to distributions for qualified education loan repayments, shall apply.
SEC. 2.Section 17140.3 of the Revenue and Taxation Code is amended to read:17140.3.Section 529 of the Internal Revenue Code, relating to qualified state tuition programs, shall apply, except as otherwise provided.
(a)Section 529(a) of the Internal Revenue Code is modified as follows:
(1)By substituting the phrase under this part and Part 11 (commencing with Section 23001) in lieu of the phrase under this subtitle.
(2)By substituting Article 2 (commencing with Section 23731) in lieu of Section 511.
(b)A copy of the report required to be filed with the Secretary of the Treasury under Section 529(d) of the Internal Revenue Code shall be filed with the Franchise Tax Board at the same time and in the same manner as specified in that section.
(c)(1)The amendments made by Section 302(a)(1) of Division Q of the Consolidated Appropriations Act, 2016 (Public Law 114-113) to Section 529(e) of the Internal Revenue Code, relating to other definitions and special rules, shall apply except as otherwise provided.
(2)The amendments made by Section 302(b)(1) of Division Q of the Consolidated Appropriations Act, 2016 (Public Law 114-113) to Section 529(c)(3) of the Internal Revenue Code, relating to distributions, shall apply, except as otherwise provided.
(3)The amendments made by Section 302(c)(1) of Division Q of the Consolidated Appropriations Act, 2016 (Public Law 114-113) to Section 529(c)(3)(D) of the Internal Revenue Code, relating to special rule for contributions of refunded amounts, shall apply, except as otherwise provided.
(d)(1)The amendments made by Section 11025(a) of the Tax Cuts and Jobs Act (Public Law 115-97) to Section 529(c)(3)(C) of the Internal Revenue Code, relating to change in beneficiaries or programs, shall apply, except as otherwise provided.
(2)(A)The amendments made by Section 11032(a)(1) of the Tax Cuts and Jobs Act (Public Law 115-97) to Section 529(c) of the Internal Revenue Code, relating to tax treatment of designated beneficiaries and contributors, shall not apply, except as otherwise provided.
(B)The amendments made by Section 11032(a)(2) of the Tax Cuts and Jobs Act (Public Law 115-97) to Section 529(e)(3)(A) of the Internal Revenue Code, relating to qualified higher education expenses, shall not apply, except as otherwise provided.
(C)In the case of any distribution made under Section 529(e)(3)(A) of the Internal Revenue Code, as amended by Section 11032(a)(2) of the Tax Cuts and Jobs Act (Public Law 115-97), that would be treated for federal income tax purposes as a qualified higher education expense under Section 529(c)(7) of the Internal Revenue Code, as added by Section 11032(a)(1) of the Tax Cuts and Jobs Act (Public Law 115-97), the amount of that distribution shall, notwithstanding anything in Section 529 of the Internal Revenue Code to the contrary, be includable in the gross income of the distributee in the manner as provided under Section 72 of the Internal Revenue Code.
(D)Any distribution includable in the gross income of a distributee under subparagraph (C) shall not affect the exempt status of the qualified tuition program under Section 529 of the Internal Revenue Code for purposes of this part.
(e)(1)The amendments made by Section 126(a) of Title I of Division T of the Consolidated Appropriations Act, 2023 (Public Law 117-328) to Section 529(c) of the Internal Revenue Code, relating to special rollovers to Roth IRAs from long-term qualified tuition programs, shall apply with respect to distributions made during taxable years beginning on or after January 1, 2025, and before January 1, 2030.
(2)The amendments made by Section 126(c) of Title I of Division T of the Consolidated Appropriations Act, 2023 (Public Law 117-328) to Section 529(d) of the Internal Revenue Code, relating to reporting, shall apply with respect to distributions made in taxable years beginning on or after January 1, 2025, and before January 1, 2030.
(3)For the purpose of complying with Section 41, the Legislature finds and declares the following with respect to the exclusions from income for distributions allowed by this section:
(A)The specific goal that the exclusion will achieve is to conform to federal law to bring tax relief and ease return preparation for taxpayers who transfer funds under this subdivision.
(B)Detailed performance indicators for the Legislature to use in determining whether the exclusion meets the goal described in subparagraph (A) are the number of taxpayers that make the transfer permitted under this subdivision and the average amount of the transfer permitted under this subdivision.
(e)(f)(1)For taxable years beginning on or after January 1, 2021, the amendments made by Section 302(a) of Division O of the Further Consolidated Appropriations Act, 2020 (Public Law 116-94) to Section 529(c)(8) of the Internal Revenue Code, relating to distributions for certain expenses associated with registered apprenticeship programs, shall apply.
(2)For taxable years beginning on or after January 1, 2021, the amendments made by Section 302(b)(1) of Division O of the Further Consolidated Appropriations Act, 2020 (Public Law 116-94) to Section 529(c)(9) of the Internal Revenue Code, relating to distributions for qualified education loan repayments, shall apply.
SEC. 3.This act provides for a tax levy within the meaning of Article IV of the California Constitution and shall go into immediate effect.
|
Date
|
Status
|
|---|---|
| Feb 2, 2026 | Returned to Secretary of Senate pursuant to Joint Rule 56. |
| May 23, 2025 | May 23 hearing: Held in committee and under submission. |
| May 20, 2025 | Set for hearing May 23. |
| May 19, 2025 | May 19 hearing: Placed on APPR. suspense file. |
| May 15, 2025 | Set for hearing May 19. |
| May 14, 2025 | From committee: Do pass and re-refer to Com. on APPR. (Ayes 4. Noes 0. Page 1083.) (May 14). Re-referred to Com. on APPR. |
| Apr 29, 2025 | From committee with author's amendments. Read second time and amended. Re-referred to Com. on REV. & TAX. |
| Mar 18, 2025 | Set for hearing May 14. |
| Mar 5, 2025 | Referred to Com. on REV. & TAX. |
| Feb 21, 2025 | From printer. May be acted upon on or after March 23. |
| Feb 20, 2025 | Introduced. Read first time. To Com. on RLS. for assignment. To print. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| May 19, 2025 | Placed on suspense file | Senate Standing Committee on Appropriations |
Passed |
|
| May 14, 2025 | Do pass, but first be re-referred to the Committee on [Appropriations] | Senate Standing Committee on Revenue and Taxation |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| California State Treasurer | ** Support | |
| California Tax Reform Association | ** Against | |
| Fidelity Investments | ** Support | |
| Financial Planning Association | ** Support | |
| Financial Planning Association of California | ** Support | |
| Securities Industry And Financial Markets Association | ** Support |
SENATE COMMITTEE ON
Senator Anna Caballero, Chair
2025 - 2026 Regular Session
SB 657 (Niello) - Personal Income Tax Law: deferred compensation: exclusions: long-term qualified tuition program
Version: | Policy Vote: |
Urgency: | Mandate: |
Hearing Date: | Consultant: |
Bill Summary:
SB 657 would exclude from gross income a special rollover distribution from a Qualified Tuition Program to a Roth Individual Retirement Account (IRA), as specified.
Fiscal Impact:
The Franchise Tax Board (FTB) estimates that this bill would result in General Fund revenue losses of $12 million in 2025-26, $8.5 million in 2026-27, and $10 million in 2027-28. FTB’s administrative costs have yet to be identified.
Background:
Tax expenditure programs (TEPs) are special tax provisions that reduce the amount of revenues the “basic” tax system would otherwise generate in order to provide (1) benefits to certain groups of taxpayers, and/or (2) incentives to encourage certain types of behavior and activities, such as charitable giving. Specifically, current law provides for, among other things, various income and corporation tax credits and deductions, as well as exemptions from the sales and use tax. The Department of Finance is required to publish a list of TEPs (currently totaling several hundred), which currently exceed $91 billion annually.
State law does not automatically conform to federal changes. Instead, the Legislature must conform to federal changes. Specifically it can pass (1) an individual bill that conforms to a specific federal tax provision, or (2) an omnibus bill to conforms state law to federal law as of a specified date. Current state law generally conforms to federal tax law as of January 1, 2015. California conforms to Internal Revenue Code (IRC) 529 through standalone conformity (AB 2797, Committee on Budget, 1998), which has been modified and updated over the years. California modifies the additional 10 percent tax on excess distributions to instead be an additional tax of 2.5 percent for state purposes. Similar to federal law, state law provides that contributions made to a qualified tuition program (QTP), including the ScholarShare program, are not deductible.
A QTP, commonly called a 529 plan, is a tax-advantaged savings plan for future educational expenses. Two types of 529 plans are available: college savings plans and prepaid plans. A state, state agency, or instrumentality of a state can establish and maintain either a college savings plan or a prepaid plan. Additionally, eligible educational institutions can establish and maintain a prepayment plan, but not a savings plan. QTP contributions on behalf of any beneficiary cannot be more than the amount necessary to provide for the beneficiary's qualified higher education expenses. The contributions to the QTP are made using after-tax dollars.
529 college savings plans allow contributors to invest in various financial instruments, which can earn interest, dividends, and capital gains based on the performance of these investments. When making a distribution from 529 college savings plans for qualified education expenses or other qualified purposes pursuant to IRC 529, the earnings are not taxed, nor are the principal contributions, as it is simply a return of the original after-tax contributions. If distributions are made for non-qualified purposes, the earnings portion is taxed as income and subject to a 10 percent federal penalty and a 2.5 percent state penalty.
Alternatively, a 529 prepaid tuition plan locks in current tuition rates, thus offering a hedge against future tuition inflation. The purchase price paid per tuition unit becomes the basis for the 529 prepaid tuition investment contract. When the 529 prepaid tuition plan makes a distribution, the prepaid units are assigned a value at the current tuition rate or the rate spelled out in the investment contract. The difference between the basis and the current assigned value is the plan’s “earnings.” These earnings are not subject to tax if made for qualified education expenses, qualified purposes pursuant to IRC 529, or were the result of a refund for a scholarship, Veterans Affairs benefit, or service-academy value. However, a distribution for any other purpose will result in a 10 percent federal penalty and a 2.5 percent state penalty on earnings. The return of basis is not subject to tax because it was paid with after-tax dollars.
The Golden State ScholarShare Trust Program is a 529 savings plan administered by the State Treasurer's Office that offers California families a tax-advantaged college tuition savings plan to invest and save for college. ScholarShare is the state’s only QTP. However, California universities and colleges may participate in institutional plans or accept QTPs from other states.
Originally, QTPs were only authorized to pay for a beneficiary's specified qualified higher education expenses at an eligible institution of higher education. However, recent changes have expanded the scope of these expenses to include:
- Tuition expenses in connection with a beneficiary's enrollment or attendance at an elementary or secondary (kindergarten through grade 12) public, private, or religious school up to $10,000 per year from all of the beneficiary's QTPs. California does not confirm to this federal provision.
- Expenses for fees, books, supplies, and equipment required for participation in an apprenticeship program registered and certified with the Secretary of Labor. (Federal and state - AB 340 Ward, 2021.)
- Qualified education loan repayments on a designated beneficiary's or their sibling's student loan, limited to $10,000 in an individual's lifetime. (Federal and state - AB 340 Ward, 2021.)
- Allowing families to roll over funds from a 529 education savings account to an ABLE account for the same beneficiary or a member of the beneficiary's family. (Federal and state - AB 91 Burke, 2019).
Another recent change to IRC 529 (SECURE 2.0)permits the beneficiary of a QTP a special rollover distribution to their Roth IRA. For the rollover earnings to be excluded from gross income, the rollover amount (1) must be paid through a direct trustee-to-trustee transfer, (2) must be distributed from a QTP account that has been open for at least 15 years as of the date of the distribution, (3) must not exceed the amount contributed to the QTP (and attributable earnings) before the 5-year period ending on the date of the distribution, (4) must not exceed the $35,000 lifetime limit (both contributions and earnings) for special rollovers for that beneficiary, and (5) are subject to the annual contribution limit for Roth IRAs.
California automatically conforms to IRC provisions relating to Roth IRAs. However, it has not conformed to SECURE 2.0’s tax-free rollovers. Consequently, a rollover earnings from a 529 plan to a Roth IRA would be included in the taxpayer’s gross income for state tax purposes, subject to state income tax, and a 2.5 percent distribution penalty.
Proposed Law:
This bill, for taxable years 2025 through 2029, would exclude from gross income a special rollover distribution from a QTP, including a ScholarShare account, to a Roth IRA.
Related Legislation:
- SB 529 (Choi) would authorize a personal income tax deduction against gross income equal to the contribution made to a California qualified tuition program, as specified. The bill failed passage in the Senate Committee on Revenue and Taxation.
- AB 1589 (Connolly, 2023) and AB 1026 (Ta, 2023) were both similar to this bill and died in the Assembly Revenue and Taxation Committee.
- SB 1374 (Borgeas, 2022), also substantially similar to this bill, was vetoed by Governor Newsom.
Staff Comments: FTB’s estimated revenue loss is based on a proration of the Joint Committee on Taxation’s (JCT) similar estimate at the federal level. JCT estimated the national impact of the exclusion to be $166 billion in federal fiscal year 2024.
-- END --
SENATE COMMITTEE ON REVENUE AND TAXATION
Senator Jerry McNerney, Chair
2025 - 2026 Regular
Bill No: | SB 657 | Hearing Date: | 5/14/25 |
Author: | Niello | Tax Levy: | Yes |
Version: | 4/29/25 Amended | Fiscal: | Yes |
Consultant: | Summers | ||
Personal Income Tax Law: deferred compensation: exclusions: long-term qualified tuition program
Excludes from gross income a special rollover distribution, made after January 1, 2025, and before January 1, 2030, from a Qualified Tuition Program, including a ScholarShare account, to a Roth Individual Retirement Account.
Background
Conformity. State law does not automatically conform to changes in federal tax law, except for specific retirement provisions. Instead, the Legislature must affirmatively conform to federal changes, which it can do in two different ways. First, the Legislature can pass an individual tax bill that conforms to a specific federal provision, such as the Regulated Investment Company Modernization Act (AB 1423, Perea, 2011). Second, the Legislature can pass one omnibus bill to ensure that state law conforms to federal law as of a specified date. Currently, state law generally conforms to federal tax law as of January 1, 2015 (AB 154, Ting, 2015).
Tax expenditures. California law allows various income tax credits, deductions, exemptions, and exclusions. The Legislature enacts such tax incentives to compensate taxpayers for incurring certain expenses, such as child adoption, or to influence certain behavior, such as charitable giving. The Legislature uses tax incentives to encourage taxpayers to do something they would otherwise not do, but for the tax credit. The Department of Finance is required annually to publish a list of tax expenditures, which currently total around $91.5 billion.
Income. Existing federal and state laws provide that gross income includes all income from any source, including compensation for services, business income, gains from property, interest, dividends, rents, and royalties, unless specifically excluded. Existing federal and state laws exclude certain types of income from gross income, such as specified amounts received as a gift or inheritance, certain compensation for injuries and sickness, qualified scholarships, educational assistance programs, foster care payments, and interest received on certain state or federal obligations, among other things.
California conformity to IRC 529 generally. California conforms to IRC 529 through standalone conformity (AB 2797, Committee on Budget, 1998), which has been modified and updated over the years. California modifies the additional 10% tax on excess distributions to instead be an additional tax of 2.5% for state purposes. Similar to federal law, state law provides that contributions made to a qualified tuition program (QTP), including the ScholarShare program, are not deductible.
QTP - 529 college saving plans. A QTP, commonly called a 529 plan, is a tax-advantaged savings plan for future educational expenses. The name originates from Section 529 of the Internal Revenue Code, which authorizes specific tax advantages for QTPs. Two types of 529 plans are available: college savings plans and prepaid plans. A state, state agency, or instrumentality of a state can establish and maintain either a college savings plan or a prepaid plan. Additionally, eligible educational institutions can establish and maintain a prepayment plan, but not a savings plan. QTP contributions on behalf of any beneficiary cannot be more than the amount necessary to provide for the beneficiary's qualified higher education expenses. The contributions to the QTP are made using after-tax dollars.
529 college savings plans. 529 college savings plans allow contributors to invest in various financial instruments, which can earn interest, dividends, and capital gains based on the performance of these investments. When making a distribution from 529 college savings plans for qualified education expenses or other qualified purposes pursuant to IRC 529, the earnings are not taxed, nor are the principal contributions, as it is simply a return of the original after-tax contributions. If distributions are made for non-qualified purposes, the earnings portion is taxed as income and subject to a 10% federal penalty and a 2.5% state penalty.
529 prepaid tuition plan. On the other hand, a 529 prepaid tuition plan locks in current tuition rates, thus offering a hedge against tuition inflation. The purchase price paid per tuition unit becomes the basis for the 529 prepaid tuition investment contract. When the 529 prepaid tuition plan makes a distribution, the prepaid units are assigned a value at the current tuition rate or the rate spelled out in the investment contract. The difference between the basis and the current assigned value is the plan’s “earnings.” These earnings are not subject to tax if made for qualified education expenses, qualified purposes pursuant to IRC 529, or were the result of a refund for a scholarship, Veterans Affairs benefit, or service-academy value. However, a distribution for any other purpose will result in a 10% federal penalty and a 2.5% state penalty on earnings. The return of basis is not subject to tax because it was paid with after-tax dollars.
State-administered 529 college savings plan. The Golden State ScholarShare Trust Program is a 529 savings plan administered by the State Treasurer's Office that offers California families a tax-advantaged college tuition savings plan to invest and save for college. ScholarShare is the state’s only QTP. However, California universities and colleges may participate in institutional plans or accept QTP from other states.
Qualified higher education expenses. Originally, QTPs were only authorized to pay for a beneficiary's qualified higher education expenses at an eligible institution of higher education. Qualified higher education expenses generally include expenses required for the enrollment or attendance of the designated beneficiary at any college, university, vocational school, or other postsecondary educational institution eligible to participate in a student aid program administered by the Department of Education. However, recent changes have expanded the scope of these expenses to include:
- Tuition expenses in connection with a beneficiary's enrollment or attendance at an elementary or secondary (kindergarten through grade 12) public, private, or religious school up to $10,000 per year from all of the beneficiary's QTPs. (Federal only - California does not currently conform.)
- Expenses for fees, books, supplies, and equipment required for participation in an apprenticeship program registered and certified with the Secretary of Labor. (Federal and state - AB 340 Ward, 2021.)
- Qualified education loan repayments on a designated beneficiary's or their sibling's student loan, limited to $10,000 in an individual's lifetime. (Federal and state - AB 340 Ward, 2021.)
- Allows families to roll over funds from a 529 education savings account to an ABLE account for the same beneficiary or a member of the beneficiary's family. (Federal and state - AB 91 Burke, 2019).
QTP special rollover to a Roth IRA. Another recent change to IRC 529 was made by the federal Setting Every Community Up for Retirement Enhancement Act of 2022 (SECURE 2.0), which permits the beneficiary of a QTP a special rollover distribution to their Roth Individual Retirement Account (IRA). For the rollover earnings to be excluded from gross income, the rollover amount must:
- Be paid through a direct trustee-to-trustee transfer and
- Be distributed from a QTP account that has been open for at least 15 years as of the date of the distribution.
- Not exceed the amount contributed to the QTP (and attributable earnings) before the 5-year period ending on the date of the distribution.
- Not exceed the $35,000 lifetime limit for special rollovers for that beneficiary. The limit pertains to both contributions and earnings.
- Subject to the annual contribution limit for Roth IRAs.
However, if only a portion of the QTP account value is rolled over, a pro-rata calculation based on the earnings ratio of the QTP is utilized. For example, if a college student has a $40,000 balance in their QTP, of which $30,000 is from contributions and $10,000 is earnings, then they have an earnings ratio of 25%. If the student chooses to rollover the max amount of $35,000, then the earnings ratio dictates that $26,250 of that amount is attributable to contributions and $8,750 of that amount is attributable to earnings. Because the $26,250 in contributions were made with after-tax dollars, there is no income tax imposed on this at the federal level or state level. With regard to the $8,750 of earnings, this amount would be excluded from gross income on a federal level, but included for state purposes and subject to the 2.5% state penalty. Additionally, the $5,000 remaining in the QTP is now comprised of $3,750 in contributions and $1,250 in earnings.
The formula applies to both college savings plans and prepaid tuition plans. However, the terms of these pre-paid tuition plans may vary by institution and may modify this calculation.
California conformity to QTP special rollover to a Roth IRA. California automatically conforms to IRC 408A, relating to Roth IRAs. However, it has not conformed to SECURE 2.0’s tax-free rollovers. As a result, a rollover earnings from a 529 plan to a Roth IRA would be included in the taxpayer’s gross income for state tax purposes, subject to state income tax, and a 2.5% distribution penalty.
The author seeks to conform to the federal law, which would bring tax relief and ease of return preparation for taxpayers who transfer funds from a QTP to a Roth IRA.
Proposed Law
Senate Bill 657 excludes from gross income a special rollover distribution from a QTP, including a ScholarShare account, to a Roth IRA made during taxable years after January 1, 2025, and before January 1, 2030. The bill makes legislative findings and declarations supporting its purposes, defines several terms, and complies with Section 41 of the Revenue and Taxation Code.
State Revenue Impact
According to the Franchise Tax Board (FTB), SB 657 will result in a revenue loss of $12.0 million in fiscal year (FY) 2025-26, $8.5 million in FY 2026-27, and $10.0 million in FY 2027-28.
Comments
- Purpose of the bill. According to the author, “SB 657 conforms state law to federal law which allows taxpayers to benefit from the recently approved provisions in the SECURE Act of 2022 pertaining to the rollover of funds from qualified tuition plans (QTPs or 529 accounts) to Roth IRAs. To date, 32 other states have conformed to this federal law. Families and potential account holders have long expressed concerns about saving with a 529 account due to the possibility of having to take a non-qualified withdrawal and face taxation and/or penalties should a beneficiary decide not to pursue a postsecondary education or for simply having unused funds. This concern has led to hesitation, delays, or declining to fund 529 savings accounts to the necessary levels needed to adequately save for the rising costs of education. By conforming state law with federal law, this proposal would mitigate these concerns by providing individuals and families with additional flexibility and the option to minimize taxation and penalties for non-qualified withdrawals by rolling over remaining 529 account funds into a Roth-IRA, resulting in higher confidence in long-term accessibility to funds, and therefore the opening of more 529 accounts, and increased contributions and savings to new and existing 529 accounts. Further, this proposed change would allow individuals and families to start investing towards their children’s retirement.”
- Equity. SB 657 primarily benefits families with sufficient disposable income to contribute to education savings plans. According to a 2022 survey on 529 plan users, 26% earned less than $74,999 a year; 49% earned between $75,000 and $149,999; and roughly 25% made over $149,999.[1] This survey also found that 66% of households earning less than $74,999 were not saving for college at all, which is disproportionately high compared to 19% for households with incomes from $75,000 to $149,999 and 7% for households with incomes over $150,000. Families with limited financial resources, who cannot save meaningfully in 529 plans, will not benefit from the new exclusion. In this way, SB 657 may inadvertently widen existing wealth gaps by reinforcing advantages for higher-income households. Although the bill aligns with federal tax policy and reduces compliance burdens, it does not address the underlying disparities in access to savings vehicles. Policymakers may wish to consider complementary measures to support low- and moderate-income families who struggle to afford higher education.
- “Windfall” or “but for” tax benefit? Tax expenditures produce two different outcomes. The first outcome is a “windfall,” where the tax expenditure rewards behavior that would have occurred without the tax benefit. The second outcome is a “but for” tax benefit, where a particular activity would not have occurred without the incentive created by the tax expenditure. Under current law, such rollovers are subject to California tax. Allowing an exclusion may encourage new rollovers to take place, increasing retirement savings. However, some rollovers may have occurred regardless of whether California conformed to the federal exclusion for these distributions. Therefore, this exclusion may serve as a “but for” tax incentive for some taxpayers and a being a “windfall” for others.
- Revenue loss. Existing tax law provides various credits, deductions, exclusions, and exemptions for certain taxpayers. By excluding rollover distributions from QTPs to Roth IRAs from personal income, SB 657 will result in the State General Fund receiving less revenue. As a result, the state will have to reduce spending or increase taxes to account for the loss.
- Who benefits? California’s progressive income tax system applies higher marginal rates as annual taxable income grows above certain thresholds. As a result, enacting a gross income exclusion benefits higher income earners more than others; a taxpayer whose income from other sources puts them in the 12.3% bracket has a higher dollar benefit from SB 657 exclusions than a taxpayer in the 4% bracket.
- Related legislation. AB 629 (Wallis, 2023) and AB 2524 (Ward, 2024) were identical to this bill. Both AB 629 and AB 2524 were approved by the Assembly Revenue & Taxation Committee but held on the Assembly Appropriations Committee suspense file.
The Committee will also consider at its 5/14 hearing SB 529 (Choi, 2025), which authorizes a personal income tax deduction against gross income equal to the contribution made to a Qualified Tuition Program, including a ScholarShare account, not to exceed $5,000 or $10,000, as provided.
- General conformity. SB 711 (McNerney, 2025) updates the conformity date to the Internal Revenue Code set by the Revenue and Taxation Code from January 1, 2015, to January 1, 2025. The Senate Revenue & Taxation Committee staff reviewed 1,000 plus substantive changes to the IRC since 2015 and have recommended a tentative decision for each change. SB 711 does not conform to the changes made by SECURE 2.0 to IRC 529. The measure is currently pending in the Senate Appropriations Committee.
- Section 41. Section 41 of the Revenue and Taxation Code requires any bill enacting a new tax expenditure to contain, among other things, specific goals, purposes, and objectives that the tax expenditure will achieve and detailed performance indicators, along with data collection and reporting requirements (SB 1335, Leno, 2014). A bill that would authorize a new gross income exclusion is exempt from the requirement that the bill contain detailed performance indicators and data collection reporting if the Legislature determines there is no available data to collect and report (AB 3289, Committee on Revenue and Taxation, 2024). To satisfy these requirements, SB 657 finds and declares the specific goal that the exclusion will achieve is to conform to federal law to bring tax relief and ease return preparation for taxpayers, and that there is no available data to collect or report with respect to the exclusions.
Support and Opposition
(5/9/25)
Support: California State Treasurer (Sponsor)
Fidelity Investments
Financial Planning Association
Financial Planning Association of California
Securities Industry and Financial Markets Association
10 Individuals
Opposition: California Tax Reform Association
-- END --
Curley, P. (2022, June 10). Target market analysis: Income of 529 users, non-529 college savers & non-savers (2022). 529 Conference. https://www.529conference.com/target-market-analysis-income-of-529-users-non-529-college-savers-non-savers-2022/ ↑
Discussed in Hearing
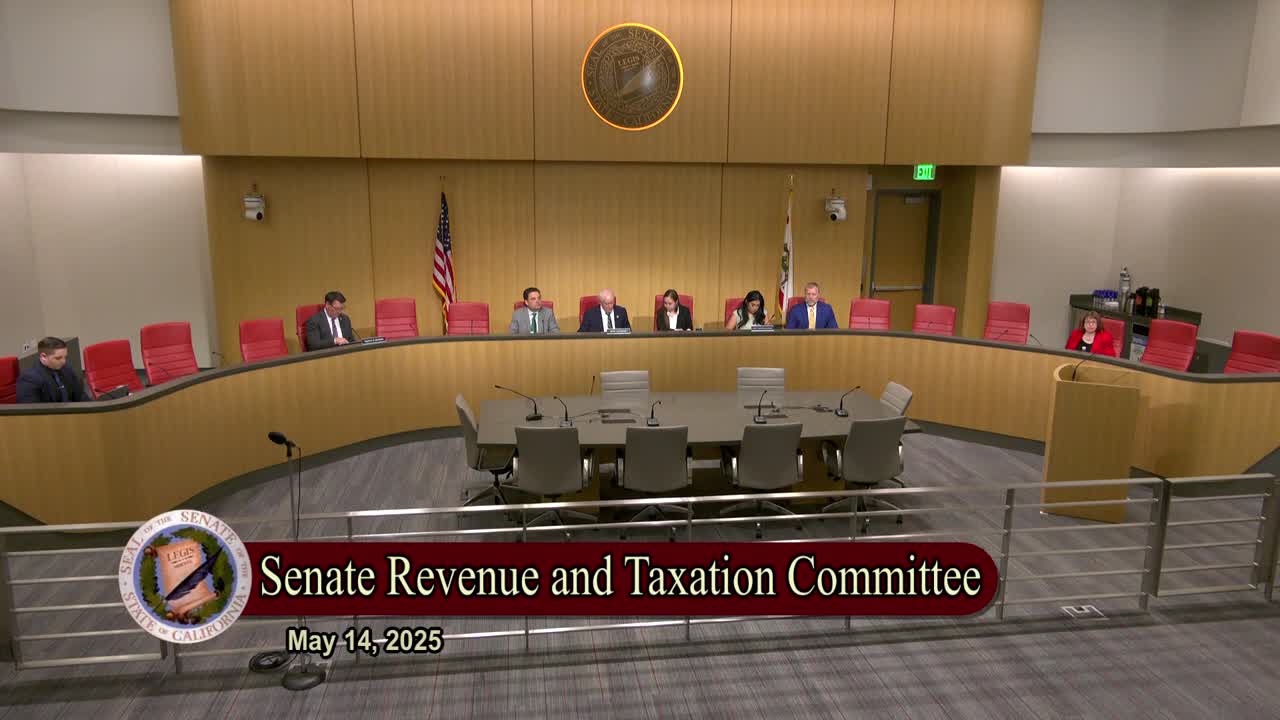 14MIN
Senate Standing Committee on Revenue and Taxation
Bill Author