AB 1249: Property taxation: exemptions: veterans’ organizations.
- Session Year: 2017-2018
- House: Assembly
- Latest Version Date: 2017-09-08
Existing property tax law establishes a veterans organization exemption under which property is exempt from taxation if, among other things, that property is used exclusively for charitable purposes and is owned by a veterans organization.
This bill would provide that the veterans organization exemption shall not be denied to a property on the basis that the property is used for fraternal, lodge, or social club purposes, and would make specific findings and declarations in that regard. The bill would also provide that the exemption shall not apply to any portion of a property that consists of a bar where alcoholic beverages are served.
Existing law requires the state to reimburse local agencies annually for certain property tax revenues lost as a result of any exemption or classification of property for purposes of ad valorem property taxation.
This bill would provide that, notwithstanding those provisions, no appropriation is made and the state shall not reimburse local agencies for property tax revenues lost by them pursuant to the bill.
This bill would take effect immediately as a tax levy.
Existing property tax law establishes a veterans organization exemption under which property is exempt from taxation if, among other things, that property is used exclusively for charitable purposes and is owned by a veterans organization.
This bill would provide that the veterans organization exemption shall not be denied to a property on the basis that the property is used for fraternal, lodge, or social club purposes, and would make specific findings and declarations in that regard. The bill would also provide that the exemption shall not apply to any portion of a property that consists of a bar where alcoholic beverages are served.
Existing law requires the state to reimburse local agencies annually for certain property tax revenues lost as a result of any exemption or classification of property for purposes of ad valorem property taxation.
This bill would provide that, notwithstanding those provisions, no appropriation is made and the state shall not reimburse local agencies for property tax revenues lost by them pursuant to the bill.
This bill would take effect immediately as a tax levy.
The Legislature finds and declares all of the following:
(a)(1)Since 1899 congressionally chartered veteran service organizations have provided a valuable service to our nations returning service members. These organizations help preserve the memories and incidents of the great hostilities fought by our nation, and preserve and strengthen comradeship among members.
(2)These veteran service organizations also own and manage various properties including lodges, posts, and fraternal halls. These properties act as a safe haven where veterans of all ages and their families can gather together to find camaraderie and fellowship, share stories, and seek support from people who understand their unique experiences. This aids in the healing process for these returning veterans, and ensures their health and happiness.
(b)As a result of congressional chartering of these veteran service organizations, the United States Internal Revenue Service created a special tax exemption for veterans organizations under Section 501(c)(19) of the Internal Revenue Code.
(c)Section 501(c)(19) of the Internal Revenue Code and related federal regulations provide for the exemption for posts or organizations of war veterans, or an auxiliary unit or society of, or a trust or foundation for, any such post or organization that, among other attributes, carries on programs to perpetuate the memory of deceased veterans and members of the Armed Forces and to comfort their survivors, conducts programs for religious, charitable, scientific, literary, or educational purposes, sponsors or participates in activities of a patriotic nature, and provides social and recreational activities for their members.
(d)Section 215.1 of the Revenue and Taxation Code stipulates that all buildings, and so much of the real property on which the buildings are situated as may be required for the convenient use and occupation of the buildings, used exclusively for charitable purposes, owned by a veterans organization that has been chartered by the Congress of the United States, organized and operated for charitable purposes, when the same are used solely and exclusively for the purpose of the organization, if not conducted for profit and no part of the net earnings of which inures to the benefit of any private individual or member thereof, are exempt from taxation.
(e)The Chief Counsel of the State Board of Equalization concluded, based on a 1979 appellate court decision, that only parts of American Legion halls are exempt from property taxation and that other parts, such as billiard rooms, card rooms, and similar areas, are not exempt.
(f)In a 1994 memorandum, the State Board of Equalizations legal division further concluded that the areas normally considered eligible for exemptions are the office areas used to counsel veterans and the area used to store veterans records, but that the meeting hall and bar found in most of the facilities are not considered used for charitable purposes.
(g)Tax-exempt status is intended to provide economic incentive and support to veteran service organizations to provide for the social welfare of the community of current and former military personnel.
(h)The State Board of Equalizations constriction of the tax exemption has resulted in an onerous tax burden on California veteran service organizations posts or halls, hinders the posts ability to provide facilities for veterans, and threatens the economic viability of many local organizations.
(i)The charitable activities of a veteran service organizations post or hall are much more than the counseling of veterans. The requirements listed for qualification for the federal tax exemption clearly dictate a need for more than just an office.
(j)Programs to perpetuate the memory of deceased veterans and members of the Armed Forces and to comfort their survivors require the use of facilities for funerals and receptions.
(k)Programs for religious, charitable, scientific, literary, or educational purposes require space for more than 50 attendees.
(l)Activities of a patriotic nature need facilities to accommodate hundreds of people.
(m)Social and recreational activities for members require precisely those areas considered not used for charitable purposes by the State Board of Equalization.
(n)The State Board of Equalizations interpretation of the Revenue and Taxation Code reflects a lack of understanding of the purpose and programs of the veterans service organizations posts or halls and is detrimental to the good works performed in support of our veteran community.
SEC. 2.Section 215.1 of the Revenue and Taxation Code is amended to read:215.1.(a)All buildings, and so much of the real property on which the buildings are situated as may be required for the convenient use and occupation of the buildings, used exclusively for charitable purposes, owned by a veterans organization that has been chartered by the Congress of the United States, organized and operated for charitable purposes, when the same are used solely and exclusively for the purpose of the organization, if not conducted for profit and no part of the net earnings of which inures to the benefit of any private individual or member thereof, shall be exempt from taxation.
(b)The exemption provided for in this section shall apply to the property of all organizations meeting the requirements of this section, subdivision (b) of Section 4 of Article XIII of the California Constitution, and paragraphs (1) to (4), inclusive, (6), and (7) of subdivision (a) of Section 214.
(c)(1)The exemption specified by subdivision (a) shall not be denied to a property on the basis that the property is used for fraternal, lodge, or social club purposes.
(2)With regard to this subdivision, the Legislature finds and declares all of the following:
(A)The exempt activities of a veterans organization as described in subdivision (a) qualitatively differ from the exempt activities of other nonprofit entities that use property for fraternal, lodge, or social club purposes in that the exempt purpose of the veterans organization is to conduct programs to perpetuate the memory of deceased veterans and members of the Armed Forces and to comfort their survivors, to conduct programs for religious, charitable, scientific, literary, or educational purposes, to sponsor or participate in activities of a patriotic nature, and to provide social and recreational activities for their members.
(B)In light of this distinction, the use of real property by a veterans organization as described in subdivision (a) for fraternal, lodge, or social club purposes is central to that organizations exempt purposes and activities.
(C)In light of the factors set forth in subparagraphs (A) and (B), the use of real property by a veterans organization as described in subdivision (a) for fraternal, lodge, or social club purposes constitutes the exclusive use of that property for a charitable purpose within the meaning of subdivision (b) of Section 4 of Article XIII of the California Constitution.
(d)The exemption provided for in this section shall not apply to any portion of a property that consists of a bar where alcoholic beverages are served. The portion of the property ineligible for the veterans organization exemption shall be that area used primarily to prepare and serve alcoholic beverages.
(e)An organization that files a claim for the exemption provided for in this section shall file with the assessor a valid organizational clearance certificate issued pursuant to Section 254.6.
(f)This exemption shall be known as the veterans organization exemption.
SEC. 3.Notwithstanding Section 2229 of the Revenue and Taxation Code, no appropriation is made by this act and the state shall not reimburse any local agency for any property tax revenues lost by it pursuant to this act.
SEC. 4.This act provides for a tax levy within the meaning of Article IV of the California Constitution and shall go into immediate effect.
The Legislature finds and declares all of the following:
(a)(1)Since 1899 congressionally chartered veteran service organizations have provided a valuable service to our nations returning service members. These organizations help preserve the memories and incidents of the great hostilities fought by our nation, and preserve and strengthen comradeship among members.
(2)These veteran service organizations also own and manage various properties including lodges, posts, and fraternal halls. These properties act as a safe haven where veterans of all ages and their families can gather together to find camaraderie and fellowship, share stories, and seek support from people who understand their unique experiences. This aids in the healing process for these returning veterans, and ensures their health and happiness.
(b)As a result of congressional chartering of these veteran service organizations, the United States Internal Revenue Service created a special tax exemption for veterans organizations under Section 501(c)(19) of the Internal Revenue Code.
(c)Section 501(c)(19) of the Internal Revenue Code and related federal regulations provide for the exemption for posts or organizations of war veterans, or an auxiliary unit or society of, or a trust or foundation for, any such post or organization that, among other attributes, carries on programs to perpetuate the memory of deceased veterans and members of the Armed Forces and to comfort their survivors, conducts programs for religious, charitable, scientific, literary, or educational purposes, sponsors or participates in activities of a patriotic nature, and provides social and recreational activities for their members.
(d)Section 215.1 of the Revenue and Taxation Code stipulates that all buildings, and so much of the real property on which the buildings are situated as may be required for the convenient use and occupation of the buildings, used exclusively for charitable purposes, owned by a veterans organization that has been chartered by the Congress of the United States, organized and operated for charitable purposes, when the same are used solely and exclusively for the purpose of the organization, if not conducted for profit and no part of the net earnings of which inures to the benefit of any private individual or member thereof, are exempt from taxation.
(e)The Chief Counsel of the State Board of Equalization concluded, based on a 1979 appellate court decision, that only parts of American Legion halls are exempt from property taxation and that other parts, such as billiard rooms, card rooms, and similar areas, are not exempt.
(f)In a 1994 memorandum, the State Board of Equalizations legal division further concluded that the areas normally considered eligible for exemptions are the office areas used to counsel veterans and the area used to store veterans records, but that the meeting hall and bar found in most of the facilities are not considered used for charitable purposes.
(g)Tax-exempt status is intended to provide economic incentive and support to veteran service organizations to provide for the social welfare of the community of current and former military personnel.
(h)The State Board of Equalizations constriction of the tax exemption has resulted in an onerous tax burden on California veteran service organizations posts or halls, hinders the posts ability to provide facilities for veterans, and threatens the economic viability of many local organizations.
(i)The charitable activities of a veteran service organizations post or hall are much more than the counseling of veterans. The requirements listed for qualification for the federal tax exemption clearly dictate a need for more than just an office.
(j)Programs to perpetuate the memory of deceased veterans and members of the Armed Forces and to comfort their survivors require the use of facilities for funerals and receptions.
(k)Programs for religious, charitable, scientific, literary, or educational purposes require space for more than 50 attendees.
(l)Activities of a patriotic nature need facilities to accommodate hundreds of people.
(m)Social and recreational activities for members require precisely those areas considered not used for charitable purposes by the State Board of Equalization.
(n)The State Board of Equalizations interpretation of the Revenue and Taxation Code reflects a lack of understanding of the purpose and programs of the veterans service organizations posts or halls and is detrimental to the good works performed in support of our veteran community.
SEC. 2.Section 215.1 of the Revenue and Taxation Code is amended to read:215.1.(a)All buildings, and so much of the real property on which the buildings are situated as may be required for the convenient use and occupation of the buildings, used exclusively for charitable purposes, owned by a veterans organization which that has been chartered by the Congress of the United States, organized and operated for charitable purposes, when the same are used solely and exclusively for the purpose of the organization, if not conducted for profit and no part of the net earnings of which inures to the benefit of any private individual or member thereof, shall be exempt from taxation.
(b)The exemption provided for in this section shall apply to the property of all organizations meeting the requirements of this section and section, subdivision (b) of Section 4 of Article XIII of the California Constitution Constitution, and paragraphs (1) to (7), (4), inclusive, (6), and (7) of subdivision (a) of Section 214.
(c)(1)The exemption specified by subdivision (a) shall not be denied to a property on the basis that the property is used for fraternal, lodge, or social club purposes.
(2)With regard to this subdivision, the Legislature finds and declares all of the following:
(A)The exempt activities of a veterans organization as described in subdivision (a) qualitatively differ from the exempt activities of other nonprofit entities that use property for fraternal, lodge, or social club purposes in that the exempt purpose of the veterans organization is to conduct programs to perpetuate the memory of deceased veterans and members of the Armed Forces and to comfort their survivors, to conduct programs for religious, charitable, scientific, literary, or educational purposes, to sponsor or participate in activities of a patriotic nature, and to provide social and recreational activities for their members.
(B)In light of this distinction, the use of real property by a veterans organization as described in subdivision (a) for fraternal, lodge, or social club purposes is central to that organizations exempt purposes and activities.
(C)In light of the factors set forth in subparagraphs (A) and (B), the use of real property by a veterans organization as described in subdivision (a) for fraternal, lodge, or social club purposes constitutes the exclusive use of that property for a charitable purpose within the meaning of subdivision (b) of Section 4 of Article XIII of the California Constitution.
(d)The exemption provided for in this section shall not apply to any portion of a property that consists of a bar where alcoholic beverages are served. The portion of the property ineligible for the veterans organization exemption shall be that area used primarily to prepare and serve alcoholic beverages.
(c)(e)An organization that files a claim for the exemption provided for in this section shall file with the assessor a valid organizational clearance certificate issued pursuant to Section 254.6.
(d)(f)This exemption shall be known as the veterans organization exemption.
SEC. 3.Notwithstanding Section 2229 of the Revenue and Taxation Code, no appropriation is made by this act and the state shall not reimburse any local agency for any property tax revenues lost by it pursuant to this act.
SEC. 4.This act provides for a tax levy within the meaning of Article IV of the California Constitution and shall go into immediate effect.
REVISIONS: HeadingLine 2.|
Date
|
Status
|
|---|---|
| Jan 12, 2018 | Stricken from file. |
| Jan 3, 2018 | Consideration of Governor's veto pending. |
| Oct 15, 2017 | Vetoed by Governor. |
| Sep 13, 2017 | Enrolled and presented to the Governor at 4 p.m. |
| Sep 7, 2017 | In Assembly. Ordered to Engrossing and Enrolling. |
| Sep 7, 2017 | Read third time. Passed. Ordered to the Assembly. |
| Sep 5, 2017 | Read second time. Ordered to third reading. |
| Sep 1, 2017 | From committee: Do pass. (Ayes 7. Noes 0.) (September 1). |
| Jun 26, 2017 | In committee: Referred to suspense file. |
| Jun 14, 2017 | From committee: Do pass and re-refer to Com. on APPR. (Ayes 6. Noes 0.) (June 14). Re-referred to Com. on APPR. |
| Jun 8, 2017 | Referred to Com. on GOV. & F. |
| May 30, 2017 | In Senate. Read first time. To Com. on RLS. for assignment. |
| May 30, 2017 | Read third time. Passed. Ordered to the Senate. (Ayes 77. Noes 0. Page 1837.) |
| May 26, 2017 | Coauthors revised. |
| May 3, 2017 | In committee: Set, first hearing. Referred to APPR. suspense file. |
| Apr 26, 2017 | From committee: Do pass and re-refer to Com. on APPR. (Ayes 10. Noes 0.) (April 25). Re-referred to Com. on APPR. |
| Apr 18, 2017 | From committee: Do pass and re-refer to Com. on V.A. (Ayes 10. Noes 0.) (April 17). Re-referred to Com. on V.A. |
| Apr 3, 2017 | In committee: Set, first hearing. Hearing canceled at the request of author. |
| Mar 9, 2017 | Referred to Coms. on REV. & TAX. and V.A. |
| Feb 19, 2017 | From printer. May be heard in committee March 21. |
| Feb 17, 2017 | Read first time. To print. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Sep 7, 2017 | Assembly 3rd Reading AB1249 Gray et al. By Anderson | Senate Floor |
Passed |
|
| Sep 1, 2017 | Do pass | Senate Standing Committee on Appropriations |
Passed |
|
| Jun 26, 2017 | Placed on suspense file | Senate Standing Committee on Appropriations |
Passed |
|
| Jun 14, 2017 | Do pass, but first be re-referred to the Committee on [Appropriations] | Senate Standing Committee on Governance and Finance |
Passed |
|
| May 30, 2017 | AB 1249 GRAY Assembly Third Reading | Assembly Floor |
Passed |
|
| May 26, 2017 | Do pass. | Assembly Standing Committee on Appropriations |
Passed |
|
| Apr 25, 2017 | Do pass and be re-referred to the Committee on [Appropriations] | Assembly Standing Committee on Veterans Affairs |
Passed |
|
| Apr 17, 2017 | Do pass and be re-referred to the Committee on [Veterans Affairs] | Assembly Standing Committee on Revenue and Taxation |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| American G.I, Forum Of California | ** Support | Sep 3, 2017 |
| American Legion, Department Of California | ** Support | Apr 24, 2017 |
| AMVETS - Department of California | ** Support | Sep 3, 2017 |
| California Assessors' Association | ** Support | Sep 3, 2017 |
| California Association Of County Veterans' Service Officers | ** Support | Sep 3, 2017 |
| California Council of Chapters | ** Support | Sep 3, 2017 |
| California State Commanders Veterans Council | ** Support | Sep 3, 2017 |
| Military Officers Association of America | ** Support | Sep 3, 2017 |
| The American Legion - Department Of California | ** Support | Sep 3, 2017 |
| Unknown. | ** Against | Jun 8, 2017 |
| Vietnam Veterans of America - California State Council | ** Support | Sep 3, 2017 |
GOVERNOR'S VETO
GV Bill Id:AB 1249
Author:(Gray)
As Enrolled Ver:September 8, 2017
2/3 vote
Committee | Votes | Ayes | Noes |
Revenue & Taxation | 10-0 | Ridley-Thomas, Travis Allen, Bocanegra, Dahle, Burke, Chen, Dababneh, Gipson, Mullin, Quirk | |
Veterans Affairs | 10-0 | Irwin, Brough, Daly, Frazier, Gloria, Mathis, Muratsuchi, Quirk-Silva, Salas, Voepel | |
Appropriations | 17-0 | Gonzalez Fletcher, Bigelow, Bloom, Bocanegra, Bonta, Brough, Calderon, McCarty, Quirk, Fong, Friedman, Gallagher, Eduardo Garcia, Gray, Muratsuchi, Obernolte, Reyes |
|
ASSEMBLY: | 77-0 | (May 30, 2017) | SENATE: | 39-0 | (September 7, 2017) |
SUMMARY: Extends the application of the "veterans' organization" property tax exemption to real property owned by certain veterans' organizations and used for fraternal, lodge, or social club purposes, as specified, excluding the bar area. Specifically, this bill:
- Provides that property, which is owned by a veteran's organization chartered by the United States (U.S.) Congress and otherwise eligible for the veterans' organization exemption, may not be denied the exemption on the basis that the property is used for fraternal, lodge, or social club purposes.
- Specifies that the veterans' organization exemption shall not apply to any portion of the property that consists of a bar where alcoholic beverages are served. The portion of the property ineligible for the exemption is the area used primarily to prepare and serve alcoholic beverages.
- Makes findings and declarations related to the activities of veterans' organizations.
- Provides that the state shall not reimburse any local agency for any property tax revenues lost by it pursuant to this bill.
- Takes effect immediately as a tax levy.
EXISTING FEDERAL LAW defines a post or an organization of past or present members of the Armed Forces of the U.S. as tax-exempt under Internal Revenue Code (IRC) Section 501(c)(19) if:
- The post or organization is organized in the U.S. or any of its possessions;
- At least 75% of the members are past or present members of the Armed Forces of the U.S. and substantially all of the other members of which are individuals who are cadets or are spouses, widows, widowers, ancestors, or lineal descendants of past or present members of the Armed Forces of the U.S. or of cadets; and,
- No part of the net earnings inure to the benefit of any private shareholder or individual.
EXISTING STATE LAW:
- Provides that all property is taxable, unless explicitly exempted by the California Constitution or federal law and limits the maximum amount of any ad valorem tax on real property at 1% of full cash value.
- Provides an exemption from taxation for property that is irrevocably dedicated to religious, hospital, scientific, or charitable purposes, if the property is used for the actual operation of the exempt activity and is owned by a nonprofit entity qualified as an exempt organization by the Internal Revenue Service, the Franchise Tax Board, or both (the so-called 'welfare exemption') [California Constitution Article XIII, Section 4; Revenue and Taxation Code (R&TC) Section 214]. The entity that owns the property is prohibited from having any earnings that contribute to the benefit of any private shareholder or individual. This welfare exemption has been expanded over the years to add certain specific types of property that do not otherwise qualify under the general exemption.
- Provides a property tax exemption for all buildings and real property exclusively used for charitable purposes by a veterans' organization that is: a) chartered by the U.S. Congress, and b) organized and operated for charitable purposes. In order to obtain the exemption, the organization must file a claim with the county assessor.
FISCAL EFFECT: According to the Assembly Appropriations Committee:
- Annual local revenue loss of approximately $625,000, resulting in General Fund costs of $310,000 as a result of the Proposition 98 guarantee.
- Moderate one-time administrative costs of around $100,000 to the Board of Equalization (BOE) to implement the provisions of this bill.
COMMENTS:
- The author has provided the following statement in support of this bill:
Assembly Bill 1249 would provide clarity to counties in order to maintain crucial property tax exemptions guaranteed to veterans' organizations, and ensure they have the resources they need to continue serving those who have sacrificed so much for our freedom. AB 1249 would guarantee that the welfare exemption would not be denied to veterans' halls and other property owned by veterans' organizations who host events for fraternal, lodge, or social purposes. It is important to note that the exemption would not apply to any portion of the property where alcohol is provided. For generations, veteran halls in cities and towns across our country have been an invaluable resource for active military and veterans. If AB 1249 becomes law, it would assist in the preservation of these important community centers for years to come.
- Supporters of this bill appreciate the effort to "ensure that as non-profit organizations, existing property tax exemptions for veteran halls are preserved."
- Committee Staff Comments:
- The veterans' organization exemption: Property owned by a veterans' organization chartered by the U.S. Congress is eligible for the welfare exemption, provided that the organization complies with all applicable requirements; is exempt from tax under federal and state law; and has a "veterans' organization exemption" certificate of compliance on file with the county assessor. The majority of veterans' organizations are ineligible for exemption because another provision of the law – R&TC Section 214(a)(5) – disqualifies property if it is used for fraternal, lodge, or social purposes. In practice, only small portions of property owned by veterans' organizations actually receive the property tax exemption. Buildings owned by the Veterans of Foreign Wars and the American Legion often have many uses, some of which are social in nature. As a result, the application of the veterans' organization exemption is inconsistent from county to county. Some counties assess the entire property; others do not assess the property at all; and still others exempt just the office and facilities that directly serve veterans, such as counseling rooms used for readjustment services.
According to the BOE analysis of this bill, R&TC Section 215.1, which provides for the veterans' organization exemption, was added by AB 184 (Powers), Chapter 151, Statutes of 1972. The BOE opposed AB 184 and, in a letter sent to Governor Reagan, explained, "While AB 184 implies that the activities of veterans' organizations are charitable, it does not directly so state…. This curious construction invites litigation. If a tax benefit is to be granted, it should be clear as to what that benefit is." The BOE noted several potential interpretations of the language in AB 184. First, AB 184 may be viewed as the creation of a new exemption that would be invalid without the support of a constitution amendment. Alternatively, AB 184 may be viewed as merely "permitting veterans' organizations to receive the welfare exemption if they meet the traditional concepts of charity and otherwise satisfy other welfare exemption requirements," in which case AB 184 is "an exercise in futility since it is highly doubtful that any organization could qualify." Finally, AB 184 may be viewed as "a vague attempt to expand the concept of charity so as to permit veterans' organizations to receive the benefit of the welfare exemption." This interpretation is also of "doubtful constitution validity." The Governor, however, signed AB 184 into law.
While many veterans' organizations applied for the new exemption, the BOE denied all the claims. Representatives of veterans' organizations subsequently protested the denials before the BOE on January 4, 1974. Ultimately, this exemption "was extended to a limited portion of the entire veterans' organization property, such as the counseling rooms used for readjustment services, post-traumatic stress disorders, and alcohol or drug assistance programs."
The BOE staff notes the veterans' organization exemption has had little practical effect since relatively few properties owned by veterans' organizations currently receive the exemption, and those that do are only receiving a partial exemption on a small part of their property. In fact, only about 50 organizations currently apply for the exemption and a number of these receive a partial exemption, generally on the office or counseling rooms used for readjustment services, post-traumatic stress disorders, and alcohol or drug assistance programs. Most of the properties consist of a club room, auditorium, restaurant, and/or bar, which are not eligible for the property tax exemption, except where the use is clearly incidental to a primary charitable purpose.
- What is the problem? According to the sponsors of the bill, the exemption is intended to subsidize veteran organizations. Membership at these organizations has dramatically declined over the years because the membership is primarily made up of World War II, Korea, and Vietnam veterans. Younger veterans are not joining these organizations; as a result, those organizations are collecting less in dues to pay for upkeep of the property. The American Legion, which had 3.3 million members nationally at its height in 1947, still has 14,000 active posts and 2 million members nationwide, but only about 30,000 are veterans under the age of 40[1]. If the underlying problem is a lack of interest from younger veterans, it is unclear to Committee staff if relieving veterans' organizations from property taxes would help preserve them as community centers.
- Slippery slope? While this bill provides tax relief to veterans' organizations, it sets a precedent for other groups to seek similar property tax exemptions. As stated in the BOE analysis of this bill, lodges and clubs owned by the Elks, Moose, Oddfellows, and Rotary, etc., are not exempt from taxation. The Committee may wish to consider whether the activities of U.S. Congress-chartered veterans' organizations significantly differ from community services performed by similarly situated non-profit organizations and whether the difference warrants a disparate tax treatment of properties owned by those organizations.
- Constitutional concerns: The language of the Constitution is clear that the qualifying property must be owned, operated and used by a nonprofit entity for exempt purposes and activities, and no part of the entity's net earnings may inure to the benefit of any private shareholder or individual. Property must be used exclusively for religious, hospital, or charitable purposes. In 1973, the Attorney General opined that R&TC Section 251.1 (which is proposed to be amended by this bill) was constitutional because it contained an additional eligibility requirement, namely a requirement to meet all of the provisions of R&TC Section 214(a)(1) to (7). In this connection, subparagraph (5) of Section 214(a) mandates that the property be not used for fraternal or lodge purposes or for social club purposes, except where that use is clearly incidental to a primary religious, hospital, scientific or charitable purpose. This bill proposes to delete this requirement, which puts in question the constitutionality of Section 251.1, as proposed to be amended.
Assembly Bill 1249 allows property owned by veterans' organizations to receive a full property tax exemption for fraternal, lodge, or social club purposes.
Last year, I signed SB 1458, which expanded eligibility for the disabled veteran's property tax exemption. In 2014, I signed SB 1113 which extended the statute of limitations for a veteran with a 100% service disability to claim a disabled veteran's property tax exemption refund from four to eight years. Earlier this year, I signed SB 3 to put a $4 billion bond before the voters that, if passed, would continue a long-standing statewide program that provides home loans to qualified veterans.
We have taken steps to expand eligibility for the property tax exemption in appropriate ways for our veterans. This bill, however, allows an already generous property tax benefit to be expanded on a larger scale. I am, therefore, returning this bill without my signature.
Analysis Prepared by: Carlos Anguiano / REV. & TAX. / (916) 319-2098 FN: 0002504
Mike Seely, A lonely veteran opened the doors to this American Legion post in order to save it, Los Angeles Times, Jan. 10, 2017. ↑
Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | AB |
THIRD READING
Bill No: AB 1249
:
SENATE GOVERNANCE & FIN. COMMITTEE: 6-0, 6/14/17
AYES: McGuire, Nguyen, Beall, Hertzberg, Lara, Moorlach
NO VOTE RECORDED: Hernandez
SENATE APPROPRIATIONS COMMITTEE: 7-0, 9/1/17
AYES: Lara, Bates, Beall, Bradford, Hill, Nielsen, Wiener
ASSEMBLY FLOOR: 77-0, 5/30/17 - See last page for vote
DIGEST:
This bill provides that assessors can’t deny the welfare exemption on property owned by veterans’ organizations used for fraternal, lodge, or social club purposes.
Existing law:
- Provides that all property is taxable unless explicitly exempted by the Constitution or federal law (Article XIII, Section 1 of the California Constitution), but allows the Legislature to exempt property used for religious, hospital, or charitable purposes, so long as it’s owned by nonprofit entities organized and operated for charitable purposes, none of whose income inures to the benefit of any private shareholder or individual (Article XIII, Section 4). This exemption is commonly known as the welfare exemption.
- Requires taxpayers and property to comply with all of the following to obtain the welfare exemption:
- The property is used for the actual operation of the exempt activity, and does not exceed an amount of property reasonably necessary to accomplish the exempt purpose,
- The property is not used to benefit the owner or any other person,
- The property is not used for fraternal, lodge, or social club purposes, except to the extent that the use is clearly incidental to the exempt purpose, and
- The property is irrevocably dedicated to charitable purposes, and will not inure to the benefit of a person upon sale or dissolution, except in specified circumstances.
- Allows property owned by a veterans’ organization chartered by the United States Congress to obtain the welfare exemption, so long as the organization complies with the requirements above, is tax-exempt under federal and state law, and has a “veterans’ organization exemption” certificate of compliance on file with the county assessor.
This bill:
- Provides that the welfare exemption shall not be denied to property owned by veterans’ organizations that is used for fraternal, lodge, or social club purposes, by stating that veterans’ organizations’ social uses of property qualitatively differs from the exempt activities of other organizations as specified, and deeming it as central to the organization’s exempt purpose.
- Denies the exemption to any part of a property where alcoholic beverages are served, and states that the part of the property that’s ineligible for the exemption is the area where alcoholic beverages are prepared and served.
- Makes legislative findings and declarations supporting its purposes.
Comments
The California Constitution allows the Legislature to enact the welfare exemption for specified property meeting three standards: first, the property must operate for charitable purposes. Second, a non-profit organization owns the property, and lastly, any net earnings don’t inure to the benefit of any private individual or shareholder. The Legislature subsequently enacted a section of law setting forth additional requirements for all charitable organizations, and another section of law only for veterans’ organizations. However, a conflict exists between the welfare exemption’s requirements prohibiting exempt property from being used for fraternal, lodge, or social club purposes, and the use of buildings owned by Veterans of Foreign Wars (VFW) and the American Legion which often have uses which are social in nature. As a result, the application of the veterans’ organization exemption varies across counties, where independent, elected assessors enforce property tax law. Some assessors don’t apply the exemption at all; others exempt just the office and facilities that directly serve veterans, while others simply don’t assess the property. SB 2 responds to veterans’ groups request for clarity that property owned by VFW and American Legion that serve veterans’ unique need should be eligible for the welfare exemption from property tax.
FISCAL EFFECT: Appropriation: Fiscal Com.: Local:
According to the Senate Appropriations Committee:
- This bill lowers local property tax revenue by roughly $625,000 annually. Reductions in local property tax revenues, in turn, increase General Fund Proposition 98 spending by up to roughly 50 percent (the exact amount depends on the specific amount of the annual Proposition 98 guarantee, which in turns depends upon a variety of economic, demographic and budgetary factors).
- The Board of Equalization (BOE) would incur annual costs of up to $150,000 (General Fund) for the first three years to administer the provisions of the bill. Specifically, BOE would incur costs primarily to issue organizational clearance certificates to veterans’ organizations applying for the exemption under the bill.
American G.I, Forum of California
The American Legion - Department of California
AMVETS – Department of California
California Assessors’ Association
California Association of County Veterans’ Service Officers
California Council of Chapters
California State Commanders Veterans Council
Military Officers Association of America
Vietnam Veterans of America – California State Council
None received
ARGUMENTS IN SUPPORT: According to the author, “Assembly Bill 1249 provides clarity to counties in order to maintain crucial property tax exemptions guaranteed to veterans’ organizations, and ensure they have the resources they need to continue serving those who have sacrificed so much for our freedom. AB 1249 would guarantee that the welfare exemption would not be denied to veterans’ halls and other property owned by veterans’ organizations who host events for fraternal, lodge, or social purposes. It is important to note that the exemption would not apply to any portion of the property where alcohol is provided. For generations, veteran halls in cities and towns across our country have been an invaluable resource for active military and veterans. If AB 1249 becomes law, it would assist in the preservation of these important community centers for years to come.”
ASSEMBLY FLOOR: 77-0, 5/30/17
AYES: Acosta, Aguiar-Curry, Travis Allen, Arambula, Baker, Berman, Bigelow, Bloom, Bocanegra, Bonta, Brough, Burke, Caballero, Calderon, Cervantes, Chávez, Chen, Chiu, Chu, Cooley, Cooper, Cunningham, Dababneh, Dahle, Daly, Flora, Fong, Frazier, Friedman, Gallagher, Cristina Garcia, Eduardo Garcia, Gipson, Gloria, Gomez, Gonzalez Fletcher, Gray, Grayson, Harper, Holden, Irwin, Jones-Sawyer, Kalra, Kiley, Lackey, Levine, Limón, Low, Maienschein, Mathis, Mayes, McCarty, Medina, Melendez, Mullin, Muratsuchi, Nazarian, Obernolte, O'Donnell, Patterson, Quirk, Quirk-Silva, Reyes, Ridley-Thomas, Rodriguez, Rubio, Salas, Santiago, Steinorth, Mark Stone, Thurmond, Ting, Voepel, Waldron, Weber, Wood, Rendon
NO VOTE RECORDED: Chau, Choi, Eggman
9/3/17 17:41:13
**** END ****
SENATE COMMITTEE ON
Senator Ricardo Lara, Chair
2017 - 2018 Regular Session
AB 1249 (Gray) - Property taxation: exemptions: veterans’ organizations
Version: | Policy Vote: |
Urgency: | Mandate: |
Hearing Date: | Consultant: |
This bill meets the criteria for referral to the Suspense File.
Bill Summary: AB 1249 would allow the veterans’ organization exemption to apply to real property owned by veterans’ organizations that is used for fraternal, lodge, or social club purposes, excluding the bar area.
Fiscal Impact:
- This measure would lower local property tax revenue by roughly $625,000 annually. Reductions in local property tax revenues, in turn, increase General Fund Proposition 98 spending by up to roughly 50 percent (the exact amount depends on the specific amount of the annual Proposition 98 guarantee, which in turns depends upon a variety of economic, demographic and budgetary factors).
- The Board of Equalization (BOE) would incur annual costs of up to $150,000 (General Fund) for the first three years to administer the provisions of the bill. Specifically, BOE would incur costs primarily to issue organizational clearance certificates to veterans’ organizations applying for the exemption under the bill.
Background: Current law provides a property tax exemption on real property owned by veterans’ organizations. However, in practice, only small portions of most property owned by veterans’ organizations actually receive the property tax exemption. The majority of veterans organizations’ property is ineligible for exemption because another provision of law disqualifies property if used for fraternal, lodge, or social purposes. The application of veterans’ organization exemptions is inconsistent from county to county. Some counties assess the entire property, others do not assess the property at all, and still others exempt just the office and facilities that directly serve veterans, such as counseling rooms used for readjustment services.
Proposed Law: This bill would provide that the welfare exemption shall not be denied to property owned by veterans’ organizations that is used for fraternal, lodge, or social club purposes. However, the exemption doesn’t apply to any portion of a property where alcoholic beverages, as defined, are sold.
Related Legislation: This bill is largely identical to SB 2 (Anderson, 2015) and SB 1152 (Anderson, 2014), both of which were held on the Assembly Revenue and Taxation Committee’s suspense file.
Staff Comments: BOE estimates that 250 properties around the State are owned by veteran’s organizations and would be impacted by the bill. Available data indicate that the total assessed value of veterans organizations’ affected property (excluding the bar area) amounts to $62.5 million. At the one-percent statewide property rate, the annual local property tax loss would be $625,000. The precise impact on the General Fund would depend on the specific factors which determine the annual Proposition 98 minimum funding guarantee.
-- END --
SENATE COMMITTEE ON GOVERNANCE AND FINANCE
Senator Mike McGuire, Chair
2017 - 2018 Regular
Bill No: | AB 1249 | Hearing Date: | 6/14/17 |
Author: | Gray | Tax Levy: | Yes |
Version: | 2/17/17 | Fiscal: | Yes |
Consultant: | Grinnell | ||
Property taxation: exemptions: veterans’ organizations
Provides that assessors can’t deny the welfare exemption on property owned by veterans’ organizations used for fraternal, lodge, or social club purposes.
Background
Section One of Article XIII of the California Constitution provides that all property is taxable unless explicitly exempted by the Constitution or federal law. However, the Constitution allows the Legislature to exempt property used for religious, hospital, or charitable purposes, so long as its owned by nonprofit entities organized and operated for charitable purposes, none of whose income inures to the benefit of any private shareholder or individual. The Legislature enacted this exemption in law, commonly known as the “welfare exemption.” To be eligible, the law requires both the owner and property to meet the standards in the Constitution, in addition to other requirements, such as:
- The property is used for the actual operation of the exempt activity, and does not exceed an amount of property reasonably necessary to accomplish the exempt purpose;
- The property is not used to benefit the owner or any other person;
- The property is not used for fraternal, lodge, or social club purposes, except to the extent that the use is clearly incidental to its charitable purpose; and
- The property is irrevocably dedicated to charitable purposes and will not inure to the benefit of a person upon sale or dissolution, except in specified circumstances.
Property owned by a veterans’ organization chartered by the United States Congress is eligible for the welfare exemption so long as the organization complies with the requirements above, is tax-exempt under federal and state law, and has a “veterans’ organization exemption” certificate of compliance on file with the county assessor. However, this exemption conflicts with the welfare exemption’s general statutory prohibition on exempting property used for fraternal, lodge, or social club purposes, because buildings owned by Veterans of Foreign Wars (VFW) and the American Legion often have many uses, some of which are social in nature. As a result, the application of the veterans’ organization exemption can vary across counties, where independent, elected assessors administer the property tax. Some assessors don’t apply the exemption at all and assess the building at full cash value; others exempt just the office and facilities that directly serve veterans, while others consider the entire building exempt. Veterans’ groups seek clarity that property owned by VFW and American Legion that serve veterans’ unique need should be eligible for the welfare exemption from property tax.
Proposed Law
Assembly Bill 1249 provides that the welfare exemption shall not be denied to property owned by veterans’ organizations that is used for fraternal, lodge, or social club purposes. However, the exemption doesn’t apply to any portion of a property where alcoholic beverages are sold, as defined. The measure also states legislative findings and declarations.
State Revenue Impact
According to the Board of Equalization, AB 1249 results in annual revenue losses of $625,000.
Comments
1. Purpose of the bill. According to the author, “Assembly Bill 1249 provides clarity to counties in order to maintain crucial property tax exemptions guaranteed to veterans’ organizations, and ensure they have the resources they need to continue serving those who have sacrificed so much for our freedom. AB 1249 would guarantee that the welfare exemption would not be denied to veterans’ halls and other property owned by veterans’ organizations who host events for fraternal, lodge, or social purposes. It is important to note that the exemption would not apply to any portion of the property where alcohol is provided. For generations, veteran halls in cities and towns across our country have been an invaluable resource for active military and veterans. If AB 1249 becomes law, it would assist in the preservation of these important community centers for years to come.”
2. Next best. The California Constitution prohibits the Legislature from enacting changes to the property tax that conflict with its provisions. AB 1249 stretches the constitutional welfare exemption to apply to veterans’ organizations by defining a veterans’ organization’s lodge, fraternal, and social uses as central to its constitutionally required charitable purpose. While the Legislature has some discretion to interpret constitutional provisions, statutory changes to the property tax are always a second best option. The most effective and direct way to clearly exclude property owned by veterans’ organizations is to amend the Constitution.
3. Precedent. While AB 1249 would help veterans’ organizations, the measure creates a precedent by applying the exemption more broadly to veterans’ organizations’ property than to other groups. Under the bill, a building owned and used by the Elks’ Club would be taxed differently than the same building owned and used for the same purposes by the American Legion. Given this difference, nonprofit social clubs and lodges that perform considerable community services may want similar treatment. The Committee may wish to consider the precedent AB 1249 sets.
4. Do it again. AB 1249 is largely identical to SB 2 (Anderson, 2015) and SB 1152 (Anderson, 2014), both of which were approved by this Committee. However, both measures were held on the Assembly Revenue and Taxation Committee’s suspense file.
Assembly Actions
Assembly Veterans Affairs Committee: 10-0
Assembly Revenue and Taxation Committee: 10-0
Assembly Appropriations Committee: 17-0
Assembly Floor: 77-0
Support and Opposition
(6/7/17)
Support: American G.I, Forum of California, The American Legion - Department of California; AMVETS – Department of California; California Assessors’ Association; California Association of County Veterans’ Service Officers; California Council of Chapters; California State Commanders Veterans Council; Military Officers Association of America; Vietnam Veterans of America – California State Council.
Opposition: Unknown.
-- END --
ASSEMBLY THIRD READING
ATR Bill Id:AB 1249
Author:(Gray)
As Introduced Ver:February 17, 2017
Majority vote. Tax levy
Committee | Votes | Ayes | Noes |
Revenue & Taxation | 10-0 | Ridley-Thomas, Travis Allen, Bocanegra, Dahle, Burke, Chen, Dababneh, Gipson, Mullin, Quirk | |
Veterans Affairs | 10-0 | Irwin, Brough, Daly, Frazier, Gloria, Mathis, Muratsuchi, Quirk-Silva, Salas, Voepel | |
Appropriations | 17-0 | Gonzalez Fletcher, Bigelow, Bloom, Bocanegra, Bonta, Brough, Calderon, McCarty, Quirk, Fong, Friedman, Gallagher, Eduardo Garcia, Gray, Muratsuchi, Obernolte, Reyes |
|
SUMMARY: Extends the application of the "veterans' organization" property tax exemption to real property owned by certain veterans' organizations and used for fraternal, lodge, or social club purposes, as specified, excluding the bar area. Specifically, this bill:
- Provides that property, which is owned by a veteran's organization chartered by the United States (U.S.) Congress and otherwise eligible for the veterans' organization exemption, may not be denied the exemption on the basis that the property is used for fraternal, lodge, or social club purposes.
- Specifies that the veterans' organization exemption shall not apply to any portion of the property that consists of a bar where alcoholic beverages are served. The portion of the property ineligible for the exemption is the area used primarily to prepare and serve alcoholic beverages.
- Makes findings and declarations related to the activities of veterans' organizations.
- Provides that the state shall not reimburse any local agency for any property tax revenues lost by it pursuant to this bill.
- Takes effect immediately as a tax levy.
EXISTING FEDERAL LAW defines a post or an organization of past or present members of the Armed Forces of the United States (U.S.) as tax-exempt under Internal Revenue Code (IRC) Section 501(c)(19) if:
- The post or organization is organized in the U.S. or any of its possessions;
- At least 75% of the members are past or present members of the Armed Forces of the U.S. and substantially all of the other members of which are individuals who are cadets or are spouses, widows, widowers, ancestors, or lineal descendants of past or present members of the Armed Forces of the U.S. or of cadets; and,
- No part of the net earnings inure to the benefit of any private shareholder or individual.
EXISTING STATE LAW:
- Provides that all property is taxable, unless explicitly exempted by the California Constitution or federal law and limits the maximum amount of any ad valorem tax on real property at 1% of full cash value.
- Provides an exemption from taxation for property that is irrevocably dedicated to religious, hospital, scientific, or charitable purposes, if the property is used for the actual operation of the exempt activity and is owned by a nonprofit entity qualified as an exempt organization by the Internal Revenue Service, the Franchise Tax Board, or both (the so-called 'welfare exemption') [California Constitution Article XIII, Section 4; Revenue and Taxation Code (R&TC) Section 214]. The entity that owns the property is prohibited from having any earnings that contribute to the benefit of any private shareholder or individual. This welfare exemption has been expanded over the years to add certain specific types of property that do not otherwise qualify under the general exemption.
- Provides a property tax exemption for all buildings and real property exclusively used for charitable purposes by a veterans' organization that is: a) chartered by the U.S. Congress, and b) organized and operated for charitable purposes. In order to obtain the exemption, the organization must file a claim with the county assessor.
FISCAL EFFECT: According to the Assembly Appropriations Committee:
- Annual local revenue loss of approximately $625,000, resulting in General Fund (GF) costs of $310,000 as a result of the Proposition 98 guarantee.
- Moderate one-time administrative costs of around $100,000 to the Board of Equalization (BOE) to implement the provisions of this bill.
COMMENTS:
- The author has provided the following statement in support of this bill:
Assembly Bill 1249 would provide clarity to counties in order to maintain crucial property tax exemptions guaranteed to veterans' organizations, and ensure they have the resources they need to continue serving those who have sacrificed so much for our freedom. AB 1249 would guarantee that the welfare exemption would not be denied to veterans' halls and other property owned by veterans' organizations who host events for fraternal, lodge, or social purposes. It is important to note that the exemption would not apply to any portion of the property where alcohol is provided. For generations, veteran halls in cities and towns across our country have been an invaluable resource for active military and veterans. If AB 1249 becomes law, it would assist in the preservation of these important community centers for years to come.
- Supporters of this bill appreciate the effort to "ensure that as non-profit organizations, existing property tax exemptions for veteran halls are preserved."
- Committee Staff Comments:
- The veterans' organization exemption: Property owned by a veterans' organization chartered by the U.S. Congress is eligible for the welfare exemption, provided that the organization complies with all applicable requirements; is exempt from tax under federal and state law; and has a "veterans' organization exemption" certificate of compliance on file with the county assessor. The majority of veterans' organizations are ineligible for exemption because another provision of the law – R&TC Section 214(a)(5) – disqualifies property if it is used for fraternal, lodge, or social purposes. In practice, only small portions of property owned by veterans' organizations actually receive the property tax exemption. Buildings owned by the Veterans of Foreign Wars and the American Legion often have many uses, some of which are social in nature. As a result, the application of the veterans' organization exemption is inconsistent from county to county. Some counties assess the entire property; others do not assess the property at all; and still others exempt just the office and facilities that directly serve veterans, such as counseling rooms used for readjustment services.
According to the BOE analysis of this bill, R&TC Section 215.1, which provides for the veterans' organization exemption, was added by AB 184 (Powers), Chapter 151, Statutes of 1972. The BOE opposed AB 184 and, in a letter sent to Governor Reagan, explained, "While AB 184 implies that the activities of veterans' organizations are charitable, it does not directly so state…. This curious construction invites litigation. If a tax benefit is to be granted, it should be clear as to what that benefit is." The BOE noted several potential interpretations of the language in AB 184. First, AB 184 may be viewed as the creation of a new exemption that would be invalid without the support of a constitution amendment. Alternatively, AB 184 may be viewed as merely "permitting veterans' organizations to receive the welfare exemption if they meet the traditional concepts of charity and otherwise satisfy other welfare exemption requirements," in which case AB 184 is "an exercise in futility since it is highly doubtful that any organization could qualify." Finally, AB 184 may be viewed as "a vague attempt to expand the concept of charity so as to permit veterans' organizations to receive the benefit of the welfare exemption." This interpretation is also of "doubtful constitution validity." The Governor, however, signed AB 184 into law.
While many veterans' organizations applied for the new exemption, the BOE denied all the claims. Representatives of veterans' organizations subsequently protested the denials before the BOE on January 4, 1974. Ultimately, this exemption "was extended to a limited portion of the entire veterans' organization property, such as the counseling rooms used for readjustment services, post-traumatic stress disorders, and alcohol or drug assistance programs."
The BOE staff notes the veterans' organization exemption has had little practical effect since relatively few properties owned by veterans' organizations currently receive the exemption, and those that do are only receiving a partial exemption on a small part of their property. In fact, only about 50 organizations currently apply for the exemption and a number of these receive a partial exemption, generally on the office or counseling rooms used for readjustment services, post-traumatic stress disorders, and alcohol or drug assistance programs. Most of the properties consist of a club room, auditorium, restaurant, and/or bar, which are not eligible for the property tax exemption, except where the use is clearly incidental to a primary charitable purpose.
- What is the problem? According to the sponsors of the bill, the exemption is intended to subsidize veteran organizations. Membership at these organizations has dramatically declined over the years because the membership is primarily made up of World War II, Korea, and Vietnam veterans. Younger veterans are not joining these organizations; as a result, those organizations are collecting less in dues to pay for upkeep of the property. The American Legion, which had 3.3 million members nationally at its height in 1947, still has 14,000 active posts and 2 million members nationwide, but only about 30,000 are veterans under the age of 40[1]. If the underlying problem is a lack of interest from younger veterans, it is unclear to Committee staff if relieving veterans' organizations from property taxes would help preserve them as community centers.
- Slippery slope? While this bill provides tax relief to veterans' organizations, it sets a precedent for other groups to seek similar property tax exemptions. As stated in the BOE analysis of this bill, lodges and clubs owned by the Elks, Moose, Oddfellows, and Rotary, etc., are not exempt from taxation. The Committee may wish to consider whether the activities of U.S. Congress-chartered veterans' organizations significantly differ from community services performed by similarly situated non-profit organizations and whether the difference warrants a disparate tax treatment of properties owned by those organizations.
- Constitutional concerns: The language of the Constitution is clear that the qualifying property must be owned, operated and used by a nonprofit entity for exempt purposes and activities, and no part of the entity's net earnings may inure to the benefit of any private shareholder or individual. Property must be used exclusively for religious, hospital, or charitable purposes. In 1973, the Attorney General opined that R&TC Section 251.1 (which is proposed to be amended by this bill) was constitutional because it contained an additional eligibility requirement, namely a requirement to meet all of the provisions of R&TC Section 214(a)(1) - (7). In this connection, subparagraph (5) of Section 214(a) mandates that the property be not used for fraternal or lodge purposes or for social club purposes, except where that use is clearly incidental to a primary religious, hospital, scientific or charitable purpose. This bill proposes to delete this requirement, which puts in question the constitutionality of Section 251.1, as proposed to be amended.
Analysis Prepared by: Carlos Anguiano / REV. & TAX. / (916) 319-2098 FN: 0000586
Mike Seely, A lonely veteran opened the doors to this American Legion post in order to save it, Los Angeles Times, Jan. 10, 2017. ↑
Date of Hearing: May 3, 2017
ASSEMBLY COMMITTEE ON APPROPRIATIONS
Lorena Gonzalez Fletcher, Chair
ABPCA Bill Id:AB 1249
Author:(Gray) – As Introduced Ver:February 17, 2017
Policy Committee: | Revenue and Taxation | Vote: | 10 - 0 |
Veterans Affairs | 10 - 0 | ||
|
|
Urgency: No State Mandated Local Program: No Reimbursable: No
SUMMARY:
This bill extends the application of the "veterans' organization" property tax exemption to real property owned by certain veterans' organizations and used for fraternal, lodge, or social club purposes, as specified, excluding the bar area.
FISCAL EFFECT:
- Annual local revenue loss of approximately $625,000, resulting in General Fund (GF) costs of $310,000 as a result of the Proposition 98 guarantee.
- Moderate one-time administrative costs of around $100,000 to the Board of Equalization (BOE) to implement the provisions of this bill.
COMMENTS:
- Background. Under current law, certain veterans’ organizations are eligible for the welfare exemption, meaning that these organizations’ property are not subject the property tax. However, many veterans’ organizations are ineligible for exemption because a property is disqualified if it is used for fraternal, lodge, or social purposes. Therefore in practice, only small portions of property owned by veterans’ organizations actually receive the property tax exemption. For example, buildings owned by the American Legion often have many uses, some of which are social in nature. Currently, only around 50 organizations currently apply for the exemption, and a number of these only receive a partial exemption because of the limits on the uses of exempt property.
- Purpose. According to the author, AB 1249 will help ensure veterans’ organizations have the resources needed to serve California’s veterans. The author notes that this bill will guarantee that the welfare exemption won’t be denied to veterans’ halls and other property owned by veterans’ organizations who host events for fraternal, lodge, or social purposes.
- Previous legislation. SB 2 (Anderson) of the 2015-16 Legislative Session, which was similar to this bill, died in the Assembly Committee on Revenue and Taxation. SB 1152 (Anderson) of the 2013-14 Legislative Session, which also was substantially similar to this bill, also died in the Assembly Committee on Revenue and Taxation.
Analysis Prepared by: Luke Reidenbach / APPR. / (916) 319-2081
Date of Hearing: April 25, 2017
ASSEMBLY COMMITTEE ON VETERANS AFFAIRS
Jacqui Irwin, Chair
ABPCA Bill Id:AB 1249 (
Author:Gray) – As Introduced Ver:February 17, 2017
SUBJECT: Property taxation: exemptions: veterans’ organizations
SUMMARY: Extends the application of the "veterans' organization" property tax exemption to real property owned by certain veterans' organizations and used for fraternal, lodge, or social club purposes, as specified, excluding the bar area. Specifically, this bill:
- Provides that property, which is owned by a veteran's organization chartered by the United States (U.S.) Congress and otherwise eligible for the veterans' organization exemption, may not be denied the exemption on the basis that the property is used for fraternal, lodge, or social club purposes.
- Specifies that the veterans' organization exemption shall not apply to any portion of the property that consists of a bar where alcoholic beverages are served. The portion of the property ineligible for the exemption is the area used primarily to prepare and serve alcoholic beverages.
- Makes findings and declarations related to the activities of veterans’ organizations.
- Provides that the state shall not reimburse any local agency for any property tax revenues lost by it pursuant to this bill.
- Takes effect immediately as a tax levy.
EXISTING LAW:
Existing federal law defines a post or an organization of past or present members of the Armed Forces of the United States (U.S.) as tax-exempt under Internal Revenue Code (IRC) Section 501(c)(19) if:
- The post or organization is organized in the U.S. or any of its possessions;
- At least 75% of the members are past or present members of the Armed Forces of the U.S. and substantially all of the other members of which are individuals who are cadets or are spouses, widows, widowers, ancestors, or lineal descendants of past or present members of the Armed Forces of the U.S. or of cadets; and,
- No part of the net earnings inure to the benefit of any private shareholder or individual.
- The post or organization is organized in the U.S. or any of its possessions;
Existing state law:
- Provides that all property is taxable, unless explicitly exempted by the California Constitution or federal law and limits the maximum amount of any ad valorem tax on real property at 1% of full cash value.
- Provides an exemption from taxation for property that is irrevocably dedicated to religious, hospital, scientific, or charitable purposes, if the property is used for the actual operation of the exempt activity and is owned by a nonprofit entity qualified as an exempt organization by the Internal Revenue Service, the Franchise Tax Board, or both (the so-called 'welfare exemption') [Article XIII, Section 4, of the California Constitution; Revenue and Taxation Code (R&TC) Section 214]. The entity that owns the property is prohibited from having any earnings that contribute to the benefit of any private shareholder or individual. This welfare exemption has been expanded over the years to add certain specific types of property that do not otherwise qualify under the general exemption.
- Provides a property tax exemption for all buildings and real property exclusively used for charitable purposes by a veterans' organization that is: (a) chartered by the U.S. Congress, and (b) organized and operated for charitable purposes. In order to obtain the exemption, the organization must file a claim with the county assessor.
FISCAL EFFECT: >
COMMENTS: This bill was heard in the Revenue and Taxation Committee where it received unanimous support. Thus the following comments are focused on the veterans aspects of this bill. According to the author:
Assembly Bill 1249 would provide clarity to counties in order to maintain crucial property tax exemptions guaranteed to veterans’ organizations, and ensure they have the resources they need to continue serving those who have sacrificed so much for our freedom. AB 1249 would guarantee that the welfare exemption would not be denied to veterans’ halls and other property owned by veterans’ organizations who host events for fraternal, lodge, or social purposes. It is important to note that the exemption would not apply to any portion of the property where alcohol is provided. For generations, veteran halls in cities and towns across our country have been an invaluable resource for active military and veterans. If AB 1249 becomes law, it would assist in the preservation of these important community centers for years to come.
Tax exempt status is intended to provide economic incentive and support to veterans’ organizations to persist and provide for the social welfare of the community of current and former military personnel.
The Board of Equalization constriction of the tax exemption has resulted in an onerous tax burden on California VSO Posts’ ability to provide facilities for veterans and threatens the economic viability of many local organizations.
There is a demographic shift in the veteran population as Vietnam and Korea veterans age out. The Iraq-Afghanistan era veterans may choose to participate in the traditional VSOs, so far the overall trend has been toward declining membership. Younger veterans have and may increasingly in the future seek to form new VSOs of their own. Congressional Charters are very rarely granted anymore. Though this is not in the bill, if that requirement for Congressional Chartering were deleted in favor of a requirement that the organization simply be a veterans organization it would support more VSOs. So perhaps something like this:
215.1. (a) All buildings, and so much of the real property …, used exclusively for charitable purposes, owned by a veterans’ organization … organized and operated for charitable purposes, …, shall be exempt from taxation.
Previous legislation: SB 2 (Anderson), 2015-16, was substantially similar to this bill. SB 2 was held in Assembly Revenue and Taxation.
SB 1152 (Anderson), 2013-14, was substantially similar to this bill. SB 1152 was held in Assembly Revenue and Taxation.
SB 1469 (Johannessen), 2001-02, would have provided that property is still eligible for the veterans' organization exemption if the only reason for disqualification is that the property is occasionally made available for private rentals as a service to the community.
REGISTERED SUPPORT / OPPOSITION:
Support
American G.I Forum of California
American Legion, Department of California
American Veterans, Department of California
California Association of County Veterans Services Officers
California State Commander Veterans Council
Military Officers Association of America, California Council of Chapters
Vietnam Veterans of America, California State Council
Opposition
None on File.
Analysis Prepared by: John Spangler / V.A. / (916) 319-3550
Date of Hearing: April 17, 2017
ASSEMBLY COMMITTEE ON REVENUE AND TAXATION
Sebastian Ridley-Thomas, Chair
ABPCA Bill Id:AB 1249 (
Author:Gray) – As Introduced Ver:February 17, 2017
Majority vote. Tax levy. Fiscal committee.
SUBJECT: Property taxation: exemptions: veterans’ organizations
SUMMARY: Extends the application of the "veterans' organization" property tax exemption to real property owned by certain veterans' organizations and used for fraternal, lodge, or social club purposes, as specified, excluding the bar area. Specifically, this bill:
- Provides that property, which is owned by a veteran's organization chartered by the United States (U.S.) Congress and otherwise eligible for the veterans' organization exemption, may not be denied the exemption on the basis that the property is used for fraternal, lodge, or social club purposes.
- Specifies that the veterans' organization exemption shall not apply to any portion of the property that consists of a bar where alcoholic beverages are served. The portion of the property ineligible for the exemption is the area used primarily to prepare and serve alcoholic beverages.
- Makes findings and declarations related to the activities of veterans’ organizations.
- Provides that the state shall not reimburse any local agency for any property tax revenues lost by it pursuant to this bill.
- Takes effect immediately as a tax levy.
EXISTING FEDERAL LAW defines a post or an organization of past or present members of the Armed Forces of the United States (U.S.) as tax-exempt under Internal Revenue Code (IRC) Section 501(c)(19) if:
- The post or organization is organized in the U.S. or any of its possessions;
- At least 75% of the members are past or present members of the Armed Forces of the U.S. and substantially all of the other members of which are individuals who are cadets or are spouses, widows, widowers, ancestors, or lineal descendants of past or present members of the Armed Forces of the U.S. or of cadets; and,
- No part of the net earnings inure to the benefit of any private shareholder or individual.
EXISTING STATE LAW:
- Provides that all property is taxable, unless explicitly exempted by the California Constitution or federal law and limits the maximum amount of any ad valorem tax on real property at 1% of full cash value.
- Provides an exemption from taxation for property that is irrevocably dedicated to religious, hospital, scientific, or charitable purposes, if the property is used for the actual operation of the exempt activity and is owned by a nonprofit entity qualified as an exempt organization by the Internal Revenue Service, the Franchise Tax Board, or both (the so-called 'welfare exemption') [Article XIII, Section 4, of the California Constitution; Revenue and Taxation Code (R&TC) Section 214]. The entity that owns the property is prohibited from having any earnings that contribute to the benefit of any private shareholder or individual. This welfare exemption has been expanded over the years to add certain specific types of property that do not otherwise qualify under the general exemption.
- Provides a property tax exemption for all buildings and real property exclusively used for charitable purposes by a veterans' organization that is: (a) chartered by the U.S. Congress, and (b) organized and operated for charitable purposes. In order to obtain the exemption, the organization must file a claim with the county assessor.
FISCAL EFFECT: The State Board of Equalization estimates that this bill will result in an annual local revenue loss of $625,000.
COMMENTS:
- The author has provided the following statement in support of this bill:
Assembly Bill 1249 would provide clarity to counties in order to maintain crucial property tax exemptions guaranteed to veterans’ organizations, and ensure they have the resources they need to continue serving those who have sacrificed so much for our freedom. AB 1249 would guarantee that the welfare exemption would not be denied to veterans’ halls and other property owned by veterans’ organizations who host events for fraternal, lodge, or social purposes. It is important to note that the exemption would not apply to any portion of the property where alcohol is provided. For generations, veteran halls in cities and towns across our country have been an invaluable resource for active military and veterans. If AB 1249 becomes law, it would assist in the preservation of these important community centers for years to come.
- Supporters of this bill appreciate the effort to “ensure that as non-profit organizations, existing property tax exemptions for veteran halls are preserved.”
- Committee Staff Comments:
- The veterans' organization exemption: Property owned by a veterans' organization chartered by the U.S. Congress is eligible for the welfare exemption, provided that the organization complies with all applicable requirements; is exempt from tax under federal and state law; and has a "veterans' organization exemption" certificate of compliance on file with the county assessor. The majority of veterans' organizations are ineligible for exemption because another provision of the law – R&TC Section 214(a)(5) – disqualifies property if it is used for fraternal, lodge, or social purposes. In practice, only small portions of property owned by veterans' organizations actually receive the property tax exemption. Buildings owned by the Veterans of Foreign Wars and the American Legion often have many uses, some of which are social in nature. As a result, the application of the veterans' organization exemption is inconsistent from county to county. Some counties assess the entire property; others do not assess the property at all; and still others exempt just the office and facilities that directly serve veterans, such as counseling rooms used for readjustment services.
According to the BOE analysis of this bill, R&TC Section 215.1, which provides for the veterans' organization exemption, was added by AB 184 (Powers), Chapter 151, Statutes of 1972. The BOE opposed AB 184 and, in a letter sent to Governor Reagan, explained, "While AB 184 implies that the activities of veterans' organizations are charitable, it does not directly so state…. This curious construction invites litigation. If a tax benefit is to be granted, it should be clear as to what that benefit is." The BOE noted several potential interpretations of the language in AB 184. First, AB 184 may be viewed as the creation of a new exemption that would be invalid without the support of a constitution amendment. Alternatively, AB 184 may be viewed as merely "permitting veterans' organizations to receive the welfare exemption if they meet the traditional concepts of charity and otherwise satisfy other welfare exemption requirements," in which case AB 184 is "an exercise in futility since it is highly doubtful that any organization could qualify." Finally, AB 184 may be viewed as "a vague attempt to expand the concept of charity so as to permit veterans' organizations to receive the benefit of the welfare exemption." This interpretation is also of "doubtful constitution validity." The Governor, however, signed AB 184 into law.
While many veterans' organizations applied for the new exemption, the BOE denied all the claims. Representatives of veterans' organizations subsequently protested the denials before the BOE on January 4, 1974. Ultimately, this exemption "was extended to a limited portion of the entire veterans' organization property, such as the counseling rooms used for readjustment services, post-traumatic stress disorders, and alcohol or drug assistance programs."
The BOE staff notes the veterans' organization exemption has had little practical effect since relatively few properties owned by veterans' organizations currently receive the exemption, and those that do are only receiving a partial exemption on a small part of their property. In fact, only about 50 organizations currently apply for the exemption and a number of these receive a partial exemption, generally on the office or counseling rooms used for readjustment services, post-traumatic stress disorders, and alcohol or drug assistance programs. Most of the properties consist of a club room, auditorium, restaurant, and/or bar, which are not eligible for the property tax exemption, except where the use is clearly incidental to a primary charitable purpose. - What is the problem? According to the sponsors of the bill, the exemption is intended to subsidize veteran organizations. Membership at these organizations has dramatically declined over the years because the membership is primarily made up of World War II, Korea, and Vietnam veterans. Younger veterans are not joining these organizations; as a result, those organizations are collecting less in dues to pay for upkeep of the property. The American Legion, which had 3.3 million members nationally at its height in 1947, still has 14,000 active posts and 2 million members nationwide, but only about 30,000 are veterans under the age of 40[1]. If the underlying problem is a lack of interest from younger veterans, it is unclear to Committee staff if relieving veterans’ organizations from property taxes would increase membership.
- Slippery slope? While this bill provides tax relief to veterans' organizations, it sets a precedent for other groups to seek similar property tax exemptions. As stated in the BOE analysis of this bill, lodges and clubs owned by the Elks, Moose, Oddfellows, and Rotary, etc., are not exempt from taxation. The Committee may wish to consider whether the activities of U.S. Congress-chartered veterans' organizations significantly differ from community services performed by similarly situated non-profit organizations and whether the difference warrants a disparate tax treatment of properties owned by those organizations.
- Constitutional concerns: The language of the Constitution is clear that the qualifying property must be owned, operated and used by a nonprofit entity for exempt purposes and activities, and no part of the entity's net earnings may inure to the benefit of any private shareholder or individual. Property must be used exclusively for religious, hospital, or charitable purposes. In 1973, the Attorney General opined that R&TC Section 251.1 (which is proposed to be amended by this bill) was constitutional because it contained an additional eligibility requirement, namely a requirement to meet all of the provisions of R&TC Section 214(a)(1) - (7). In this connection, subparagraph (5) of Section 214(a) mandates that the property be not used for fraternal or lodge purposes or for social club purposes, except where that use is clearly incidental to a primary religious, hospital, scientific or charitable purpose. This bill proposes to delete this requirement, which puts in question the constitutionality of Section 251.1, as proposed to be amended.
- The veterans' organization exemption: Property owned by a veterans' organization chartered by the U.S. Congress is eligible for the welfare exemption, provided that the organization complies with all applicable requirements; is exempt from tax under federal and state law; and has a "veterans' organization exemption" certificate of compliance on file with the county assessor. The majority of veterans' organizations are ineligible for exemption because another provision of the law – R&TC Section 214(a)(5) – disqualifies property if it is used for fraternal, lodge, or social purposes. In practice, only small portions of property owned by veterans' organizations actually receive the property tax exemption. Buildings owned by the Veterans of Foreign Wars and the American Legion often have many uses, some of which are social in nature. As a result, the application of the veterans' organization exemption is inconsistent from county to county. Some counties assess the entire property; others do not assess the property at all; and still others exempt just the office and facilities that directly serve veterans, such as counseling rooms used for readjustment services.
- Prior legislation:
- SB 2 (Anderson), of the 2015-16 Legislative Session, was substantially similar to this bill. SB 2 was held on this Committee’s Suspense File.
- SB 1152 (Anderson), of the 2013-14 Legislative Session, was substantially similar to this bill. SB 1152 was held on this Committee's Suspense File.
- SB 1469 (Johannessen), of the 2001-02 Legislative Session, would have provided that property is still eligible for the veterans' organization exemption if the only reason for disqualification is that the property is occasionally made available for private rentals as a service to the community. SB 1469 was never heard by the Senate Revenue and Taxation Committee.
REGISTERED SUPPORT / OPPOSITION:
Support
American G.I Forum of California
American Legion, Department of California
American Veterans, Department of California
California Association of County Veterans Services Officers
California State Commander Veterans Council
Military Officers Association of America, California Council of Chapters
Vietnam Veterans of America, California State Council
Opposition
None on file
Analysis Prepared by: Carlos Anguiano / REV. & TAX. / (916) 319-2098
Mike Seely, A lonely veteran opened the doors to this American Legion post in order to save it, Los Angeles Times, Jan. 10, 2017. ↑
Discussed in Hearing
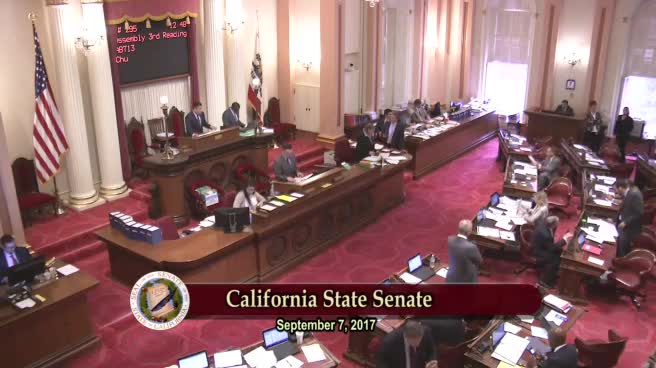 2MIN
Senate Floor
 1H
Senate Standing Committee on Appropriations
 2MIN
Senate Standing Committee on Governance and Finance
 1MIN
Assembly Floor
 1H
Assembly Standing Committee on Appropriations
 10MIN
Assembly Standing Committee on Veterans Affairs
 7MIN
Assembly Standing Committee on Revenue and Taxation
Bill Author
Bill Co-Author(s):