AB 2562: Department of Housing and Community Development loans.
- Session Year: 2017-2018
- House: Assembly
- Latest Version Date: 2018-09-26
Existing law, the Multifamily Housing Program, is administered by the Department of Housing and Community Development to address renter housing needs through an omnibus multifamily housing program. Under the program, assistance provided to a project is required to be provided in the form of a deferred payment loan to pay for the eligible costs of development. Existing law, subject to specified terms, authorizes the department to approve an extension of an existing loan, the subordination of an existing loan to new debt, or an investment of tax credit equity if the rental housing development is being operated in a manner consistent with the regulatory agreement and the development requires an extension in order to continue to operate in that manner. Existing law also authorizes the department to reduce the interest rate on any loan issued by the department to a rental housing development to as low as 0.42% per annum, or a rate determined by the department that is sufficient to cover the costs of project monitoring, whichever is greater, if the development meets specified requirements regarding, among other things, debt and household income.
Existing law also authorizes the Department of Housing and Community Development to approve an extension of a department loan, the subordination of a department loan to new debt, or an investment of tax credit equity under specified rental housing finance programs other than the Multifamily Housing Program, subject to specified conditions.
This bill would include loans made under the Multifamily Housing Program and any and all other multifamily housing loans funded or monitored by the department within these latter provisions authorizing the extension of an existing loan, subordination of an existing loan to new debt, or an investment of tax credit equity. The bill would require the department to reduce the interest rate on any loan issued by the department to a rental housing development if the development will utilize low-income housing tax credits, the department makes a specified determination regarding the loan or the ability of the development to syndicate, and the rate change will materially increase the feasibility of the proposed project and ensure long-term affordability for the residents.
Existing law also authorizes the department to change the current interest rate for any loan for which it receives a loan extension request, associated with an award of federal or state low income housing tax credits made on or after January 1, 2014, to the applicable federal rate most recently published by the Internal Revenue Service.
This bill instead would provide that the department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request, associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate published by the Internal Revenue Service and in effect at the time of the project closing.
Existing law requires the department to charge a fee in an amount sufficient to cover administrative costs associated with a loan modification requested by a borrower pursuant to these provisions.
This bill would instead authorize the department to charge the fee.
Existing law, the Multifamily Housing Program, is administered by the Department of Housing and Community Development to address renter housing needs through an omnibus multifamily housing program. Under the program, assistance provided to a project is required to be provided in the form of a deferred payment loan to pay for the eligible costs of development. Existing law, subject to specified terms, authorizes the department to approve an extension of an existing loan, the subordination of an existing loan to new debt, or an investment of tax credit equity if the rental housing development is being operated in a manner consistent with the regulatory agreement and the development requires an extension in order to continue to operate in that manner. Existing law also authorizes the department to reduce the interest rate on any loan issued by the department to a rental housing development to as low as 0.42% per annum, or a rate determined by the department that is sufficient to cover the costs of project monitoring, whichever is greater, if the development meets specified requirements regarding, among other things, debt and household income.
Existing law also authorizes the Department of Housing and Community Development to approve an extension of a department loan, the subordination of a department loan to new debt, or an investment of tax credit equity under specified rental housing finance programs other than the Multifamily Housing Program, subject to specified conditions.
This bill would include loans made under the Multifamily Housing Program and any and all other multifamily housing loans funded or monitored by the department within these latter provisions authorizing the extension of an existing loan, subordination of an existing loan to new debt, or an investment of tax credit equity. The bill would require the department to reduce the interest rate on any loan issued by the department to a rental housing development if the development will utilize low-income housing tax credits, the department makes a specified determination regarding the loan or the ability of the development to syndicate, and the rate change will materially increase the feasibility of the proposed project and ensure long-term affordability for the residents.
Existing law also authorizes the department to change the current interest rate for any loan for which it receives a loan extension request, associated with an award of federal or state low income housing tax credits made on or after January 1, 2014, to the applicable federal rate most recently published by the Internal Revenue Service.
This bill instead would provide that the department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request, associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate published by the Internal Revenue Service and in effect at the time of the project closing.
Existing law requires the department to charge a fee in an amount sufficient to cover administrative costs associated with a loan modification requested by a borrower pursuant to these provisions.
This bill would instead authorize the department to charge the fee.
Existing law, the Multifamily Housing Program, is administered by the Department of Housing and Community Development to address renter housing needs through an omnibus multifamily housing program. Under the program, assistance provided to a project is required to be provided in the form of a deferred payment loan to pay for the eligible costs of development. Existing law, subject to specified terms, authorizes the department to approve an extension of an existing loan, the subordination of an existing loan to new debt, or an investment of tax credit equity if the rental housing development is being operated in a manner consistent with the regulatory agreement and the development requires an extension in order to continue to operate in that manner. Existing law also authorizes the department to reduce the interest rate on any loan issued by the department to a rental housing development to as low as 0.42% per annum, or a rate determined by the department that is sufficient to cover the costs of project monitoring, whichever is greater, if the development meets specified requirements regarding, among other things, debt and household income.
Existing law also authorizes the Department of Housing and Community Development to approve an extension of a department loan, the subordination of a department loan to new debt, or an investment of tax credit equity under specified rental housing finance programs other than the Multifamily Housing Program, subject to specified conditions.
This bill would include loans made under the Multifamily Housing Program and any and all other multifamily housing loans funded or monitored by the department within these latter provisions authorizing the extension of an existing loan, subordination of an existing loan to new debt, or an investment of tax credit equity. The bill would also authorize, with respect to loans made under the Multifamily Housing Program, the extension of an existing loan, subordination of an existing loan to new debt, or an investment of tax credit equity to be made in connection with the combining of multiple sites or collateral as if the existing loan is a new loan, as specified. The bill would require the department to reduce the interest rate on any loan issued by the department to a rental housing development if the development will utilize low-income housing tax credits, the department makes a specified determination regarding the loan or the ability of the development to syndicate, and the rate change will materially increase the feasibility of the proposed project and ensure long-term affordability for the residents.
Existing law also authorizes the department to change the current interest rate for any loan for which it receives a loan extension request, associated with an award of federal or state low income housing tax credits made on or after January 1, 2014, to the applicable federal rate most recently published by the Internal Revenue Service.
This bill instead would provide that the department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request, associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate published by the Internal Revenue Service and in effect at the time of the project closing.
Existing law requires the department to charge a fee in an amount sufficient to cover administrative costs associated with a loan modification requested by a borrower pursuant to these provisions.
This bill would instead authorize the department to charge the fee.
Existing law, the Multifamily Housing Program, is administered by the Department of Housing and Community Development to address renter housing needs through an omnibus multifamily housing program. Under the program, assistance provided to a project is required to be provided in the form of a deferred payment loan to pay for the eligible costs of development. Existing law, subject to specified terms, authorizes the department to approve an extension of an existing loan, the subordination of an existing loan to new debt, or an investment of tax credit equity if the rental housing development is being operated in a manner consistent with the regulatory agreement and the development requires an extension in order to continue to operate in that manner. Existing law also authorizes the department to reduce the interest rate on any loan issued by the department to a rental housing development to as low as 0.42% per annum, or a rate determined by the department that is sufficient to cover the costs of project monitoring, whichever is greater, if the development meets specified requirements regarding, among other things, debt and household income.
Existing law also authorizes the Department of Housing and Community Development to approve an extension of a department loan, the subordination of a department loan to new debt, or an investment of tax credit equity under specified rental housing finance programs other than the Multifamily Housing Program, subject to specified conditions.
This bill would authorize each include loans made under the Multifamily Housing Program and any and all other multifamily housing loans funded or monitored by the department within these latter provisions authorizing the extension of an existing loan, subordination of an existing loan to new debt, or an investment of tax credit equity equity. The bill would also authorize, with respect to loans made under the Multifamily Housing Program, the extension of an existing loan, subordination of an existing loan to new debt, or an investment of tax credit equity to be made in connection with the combining of multiple sites or collateral as if the existing loan is a new loan, as specified, and specified. The bill would require the department to reduce the interest rate on any loan issued by the department to a rental housing development if the development will utilize low-income housing tax credits, the department makes a specified determination regarding the loan or the ability of the development to syndicate, and the rate change will materially increase the feasibility of the proposed project and ensure long-term affordability for the residents.
Existing law also authorizes the department to change the current interest rate for any loan for which it receives a loan extension request, associated with an award of federal or state low income housing tax credits made on or after January 1, 2014, to the applicable federal rate most recently published by the Internal Revenue Service.
This bill instead would provide that the department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request, associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate published by the Internal Revenue Service and in effect at the time of the project closing.
Existing law requires the department to charge a fee in an amount sufficient to cover administrative costs associated with a loan modification requested by a borrower pursuant to these provisions.
This bill would instead authorize the department to charge the fee.
Existing law, the Multifamily Housing Program, is administered by the Department of Housing and Community Development to address renter housing needs through an omnibus multifamily housing program. Under the program, assistance provided to a project is required to be provided in the form of a deferred payment loan to pay for the eligible costs of development. Existing law, subject to specified terms, authorizes the department to approve an extension of an existing loan, the subordination of an existing loan to new debt, or an investment of tax credit equity if the rental housing development is being operated in a manner consistent with the regulatory agreement and the development requires an extension in order to continue to operate in that manner. Existing law also authorizes the department to reduce the interest rate on any loan issued by the department to a rental housing development to as low as 0.42% per annum, or a rate determined by the department that is sufficient to cover the costs of project monitoring, whichever is greater, if the development meets specified requirements regarding, among other things, debt and household income.
This bill would authorize each extension of an existing loan, subordination of an existing loan to new debt, or investment of tax credit equity to be made in connection with the combining of multiple sites or collateral as if the existing loan is a new loan, as specified, and would authorize require the department to revise the requirements for reduce the interest rate reduction to instead require that if the development will utilize low-income housing tax credits, the department makes a specified determination regarding the loan or the ability of the development to syndicate, and the rate change will materially increase the feasibility of the proposed project and further the goals and purpose of the department and the appropriate loan program. ensure long-term affordability for the residents.
Existing law also authorizes the department to change the current interest rate for any loan for which it receives a loan extension request, associated with an award of federal or state low income housing tax credits made on or after January 1, 2014, to the applicable federal rate most recently published by the Internal Revenue Service.
This bill instead would provide that the department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request, associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate published by the Internal Revenue Service and in effect at the time of the project closing.
Existing law requires the department to charge a fee in an amount sufficient to cover administrative costs associated with a loan modification requested by a borrower pursuant to these provisions.
This bill would instead authorize the department to charge the fee.
Existing law authorizes the Department of Housing and Community Development to make loans under a multifamily housing program, and law, the Multifamily Housing Program, is administered by the Department of Housing and Community Development to address renter housing needs through an omnibus multifamily housing program. Under the program, assistance provided to a project is required to be provided in the form of a deferred payment loan to pay for the eligible costs of development. Existing law, subject to specified terms, authorizes the department to approve an extension of an existing loan, the subordination of an existing loan to new debt, or an investment of tax credit equity if the rental housing development is being operated in a manner consistent with the regulatory agreement and the development requires an extension in order to continue to operate in that manner. Existing law also authorizes the department to reduce the interest rate on any loan issued by the department to a rental housing development to as low as 0.42% per annum, or a rate determined by the department that is sufficient to cover the costs of project monitoring, whichever is greater, if the development meets specified requirements regarding, among other things, debt and household income.
This bill would authorize the department to reduce the interest rate on any loan issued by the department to a rental housing development to only a rate determined by the department that is sufficient to cover the costs of project monitoring and would each extension of an existing loan, subordination of an existing loan to new debt, or investment of tax credit equity to be made in connection with the combining of multiple sites or collateral as if the existing loan is a new loan, as specified, and would authorize the department to revise the requirements for the interest rate reduction to instead require that the rate change increase the feasibility of the proposed project and further the goals and purpose of the department and the appropriate loan program.
Existing law also authorizes the department to change the current interest rate for any loan for which it receives a loan extension request, associated with an award of federal or state low income housing tax credits made on or after January 1, 2014, to the applicable federal rate most recently published by the Internal Revenue Service.
This bill instead would provide that the department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request, associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate published by the Internal Revenue Service and in effect at the time of the project closing.
Existing law requires the department to charge a fee in an amount sufficient to cover administrative costs associated with a loan modification requested by a borrower pursuant to these provisions.
This bill would instead authorize the department to charge the fee.
Existing law authorizes the Department of Housing and Community Development to make loans under a multifamily housing program, and to reduce the interest rate on any loan issued by the department to a rental housing development to as low as 0.42% per annum, or a rate determined by the department that is sufficient to cover the costs of project monitoring, whichever is greater, if the development meets specified requirements regarding, among other things, debt and household income.
This bill would authorize the department to reduce the interest rate on any loan issued by the department to a rental housing development to only a rate determined by the department that is sufficient to cover the costs of project monitoring and would revise the requirements for the reduction to instead require that the rate change increase the feasibility of the proposed project and further the goals and purpose of the department and the appropriate loan program.
Existing law also authorizes the department to change the current interest rate for any loan for which it receives a loan extension request, associated with an award of federal or state low income housing tax credits made on or after January 1, 2014, to the applicable federal rate most recently published by the Internal Revenue Service.
This bill instead would provide that the department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request, associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate published by the Internal Revenue Service and in effect at the time of the project closing.
Existing law requires the department to charge a fee in an amount sufficient to cover administrative costs associated with a loan modification requested by a borrower pursuant to these provisions.
This bill would instead authorize the department to charge the fee.
Existing law authorizes the Department of Housing and Community Development to make loans under a multifamily housing program, and to reduce the interest rate on any loan issued by the department to a rental housing development to as low as 0.42% per annum, or a rate determined by the department that is sufficient to cover the costs of project monitoring, whichever is greater, if the development meets specified requirements regarding, among other things, debt and household income.
This bill would authorize the department to reduce the interest rate on any loan issued by the department to a rental housing development to only a rate determined by the department that is sufficient to cover the costs of project monitoring and would revise these the requirements for the reduction to instead require that the rate change increase the feasibility of the proposed project and will further the goals and purpose of the department and the appropriate loan program.
Existing law also authorizes the department to change the current interest rate for any loan for which it receives a loan extension request, associated with an award of federal or state low income housing tax credits made on or after January 1, 2014, to the applicable federal rate most recently published by the Internal Revenue Service.
This bill instead would provide that the department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request, associated with an award of federal or state low income low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate published by the Internal Revenue Service and in effect at the time of the loan extension and project closing.
Existing law authorizes the Department of Housing and Community Development to make loans under a multifamily housing program, and to reduce the interest rate on any loan issued by the department to a rental housing development to as low as 0.42% per annum, or a rate determined by the department that is sufficient to cover the costs of project monitoring, if the development meets specified requirements regarding, among other things, debt and household income.
This bill would revise these requirements to instead require that the rate change increase the feasibility of the proposed project and will further the goals and purpose of the department and the appropriate loan program.
Existing law also authorizes the department to change the current interest rate for any loan for which it receives a loan extension request, associated with an award of federal or state low income housing tax credits made on or after January 1, 2014, to the applicable federal rate most recently published by the Internal Revenue Service.
This bill instead would provide that the department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request, associated with an award of federal or state low income housing tax credits made on or after January 1, 2014, to the applicable federal rate published by the Internal Revenue Service and in effect at the time of the loan extension and project closing.
(a)Notwithstanding any other law, the department shall reduce the interest rate on any loan issued by the department to a rental housing development to as low as forty-two hundredths of 1 percent per annum, or a rate determined by the department that is sufficient to cover the costs of project monitoring described in subdivision (c) of Section 50675.6, whichever is greater, if the following conditions are met:
(1)The development will utilize low-income housing tax credits.
(2)The department determines either one of the following:
(A)The loan issued by the department is not eligible to be treated as debt for federal or state low-income housing tax credit purposes without a reduction in the interest rate of the loan.
(B)The department determines that the rental housing development is not able to syndicate due to projected negative capital account balances.
(3)The change in the interest rate will materially increase the feasibility of the proposed project and will ensure long-term affordability for the residents.
(b)The department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate published by the United States Internal Revenue Service and in effect at the time of the project closing. The additional tax credit equity generated by the change in interest rate shall be used for rehabilitation of the development. If the total amount of debt and accrued interest at the end of the loan term would be greater after making this change than it would have been under the original interest rate, the department may forgive an amount of accrued interest equal to the lesser of either the amount necessary to make the expected principal and accrued interest the same as it would have been using the original interest rate, or the total amount of interest accrued at the time of the sponsors request.
(c)The department may charge a fee in an amount sufficient to cover administrative costs associated with a loan modification requested by a borrower pursuant to this section.
(d)For purposes of a determination made under paragraph (2) of subdivision (a), the department may require a third-party tax professional to verify the determination, the cost of which shall be borne by the sponsor.
(e)The amendments made to this section by Assembly Bill 2562 of the 201718 Regular Session shall not be construed to affect any interest rate reduction authorized by the department pursuant to this section as it read prior to the effective date of these amendments.
SEC. 2.Section 50560 of the Health and Safety Code is amended to read:50560.(a)Subject to the requirements of this chapter, the department may approve an extension of a department loan, the reinstatement of a qualifying unpaid matured loan, the subordination of a department loan to new debt, or an investment of tax credit equity under one or more of the following rental housing finance programs: the original Rental Housing Construction Program established by Chapter 9 (commencing with Section 50735), the Special User Housing Rehabilitation Program established by Section 50670, the Deferred Payment Rehabilitation Loan Program established by Chapter 6.5 (commencing with Section 50660), the rental component of the California Natural Disaster Assistance Program established by Chapter 6.5 (commencing with Section 50671), the State Earthquake Rehabilitation Assistance Program established by Chapter 6.5 (commencing with Section 50671), the rental component of the California Housing Rehabilitation Program established by Section 50668.5, the component of the Rental Housing Construction Program funded with bond proceeds governed by Section 50771.1, the Family Housing Demonstration Program established by Chapter 15 (commencing with Section 50880), the Families Moving to Work Program established by Chapter 15 (commencing with Section 50880), the Multifamily Housing Program established by Chapter 6.7 (commencing with Section 50675), and any and all other multifamily housing loans funded or monitored by the department.
(b)Once the department has approved a loan extension, reinstatement of a qualifying unpaid matured loan, subordination, or tax credit investment pursuant to this chapter, the statutes enumerated in subdivision (a), and the regulations promulgated pursuant to these statutes, shall no longer apply to developments restructured pursuant to this chapter. These developments shall instead be governed by this chapter and guidelines adopted pursuant to subdivision (h).
(c)All projects restructured pursuant to this chapter shall comply with the affirmative marketing and language accessibility requirements set forth in Section 50736 of this code and Section 65863 of the Government Code.
(d)The department may approve an extension of a loan, the reinstatement of a qualifying unpaid matured loan, the subordination of a department loan to new debt, or an investment of tax credit equity if it determines that the project has, or will have after rehabilitation or repairs, a potential remaining useful life equal to or greater than the term of the restructured loan.
(e)The department may subordinate its loan to refinance existing senior debt only as necessary for project feasibility and to reimburse borrower advances for predevelopment costs, recent capital improvements, and recent operating deficits.
(f)If the extension of a department loan, the reinstatement of a qualifying unpaid matured loan, the subordination of a department loan to new debt, or an investment of tax credit equity will result in a rent increase for tenants of a development, the department may only subordinate a loan to senior debt if necessary to increase the feasibility of a project and to fund reasonable rehabilitation or improvements including soft costs. The application to refinance shall include a third-party analysis that supports the need for refinancing.
(g)The department may approve additional senior debt only as necessary to finance rehabilitation or repairs, including soft costs, that are modest in size, scope, and cost, as determined by the department.
(h)It is the intent of the Legislature in enacting this chapter to provide to the department the flexibility necessary to maintain the quality of the affordable rental housing units for which the state has already made a significant public investment. The department may implement this chapter through guidelines that shall not be subject to Chapter 2.5 (commencing with Section 11340) of Part 1 of Title 2 of the Government Code. These guidelines shall be developed through the following process:
(1)The department shall provide a notice of proposed action as described in Section 11346.5 of the Government Code to the public at least 21 days before the close of the public comment period.
(2)The department shall schedule at least one public hearing as described in Section 11346.8 of the Government Code before the close of the public comment period.
(3)The department shall maintain a rulemaking file as described in Section 11347.3 of the Government Code.
(4)The final version of the guidelines shall be accompanied by a final statement of reason as described in subdivision (a) of Section 11346.9 of the Government Code.
(5)The rules and guidelines shall be effective immediately upon adoption by the department.
(a)Notwithstanding any other law, the department shall reduce the interest rate on any loan issued by the department to a rental housing development to as low as forty-two hundredths of 1 percent per annum, or a rate determined by the department that is sufficient to cover the costs of project monitoring described in subdivision (c) of Section 50675.6, whichever is greater, if the following conditions are met:
(1)The development will utilize low-income housing tax credits.
(2)The department determines either one of the following:
(A)The loan issued by the department is not eligible to be treated as debt for federal or state low-income housing tax credit purposes without a reduction in the interest rate of the loan.
(B)The department determines that the rental housing development is not able to syndicate due to projected negative capital account balances.
(3)The change in the interest rate will materially increase the feasibility of the proposed project and will ensure long-term affordability for the residents.
(b)The department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate published by the United States Internal Revenue Service and in effect at the time of the project closing. The additional tax credit equity generated by the change in interest rate shall be used for rehabilitation of the development. If the total amount of debt and accrued interest at the end of the loan term would be greater after making this change than it would have been under the original interest rate, the department may forgive an amount of accrued interest equal to the lesser of either the amount necessary to make the expected principal and accrued interest the same as it would have been using the original interest rate, or the total amount of interest accrued at the time of the sponsors request.
(c)The department may charge a fee in an amount sufficient to cover administrative costs associated with a loan modification requested by a borrower pursuant to this section.
(d)For purposes of a determination made under paragraph (2) of subdivision (a), the department may require a third-party tax professional to verify the determination, the cost of which shall be borne by the sponsor.
(e)The amendments made to this section by Assembly Bill 2562 of the 201718 Regular Session shall not be construed to affect any interest rate reduction authorized by the department pursuant to this section as it read prior to the effective date of these amendments.
SEC. 2.Section 50560 of the Health and Safety Code is amended to read:50560.(a)Subject to the requirements of this chapter, the department may approve an extension of a department loan, the reinstatement of a qualifying unpaid matured loan, the subordination of a department loan to new debt, or an investment of tax credit equity under one or more of the following rental housing finance programs: the original Rental Housing Construction Program established by Chapter 9 (commencing with Section 50735), the Special User Housing Rehabilitation Program established by Section 50670, the Deferred Payment Rehabilitation Loan Program established by Chapter 6.5 (commencing with Section 50660), the rental component of the California Natural Disaster Assistance Program established by Chapter 6.5 (commencing with Section 50671), the State Earthquake Rehabilitation Assistance Program established by Chapter 6.5 (commencing with Section 50671), the rental component of the California Housing Rehabilitation Program established by Section 50668.5, the component of the Rental Housing Construction Program funded with bond proceeds governed by Section 50771.1, the Family Housing Demonstration Program established by Chapter 15 (commencing with Section 50880), the Families Moving to Work Program established by Chapter 15 (commencing with Section 50880), the Multifamily Housing Program established by Chapter 6.7 (commencing with Section 50675), and any and all other multifamily housing loans funded or monitored by the department.
(b)Once the department has approved a loan extension, reinstatement of a qualifying unpaid matured loan, subordination, or tax credit investment pursuant to this chapter, the statutes enumerated in subdivision (a), and the regulations promulgated pursuant to these statutes, shall no longer apply to developments restructured pursuant to this chapter. These developments shall instead be governed by this chapter and guidelines adopted pursuant to subdivision (h).
(c)All projects restructured pursuant to this chapter shall comply with the affirmative marketing and language accessibility requirements set forth in Section 50736 of this code and Section 65863 of the Government Code.
(d)The department may approve an extension of a loan, the reinstatement of a qualifying unpaid matured loan, the subordination of a department loan to new debt, or an investment of tax credit equity if it determines that the project has, or will have after rehabilitation or repairs, a potential remaining useful life equal to or greater than the term of the restructured loan.
(e)The department may subordinate its loan to refinance existing senior debt only as necessary for project feasibility and to reimburse borrower advances for predevelopment costs, recent capital improvements, and recent operating deficits.
(f)If the extension of a department loan, the reinstatement of a qualifying unpaid matured loan, the subordination of a department loan to new debt, or an investment of tax credit equity will result in a rent increase for tenants of a development, the department may only subordinate a loan to senior debt if necessary to increase the feasibility of a project and to fund reasonable rehabilitation or improvements including soft costs. The application to refinance shall include a third-party analysis that supports the need for refinancing.
(g)The department may approve additional senior debt only as necessary to finance rehabilitation or repairs, including soft costs, that are modest in size, scope, and cost, as determined by the department.
(h)It is the intent of the Legislature in enacting this chapter to provide to the department the flexibility necessary to maintain the quality of the affordable rental housing units for which the state has already made a significant public investment. The department may implement this chapter through guidelines that shall not be subject to Chapter 2.5 (commencing with Section 11340) of Part 1 of Title 2 of the Government Code. These guidelines shall be developed through the following process:
(1)The department shall provide a notice of proposed action as described in Section 11346.5 of the Government Code to the public at least 21 days before the close of the public comment period.
(2)The department shall schedule at least one public hearing as described in Section 11346.8 of the Government Code before the close of the public comment period.
(3)The department shall maintain a rulemaking file as described in Section 11347.3 of the Government Code.
(4)The final version of the guidelines shall be accompanied by a final statement of reason as described in subdivision (a) of Section 11346.9 of the Government Code.
(5)The rules and guidelines shall be effective immediately upon adoption by the department.
(a)Notwithstanding any other law, the department shall reduce the interest rate on any loan issued by the department to a rental housing development to as low as forty-two hundredths of 1 percent per annum, or a rate determined by the department that is sufficient to cover the costs of project monitoring described in subdivision (c) of Section 50675.6, whichever is greater, if the following conditions are met:
(1)The development will utilize low-income housing tax credits.
(2)The department determines either one of the following:
(A)The loan issued by the department is not eligible to be treated as debt for federal or state low-income housing tax credit purposes without a reduction in the interest rate of the loan.
(B)The department determines that the rental housing development is not able to syndicate due to projected negative capital account balances.
(3)The change in the interest rate will materially increase the feasibility of the proposed project and will ensure long-term affordability for the residents.
(b)The department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate published by the United States Internal Revenue Service and in effect at the time of the project closing. The additional tax credit equity generated by the change in interest rate shall be used for rehabilitation of the development. If the total amount of debt and accrued interest at the end of the loan term would be greater after making this change than it would have been under the original interest rate, the department may forgive an amount of accrued interest equal to the lesser of either the amount necessary to make the expected principal and accrued interest the same as it would have been using the original interest rate, or the total amount of interest accrued at the time of the sponsors request.
(c)The department may charge a fee in an amount sufficient to cover administrative costs associated with a loan modification requested by a borrower pursuant to this section.
(d)For purposes of a determination made under paragraph (2) of subdivision (a), the department may require a third-party tax professional to verify the determination, the cost of which shall be borne by the sponsor.
(e)The amendments made to this section by Assembly Bill 2562 of the 201718 Regular Session shall not be construed to affect any interest rate reduction authorized by the department pursuant to this section as it read prior to the effective date of these amendments.
SEC. 2.Section 50560 of the Health and Safety Code is amended to read:50560.(a)Subject to the requirements of this chapter, the department may approve an extension of a department loan, the reinstatement of a qualifying unpaid matured loan, the subordination of a department loan to new debt, or an investment of tax credit equity under one or more of the following rental housing finance programs: the original Rental Housing Construction Program established by Chapter 9 (commencing with Section 50735), the Special User Housing Rehabilitation Program established by Section 50670, the Deferred Payment Rehabilitation Loan Program established by Chapter 6.5 (commencing with Section 50660), the rental component of the California Natural Disaster Assistance Program established by Chapter 6.5 (commencing with Section 50671), the State Earthquake Rehabilitation Assistance Program established by Chapter 6.5 (commencing with Section 50671), the rental component of the California Housing Rehabilitation Program established by Section 50668.5, the component of the Rental Housing Construction Program funded with bond proceeds governed by Section 50771.1, the Family Housing Demonstration Program established by Chapter 15 (commencing with Section 50880), the Families Moving to Work Program established by Chapter 15 (commencing with Section 50880), the Multifamily Housing Program established by Chapter 6.7 (commencing with Section 50675), and any and all other multifamily housing loans funded or monitored by the department.
(b)Once the department has approved a loan extension, reinstatement of a qualifying unpaid matured loan, subordination, or tax credit investment pursuant to this chapter, the statutes enumerated in subdivision (a), and the regulations promulgated pursuant to these statutes, shall no longer apply to developments restructured pursuant to this chapter. These developments shall instead be governed by this chapter and guidelines adopted pursuant to subdivision (h).
(c)All projects restructured pursuant to this chapter shall comply with the affirmative marketing and language accessibility requirements set forth in Section 50736 of this code and Section 65863 of the Government Code.
(d)The department may approve an extension of a loan, the reinstatement of a qualifying unpaid matured loan, the subordination of a department loan to new debt, or an investment of tax credit equity if it determines that the project has, or will have after rehabilitation or repairs, a potential remaining useful life equal to or greater than the term of the restructured loan.
(e)The department may subordinate its loan to refinance existing senior debt only as necessary for project feasibility and to reimburse borrower advances for predevelopment costs, recent capital improvements, and recent operating deficits.
(f)If the extension of a department loan, the reinstatement of a qualifying unpaid matured loan, the subordination of a department loan to new debt, or an investment of tax credit equity will result in a rent increase for tenants of a development, the department may only subordinate a loan to senior debt if necessary to increase the feasibility of a project and to fund reasonable rehabilitation or improvements including soft costs. The application to refinance shall include a third-party analysis that supports the need for refinancing.
(g)The department may approve additional senior debt only as necessary to finance rehabilitation or repairs, including soft costs, that are modest in size, scope, and cost, as determined by the department.
(h)It is the intent of the Legislature in enacting this chapter to provide to the department the flexibility necessary to maintain the quality of the affordable rental housing units for which the state has already made a significant public investment. The department may implement this chapter through guidelines that shall not be subject to Chapter 2.5 (commencing with Section 11340) of Part 1 of Title 2 of the Government Code. These guidelines shall be developed through the following process:
(1)The department shall provide a notice of proposed action as described in Section 11346.5 of the Government Code to the public at least 21 days before the close of the public comment period.
(2)The department shall schedule at least one public hearing as described in Section 11346.8 of the Government Code before the close of the public comment period.
(3)The department shall maintain a rulemaking file as described in Section 11347.3 of the Government Code.
(4)The final version of the guidelines shall be accompanied by a final statement of reason as described in subdivision (a) of Section 11346.9 of the Government Code.
(5)The rules and guidelines shall be effective immediately upon adoption by the department.
SEC. 3.Section 50675.6 of the Health and Safety Code is amended to read:50675.6.(a)A sponsor may apply for loans for one or more rental or transitional housing developments. A housing development may utilize any combination of federal, state, local, and private financial resources necessary to make the development affordable, for the term of the states regulatory agreement, to the eligible households.(b)(1) Loans made pursuant to subdivision (f) of Section 50675.7 to sponsors by a local public entity as part of its code enforcement efforts for rental housing developments involving rehabilitation shall only be for terms of not less than 20 years. All other loans shall be for a term of not less than 55 years.(2)For loans made pursuant to this chapter, the department may approve an extension of an existing loan, the subordination of an existing loan to new debt, or an investment of tax credit equity, as long as the rental housing development is being operated in a manner consistent with the regulatory agreement and the development requires an extension in order to continue to operate in a manner consistent with this chapter.(A)Each extension of an existing loan, subordination of an existing loan, or investment of tax credit equity may be made in connection with the combining of multiple sites or collateral as if the existing loan were a new loan, and shall otherwise be consistent with the departments uniform multifamily regulations (Subchapter 19 (commencing with Section 8300) of Chapter 7 of Division 1 of Title 25 of the California Code of Regulations).(B)Each extension shall be for a period of not less than 10 years and each extension shall not exceed 55 years or, if needed to match the term of tax credit restrictions, exceed 58 years. The interest rate for the extension shall be 3 percent simple interest, or such interest rate as authorized by the department pursuant to Section 50406.7.(C)All loan payments shall be deferred for the full term of the loan, except for residual receipts payments. These residual receipts payments shall be structured to avoid reducing the amount of payments on local public agency loans resulting solely from changes in the payment terms on the departments loan, and not resulting from fees or other payments to the borrower, and shall otherwise be consistent with the departments uniform multifamily regulations (Subchapter 19 (commencing with Section 8300) of Chapter 7 of Division 1 of Title 25 of the California Code of Regulations) or successor regulations. The department may charge a transaction fee to cover its costs for processing these restructuring transactions. The department may waive or defer some or all of this fee, if it determines that a particular development or class of developments does not have the ability to make these payments.(c)Principal and accumulated interest is due and payable upon completion of the term of the loan. The loan shall bear simple interest at the rate of 3 percent per annum on the unpaid principal balance. The department may forgive that portion of that loan that is used to cover costs of developing child care facilities. The department shall require annual loan payments in the minimum amount necessary to cover the costs of project monitoring. For the first 30 years of the loan term, the amount of the required loan payments shall not exceed forty-two hundredths of 1 percent (.42%) per annum.(d)The department may establish maximum loan-to-value requirements for some or all of the types of projects that are eligible for funding under this chapter.(e)The department shall establish per-unit and per-project loan limits for all project types.(a)Notwithstanding any other law, the department shall reduce the interest rate on any loan issued by the department to a rental housing development to as low as forty-two hundredths of 1 percent per annum, or a rate determined by the department that is sufficient to cover the costs of project monitoring described in subdivision (c) of Section 50675.6, whichever is greater, if the following conditions are met:
(1)The development will utilize low-income housing tax credits.
(2)The department determines either one of the following:
(A)The loan issued by the department is not eligible to be treated as debt for federal or state low-income housing tax credit purposes without a reduction in the interest rate of the loan.
(B)The department determines that the rental housing development is not able to syndicate due to projected negative capital account balances.
(3)The change in the interest rate will materially increase the feasibility of the proposed project and will ensure long-term affordability for the residents.
(b)The department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate published by the United States Internal Revenue Service and in effect at the time of the project closing. The additional tax credit equity generated by the change in interest rate shall be used for rehabilitation of the development. If the total amount of debt and accrued interest at the end of the loan term would be greater after making this change than it would have been under the original interest rate, the department may forgive an amount of accrued interest equal to the lesser of either the amount necessary to make the expected principal and accrued interest the same as it would have been using the original interest rate, or the total amount of interest accrued at the time of the sponsors request.
(c)The department may charge a fee in an amount sufficient to cover administrative costs associated with a loan modification requested by a borrower pursuant to this section.
(d)For purposes of a determination made under paragraph (2) of subdivision (a), the department may require a third-party tax professional to verify the determination, the cost of which shall be borne by the sponsor.
(e)The amendments made to this section by Assembly Bill 2562 of the 201718 Regular Session shall not be construed to affect any interest rate reduction authorized by the department pursuant to this section as it read prior to the effective date of these amendments.
SEC. 2.Section 50560 of the Health and Safety Code is amended to read:50560.(a)Subject to the requirements of this chapter, the department may approve an extension of a department loan, the reinstatement of a qualifying unpaid matured loan, the subordination of a department loan to new debt, or an investment of tax credit equity under one or more of the following rental housing finance programs: the original Rental Housing Construction Program established by Chapter 9 (commencing with Section 50735), the Special User Housing Rehabilitation Program established by Section 50670, the Deferred Payment Rehabilitation Loan Program established by Chapter 6.5 (commencing with Section 50660), the rental component of the California Natural Disaster Assistance Program established by Chapter 6.5 (commencing with Section 50671), the State Earthquake Rehabilitation Assistance Program established by Chapter 6.5 (commencing with Section 50671), the rental component of the California Housing Rehabilitation Program established by Section 50668.5, the component of the Rental Housing Construction Program funded with bond proceeds governed by Section 50771.1, the Family Housing Demonstration Program established by Chapter 15 (commencing with Section 50880), and the Families Moving to Work Program established by Chapter 15 (commencing with Section 50880). 50880), the Multifamily Housing Program established by Chapter 6.7 (commencing with Section 50675), and any and all other multifamily housing loans funded or monitored by the department.
(b)Once the department has approved a loan extension, reinstatement of a qualifying unpaid matured loan, subordination, or tax credit investment pursuant to this chapter, the statutes enumerated in subdivision (a), and the regulations promulgated pursuant to these statutes, shall no longer apply to developments restructured pursuant to this chapter. These developments shall instead be governed by this chapter and guidelines adopted pursuant to subdivision (h).
(c)All projects restructured pursuant to this chapter shall comply with the affirmative marketing and language accessibility requirements set forth in Section 50736 of this code and Section 65863 of the Government Code.
(d)The department may approve an extension of a loan, the reinstatement of a qualifying unpaid matured loan, the subordination of a department loan to new debt, or an investment of tax credit equity if it determines that the project has, or will have after rehabilitation or repairs, a potential remaining useful life equal to or greater than the term of the restructured loan.
(e)The department may subordinate its loan to refinance existing senior debt only as necessary for project feasibility and to reimburse borrower advances for predevelopment costs, recent capital improvements, and recent operating deficits.
(f)If the extension of a department loan, the reinstatement of a qualifying unpaid matured loan, the subordination of a department loan to new debt, or an investment of tax credit equity will result in a rent increase for tenants of a development, the department may only subordinate a loan to senior debt if necessary to increase the feasibility of a project and to fund reasonable rehabilitation or improvements including soft costs. The application to refinance shall include a third-party analysis that supports the need for refinancing.
(g)The department may approve additional senior debt only as necessary to finance rehabilitation or repairs, including soft costs, that are modest in size, scope, and cost, as determined by the department.
(h)It is the intent of the Legislature in enacting this chapter to provide to the department the flexibility necessary to maintain the quality of the affordable rental housing units for which the state has already made a significant public investment. The department may implement this chapter through guidelines that shall not be subject to Chapter 2.5 (commencing with Section 11340) of Part 1 of Title 2 of the Government Code. These guidelines shall be developed through the following process:
(1)The department shall provide a notice of proposed action as described in Section 11346.5 of the Government Code to the public at least 21 days before the close of the public comment period.
(2)The department shall schedule at least one public hearing as described in Section 11346.8 of the Government Code before the close of the public comment period.
(3)The department shall maintain a rulemaking file as described in Section 11347.3 of the Government Code.
(4)The final version of the guidelines shall be accompanied by a final statement of reason as described in subdivision (a) of Section 11346.9 of the Government Code.
(5)The rules and guidelines shall be effective immediately upon adoption by the department.
SEC. 2.SEC. 3.Section 50675.6 of the Health and Safety Code is amended to read:50675.6.(a)A sponsor may apply for loans for one or more rental or transitional housing developments. A housing development may utilize any combination of federal, state, local, and private financial resources necessary to make the development affordable, for the term of the states regulatory agreement, to the eligible households.
(b)(1) Loans made pursuant to subdivision (f) of Section 50675.7 to sponsors by a local public entity as part of its code enforcement efforts for rental housing developments involving rehabilitation shall only be for terms of not less than 20 years. All other loans shall be for a term of not less than 55 years.
(2)For loans made pursuant to this chapter, the department may approve an extension of an existing loan, the subordination of an existing loan to new debt, or an investment of tax credit equity, as long as the rental housing development is being operated in a manner consistent with the regulatory agreement and the development requires an extension in order to continue to operate in a manner consistent with this chapter.
(A)Each extension of an existing loan, subordination of an existing loan, or investment of tax credit equity may be made in connection with the combining of multiple sites or collateral as if the existing loan were a new loan, and shall otherwise be consistent with the departments uniform multifamily regulations (Subchapter 19 (commencing with Section 8300) of Chapter 7 of Division 1 of Title 25 of the California Code of Regulations).
(B)Each extension shall be for a period of not less than 10 years and each extension shall not exceed 55 years or, if needed to match the term of tax credit restrictions, exceed 58 years. The interest rate for the extension shall be 3 percent simple interest, or such interest rate as authorized by the department pursuant to Section 50406.7.
(C)All loan payments shall be deferred for the full term of the loan, except for residual receipts payments. These residual receipts payments shall be structured to avoid reducing the amount of payments on local public agency loans resulting solely from changes in the payment terms on the departments loan, and not resulting from fees or other payments to the borrower, and shall otherwise be consistent with the departments uniform multifamily regulations (Subchapter 19 (commencing with Section 8300) of Chapter 7 of Division 1 of Title 25 of the California Code of Regulations) or successor regulations. The department may charge a transaction fee to cover its costs for processing these restructuring transactions. The department may waive or defer some or all of this fee, if it determines that a particular development or class of developments does not have the ability to make these payments.
(c)Principal and accumulated interest is due and payable upon completion of the term of the loan. The loan shall bear simple interest at the rate of 3 percent per annum on the unpaid principal balance. The department may forgive that portion of that loan that is used to cover costs of developing child care facilities. The department shall require annual loan payments in the minimum amount necessary to cover the costs of project monitoring. For the first 30 years of the loan term, the amount of the required loan payments shall not exceed forty-two hundredths of 1 percent (.42%) per annum.
(d)The department may establish maximum loan-to-value requirements for some or all of the types of projects that are eligible for funding under this chapter.
(e)The department shall establish per-unit and per-project loan limits for all project types.
(a)Notwithstanding any other law, the department may shall reduce the interest rate on any loan issued by the department to a rental housing development to as low as forty-two hundredths of 1 percent per annum, or a rate determined by the department that is sufficient to cover the costs of project monitoring described in subdivision (c) of Section 50675.6, whichever is greater, if the development meets all of the following requirements: conditions are met:
(1)The development will utilize low-income housing tax credits.
(2)The department determines that the either one of the following:
(A)The loan issued by the department is not eligible to be treated as debt for federal or state low-income housing tax credit purposes without a reduction in the interest rate of the loan. The department may require a third-party tax professional to verify this determination, the cost of which shall be borne by the sponsor.
(B)The department determines that the rental housing development is not able to syndicate due to projected negative capital account balances.
(3)The change in the interest rate will materially increase the feasibility of the proposed project and will further the goals and purpose of the department and the appropriate loan program. ensure long-term affordability for the residents.
(4)The new department loan shall not be used to supplant or replace an existing department loan.(b)The department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate published by the United States Internal Revenue Service and in effect at the time of the project closing. The additional tax credit equity generated by the change in interest rate shall be used for rehabilitation of the development. If the total amount of debt and accrued interest at the end of the loan term would be greater after making this change than it would have been under the original interest rate, the department may forgive an amount of accrued interest equal to the lesser of either the amount necessary to make the expected principal and accrued interest the same as it would have been using the original interest rate, or the total amount of interest accrued at the time of the sponsors request.
(c)The department may charge a fee in an amount sufficient to cover administrative costs associated with a loan modification requested by a borrower pursuant to this section.
(d)For purposes of a determination made under paragraph (2) of subdivision (a), the department may require a third-party tax professional to verify the determination, the cost of which shall be borne by the sponsor.
(d)
(e)The amendments made to this section by Assembly Bill 2562 of the 20172018 201718 Regular Session shall not be construed to affect any interest rate reduction authorized by the department pursuant to this section as it read prior to the effective date of these amendments.
SEC. 2.Section 50675.6 of the Health and Safety Code is amended to read:50675.6.(a)A sponsor may apply for loans for one or more rental or transitional housing developments. A housing development may utilize any combination of federal, state, local, and private financial resources necessary to make the development affordable, for the term of the states regulatory agreement, to the eligible households.
(b)(1) Loans made pursuant to subdivision (f) of Section 50675.7 to sponsors by a local public entity as part of its code enforcement efforts for rental housing developments involving rehabilitation shall only be for terms of not less than 20 years. All other loans shall be for a term of not less than 55 years.
(2)For loans made pursuant to this chapter, the department may approve an extension of an existing loan, the subordination of an existing loan to new debt, or an investment of tax credit equity, as long as the rental housing development is being operated in a manner consistent with the regulatory agreement and the development requires an extension in order to continue to operate in a manner consistent with this chapter.
(A)Each extension of an existing loan, subordination of an existing loan, or investment of tax credit equity may be made in connection with the combining of multiple sites or collateral as if the existing loan were a new loan, and shall otherwise be consistent with the departments uniform multifamily regulations (Subchapter 19 (commencing with Section 8300) of Chapter 7 of Division 1 of Title 25 of the California Code of Regulations).
(B)Each extension shall be for a period of not less than 10 years and each extension shall not exceed 55 years or, if needed to match the term of tax credit restrictions, exceed 58 years. The interest rate for the extension shall be 3 percent simple interest, or such interest rate as authorized by the department pursuant to Section 50406.7.
(C)All loan payments shall be deferred for the full term of the loan, except for residual receipts payments. These residual receipts payments shall be structured to avoid reducing the amount of payments on local public agency loans resulting solely from changes in the payment terms on the departments loan, and not resulting from fees or other payments to the borrower, and shall otherwise be consistent with the departments uniform multifamily regulations (Subchapter 19 (commencing with Section 8300) of Chapter 7 of Division 1 of Title 25 of the California Code of Regulations) or successor regulations. The department may charge a transaction fee to cover its costs for processing these restructuring transactions. The department may waive or defer some or all of this fee, if it determines that a particular development or class of developments does not have the ability to make these payments.
(c)Principal and accumulated interest is due and payable upon completion of the term of the loan. The loan shall bear simple interest at the rate of 3 percent per annum on the unpaid principal balance. The department may forgive that portion of that loan that is used to cover costs of developing child care facilities. The department shall require annual loan payments in the minimum amount necessary to cover the costs of project monitoring. For the first 30 years of the loan term, the amount of the required loan payments shall not exceed forty-two hundredths of 1 percent (.42%) per annum.
(d)The department may establish maximum loan-to-value requirements for some or all of the types of projects that are eligible for funding under this chapter.
(e)The department shall establish per-unit and per-project loan limits for all project types.
(a)Notwithstanding any other law, the department may reduce the interest rate on any loan issued by the department to a rental housing development to as low as forty-two hundredths of 1 percent per annum, or a rate determined by the department that is sufficient to cover the costs of project monitoring described in subdivision (c) of Section 50675.6 50675.6, whichever is greater, if the development meets all of the following requirements:
(1)The development will utilize low-income housing tax credits.
(2)The department determines that the loan issued by the department is not eligible to be treated as debt for federal or state low-income housing tax credit purposes without a reduction in the interest rate of the loan. The department may require a third-party tax professional to verify this determination, the cost of which shall be borne by the sponsor.
(3)The change in the interest rate will increase the feasibility of the proposed project and will further the goals and purpose of the department and the appropriate loan program.
(4)The new department loan shall not be used to supplant or replace an existing department loan.
(b)The department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate published by the United States Internal Revenue Service and in effect at the time of the project closing. The additional tax credit equity generated by the change in interest rate shall be used for rehabilitation of the development. If the total amount of debt and accrued interest at the end of the loan term would be greater after making this change than it would have been under the original interest rate, the department may forgive an amount of accrued interest equal to the lesser of either the amount necessary to make the expected principal and accrued interest the same as it would have been using the original interest rate, or the total amount of interest accrued at the time of the sponsors request.
(c)The department may charge a fee in an amount sufficient to cover administrative costs associated with a loan modification requested by a borrower pursuant to this section.
(d)The amendments made to this section by Assembly Bill 2562 of the 20172018 Regular Session shall not be construed to affect any interest rate reduction authorized by the department pursuant to this section as it read prior to the effective date of these amendments.
SEC. 2.Section 50675.6 of the Health and Safety Code is amended to read:50675.6.(a) A sponsor may apply for loans for one or more rental or transitional housing developments. A housing development may utilize any combination of federal, state, local, and private financial resources necessary to make the development affordable, for the term of the states regulatory agreement, to the eligible households.
(b) (1) Loans made pursuant to subdivision (f) of Section 50675.7 to sponsors by a local public entity as part of its code enforcement efforts for rental housing developments involving rehabilitation shall only be for terms of not less than 20 years. All other loans shall be for a term of not less than 55 years.
(2)For loans made pursuant to this chapter, the department may approve an extension of an existing loan, the subordination of an existing loan to new debt, or an investment of tax credit equity, as long as the rental housing development is being operated in a manner consistent with the regulatory agreement and the development requires an extension in order to continue to operate in a manner consistent with this chapter. Each
(A)Each extension of an existing loan, subordination of an existing loan, or investment of tax credit equity may be made in connection with the combining of multiple sites or collateral as if the existing loan were a new loan, and shall otherwise be consistent with the departments uniform multifamily regulations (Subchapter 19 (commencing with Section 8300) of Chapter 7 of Division 1 of Title 25 of the California Code of Regulations).
(B)Each extension shall be for a period of not less than 10 years and each extension shall not exceed 55 years or, if needed to match the term of tax credit restrictions, exceed 58 years. The interest rate for the extension shall be 3 percent simple interest, or such interest rate as authorized by the department pursuant to Section 50406.7. All
(C)All loan payments shall be deferred for the full term of the loan, except for residual receipts payments. These residual receipts payments shall be structured to avoid reducing the amount of payments on local public agency loans resulting solely from changes in the payment terms on the departments loan, and not resulting from fees or other payments to the borrower, and shall otherwise be consistent with the departments uniform multifamily regulations (Subchapter 19 (commencing with Section 8300) of Chapter 7 of Division 1 of Title 25 of the California Code of Regulations) or successor regulations. The department may charge a transaction fee to cover its costs for processing such these restructuring transactions. The department may waive or defer some or all of this fee, if it determines that a particular development or class of developments does not have the ability to make these payments.
(c) Principal and accumulated interest is due and payable upon completion of the term of the loan. The loan shall bear simple interest at the rate of 3 percent per annum on the unpaid principal balance. The department may forgive that portion of that loan that is used to cover costs of developing child care facilities. The department shall require annual loan payments in the minimum amount necessary to cover the costs of project monitoring. For the first 30 years of the loan term, the amount of the required loan payments shall not exceed forty-two hundredths of 1 percent (.42%) per annum.
(d) The department may establish maximum loan-to-value requirements for some or all of the types of projects that are eligible for funding under this chapter.
(e) The department shall establish per-unit and per-project loan limits for all project types.
(a)Notwithstanding any other law, the department may reduce the interest rate on any loan issued by the department to a rental housing development to a rate determined by the department that is sufficient to cover the costs of project monitoring described in subdivision (c) of Section 50675.6 if the development meets all of the following requirements:
(1)The development will utilize low-income housing tax credits.
(2)The department determines that the loan issued by the department is not eligible to be treated as debt for federal or state low-income housing tax credit purposes without a reduction in the interest rate of the loan. The department may require a third-party tax professional to verify this determination, the cost of which shall be borne by the sponsor.
(3)The change in the interest rate will increase the feasibility of the proposed project and will further the goals and purpose of the department and the appropriate loan program.
(4)The new department loan shall not be used to supplant or replace an existing department loan.
(b)The department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate published by the United States Internal Revenue Service and in effect at the time of the project closing. The additional tax credit equity generated by the change in interest rate shall be used for rehabilitation of the development. If the total amount of debt and accrued interest at the end of the loan term would be greater after making this change than it would have been under the original interest rate, the department may forgive an amount of accrued interest equal to the lesser of either the amount necessary to make the expected principal and accrued interest the same as it would have been using the original interest rate, or the total amount of interest accrued at the time of the sponsors request.
(c)The department shall may charge a fee in an amount sufficient to cover administrative costs associated with a loan modification requested by a borrower pursuant to this section.
(d)The amendments made to this section by Assembly Bill 2562 of the 20172018 Regular Session shall not be construed to affect any interest rate reduction authorized by the department pursuant to this section as it read prior to the effective date of these amendments.
(a)Notwithstanding any other law, the department may reduce the interest rate on any loan issued by the department to a rental housing development to as low as forty-two hundredths of 1 percent per annum, or a rate determined by the department that is sufficient to cover the costs of project monitoring described in subdivision (c) of Section 50675.6, whichever is greater, 50675.6 if the development meets all of the following requirements:
(1)The development will utilize low-income housing tax credits.
(2)The department determines that the loan issued by the department is not eligible to be treated as debt for federal or state low-income housing tax credit purposes without a reduction in the interest rate of the loan. The determination must be acceptable to the department. The department may require a third-party tax professional to verify this determination, the cost of which shall be borne by the sponsor.
(3)The change in the interest rate will increase the feasibility of the proposed project and will further the goals and purpose of the department and the appropriate loan program.
(4)The new department loan shall not be used to supplant or replace an existing department loan.
(b)The department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate published by the United States Internal Revenue Service and in effect at the time of the loan extension and project closing. The additional tax credit equity generated by the change in interest rate shall be used for rehabilitation of the development. If the total amount of debt and accrued interest at the end of the loan term would be greater after making this change than it would have been under the original interest rate, the department may forgive an amount of accrued interest equal to the lesser of either the amount necessary to make the expected principal and accrued interest the same as it would have been using the original interest rate, or the total amount of interest accrued at the time of the sponsors request.
(c)The department shall charge a fee in an amount sufficient to cover administrative costs associated with a loan modification requested by a borrower pursuant to this section.
(d)The amendments made to this section by Assembly Bill 2562 of the 20172018 Regular Session shall not be construed to affect any interest rate reduction authorized by the department pursuant to this section as it read prior to the effective date of these amendments.
(a)Notwithstanding any other law, the department is authorized to may reduce the interest rate on any loan issued by the department to a rental housing development to as low as forty-two hundredths of 1 percent per annum, or a rate determined by the department that is sufficient to cover the costs of project monitoring described in subdivision (c) of Section 50675.6, whichever is greater, if the development meets all of the following requirements:
(1)The development has no other debt with regularly scheduled or amortizing debt service payments. The department reserves the right to impose a default interest rate of 3 percent should amortizing debt be placed on the project.(2)(1)The development will utilize low-income housing tax credits.
(3)(2)The sponsor department determines that the loan issued by the department is not eligible to be treated as debt for federal or state low-income housing tax credit purposes without a reduction in the interest rate of the loan. The determination must be acceptable to the department. The department may contract with require a third-party tax professional for verification, to verify this determination, the cost of which shall be borne by the sponsor.
(4)The development has no debt in a senior lien position to the departments debt.(5)The development has 35 percent or more of the total units in the project serving households with income not exceeding 30 percent of the area median income.(3)The change in the interest rate will increase the feasibility of the proposed project and will further the goals and purpose of the department and the appropriate loan program.
(6)(4)The new department loan shall not be used to supplant or replace an existing department loan.
(b)The department is authorized to change the current interest rate for any loan issued by the department for which it receives a loan extension request associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate most recently published by the United States Internal Revenue Service. Service and in effect at the time of the loan extension and project closing. The additional tax credit equity generated by the change in interest rate shall be used for rehabilitation of the development. If the total amount of debt and accrued interest at the end of the loan term would be greater after making this change than it would have been under the original interest rate, the department may forgive an amount of accrued interest equal to the lesser of either the amount necessary to make the expected principal and accrued interest the same as it would have been using the original interest rate, or the total amount of interest accrued at the time of the sponsors request.
(c)The department shall charge a fee in an amount sufficient to cover administrative costs associated with a loan modification requested by a borrower pursuant to this section.
|
Date
|
Status
|
|---|---|
| Sep 26, 2018 | Chaptered by Secretary of State - Chapter 765, Statutes of 2018. |
| Sep 26, 2018 | Approved by the Governor. |
| Sep 7, 2018 | Enrolled and presented to the Governor at 2:30 p.m. |
| Aug 29, 2018 | Senate amendments concurred in. To Engrossing and Enrolling. |
| Aug 27, 2018 | In Assembly. Concurrence in Senate amendments pending. May be considered on or after August 29 pursuant to Assembly Rule 77. |
| Aug 27, 2018 | Read third time. Passed. Ordered to the Assembly. |
| Aug 23, 2018 | Read second time. Ordered to third reading. |
| Aug 22, 2018 | Read third time and amended. Ordered to second reading. |
| Aug 20, 2018 | Read second time. Ordered to third reading. |
| Aug 17, 2018 | From committee: Amend, and do pass as amended. (Ayes 5. Noes 2.) (August 16). |
| Aug 6, 2018 | In committee: Referred to APPR. suspense file. |
| Jun 27, 2018 | From committee: Do pass and re-refer to Com. on APPR. (Ayes 9. Noes 3.) (June 26). Re-referred to Com. on APPR. |
| Jun 18, 2018 | From committee chair, with author's amendments: Amend, and re-refer to committee. Read second time, amended, and re-referred to Com. on T. & H. |
| Jun 12, 2018 | In committee: Hearing postponed by committee. |
| Jun 11, 2018 | From committee chair, with author's amendments: Amend, and re-refer to committee. Read second time, amended, and re-referred to Com. on T. & H. |
| Jun 7, 2018 | Referred to Com. on T. & H. |
| May 31, 2018 | In Senate. Read first time. To Com. on RLS. for assignment. |
| May 30, 2018 | Read third time. Passed. Ordered to the Senate. |
| May 25, 2018 | From committee: Do pass. (Ayes 12. Noes 4.) (May 25). |
| May 16, 2018 | In committee: Set, first hearing. Referred to APPR. suspense file. |
| Apr 30, 2018 | Re-referred to Com. on APPR. |
| Apr 26, 2018 | Read second time and amended. |
| Apr 25, 2018 | From committee: Amend, and do pass as amended and re-refer to Com. on APPR. (Ayes 6. Noes 1.) (April 25). |
| Mar 15, 2018 | Re-referred to Com. on H. & C.D. |
| Mar 14, 2018 | From committee chair, with author's amendments: Amend, and re-refer to Com. on H. & C.D. Read second time and amended. |
| Mar 5, 2018 | Referred to Com. on H. & C.D. |
| Feb 16, 2018 | From printer. May be heard in committee March 18. |
| Feb 15, 2018 | Read first time. To print. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Aug 29, 2018 | AB 2562 MULLIN Concurrence in Senate Amendments | Assembly Floor |
Passed |
|
| Aug 27, 2018 | Assembly 3rd Reading AB2562 Mullin et al. By Wiener | Senate Floor |
Passed |
|
| Aug 16, 2018 | Do pass as amended | Senate Standing Committee on Appropriations |
Passed |
|
| Aug 6, 2018 | Placed on suspense file | Senate Standing Committee on Appropriations |
Passed |
|
| Jun 26, 2018 | Do pass, but first be re-referred to the Committee on [Appropriations] | Senate Standing Committee on Transportation and Housing |
Passed |
|
| May 30, 2018 | AB 2562 MULLIN Assembly Third Reading | Assembly Floor |
Passed |
|
| May 25, 2018 | Do pass. | Assembly Standing Committee on Appropriations |
Passed |
|
| Apr 25, 2018 | Do pass as amended and be re-referred to the Committee on [Appropriations] | Assembly Standing Committee on Housing and Community Development |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| City of San Jose | ** Support | Aug 23, 2018 |
| Corporation For Supportive Housing | ** Support | Aug 23, 2018 |
| LeadingAge California | ** Support | Aug 23, 2018 |
| Non Profit Housing Association of Northern California | * Support | Apr 25, 2018 |
| Non-Profit Housing Association of Northern California | ** Support | Aug 23, 2018 |
CONCURRENCE IN SENATE AMENDMENTS
CSA1 Bill Id:AB 2562
Author:(Mullin)
As Amended Ver:August 22, 2018
Majority vote
ASSEMBLY: | 54-24 | (May 30, 2018) | SENATE: | 27-12 | (August 27, 2018) |
Original Committee Reference: H. & C.D.
SUMMARY: Authorizes the Department of Housing and Community Development (HCD) to change interest rates on loans issued to low-income rental housing projects. Specifically, this bill:
- Revises the conditions a rental housing development must meet in order for HCD to reduce the interest rate on its loan, as follows:
- Eliminates the requirement that the development have no other debt with regularly scheduled or amortizing debt service payments.
- Provides that HCD (rather than the sponsor) must determine if the loan is eligible to be treated as debt for federal or state low income housing tax credit (LIHTC) purposes without a reduction in the interest rate, or if the development is not able to syndicate due to projected negative capital account balances. (A syndicated loan is one in which two or more lenders jointly provide loans for one or more borrowers on the same loan terms and the same loan agreement.) Authorizes HCD to require a third-party tax professional to verify the determination, the cost of which shall be borne by the sponsor.
- Eliminates the requirement that the development have no debt in a senior lien position to HCD's debt.
- Eliminates the requirement that the development have 35% or more of the total units in the project serving households with income at or below 30% area median income (AMI).
- Adds a requirement that the change in the interest rate will materially increase the feasibility of the proposed project and will ensure long-term affordability for residents.
- Modifies the authority for HCD to change the current interest rate pursuant to a loan extension request associated with an award of federal or state LIHTCs made on or after January 1, 2014, by specifying that HCD can use the applicable federal rate in effect at the time of the project closing rather than the most recent rate published by the IRS.
- Authorizes (rather than requires) HCD to charge a fee to cover administrative costs.
- Provides that this bill shall not affect any interest rate reduction authorized by HCD prior to this bill being enacted.
- Specifies that MHP and other multi-family loans under HCD are eligible for a loan extension, subordination of the loan to existing debt, or an investment of tax credit equity.
The Senate amendments: Specify that MHP and any other multifamily loans issued by HCD are eligible for a loan extension, subordination of the loan to existing debt, or an investment of tax credit equity.
FISCAL EFFECT: According to the Assembly Committee on Appropriations: Unknown, but significant costs to HCD to review and process loan modifications in an expedited manner. For example, if 20% of HCD's loan portfolio requested a modification, estimated annual costs are $1.7 million (General Fund) in the first year and $1.5 million ongoing for nine positions, including two attorneys, necessary to perform the work.
COMMENTS:
Background: Rental housing developments that are affordable to low- and very-low income families and individuals typically require multiple sources of construction financing. Two key sources of funding are the Multifamily Housing Program (MHP) and the Low-Income Housing Tax Credit (LIHTC). The Tax Credit Allocation Committee (TCAC) administers the LIHTC program and awards credits to qualified developers who can then sell those credits to private investors who use the credits to reduce their federal tax liability. The developer, in turn, invests the capital into the affordable housing project.
MHP provides deferred payment loans ("soft" loans) to developers for the construction of affordable housing to low and very low income residents. All loans are for fifty-five years at 3% simple interest and payments of principal and the accumulated interest are due at the end of the loan period. These deferred loans significantly lower the developer's debt service expenditures, allowing the developer to offer rents at an affordable level to lower-income households.
For such soft loans to be considered a loan and not a grant for LIHTC purposes, however, a project sponsor must be able to demonstrate some plausible set of circumstances under which it could repay the loan. Because MHP loans carry a 3% deferred interest rate, this can create a conflict for projects that receive an MHP loan, reducing the amount of federal tax credits for which such a project can qualify. In some cases, the developer would be liable for a large amount of "exit taxes" once the tax credit investor leaves the partnership after year fifteen, which could put the affordable housing at risk.
In an attempt to address this problem, AB 523 (Ammiano), Chapter 445, Statutes of 2014 gave HCD discretion in limited circumstances to reduce the interest rate on a project that receives an MHP loan and is also awarded a LIHTC. To qualify, a sponsor has to prove to the satisfaction of HCD that without the reduction in the interest rate on the MHP loan the amount of tax credit the project could qualify for would be reduced and there are no other loans on the development that require ongoing debt payments. That bill provided a minimum floor of 0.42% interest per year.
This bill also loosens requirements on development eligibility in order to allow more low-income rental housing projects receiving HCD loans, such as projects in the Affordable Housing and Sustainable Communities Program or the Veterans Housing and Homelessness Prevention Program, to qualify for this interest rate modification. Additionally, this bill permits HCD to increase interest rates on any extended HCD loans to the AFR, which may be needed to preserve project feasibility in some instances where loans are being extended for more than five years or otherwise modified.
Federal tax reform: The 2017 federal tax reform bill, the Tax Cuts and Jobs Act, lowered the corporate tax rate from 35% to 21%. As a result, the value of the LIHTC, which provides a way for corporations to offset some of their federal tax liability, has declined. Though the 2018 federal omnibus spending bill increased LIHTC allocations by 12.5%, experts estimate that the net effect of the two bills will result in a loss of about 204,000 affordable rental homes nationwide over the next decade.[1] In California specifically, the 12.5% increase is worth about $125 million annually over the four-year term of the increase, but the corporate rate change will cause a loss of $500 million per year in LIHTC value on a permanent basis. The modifications in this bill could prevent existing affordable rental housing developments that utilize LIHTC from losing their affordability, and make it easier for future projects awarded LIHTC to maintain affordability.
Analysis Prepared by: Lisa Engel / H. & C.D. / (916) 319-2085 FN: 0004951
Michael Novogradac and Peter Lawrence, “How Many Jobs, Affordable Rental Homes Each State Would Gain Under FY 2018 Omnibus?,” Novogradac & Company, Notes from Novogradac (blog), April 4, 2018. ↑
Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | AB |
THIRD READING
Bill No: AB 2562
: 8/22/18
SENATE TRANS. & HOUSING COMMITTEE: 9-3, 6/26/18
AYES: Beall, Cannella, Allen, Dodd, Galgiani, McGuire, Roth, Skinner, Wiener
NOES: Gaines, Morrell, Vidak
NO VOTE RECORDED: Wieckowski
SENATE APPROPRIATIONS COMMITTEE: 5-2, 8/16/18
AYES: Portantino, Beall, Bradford, Hill, Wiener
NOES: Bates, Nielsen
ASSEMBLY FLOOR: 54-24, 5/30/18 - See last page for vote
DIGEST:
This bill authorizes the state Department of Housing and Community Development (HCD) to adjust interest rates on loans issued to low-income rental housing projects and to provide flexibility on refinancing certain project loans.
Senate Floor Amendments of 8/22/18 remove a provision authorizing each extension of an existing loan, subordination of an existing loan, or investment of tax credit equity under the Multifamily Housing Program (MHP) to be made in connection with the combining of multiple sites or collateral as if the existing loan were a new loan.
Existing law:
- Creates the state low income housing tax credit (LIHTC) program within the Tax Credit Allocation Committee (TCAC) in the State Treasurer’s Office. TCAC administers state LIHTCs to augment federal LIHTCs.
- Authorizes HCD to reduce the interest rate on any loan it issues to a rental housing development to as low as 0.42% per year, or a rate determined by HCD that is sufficient to cover the costs of project monitoring, whichever is greater, if the development meets all of the following requirements:
- The development has no other debt with regularly scheduled or amortizing debt service payments. HCD may impose a default interest rate of 3% should amortizing debt be placed on the project.
- The development will utilize LIHTCs.
- The sponsor determines that the loan issued by HCD is not eligible to be treated as debt for federal or state LIHTC purposes without a reduction in the interest rate of the loan. The determination must be acceptable to HCD, who may contract with a third-party tax professional for verification, the cost of which shall be borne by the sponsor.
- The development has no debt in a senior lien position to HCD’s debt.
- The development has 35% or more of the total units in the project serving households with income not exceeding 30% of area median income.
- The new HCD loan shall not be used to supplant or replace an existing HCD loan.
- Authorizes HCD to change the current interest rate for any loan for which it receives a loan extension request associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate most recently published by the Internal Revenue Service.
- Requires HCD to charge a fee to cover administrative costs.
- Authorizes a sponsor to apply for loans for rental or transitional housing developments under MHP.
- Authorizes HCD to approve an extension of an existing MHP loan, the subordination of an existing loan to new debt, or an investment of tax credit equity under specified circumstances. Requires all MHP loan payments to be deferred for the full term of the loan, except for residual receipts payments, which shall be structured to avoid reducing the amount of payments on local public agency loans as specified.
- Authorizes HCD to charge a transaction fee to cover its restructuring costs, though it may waive the fee if it determines that a particular development does not have the ability to make these payments.
- Authorizes a sponsor to apply for MHP loans for loans for one or more rental or transitional housing developments, as specified.
This bill:
- Revises the conditions a rental housing development must meet in order for HCD to reduce the interest rate on its loan, as follows:
- Eliminates the requirement that the development have no other debt with regularly scheduled or amortizing debt service payments.
- Provides that HCD (rather than the sponsor) must determine if the loan is eligible to be treated as debt for federal or state LIHTC purposes without a reduction in the interest rate, or if the development is not able to syndicate due to projected negative capital account balances. (A syndicated loan is one in which two or more lenders jointly provide loans for one or more borrowers on the same loan terms and the same loan agreement.) Authorizes HCD to require a third-party tax professional to verify the determination, the cost of which shall be borne by the sponsor.
- Eliminates the requirement that the development have no debt in a senior lien position to HCD’s debt.
- Eliminates the requirement that the development have 35% or more of the total units in the project serving households with income at or below 30% AMI.
- Adds a requirement that the change in the interest rate will materially increase the feasibility of the proposed project and will ensure long-term affordability for residents.
- Modifies the authority for HCD to change the current interest rate pursuant to a loan extension request associated with an award of federal or state LIHTCs made on or after January 1, 2014, by specifying that HCD can use the applicable federal rate in effect at the time of the project closing rather than the most recent rate published by the IRS.
- Authorizes (rather than requires) HCD to charge a fee to cover administrative costs.
- Provides that this bill shall not affect any interest rate reduction authorized by HCD prior to this bill being enacted.
- Specifies that MHP and other multifamily loans under HCD are eligible for a loan extension, subordination of the loan to existing debt, or an investment of tax credit equity.
Background
The LIHTC is an indirect federal subsidy developed in 1986 to incentivize the private development of affordable rental housing for low-income households. The federal LIHTC program enables low-income housing sponsors and developers to raise project equity through the allocation of tax benefits to investors. TCAC administers the program and awards credits to qualified developers, who can then sell those credits to private investors who use the credits to reduce their federal tax liability. The developer in turn invests the capital into the affordable housing project. In 1987, the Legislature authorized a state LIHTC program to augment the federal program. State tax credits can only be awarded to projects that have also received, or are concurrently receiving, an allocation of the federal LIHTCs.
The 2017 federal tax reform bill, the Tax Cuts and Jobs Act, lowered the corporate tax rate from 35% to 21%. As a result, the value of the LIHTC, which provides a way for corporations to offset some of their federal tax liability, has declined. Though the 2018 federal omnibus spending bill increased LIHTC allocations by 12.5%, experts estimate that the net effect of the two bills will result in a loss of about 204,000 affordable rental homes nationwide over the next decade. In California specifically, the 12.5% increase is worth about $125 million annually over the four-year term of the increase, but the corporate rate change will cause a loss of $500 million per year in LIHTC value on a permanent basis. The modifications in this bill could prevent existing affordable rental housing developments that utilize LIHTCs from losing their affordability and make it easier for future projects awarded LIHTCs to maintain affordability.
Comments
- Purpose. The author states that federal LIHTCs are the backbone of affordable housing finance in California. This bill grants HCD broad authority to adjust interest rates on MHP loans that utilize LIHTCs in order to make affordable housing projects feasible. The author states that local public agencies have been adjusting their interest rates for years to make affordable projects feasible; this bill will provide flexibility at the state level as well. This flexibility can result in more equity leveraged from tax credit investors to pay for affordable housing.
- MHP and LIHTC. HCD’s loans for affordable rental housing are “soft” loans, meaning that most principal and interest payments are deferred to the end of the loan term rather than being due on a monthly basis. MHP provides deferred payment loans to developers for the construction of affordable housing for low- and very low-income individuals; lowering the developer’s debt service expenditures enables the developer to offer lower rents. For these loans to be considered a loan rather than a grant for LIHTC purposes, a project sponsor must be able to demonstrate how it could plausibly repay the loan. Because MHP loans carried a 3% deferred interest rate, it sometimes created conflicts for projects that received an MHP loan, reducing the amount of federal LIHTCs for which the project could qualify.
In addition, to receive the benefits of the federal LIHTC, owners of qualifying rental housing must maintain compliance with low-income occupancy requirements for a minimum of 15 years. Once the 15-year compliance period is complete, an investor typically no longer has an economic interest in the investment and wants to dispose of it. In some cases, this left the developer liable for a large amount of “exit taxes,” potentially putting the development at risk.
To address these issues, AB 523 (Ammiano, 2014) authorized HCD to, in limited circumstances, reduce the interest rate on a project that receives an MHP loan and is also awarded an LIHTC. To qualify, a sponsor has to demonstrate to HCD that without the reduction in interest rate on the MHP loan, the amount of tax credit the project could qualify for would be reduced and there are no other loans on the development that require ongoing payments. This bill provides additional flexibility in the circumstances under which HCD may adjust the interest rate on an MHP loan.
- Recent amendments. This bill was amended in the Senate Appropriations Committee to specify that MHP and any other multifamily loans to the programs issued by HCD are eligible for a loan extension, subordination of the loan to existing debt, or an investment of tax credit equity. It was further amended on the Senate Floor to remove a provision relating to combining MHP loans with other loans, due to technical implementation concerns.
Related/Prior Legislation
AB 523 (Ammiano, Chapter 445, Statutes of 2014) allowed HCD to reduce the interest rate on any loan it has issued to a rental housing development under specified conditions.
FISCAL EFFECT: Appropriation: Fiscal Com.: Local:
According to the Senate Appropriations Committee:
- HCD estimates administrative costs of approximately $1.2 million annually beginning in 2019-20 to perform loan modifications on existing loans, assuming 17 scattered-site re-syndication requests are received annually. HCD assumes that the vast majority of loan modifications would occur during initial project development. (Various funds, primarily Housing Rehabilitation Loan Fund).
- Unknown, significant loss of interest revenues, the proceeds of which are used to fund HCD loan administration costs and future loans (various funds, primarily Housing Rehabilitation Loan Fund). For each $1 million in loan proceeds for which the simple interest rate is reduced from 3% to 0%, there would be a loss of $1.65 million over the life of a 55-year loan ($30,000 per year).
- Unknown loss of revenues as a result of the provision that provides HCD with discretion to charge an administrative fee for loan modifications, rather than requiring the fee. (Various funds, primarily Housing Rehabilitation Loan Fund).
- Unknown future impacts as a result of provisions that allow HCD loans to be subordinate to other debt on developments. These provisions constitute a risk to future HCD debt repayments in the event of a default. (Various funds, primarily Housing Rehabilitation Loan Fund)
City of San Jose
Corporation for Supportive Housing
LeadingAge California
Non-Profit Housing Association of Northern California
OPPOSITION: (Verified 8/23/18)
None received
ARGUMENTS IN SUPPORT: The Non-Profit Housing Association of Northern California states that this bill will support continued development of affordable housing despite federal disinvestment, result in more affordable homes by ensuring financial feasibility and compatibility of state and federal funding resources, and provide the state with an effective tool and flexibility to ensure that affordable homes get built.
ASSEMBLY FLOOR: 54-24, 5/30/18
AYES: Aguiar-Curry, Arambula, Berman, Bloom, Bonta, Burke, Caballero, Calderon, Carrillo, Cervantes, Chau, Chiu, Chu, Cooley, Cooper, Daly, Eggman, Frazier, Friedman, Cristina Garcia, Eduardo Garcia, Gipson, Gloria, Gonzalez Fletcher, Gray, Grayson, Holden, Irwin, Jones-Sawyer, Kalra, Kamlager-Dove, Levine, Limón, Low, McCarty, Medina, Mullin, Muratsuchi, Nazarian, O'Donnell, Quirk, Quirk-Silva, Reyes, Rodriguez, Rubio, Salas, Santiago, Steinorth, Mark Stone, Thurmond, Ting, Weber, Wood, Rendon
NOES: Acosta, Travis Allen, Baker, Bigelow, Brough, Chávez, Chen, Choi, Cunningham, Dahle, Flora, Fong, Gallagher, Harper, Kiley, Lackey, Maienschein, Mathis, Mayes, Melendez, Obernolte, Patterson, Voepel, Waldron
8/23/18 16:04:27
**** END ****
Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | AB |
THIRD READING
Bill No: AB 2562
:
SENATE TRANS. & HOUSING COMMITTEE: 9-3, 6/26/18
AYES: Beall, Cannella, Allen, Dodd, Galgiani, McGuire, Roth, Skinner, Wiener
NOES: Gaines, Morrell, Vidak
NO VOTE RECORDED: Wieckowski
SENATE APPROPRIATIONS COMMITTEE: 5-2, 8/16/18
AYES: Portantino, Beall, Bradford, Hill, Wiener
NOES: Bates, Nielsen
ASSEMBLY FLOOR: 54-24, 5/30/18 - See last page for vote
DIGEST:
This bill authorizes the state Department of Housing and Community Development (HCD) to adjust interest rates on loans issued to low-income rental housing projects and to provide flexibility on refinancing certain project loans.
Existing law:
- Creates the state low income housing tax credit (LIHTC) program within the Tax Credit Allocation Committee (TCAC) in the State Treasurer’s Office. TCAC administers state LIHTCs to augment federal LIHTCs.
- Authorizes HCD to reduce the interest rate on any loan it issues to a rental housing development to as low as 0.42% per year, or a rate determined by HCD that is sufficient to cover the costs of project monitoring, whichever is greater, if the development meets all of the following requirements:
- The development has no other debt with regularly scheduled or amortizing debt service payments. HCD may impose a default interest rate of 3% should amortizing debt be placed on the project.
- The development will utilize LIHTCs.
- The sponsor determines that the loan issued by HCD is not eligible to be treated as debt for federal or state LIHTC purposes without a reduction in the interest rate of the loan. The determination must be acceptable to HCD, who may contract with a third-party tax professional for verification, the cost of which shall be borne by the sponsor.
- The development has no debt in a senior lien position to HCD’s debt.
- The development has 35% or more of the total units in the project serving households with income not exceeding 30% of area median income.
- The new HCD loan shall not be used to supplant or replace an existing HCD loan.
- Authorizes HCD to change the current interest rate for any loan for which it receives a loan extension request associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate most recently published by the Internal Revenue Service.
- Requires HCD to charge a fee to cover administrative costs.
- Authorizes a sponsor to apply for loans for rental or transitional housing developments under the Multifamily Housing Program (MHP).
- Authorizes HCD to approve an extension of an existing MHP loan, the subordination of an existing loan to new debt, or an investment of tax credit equity under specified circumstances. Requires all MHP loan payments to be deferred for the full term of the loan, except for residual receipts payments, which shall be structured to avoid reducing the amount of payments on local public agency loans as specified.
- Authorizes HCD to charge a transaction fee to cover its restructuring costs, though it may waive the fee if it determines that a particular development does not have the ability to make these payments.
- Authorizes a sponsor to apply for MHP loans for loans for one or more rental or transitional housing developments, as specified.
This bill:
- Revises the conditions a rental housing development must meet in order for HCD to reduce the interest rate on its loan, as follows:
- Eliminates the requirement that the development have no other debt with regularly scheduled or amortizing debt service payments.
- Provides that HCD (rather than the sponsor) must determine if the loan is eligible to be treated as debt for federal or state LIHTC purposes without a reduction in the interest rate, or if the development is not able to syndicate due to projected negative capital account balances. (A syndicated loan is one in which two or more lenders jointly provide loans for one or more borrowers on the same loan terms and the same loan agreement.) Authorizes HCD to require a third-party tax professional to verify the determination, the cost of which shall be borne by the sponsor.
- Eliminates the requirement that the development have no debt in a senior lien position to HCD’s debt.
- Eliminates the requirement that the development have 35% or more of the total units in the project serving households with income at or below 30% AMI.
- Adds a requirement that the change in the interest rate will materially increase the feasibility of the proposed project and will ensure long-term affordability for residents.
- Modifies the authority for HCD to change the current interest rate pursuant to a loan extension request associated with an award of federal or state LIHTCs made on or after January 1, 2014, by specifying that HCD can use the applicable federal rate in effect at the time of the project closing rather than the most recent rate published by the IRS.
- Authorizes (rather than requires) HCD to charge a fee to cover administrative costs.
- Provides that this bill shall not affect any interest rate reduction authorized by HCD prior to this bill being enacted.
- Specifies that MHP and other multifamily loans under HCD are eligible for a loan extension, subordination of the loan to existing debt, or an investment of tax credit equity.
- Authorizes each extension of an existing loan, subordination of an existing loan, or investment of tax credit equity under MHP to be made in connection with the combining of multiple sites or collateral as if the existing loan were a new loan.
Background
The LIHTC is an indirect federal subsidy developed in 1986 to incentivize the private development of affordable rental housing for low-income households. The federal LIHTC program enables low-income housing sponsors and developers to raise project equity through the allocation of tax benefits to investors. TCAC administers the program and awards credits to qualified developers, who can then sell those credits to private investors who use the credits to reduce their federal tax liability. The developer in turn invests the capital into the affordable housing project. In 1987, the Legislature authorized a state LIHTC program to augment the federal program. State tax credits can only be awarded to projects that have also received, or are concurrently receiving, an allocation of the federal LIHTCs.
The 2017 federal tax reform bill, the Tax Cuts and Jobs Act, lowered the corporate tax rate from 35% to 21%. As a result, the value of the LIHTC, which provides a way for corporations to offset some of their federal tax liability, has declined. Though the 2018 federal omnibus spending bill increased LIHTC allocations by 12.5%, experts estimate that the net effect of the two bills will result in a loss of about 204,000 affordable rental homes nationwide over the next decade. In California specifically, the 12.5% increase is worth about $125 million annually over the four-year term of the increase, but the corporate rate change will cause a loss of $500 million per year in LIHTC value on a permanent basis. The modifications in this bill could prevent existing affordable rental housing developments that utilize LIHTCs from losing their affordability and make it easier for future projects awarded LIHTCs to maintain affordability.
Comments
- Purpose. The author states that federal LIHTCs are the backbone of affordable housing finance in California. This bill grants HCD broad authority to adjust interest rates on MHP loans that utilize LIHTCs in order to make affordable housing projects feasible. The author states that local public agencies have been adjusting their interest rates for years to make affordable projects feasible; this bill will provide flexibility at the state level as well. This flexibility can result in more equity leveraged from tax credit investors to pay for affordable housing.
- MHP and LIHTC. HCD’s loans for affordable rental housing are “soft” loans, meaning that most principal and interest payments are deferred to the end of the loan term rather than being due on a monthly basis. MHP provides deferred payment loans to developers for the construction of affordable housing for low- and very low-income individuals; lowering the developer’s debt service expenditures enables the developer to offer lower rents. For these loans to be considered a loan rather than a grant for LIHTC purposes, a project sponsor must be able to demonstrate how it could plausibly repay the loan. Because MHP loans carried a 3% deferred interest rate, it sometimes created conflicts for projects that received an MHP loan, reducing the amount of federal LIHTCs for which the project could qualify.
In addition, to receive the benefits of the federal LIHTC, owners of qualifying rental housing must maintain compliance with low-income occupancy requirements for a minimum of 15 years. Once the 15-year compliance period is complete, an investor typically no longer has an economic interest in the investment and wants to dispose of it. In some cases, this left the developer liable for a large amount of “exit taxes,” potentially putting the development at risk.
To address these issues, AB 523 (Ammiano, 2014) authorized HCD to, in limited circumstances, reduce the interest rate on a project that receives an MHP loan and is also awarded an LIHTC. To qualify, a sponsor has to demonstrate to HCD that without the reduction in interest rate on the MHP loan, the amount of tax credit the project could qualify for would be reduced and there are no other loans on the development that require ongoing payments. This bill provides additional flexibility in the circumstances under which HCD may adjust the interest rate on an MHP loan.
- Combining project loans. The author states that although the MHP regulations allow new MHP-funded projects to be “scattered site” (e.g., affordable units located on different sites), HCD does not feel it has legal authority to back this up. As MHP loans hit their post-year 15 phase and sponsors want to refinance in order to rehabilitate and recapitalize the projects, there is an increasing need to combine smaller properties to achieve economies of scale. This bill provides explicit authority to combine old MHP deals with other projects into a scattered site during a refinancing.
- Appropriations amendments. This bill was amended in the Senate Appropriations Committee to specify that MHP and any other multifamily loans to the programs issued by HCD are eligible for a loan extension, subordination of the loan to existing debt, or an investment of tax credit equity.
Related/Prior Legislation
AB 523 (Ammiano, Chapter 445, Statutes of 2014) allowed HCD to reduce the interest rate on any loan it has issued to a rental housing development under specified conditions.
FISCAL EFFECT: Appropriation: Fiscal Com.: Local:
According to the Senate Appropriations Committee:
- HCD estimates administrative costs of approximately $1.2 million annually beginning in 2019-20 to perform loan modifications on existing loans, assuming 17 scattered-site re-syndication requests are received annually. HCD assumes that the vast majority of loan modifications would occur during initial project development. (Various funds, primarily Housing Rehabilitation Loan Fund).
- Unknown, significant loss of interest revenues, the proceeds of which are used to fund HCD loan administration costs and future loans (various funds, primarily Housing Rehabilitation Loan Fund). For each $1 million in loan proceeds for which the simple interest rate is reduced from 3% to 0%, there would be a loss of $1.65 million over the life of a 55-year loan ($30,000 per year).
- Unknown loss of revenues as a result of the provision that provides HCD with discretion to charge an administrative fee for loan modifications, rather than requiring the fee. (Various funds, primarily Housing Rehabilitation Loan Fund).
- Unknown future impacts as a result of provisions that allow HCD loans to be subordinate to other debt on developments. These provisions constitute a risk to future HCD debt repayments in the event of a default. (Various funds, primarily Housing Rehabilitation Loan Fund)
City of San Jose
Corporation for Supportive Housing
LeadingAge California
Non-Profit Housing Association of Northern California
OPPOSITION: (Verified 8/16/18)
None received
ARGUMENTS IN SUPPORT: The Non-Profit Housing Association of Northern California states that this bill will support continued development of affordable housing despite federal disinvestment, result in more affordable homes by ensuring financial feasibility and compatibility of state and federal funding resources, and provide the state with an effective tool and flexibility to ensure that affordable homes get built.
ASSEMBLY FLOOR: 54-24, 5/30/18
AYES: Aguiar-Curry, Arambula, Berman, Bloom, Bonta, Burke, Caballero, Calderon, Carrillo, Cervantes, Chau, Chiu, Chu, Cooley, Cooper, Daly, Eggman, Frazier, Friedman, Cristina Garcia, Eduardo Garcia, Gipson, Gloria, Gonzalez Fletcher, Gray, Grayson, Holden, Irwin, Jones-Sawyer, Kalra, Kamlager-Dove, Levine, Limón, Low, McCarty, Medina, Mullin, Muratsuchi, Nazarian, O'Donnell, Quirk, Quirk-Silva, Reyes, Rodriguez, Rubio, Salas, Santiago, Steinorth, Mark Stone, Thurmond, Ting, Weber, Wood, Rendon
NOES: Acosta, Travis Allen, Baker, Bigelow, Brough, Chávez, Chen, Choi, Cunningham, Dahle, Flora, Fong, Gallagher, Harper, Kiley, Lackey, Maienschein, Mathis, Mayes, Melendez, Obernolte, Patterson, Voepel, Waldron
8/19/18 13:34:16
**** END ****
SENATE COMMITTEE ON APPROPRIATIONS
Senator Anthony Portantino, Chair
2017 - 2018 Regular Session
AB 2562 (Mullin) - Department of Housing and Community Development loans
Version: June 18, 2018 | Policy Vote: T. & H. 9 - 3 |
Urgency: No | Mandate: No |
Hearing Date: August 16, 2018 | Consultant: Mark McKenzie |
Bill Summary:
AB 2562 would require the Department of Housing and Community Development (HCD) to adjust interest rates on loans issued to low-income rental housing projects under specified conditions, and to provide flexibility on refinancing certain project loans, as specified.
*********** ANALYSIS ADDENDUM – SUSPENSE FILE ***********
The following information is revised to reflect amendments
adopted by the committee on August 16, 2018
Fiscal Impact:
- HCD estimates administrative costs of approximately $1.2 million annually beginning in 2019-20 to perform loan modifications on existing loans, assuming 17 scattered-site re-syndication requests are received annually. The department assumes that the vast majority of loan modifications would occur during initial project development. (various funds, primarily Housing Rehabilitation Loan Fund).
- Unknown, significant loss of interest revenues, the proceeds of which are used to fund HCD loan administration costs and future loans (various funds, primarily Housing Rehabilitation Loan Fund). For each $1 million in loan proceeds for which the simple interest rate is reduced from 3% to 0%, there would be a loss of $1.65 million over the life of a 55-year loan ($30,000 per year).
- Unknown loss of revenues as a result of the provision that provides HCD with discretion to charge an administrative fee for loan modifications, rather than requiring the fee. (various funds, primarily Housing Rehabilitation Loan Fund).
- Unknown future impacts as a result of provisions that allow HCD loans to be subordinate to other debt on developments. These provisions constitute a risk to future HCD debt repayments in the event of a default. (various funds, primarily Housing Rehabilitation Loan Fund)
Author Amendments:
Specify that loans under the Multifamily Housing Program and any other multifamily housing loans issued and monitored by HCD are eligible for a loan extension, subordination of the loan to existing debt, or an investment of tax credit equity.
-- END --
SENATE COMMITTEE ON APPROPRIATIONS
Senator Anthony Portantino, Chair
2017 - 2018 Regular Session
AB 2562 (Mullin) - Department of Housing and Community Development loans
Version: June 18, 2018 | Policy Vote: T. & H. 9 - 3 |
Urgency: No | Mandate: No |
Hearing Date: August 6, 2018 | Consultant: Mark McKenzie |
This bill meets the criteria for referral to the Suspense File.
Bill Summary:
AB 2562 would require the Department of Housing and Community Development (HCD) to adjust interest rates on loans issued to low-income rental housing projects under specified conditions, and to provide flexibility on refinancing certain project loans, as specified.
Fiscal Impact:
- HCD estimates administrative costs of approximately $1.2 million annually beginning in 2019-20 to perform loan modifications on existing loans, assuming 17 scattered-site re-syndication requests are received annually. The department assumes that the vast majority of loan modifications would occur during initial project development. (various funds, primarily Housing Rehabilitation Loan Fund).
- Unknown, significant loss of interest revenues, the proceeds of which are used to fund HCD loan administration costs and future loans (various funds, primarily Housing Rehabilitation Loan Fund). For each $1 million in loan proceeds for which the simple interest rate is reduced from 3% to 0%, there would be a loss of $1.65 million over the life of a 55-year loan ($30,000 per year).
- Unknown loss of revenues as a result of the provision that provides HCD with discretion to charge an administrative fee for loan modifications, rather than requiring the fee. (various funds, primarily Housing Rehabilitation Loan Fund).
- Unknown future impacts as a result of provisions that allow HCD loans to be subordinate to other debt on developments. These provisions constitute a risk to future HCD debt repayments in the event of a default. (various funds, primarily Housing Rehabilitation Loan Fund)
Background:
HCD administers several programs that provide loans to developers of affordable rental housing. HCD provides deferred payment loans under the Multifamily Housing Program (MHP) for the acquisition, construction, or rehabilitation of housing affordable to low and very-low income families and individuals. MHP loans have a term of not less than 55 years at a 3% simple interest rate, and principle and interest payments are deferred until loan maturity, although HCD collects residual payments to cover costs of administering the loan.
Existing law authorizes HCD to reduce the interest rate on any loan it issues to a rental housing development to as low as 0.42% per year, or a rate determined by HCD that is sufficient to cover the costs of project monitoring, whichever is greater, if the development meets specified requirements. The development cannot have other debt with regular debt service payments, or debt in a senior lien position to the HCD loan. Existing law authorizes HCD to approve an extension of an existing MHP loan, the subordination of an existing loan to new debt, or an investment of tax credit equity under specified circumstances.
Federal law establishes the Low-Income Housing Tax Credit Program, which is administered in this state by the California Tax Credit Committee (TCAC) in conjunction with a State Low-Income Housing Tax Credit Program. Federal law counts towards the “eligible basis” on which the credit is based, development costs supported by debt but not those supported by a grant. In addition, federal tax law defines as debt only those amounts that the developer can reasonably expect to repay by the end of the loan term. To do this, developers run a “true debt” analysis showing the project could conceivably generate enough net operating income to repay all debt, typically by showing the rents that can be charged at market rate at the end of the loan term. If the debt cannot be shown to be supportable by the project after running this test, federal tax law considers the loan a grant, and the project loses an equivalent amount of tax credit basis.
In addition, when a developer seeks low-income housing tax credits to acquire and rehabilitate an existing affordable housing development, federal tax rules require that the eligible basis be reduced by the difference between the long-term cost of below-market-rate debt, such as an HCD loan, and the long-term cost of the loan assuming use of the federally determined “applicable federal rate” (AFR). When the AFR is above HCD’s rate, the developer still owes the full amount of the HCD loan but may only count a portion of it towards the eligible basis. If HCD’s rate is equal to or less than the AFR, there is no reduction in the eligible basis. Existing law allows HCD to change the interest rate on any loan for which it receives a loan extension request associated with an award of low-income housing tax credits to the applicable federal rate most recently published by the Internal Revenue Service.
Proposed Law:
AB 2562 would require, rather than authorize, HCD to reduce the interest on any loan issued to low-income rental housing developments and revise the conditions that a development must meet to qualify for a rate reduction. Specifically, this bill would:
- Delete the requirement that a development have no other debt with regularly scheduled or amortizing debt service payments.
- Delete the requirement that a development have no debt in a senior lien position to the HCD’s debt.
- Delete the requirement that the development have 35% or more of the total units in the project serving households with income at or below 30% of the area median income.
- Delete a provision that prohibits an HCD loan from being used to supplant or replace an existing HCD loan.
- Require HCD to determine either of the following as a condition of reducing the interest rate:
- Whether an HCD loan is eligible to be treated as debt for federal or state LIHTC purposes. (previously the project sponsor would make that determination)
- The rental housing development is not able to syndicate due to projected negative capital balances.
- Require the change in interest rate to materially increase the feasibility of the proposed project and ensure long-term affordability for the residents.
The bill would also make the following changes:
- Authorize HCD to change the current rate on a loan extension request to the applicable federal rate in effect at the time of the project closing, rather than the most recently published rate, when modifying a rate in connection with the award of state or federal LIHTCs.
- Authorize, rather than require, HCD to charge a fee to cover its administrative costs associated with a loan modification request.
- Authorize each extension of an existing loan, subordination of an existing loan, or investment of tax credit equity under MHP to be made in connection with the combining of multiple sites or collateral as if the existing loan were a new loan. (scattered-site re-syndication).
Related Legislation:
AB 523 (Ammiano), Chap. 445/2013, authorized HCD to reduce or eliminate the interest rate on loans for affordable housing developments that meet specified criteria. The bill also authorized HCD to change the interest rate and forgive accrued interest on specified loans if it receives a loan extension request associated with the award of low-income housing tax credits.
SB 77 (Leno), which died in Senate Rules Committee in 2012, was identical to the introduced version of AB 523. SB 77 was originally a budget trailer bill, but was amended in the Assembly to delete the budget-related contents and add the housing provisions. That bill was never heard in a policy committee.
Staff Comments:
This bill is intended to expand the availability of affordable rental housing by allowing a reduced interest rate when it makes the difference in terms of a project passing the “true debt” tests in federal law, to maximize the amount of low-income housing tax credits that may be claimed.
HCD assumes that most requests for loan modifications would occur during initial project development, and attributes most of its administrative costs to requests for scattered-site re-syndications of MHP loans. The department estimates there will be 17 such requests annually. HCD’s ongoing monitoring activities related to a particular loan are paid for out of the residual simple interest that is collected, which is the equivalent of 0.42% interest rate. Staff notes that any reduction of interest below that amount would have to be paid from increased collection of residual interest on other loans, where it is authorized.
This bill would create future cost pressures to increase funding for affordable housing loan programs to the extent that reduced interest payments from interest reductions significantly reduces the amount of program funding available for future loans. Reductions in interest payments that would otherwise be used to capitalize new loans inhibit the ability of HCD to maintain programs at current levels.
-- END --
SENATE COMMITTEE ON TRANSPORTATION AND HOUSING
Senator Jim Beall, Chair
2017 - 2018 Regular
Bill No: AB 2562 Hearing Date: 6/26/2018
Author: | Mullin | ||
Version: | 6/18/2018 Amended | ||
Urgency: | No | Fiscal: | Yes |
Consultant: | Erin Riches | ||
SUBJECT: Department of Housing and Community Development loans
DIGEST: This bill authorizes the state Department of Housing and Community Development (HCD) to adjust interest rates on loans issued to low-income rental housing projects and to provide flexibility on refinancing certain project loans.
ANALYSIS:
Existing law:
- Creates the state low income housing tax credit (LIHTC) program within the Tax Credit Allocation Committee (TCAC) in the State Treasurer’s Office. TCAC administers state LIHTCs to augment federal LIHTCs.
- Authorizes HCD to reduce the interest rate on any loan it issues to a rental housing development to as low as 0.42% per year, or a rate determined by HCD that is sufficient to cover the costs of project monitoring, whichever is greater, if the development meets all of the following requirements:
- The development has no other debt with regularly scheduled or amortizing debt service payments. HCD may impose a default interest rate of 3% should amortizing debt be placed on the project.
- The development will utilize LIHTCs.
- The sponsor determines that the loan issued by HCD is not eligible to be treated as debt for federal or state LIHTC purposes without a reduction in the interest rate of the loan. The determination must be acceptable to HCD, who may contract with a third-party tax professional for verification, the cost of which shall be borne by the sponsor.
- The development has no debt in a senior lien position to HCD’s debt.
- The development has 35% or more of the total units in the project serving households with income not exceeding 30% of area median income.
- The new HCD loan shall not be used to supplant or replace an existing HCD loan.
- Authorizes HCD to change the current interest rate for any loan for which it receives a loan extension request associated with an award of federal or state low-income housing tax credits made on or after January 1, 2014, to the applicable federal rate most recently published by the Internal Revenue Service.
- Requires HCD to charge a fee to cover administrative costs.
- Authorizes a sponsor to apply for loans for rental or transitional housing developments under the Multifamily Housing Program (MHP).
- Authorizes HCD to approve an extension of an existing MHP loan, the subordination of an existing loan to new debt, or an investment of tax credit equity under specified circumstances. Requires all MHP loan payments to be deferred for the full term of the loan, except for residual receipts payments, which shall be structured to avoid reducing the amount of payments on local public agency loans as specified.
- Authorizes HCD to charge a transaction fee to cover its restructuring costs, though it may waive the fee if it determines that a particular development does not have the ability to make these payments.
- Authorizes a sponsor to apply for MHP loans for loans for one or more rental or transitional housing developments, as specified.
This bill:
- Revises the conditions a rental housing development must meet in order for HCD to reduce the interest rate on its loan, as follows:
- Eliminates the requirement that the development have no other debt with regularly scheduled or amortizing debt service payments.
- Provides that HCD (rather than the sponsor) must determine if the loan is eligible to be treated as debt for federal or state LIHTC purposes without a reduction in the interest rate, or if the development is not able to syndicate due to projected negative capital account balances. (A syndicated loan is one in which two or more lenders jointly provide loans for one or more borrowers on the same loan terms and the same loan agreement.) Authorizes HCD to require a third-party tax professional to verify the determination, the cost of which shall be borne by the sponsor.
- Eliminates the requirement that the development have no debt in a senior lien position to HCD’s debt.
- Eliminates the requirement that the development have 35% or more of the total units in the project serving households with income at or below 30% AMI.
- Adds a requirement that the change in the interest rate will materially increase the feasibility of the proposed project and will ensure long-term affordability for residents.
- Modifies the authority for HCD to change the current interest rate pursuant to a loan extension request associated with an award of federal or state LIHTCs made on or after January 1, 2014, by specifying that HCD can use the applicable federal rate in effect at the time of the project closing rather than the most recent rate published by the IRS.
- Authorizes (rather than requires) HCD to charge a fee to cover administrative costs.
- Provides that this bill shall not affect any interest rate reduction authorized by HCD prior to this bill being enacted.
- Authorizes each extension of an existing loan, subordination of an existing loan, or investment of tax credit equity under MHP to be made in connection with the combining of multiple sites or collateral as if the existing loan were a new loan.
COMMENTS
- Purpose. The author states that federal LIHTCs are the backbone of affordable housing finance in California. This bill grants HCD broad authority to adjust interest rates on MHP loans that utilize LIHTCs in order to make affordable housing projects feasible. The author states that local public agencies have been adjusting their interest rates for years to make affordable projects feasible; this bill will provide flexibility at the state level as well. This flexibility can result in more equity leveraged from tax credit investors to pay for affordable housing.
- LIHTC programs. The LIHTC is an indirect federal subsidy developed in 1986 to incentivize the private development of affordable rental housing for low-income households. The federal LIHTC program enables low-income housing sponsors and developers to raise project equity through the allocation of tax benefits to investors. TCAC administers the program and awards credits to qualified developers, who can then sell those credits to private investors who use the credits to reduce their federal tax liability. The developer in turn invests the capital into the affordable housing project. In 1987, the Legislature authorized a state LIHTC program to augment the federal program. State tax credits can only be awarded to projects that have also received, or are concurrently receiving, an allocation of the federal LIHTCs.
- MHP and LIHTC. HCD’s loans for affordable rental housing are “soft” loans, meaning that most principal and interest payments are deferred to the end of the loan term rather than being due on a monthly basis. MHP provides deferred payment loans to developers for the construction of affordable housing for low- and very low-income individuals; lowering the developer’s debt service expenditures enables the developer to offer lower rents. For these loans to be considered a loan rather than a grant for LIHTC purposes, a project sponsor must be able to demonstrate how it could plausibly repay the loan. Because MHP loans carried a 3% deferred interest rate, it sometimes created conflicts for projects that received an MHP loan, reducing the amount of federal LIHTCs for which the project could qualify.
In addition, to receive the benefits of the federal LIHTC, owners of qualifying rental housing must maintain compliance with low-income occupancy requirements for a minimum of 15 years. Once the 15-year compliance period is complete, an investor typically no longer has an economic interest in the investment and wants to dispose of it. In some cases, this left the developer liable for a large amount of “exit taxes,” potentially putting the development at risk.
To address these issues, AB 523 (Ammiano, 2014) authorized HCD to, in limited circumstances, reduce the interest rate on a project that receives an MHP loan and is also awarded an LIHTC. To qualify, a sponsor has to demonstrate to HCD that without the reduction in interest rate on the MHP loan, the amount of tax credit the project could qualify for would be reduced and there are no other loans on the development that require ongoing payments. This bill provides additional flexibility in the circumstances under which HCD may adjust the interest rate on an MHP loan.
- Combining project loans. The author states that although the MHP regulations allow new MHP-funded projects to be “scattered site” (e.g., affordable units located on different sites), HCD does not feel it has legal authority to back this up. As MHP loans hit their post-year 15 phase and sponsors want to refinance in order to rehabilitate and recapitalize the projects, there is an increasing need to combine smaller properties to achieve economies of scale. This bill provides explicit authority to combine old MHP deals with other projects into a scattered site during a refinancing.
- Federal tax reform. The 2017 federal tax reform bill, the Tax Cuts and Jobs Act, lowered the corporate tax rate from 35% to 21%. As a result, the value of the LIHTC, which provides a way for corporations to offset some of their federal tax liability, has declined. Though the 2018 federal omnibus spending bill increased LIHTC allocations by 12.5%, experts estimate that the net effect of the two bills will result in a loss of about 204,000 affordable rental homes nationwide over the next decade. In California specifically, the 12.5% increase is worth about $125 million annually over the four-year term of the increase, but the corporate rate change will cause a loss of $500 million per year in LIHTC value on a permanent basis. The modifications in this bill could prevent existing affordable rental housing developments that utilize LIHTCs from losing their affordability and make it easier for future projects awarded LIHTCs to maintain affordability.
Related Legislation:
AB 523 (Ammiano, Chapter 445, Statutes of 2014) — allowed HCD to reduce the interest rate on any loan it has issued to a rental housing development under specified conditions.
Assembly Votes:
Floor: 54-24
Approps: 12-4
H&CD: 6-1
FISCAL EFFECT: Appropriation: Fiscal Com.: Local:
POSITIONS: (Communicated to the committee before noon on Wednesday,
June 20, 2018.)
SUPPORT:
City of San Jose
Corporation for Supportive Housing
LeadingAge California
Non-Profit Housing Association of Northern California
OPPOSITION:
None received.
-- END --
ASSEMBLY THIRD READING
ATR Bill Id:AB 2562
Author:(Mullin)
As Amended Ver:April 26, 2018
Majority vote
Committee | Votes | Ayes | Noes |
Housing | 6-1 | Chiu, Maienschein, Chau, Gloria, Limón, Wood | Choi |
Appropriations | 12-4 | Gonzalez Fletcher, Bloom, Bonta, Calderon, Carrillo, Chau, Eggman, Friedman, Eduardo Garcia, Nazarian, Quirk, Reyes | Bigelow, Fong, Gallagher, Obernolte |
SUMMARY: Authorizes the Department of Housing and Community Development (HCD) to change interest rates on loans issued to low-income rental housing projects. Specifically, this bill:
- Authorizes HCD to reduce the interest rate on any loan issued to a rental housing development to a rate determined by HCD that is sufficient to cover the costs of project monitoring.
- Modifies the requirements for HCD to reduce the interest rate on a loan to such a development by:
- Repealing the requirement that the development have no other debt with regularly scheduled or amortizing debt service payments;
- Requiring HCD, rather than the sponsor, to determine that the HCD loan is not eligible to be treated as debt for federal or state low-income housing tax credit (LIHTC) purposes without a reduction in the interest rate of the loan;
- Repealing the requirement that the development have no debt in a senior lien position to HCD's debt;
- Repealing the requirement that the development have 35% or more of the total units in the project serving households with income not exceeding 30% of area median income; and
- Requiring the change in the interest rate to increase the feasibility of the proposed project and to further the goals and purpose of HCD and the appropriate loan program.
- Authorizes HCD to change the current interest rate for any HCD loan for which it receives a loan extension request associated with an award of federal or state LIHTC on or after January 1, 2014, to the applicable federal rate (AFR) published by the United States Internal Revenue Service (IRS) and in effect at the time of closing.
- Specifies that loans that have already received an interest rate reduction from HCD shall not be altered.
- Makes other minor technical changes.
FISCAL EFFECT: According to the Assembly Committee on Appropriations: Unknown, but significant costs to HCD to review and process loan modifications in an expedited manner. For example, if 20% of HCD's loan portfolio requested a modification, estimated annual costs are $1.7 million (GF) in the first year and $1.5 million ongoing for nine positions, including two attorneys, necessary to perform the work.
COMMENTS:
Background: Rental housing developments that are affordable to low- and very-low income families and individuals typically require multiple sources of construction financing. Two key sources of funding are the Multifamily Housing Program (MHP) and the Low-Income Housing Tax Credit (LIHTC). The Tax Credit Allocation Committee (TCAC) administers the LIHTC program and awards credits to qualified developers who can then sell those credits to private investors who use the credits to reduce their federal tax liability. The developer, in turn, invests the capital into the affordable housing project.
MHP provides deferred payment loans ("soft" loans) to developers for the construction of affordable housing to low and very low income residents. All loans are for 45 years at 3% simple interest and payments of principal and the accumulated interest are due at the end of the loan period. These deferred loans significantly lower the developer's debt service expenditures, allowing the developer to offer rents at an affordable level to lower-income households.
For such soft loans to be considered a loan and not a grant for LIHTC purposes, however, a project sponsor must be able to demonstrate some plausible set of circumstances under which it could repay the loan. Because MHP loans carry a 3% deferred interest rate, this can create a conflict for projects that receive an MHP loan, reducing the amount of federal tax credits for which such a project can qualify. In some cases, the developer would be liable for a large amount of "exit taxes" once the tax credit investor leaves the partnership after year 15, which could put the affordable housing at risk.
In an attempt to address this problem, AB 523 (Ammiano), Chapter 445, Statutes of 2014, gave HCD discretion in limited circumstances to reduce the interest rate on a project that receives an MHP loan and is also awarded a LIHTC. To qualify, a sponsor has to prove to the satisfaction of HCD that without the reduction in the interest rate on the MHP loan the amount of tax credit the project could qualify for would be reduced and there are no other loans on the development that require ongoing debt payments. That bill provided a minimum floor of 0.42% interest per year.
This bill removes the 0.42% minimum interest rate on loans and instead allows HCD to set any interest rate sufficient to cover project monitoring costs. This bill also loosens requirements on development eligibility in order to allow more low-income rental housing projects receiving HCD loans, such as projects in the Affordable Housing and Sustainable Communities Program or the Veterans Housing and Homelessness Prevention Program, to qualify for this interest rate modification. Additionally, this bill permits HCD to increase interest rates on any extended HCD loans to the AFR, which may be needed to preserve project feasibility in some instances where loans are being extended for more than five years or otherwise modified.
Federal tax reform: The 2017 federal tax reform bill, the Tax Cuts and Jobs Act, lowered the corporate tax rate from 35% to 21%. As a result, the value of the LIHTC, which provides a way for corporations to offset some of their federal tax liability, has declined. Though the 2018 federal omnibus spending bill increased LIHTC allocations by 12.5%, experts estimate that the net effect of the two bills will result in a loss of about 204,000 affordable rental homes nationwide over the next decade.[1] In California specifically, the 12.5% increase is worth about $125 million annually over the four-year term of the increase, but the corporate rate change will cause a loss of $500 million per year in LIHTC value on a permanent basis.[2] The modifications in this bill could prevent existing affordable rental housing developments that utilize LIHTC from losing their affordability, and make it easier for future projects awarded LIHTC to maintain affordability.
According to the author: This bill will grant HCD authority to adjust (increase or decrease) the interest rate (if requested by the project sponsor) on any loan from any program for projects that will also be using federal LIHTC to as low as 0.42% to as high as the AFR in place at the time of closing. Local public agencies have been assisting affordable housing development by being flexible in the terms of their affordable housing loans. This bill would enable HCD to provide the same kind of flexibility as local public agencies have. This flexibility will generally result in more equity leveraged from tax credit investors to pay for affordable housing.
Analysis Prepared by: Lisa Engel / H. & C.D. / (916) 319-2085 FN: 0003086
Michael Novogradac and Peter Lawrence, "How Many Jobs, Affordable Rental Homes Each State Would Gain Under FY 2018 Omnibus?," Novogradac & Company, Notes from Novogradac (blog), April 4, 2018. ↑
Matt Schwartz, "Spending Bill Increases LIHTC and Affordable Housing Funding for FY2018," California Housing Partnership Corporation, March 22, 2018. ↑
Date of Hearing: May 16, 2018
ASSEMBLY COMMITTEE ON APPROPRIATIONS
Lorena Gonzalez Fletcher, Chair
ABPCA Bill Id:AB 2562
Author:(Mullin) – As Amended Ver:April 26, 2018
Policy Committee: | Housing and Community Development | Vote: | 6 - 1 |
|
| ||
|
|
Urgency: No State Mandated Local Program: No Reimbursable: No
SUMMARY:
This bill authorizes the Department of Housing and Community Development (HCD) to change interest rates on loans issued to low-income rental housing projects. Specifically, this bill:
- Authorizes HCD to reduce the interest rate on any loan issued to a rental housing development to a rate determined by HCD that is sufficient to cover the costs of project monitoring.
- Modifies the requirements for HCD to reduce the interest rate on a loan to such a development by:
- Repealing the requirements that the development have no other debt with regularly scheduled or amortizing debt service payments and have no debt in a senior lien position to HCD’s debt.
- Requiring HCD, rather than the sponsor, to determine t the HCD loan is not eligible to be treated as debt for federal or state low-income housing tax credit (LIHTC) purposes without a reduction in the interest rate of the loan.
- Repealing the requirement that the development have 35% or more of the total units in the project serving households with income not exceeding 30% of area median income and instead requiring the change in the interest rate to increase the feasibility of the proposed project and to further the goals and purpose of HCD and the appropriate loan program.
- Authorizes HCD to change to the applicable federal rate (AFR) the current interest rate for any HCD loan for which it receives a loan extension request associated with an award of federal or state LIHTC on or after January 1, 2014. (The AFR is the applicable federal rate published by the United States Internal Revenue Service (IRS) and in effect at the time of closing.)
FISCAL EFFECT:
Unknown, but significant costs to HCD to review and process loan modifications in an expedited manner. For example, if 20% of HCD’s loan portfolio requested a modification, estimated annual costs are $1.7 million (GF) in the first year and $1.5 million ongoing for nine positions, including two attorneys, necessary to perform the work.
COMMENTS:
- Purpose. This bill seeks to improve the feasibility of affordable housing projects by granting HCD the authority to adjust (increase or decrease) the interest rate, if requested by the project sponsor, on any loan from any program for projects that will use the federal LIHTC. According to the author, “local public agencies have been assisting affordable housing development by being flexible in the terms of their affordable housing loans. AB 2562 would enable HCD to provide the same kind of flexibility as local public agencies have.”
- Background. Rental housing developments that are affordable to low- and very-low-income families and individuals typically require multiple sources of construction financing. Two key sources of such financing are the Multifamily Housing Program (MHP) and the LIHTC. The Tax Credit Allocation Committee (TCAC) administers the LIHTC program and awards credits to qualified developers who can then sell those credits to private investors who use the credits to reduce their federal tax liability. The developer, in turn, invests the capital into the affordable housing project.
In order to make multiple sources of financing work together within the federal tax framework, existing law gives HCD discretion in limited circumstances to reduce the interest rate to as low as 0.42% interest per year on a project that receives an MHP loan and is also awarded an LIHTC. To qualify, a sponsor has to prove to the satisfaction of HCD that a) without the reduction in the interest rate on the MHP loan, the amount of tax credit would be reduced, and b) there are no other loans on the development that require ongoing debt payments.
This bill removes the 0.42% minimum interest rate on loans and instead allows HCD to set any interest rate sufficient to cover project monitoring costs. This bill also loosens requirements on development eligibility to allow more low-income rental housing projects receiving HCD loans, such as projects in the Affordable Housing and Sustainable Communities Program or the Veterans Housing and Homelessness Prevention Program, to qualify for this interest rate modification. Additionally, this bill permits HCD to increase interest rates to the AFR on any extended HCD loans, which may be needed to preserve project feasibility in some instances where loans are being extended for more than five years or otherwise modified.
- Prior Legislation.
AB 523 (Ammiano), Chapter 445, Statutes of 2014, gave HCD discretion in limited circumstances to reduce the interest rate on a project that receives a MHP loan and an LIHTC.
SB 77 (Leno), of the 2011-12 Legislative Session, would have given HCD discretion in limited circumstances to reduce the interest rate to as low as 0% on a project that receives an MHP loan and an LIHTC. This bill died in the Assembly Rules Committee.
Analysis Prepared by: Jennifer Swenson / APPR. / (916) 319-2081
Date of Hearing: April 25, 2018
ASSEMBLY COMMITTEE ON HOUSING AND COMMUNITY DEVELOPMENT
David Chiu, Chair
ABPCA Bill Id:AB 2562 (
Author:Mullin) – As Amended Ver:March 14, 2018
SUBJECT: Department of Housing and Community Development loans
SUMMARY: Authorizes the Department of Housing and Community Development (HCD) to change interest rates on loans issued to low-income rental housing projects. Specifically, this bill:
- Authorizes HCD to reduce the interest rate on any loan issued to a rental housing development to a rate determined by HCD that is sufficient to cover the costs of project monitoring.
- Modifies the requirements for HCD to reduce the interest rate on a loan to such a development by:
- Repealing the requirement that the development have no other debt with regularly scheduled or amortizing debt service payments;
- Requiring HCD, rather than the sponsor, to determine that the HCD loan is not eligible to be treated as debt for federal or state low-income housing tax credit (LIHTC) purposes without a reduction in the interest rate of the loan;
- Repealing the requirement that the development have no debt in a senior lien position to HCD’s debt;
- Repealing the requirement that the development have 35% or more of the total units in the project serving households with income not exceeding 30% of area median income; and
- Requiring the change in the interest rate to increase the feasibility of the proposed project and to further the goals and purpose of HCD and the appropriate loan program.
- Authorizes HCD to change the current interest rate for any HCD loan for which it receives a loan extension request associated with an award of federal or state LIHTC on or after January 1, 2014, to the applicable federal rate (AFR) published by the United States Internal Revenue Service (IRS) and in effect at the time of closing.
- Specifies that loans that have already received an interest rate reduction from HCD shall not be altered.
- Makes other minor technical changes.
EXISTING LAW:
- Establishes the Multifamily Housing Program (MHP) to provide deferred payment loans for the acquisition, construction, or rehabilitation of housing affordable to low- and very low- income families and individuals.
- Requires MHP loans to be for a term of not less than 55 years and at 3% simple interest with payments due at the end of the term of the loan.
- Authorizes HCD to reduce the interest rate on any loan issued by the department to a rental housing development to as low as 0.42% per year, or a rate determined by HCD that is sufficient to cover the costs of project monitoring, whichever is greater, if the development meets the following requirements:
- The development has no other debt with regularly scheduled or amortizing debt service payments.
- The development will utilize LIHTCs.
- The sponsor determines that the loan issued by HCD is not eligible to be treated as debt for federal or state LIHTC purposes without a reduction in the interest rate of the loan, and HCD approves the determination.
- The development has no debt in a senior lien position to HCD’s debt.
- The development has 35% or more of the total units in the project serving households with income not exceeding 30% of area median income (AMI).
- The new HCD loan will not be used to supplant or replace an existing HCD loan.
- Authorizes HCD to change the current interest rate for any loan for which it receives a loan extension request associated with an award of federal or state LIHTCs made on or after January 1, 2014, to the AFR most recently published by the IRS. Requires the additional tax credit equity generated by the interest rate change to be used for rehabilitation of the development.
- Requires HCD to charge a fee in an amount sufficient to cover administrative costs associated with a loan modification requested by a borrower.
FISCAL EFFECT: Unknown.
COMMENTS:
Background: Rental housing developments that are affordable to low- and very-low income families and individuals typically require multiple sources of construction financing. Two key sources of funding are the Multifamily Housing Program (MHP) and the Low-Income Housing Tax Credit (LIHTC). The Tax Credit Allocation Committee (TCAC) administers the LIHTC program and awards credits to qualified developers who can then sell those credits to private investors who use the credits to reduce their federal tax liability. The developer, in turn, invests the capital into the affordable housing project.
MHP provides deferred payment loans (“soft” loans) to developers for the construction of affordable housing to low and very low income residents. All loans are for fifty-five years at 3% simple interest and payments of principal and the accumulated interest are due at the end of the loan period. These deferred loans significantly lower the developer’s debt service expenditures, allowing the developer to offer rents at an affordable level to lower-income households.
For such soft loans to be considered a loan and not a grant for LIHTC purposes, however, a project sponsor must be able to demonstrate some plausible set of circumstances under which it could repay the loan. Because MHP loans carry a 3% deferred interest rate, this can create a conflict for projects that receive an MHP loan, reducing the amount of federal tax credits for which such a project can qualify. In some cases, the developer would be liable for a large amount of “exit taxes” once the tax credit investor leaves the partnership after year fifteen, which could put the affordable housing at risk.
In an attempt to address this problem, AB 523 (Ammiano), Chapter 445, Statutes of 2014 gave HCD discretion in limited circumstances to reduce the interest rate on a project that receives an MHP loan and is also awarded a LIHTC. To qualify, a sponsor has to prove to the satisfaction of HCD that without the reduction in the interest rate on the MHP loan the amount of tax credit the project could qualify for would be reduced and there are no other loans on the development that require ongoing debt payments. That bill provided a minimum floor of 0.42% interest per year.
This bill removes the 0.42% minimum interest rate on loans and instead allows HCD to set any interest rate sufficient to cover project monitoring costs. This bill also loosens requirements on development eligibility in order to allow more low-income rental housing projects receiving HCD loans, such as projects in the Affordable Housing and Sustainable Communities Program or the Veterans Housing and Homelessness Prevention Program, to qualify for this interest rate modification. Additionally, this bill permits HCD to increase interest rates on any extended HCD loans to the AFR, which may be needed to preserve project feasibility in some instances where loans are being extended for more than five years or otherwise modified.
Federal tax reform: The 2017 federal tax reform bill, the Tax Cuts and Jobs Act, lowered the corporate tax rate from 35% to 21%. As a result, the value of the LIHTC, which provides a way for corporations to offset some of their federal tax liability, has declined. Though the 2018 federal omnibus spending bill increased LIHTC allocations by 12.5%, experts estimate that the net effect of the two bills will result in a loss of about 204,000 affordable rental homes nationwide over the next decade.[1] In California specifically, the 12.5% increase is worth about $125 million annually over the four-year term of the increase, but the corporate rate change will cause a loss of $500 million per year in LIHTC value on a permanent basis.[2] The modifications in this bill could prevent existing affordable rental housing developments that utilize LIHTC from losing their affordability, and make it easier for future projects awarded LIHTC to maintain affordability.
According to the author: This bill will grant HCD authority to adjust (increase or decrease) the interest rate (if requested by the project sponsor) on any loan from any program for projects that will also be using federal LIHTC to as low as 0.42% to as high as the AFR in place at the time of closing. Local public agencies have been assisting affordable housing development by being flexible in the terms of their affordable housing loans. AB 2562 would enable HCD to provide the same kind of flexibility as local public agencies have. This flexibility will generally result in more equity leveraged from tax credit investors to pay for affordable housing.
Committee amendment:
To better reflect the author’s intent to give HCD discretion in implementing this section, the below amendment is proposed:
- On page 3, in line 17, strike out “shall” and insert, "may"
Related legislation:
AB 523 (Ammiano), Chapter 445, Statutes of 2014: Gave HCD discretion in limited circumstances to reduce the interest rate on a project that receives an MHP loan and is also awarded a LIHTC.
SB 77 (Leno), 2012: Would have given HCD discretion in limited circumstances to reduce the interest rate to as low as 0% on a project that receives an MHP loan and is also awarded a LIHTC. This bill died in the Assembly Rules Committee.
REGISTERED SUPPORT / OPPOSITION:
Support
City of San Jose
Corporation for Supportive Housing
LeadingAge California
Non-Profit Housing Association of Northern California
Opposition
None on file
Analysis Prepared by: Nicole Restmeyer / H. & C.D. / (916) 319-2085
Michael Novogradac and Peter Lawrence, “How Many Jobs, Affordable Rental Homes Each State Would Gain Under FY 2018 Omnibus?,” Novogradac & Company, Notes from Novogradac (blog), April 4, 2018. ↑
Matt Schwartz, “Spending Bill Increases LIHTC and Affordable Housing Funding for FY2018,” California Housing Partnership Corporation, March 22, 2018. ↑
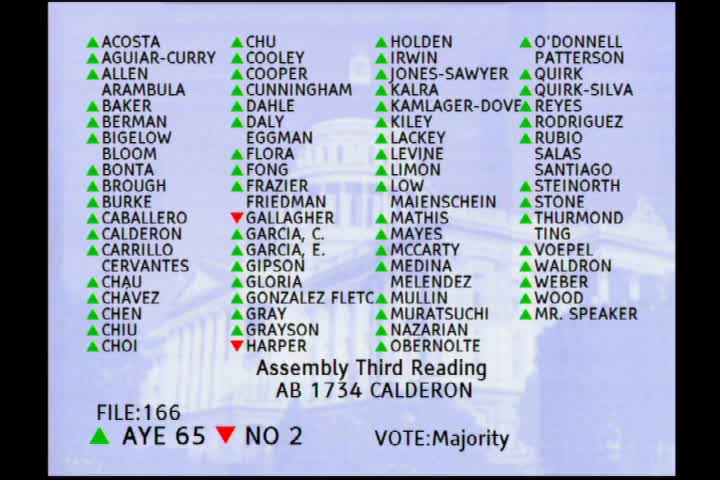
Bill Author