SB 1293: California State Auditor: high-risk local government agency audit program.
- Session Year: 2017-2018
- House: Senate
- Latest Version Date: 2018-09-18
Existing law authorizes the California State Auditor to establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency that the California State Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness. Existing law requires the California State Auditor to notify the Joint Legislative Audit Committee whenever he or she identifies a local government as at high risk. Existing law also requires that audits conducted pursuant to these provisions be approved by the Joint Legislative Audit Committee.
This bill would authorize the California State Auditor to conduct an initial assessment at a local government agency prior to conducting an audit, during which he or she may gather publicly available information from a local government agency and any additional information that the local government agency is willing to provide, for the purpose of identifying whether or not it is a high-risk local government agency. The bill would require the California State Auditor, before beginning an initial assessment at a local government agency, to notify the Joint Legislative Audit Committee in writing which local government agency will be assessed.
Existing law requires the California State Auditor, if the California State Auditor establishes the above described program and determines that a local government agency is at high risk, to issue audit reports at least once every 2 years with recommendations for improvement in the local government agency identified as at high risk.
This bill would instead require those audit reports to be issued once every 3 years.
This bill would incorporate additional changes to Section 8546.10 of the Government Code proposed by AB 2822 to be operative only if this bill and AB 2822 are enacted and this bill is enacted last.
Existing law authorizes the California State Auditor to establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency that the California State Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness. Existing law requires the California State Auditor to notify the Joint Legislative Audit Committee whenever he or she identifies a local government as at high risk. Existing law also requires that audits conducted pursuant to these provisions be approved by the Joint Legislative Audit Committee.
This bill would authorize the California State Auditor to first conduct an initial assessment, assessment at a local government agency prior to conducting an audit, during which he or she may gather publicly available information from a local government agency and any additional information that the local government agency is willing to provide, for the purpose of identifying it as whether or not it is a high-risk local government agency. The bill would require the California State Auditor, before beginning an initial assessment at a local government agency, to notify the Joint Legislative Audit Committee in writing which local government agency will be assessed.
Existing law requires the California State Auditor, if the California State Auditor establishes the above described program and determines that a local government agency is at high risk, to issue audit reports at least once every 2 years with recommendations for improvement in the local government agency identified as at high risk.
This bill would instead require those audit reports to be issued once every 3 years.
Existing law authorizes the California State Auditor to establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency that the California State Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness. Existing law requires the California State Auditor to notify the Joint Legislative Audit Committee whenever he or she identifies a local government as at high risk. Existing law also requires that audits conducted pursuant to these provisions be approved by the Joint Legislative Audit Committee.
This bill would authorize the California State Auditor to first conduct an initial assessment, during which he or she may gather information from a local government agency for the purpose of identifying it as a high-risk local government agency.
Under existing law, the Department of Parks and Recreation controls the state park system, which is made up of units. Existing law requires the department to prepare or revise a general plan for a unit, as specified. Existing law requires the Department of Parks and Recreation to, before any park or recreational area developmental plan is made, cause to be made a land carrying capacity survey of the proposed park or recreational area.This bill would require the department to review its determination of the land carrying capacity of a park or recreational area made during the development of the applicable land carrying capacity survey and would authorize the department to revise the determination to incorporate new information and advancements in survey techniques.Under existing law, the Department of Parks and Recreation controls the state park system, which is made up of units. Existing law requires the department to prepare or revise a general plan for a unit, as specified. Existing law requires the Department of Parks and Recreation to, before any park or recreational area developmental plan is made, cause to be made a land carrying capacity survey of the proposed park or recreational area.
This bill would require the department to review its determination of the land carrying capacity of a park or recreational area made during the development of the applicable land carrying capacity survey and would authorize the department to revise the determination to incorporate new information and advancements in survey techniques.
(a)The California State Auditor may establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, whether created by the California Constitution or otherwise, that the California State Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
(b)In addition to identifying a local government agency as high risk on the basis of weaknesses identified in audit and investigative reports produced by the office, the California State Auditor may consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high risk.
(c)The California State Auditors Office shall be responsible for the state costs associated with the high-risk local government agency audit program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from the Joint Legislative Audit Committee.
(d)(1)The California State Auditor shall notify the Joint Legislative Audit Committee whenever he or she identifies a local government as at high risk.
(2)The California State Auditor shall provide the Joint Legislative Audit Committee, at a public hearing of the committee, an annual update of all audits in progress.
(3)If a local government agency has taken significant corrective measures for deficiencies identified by the California State Auditor, that agency shall be removed from the high-risk local government agency audit program.
(e)Notwithstanding the requirements of Section 10231.5, if the California State Auditor establishes the program provided for in this section and the California State Auditor determines that a local government agency is at high risk, the California State Auditor shall issue audit reports at least once every three years with recommendations for improvement in the local government so identified.
(f)Audits conducted pursuant to this section shall be approved by the Joint Legislative Audit Committee.
(g)(1)The California State Auditor may conduct an initial assessment at a local government agency prior to conducting an audit, during which he or she may gather any publicly available information from a local government agency and any additional information, including any interviews, that the local government agency is willing to provide, for the purpose of identifying whether or not it is a high-risk local government agency.
(2)Before beginning an initial assessment at a local government agency, the California State Auditor shall notify the Joint Legislative Audit Committee in writing which local government agency will be assessed.
SEC. 1.5.Section 8546.10 of the Government Code is amended to read:8546.10.(a)The California State Auditor may establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, whether created by the California Constitution or otherwise, that the California State Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
(b)In addition to identifying a local government agency as high risk on the basis of weaknesses identified in audit and investigative reports produced by the office, the California State Auditor may review publicly available information and consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high risk.
(c)The California State Auditors Office shall be responsible for the state costs associated with the high-risk local government agency audit program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from the Joint Legislative Audit Committee.
(d)(1)The California State Auditor shall notify the Joint Legislative Audit Committee whenever he or she identifies a local government as at high risk.
(2)The California State Auditor shall provide the Joint Legislative Audit Committee, at a public hearing of the committee, an annual update of all audits in progress.
(3)If a local government agency has taken significant corrective measures for deficiencies identified by the California State Auditor, that agency shall be removed from the high-risk local government agency audit program.
(e)Notwithstanding the requirements of Section 10231.5, if the California State Auditor establishes the program provided for in this section and the California State Auditor determines that a local government agency is at high risk, the California State Auditor shall issue audit reports at least once every three years with recommendations for improvement in the local government so identified.
(f)Audits conducted pursuant to this section shall be approved by the Joint Legislative Audit Committee.
(g)(1)The California State Auditor may conduct an initial assessment at a local government agency prior to conducting an audit, during which he or she may gather any publicly available information from a local government agency and any additional information, including any interviews, that the local government agency is willing to provide, for the purpose of identifying whether or not it is a high-risk local government agency.
(2)Before beginning an initial assessment at a local government agency, the California State Auditor shall notify the Joint Legislative Audit Committee in writing which local government agency will be assessed.
SEC. 2.Section 1.5 of this bill incorporates amendments to Section 8546.10 of the Government Code proposed by both this bill and Assembly Bill 2822. That section of this bill shall only become operative if (1) both bills are enacted and become effective on or before January 1, 2019, (2) each bill amends Section 8546.10 of the Government Code, and (3) this bill is enacted after Assembly Bill 2822, in which case Section 1 of this bill shall not become operative.
(a)The California State Auditor may establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, whether created by the California Constitution or otherwise, that the California State Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
(b)In addition to identifying a local government agency as high risk on the basis of weaknesses identified in audit and investigative reports produced by the office, the California State Auditor may consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high risk.
(c)The California State Auditors Office shall be responsible for the state costs associated with the high-risk local government agency audit program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from the Joint Legislative Audit Committee.
(d)(1)The California State Auditor shall notify the Joint Legislative Audit Committee whenever he or she identifies a local government as at high risk.
(2)The California State Auditor shall provide the Joint Legislative Audit Committee, at a public hearing of the committee, an annual update of all audits in progress.
(3)If a local government agency has taken significant corrective measures for deficiencies identified by the California State Auditor, that agency shall be removed from the high-risk local government agency audit program.
(e)Notwithstanding the requirements of Section 10231.5, if the California State Auditor establishes the program provided for in this section and the California State Auditor determines that a local government agency is at high risk, the California State Auditor shall issue audit reports at least once every three years with recommendations for improvement in the local government so identified.
(f)Audits conducted pursuant to this section shall be approved by the Joint Legislative Audit Committee.
(g)(1)The California State Auditor may conduct an initial assessment at a local government agency prior to conducting an audit, during which he or she may gather any publicly available information from a local government agency and any additional information, including any interviews, that the local government agency is willing to provide, for the purpose of identifying whether or not it is a high-risk local government agency.
(2)Before beginning an initial assessment at a local government agency, the California State Auditor shall notify the Joint Legislative Audit Committee in writing which local government agency will be assessed.
SEC. 1.5.Section 8546.10 of the Government Code is amended to read:8546.10.(a)The California State Auditor may establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, whether created by the California Constitution or otherwise, that the California State Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
(b)In addition to identifying a local government agency as high risk on the basis of weaknesses identified in audit and investigative reports produced by the office, the California State Auditor may review publicly available information and consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high risk.
(c)The California State Auditors Office shall be responsible for the state costs associated with the high-risk local government agency audit program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from the Joint Legislative Audit Committee.
(d)(1)The California State Auditor shall notify the Joint Legislative Audit Committee whenever he or she identifies a local government as at high risk.
(2)The California State Auditor shall provide the Joint Legislative Audit Committee, at a public hearing of the committee, an annual update of all audits in progress.
(3)If a local government agency has taken significant corrective measures for deficiencies identified by the California State Auditor, that agency shall be removed from the high-risk local government agency audit program.
(e)Notwithstanding the requirements of Section 10231.5, if the California State Auditor establishes the program provided for in this section and the California State Auditor determines that a local government agency is at high risk, the California State Auditor shall issue audit reports at least once every two three years with recommendations for improvement in such a the local government so identified.
(f)Audits conducted pursuant to this section shall be approved by the Joint Legislative Audit Committee.
(g)(1)The California State Auditor may conduct an initial assessment at a local government agency prior to conducting an audit, during which he or she may gather any publicly available information from a local government agency and any additional information, including any interviews, that the local government agency is willing to provide, for the purpose of identifying whether or not it is a high-risk local government agency.
(2)Before beginning an initial assessment at a local government agency, the California State Auditor shall notify the Joint Legislative Audit Committee in writing which local government agency will be assessed.
SEC. 2.Section 1.5 of this bill incorporates amendments to Section 8546.10 of the Government Code proposed by both this bill and Assembly Bill 2822. That section of this bill shall only become operative if (1) both bills are enacted and become effective on or before January 1, 2019, (2) each bill amends Section 8546.10 of the Government Code, and (3) this bill is enacted after Assembly Bill 2822, in which case Section 1 of this bill shall not become operative.
(a)The California State Auditor may establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, whether created by the California Constitution or otherwise, that the California State Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
(b)In addition to identifying a local government agency as high risk on the basis of weaknesses identified in audit and investigative reports produced by the office, the California State Auditor may consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high risk.
(c)The California State Auditors Office shall be responsible for the state costs associated with the high-risk local government agency audit program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from the Joint Legislative Audit Committee.
(d)(1)The California State Auditor shall notify the Joint Legislative Audit Committee whenever he or she identifies a local government as at high risk. The California State Auditor may first conduct an initial assessment, during which he or she may gather information from a local government agency for the purpose of identifying it as a high-risk local government agency.
(2)The California State Auditor shall provide the Joint Legislative Audit Committee, at a public hearing of the committee, an annual update of all audits in progress.
(3)If a local government agency has taken significant corrective measures for deficiencies identified by the California State Auditor, that agency shall be removed from the high-risk local government agency audit program.
(e)Notwithstanding the requirements of Section 10231.5, if the California State Auditor establishes the program provided for in this section and the California State Auditor determines that a local government agency is at high risk, the California State Auditor shall issue audit reports at least once every two three years with recommendations for improvement in such a the local government so identified.
(f)Audits conducted pursuant to this section shall be approved by the Joint Legislative Audit Committee.
(g)(1)The California State Auditor may conduct an initial assessment at a local government agency prior to conducting an audit, during which he or she may gather any publicly available information from a local government agency and any additional information, including any interviews, that the local government agency is willing to provide, for the purpose of identifying whether or not it is a high-risk local government agency.
(2)Before beginning an initial assessment at a local government agency, the California State Auditor shall notify the Joint Legislative Audit Committee in writing which local government agency will be assessed.
(a)The California State Auditor may establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, whether created by the California Constitution or otherwise, that the California State Auditor identifies as being at high risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
(b)In addition to identifying a local government agency as high risk on the basis of weaknesses identified in audit and investigative reports produced by the office, the California State Auditor may consult with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high risk.
(c)The California State Auditors Office shall be responsible for the state costs associated with the high-risk local government agency audit program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from the Joint Legislative Audit Committee.
(d)(1)The California State Auditor shall notify the Joint Legislative Audit Committee whenever he or she identifies a local government as at high risk. The California State Auditor may first conduct an initial assessment, during which he or she may gather information from a local government agency for the purpose of identifying it as a high-risk local government agency.
(2)The California State Auditor shall provide the Joint Legislative Audit Committee, at a public hearing of the committee, an annual update of all audits in progress.
(3)If a local government agency has taken significant corrective measures for deficiencies identified by the California State Auditor, that agency shall be removed from the high-risk local government agency audit program.
(e)Notwithstanding the requirements of Section 10231.5, if the California State Auditor establishes the program provided for in this section and the California State Auditor determines that a local agency is at high risk, the California State Auditor shall issue audit reports at least once every two years with recommendations for improvement in such a local government so identified.
(f)Audits conducted pursuant to this section shall be approved by the Joint Legislative Audit Committee.
SECTION 1.Section 5019.5 of the Public Resources Code is amended to read:5019.5.(a)Before any park or recreational area developmental plan is made, the department shall make a land carrying capacity survey of the proposed park or recreational area that includes, but is not necessarily limited to, soil, moisture, and natural cover factors.(b)The department shall periodically review its determination of the land carrying capacity of a park or recreational area made during the development of the applicable land carrying capacity survey. The department may revise the determination to incorporate new information and advancements in survey techniques.(a)Before any park or recreational area developmental plan is made, the department shall cause to be made a make a land carrying capacity survey of the proposed park or recreational area, including in such survey such factors as area that includes, but is not necessarily limited to, soil, moisture, and natural cover. cover factors.
(b)The department shall periodically review its determination of the land carrying capacity of a park or recreational area made during the development of the applicable land carrying capacity survey. The department may revise the determination to incorporate new information and advancements in survey techniques.
|
Date
|
Status
|
|---|---|
| Sep 18, 2018 | Chaptered by Secretary of State. Chapter 515, Statutes of 2018. |
| Sep 18, 2018 | Approved by the Governor. |
| Sep 10, 2018 | Enrolled and presented to the Governor at 4 p.m. |
| Aug 28, 2018 | Assembly amendments concurred in. (Ayes 39. Noes 0.) Ordered to engrossing and enrolling. |
| Aug 28, 2018 | In Senate. Concurrence in Assembly amendments pending. |
| Aug 27, 2018 | Read third time. Passed. Ordered to the Senate. |
| Aug 23, 2018 | Read third time and amended. |
| Aug 16, 2018 | From consent calendar on motion of Assembly Member Obernolte. |
| Aug 9, 2018 | Read second time. Ordered to consent calendar. |
| Aug 8, 2018 | From committee: Do pass. Ordered to consent calendar. (Ayes 17. Noes 0.) (August 8). |
| Jul 5, 2018 | From committee with author's amendments. Read second time and amended. Re-referred to Com. on APPR. |
| Jun 27, 2018 | From committee: Do pass and re-refer to Com. on APPR. (Ayes 7. Noes 0.) (June 27). Re-referred to Com. on APPR. |
| May 31, 2018 | Referred to Com. on A. & A.R. |
| May 21, 2018 | In Assembly. Read first time. Held at Desk. |
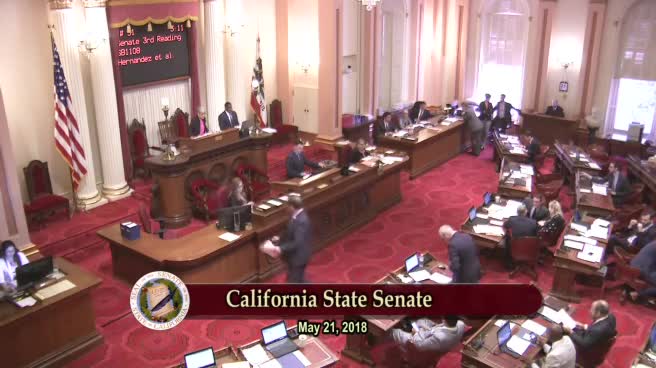
| May 21, 2018 | Read third time. Passed. (Ayes 38. Noes 0.) Ordered to the Assembly. |
| May 15, 2018 | Read second time. Ordered to third reading. |
| May 14, 2018 | From committee: Be ordered to second reading pursuant to Senate Rule 28.8. |
| May 4, 2018 | Set for hearing May 14. |
| Apr 24, 2018 | From committee: Do pass and re-refer to Com. on APPR. (Ayes 12. Noes 0. Page 4785.) (April 24). Re-referred to Com. on APPR. |
| Apr 23, 2018 | From committee: Do pass and re-refer to Com. on APPR. (Ayes 12. Noes 0.) (April 24). Re-referred to Com. on APPR. |
| Apr 19, 2018 | Set for hearing April 24. |
| Apr 19, 2018 | Re-referred to Com. on G.O. |
| Apr 17, 2018 | Withdrawn from committee. |
| Apr 16, 2018 | From committee with author's amendments. Read second time and amended. Re-referred to Com. on N.R. & W. |
| Mar 1, 2018 | Referred to Com. on N.R. & W. |
| Feb 20, 2018 | From printer. May be acted upon on or after March 22. |
| Feb 16, 2018 | Introduced. Read first time. To Com. on RLS. for assignment. To print. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Aug 28, 2018 | Unfinished Business SB1293 Lara et al. Concurrence | Senate Floor |
Passed |
|
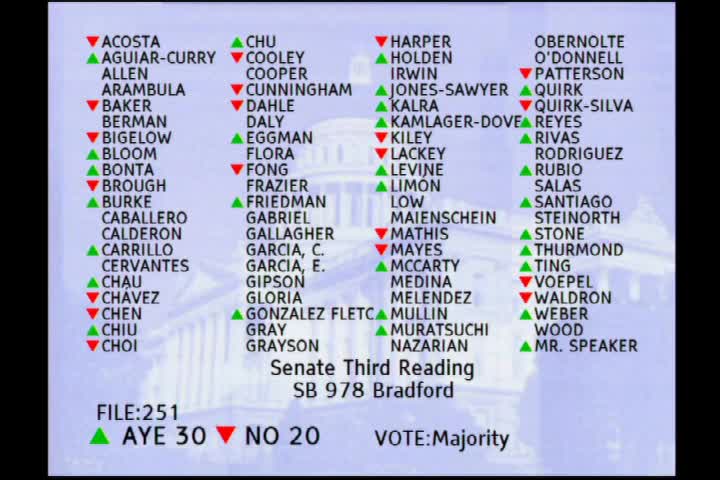
| Aug 27, 2018 | SB 1293 Lara Senate Third Reading By GONZALEZ FLETCHER | Assembly Floor |
Passed |
|
| Aug 8, 2018 | Do pass. To Consent Calendar. | Assembly Standing Committee on Appropriations |
Passed |
|
| Jun 27, 2018 | Do pass and be re-referred to the Committee on [Appropriations] | Assembly Standing Committee on Accountability and Administrative Review |
Passed |
|
| May 21, 2018 | Senate 3rd Reading SB1293 Lara | Senate Floor |
Passed |
|
| Apr 24, 2018 | Do pass, but first be re-referred to the Committee on [Appropriations] | Senate Standing Committee on Governmental Organization |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| Association of California Healthcare Districts | ** Support | Aug 28, 2018 |
| California Special Districts Association | ** Support | Aug 28, 2018 |
| League Of California Cities | ** Support | Aug 28, 2018 |
Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | SB |
UNFINISHED BUSINESS
Bill No: SB 1293
:
SENATE GOVERNMENTAL ORG. COMMITTEE: 12-0, 4/24/18
AYES: Dodd, Wilk, Bradford, Cannella, Gaines, Galgiani, Glazer, Hill, Hueso, Lara, Portantino, Vidak
SENATE APPROPRIATIONS COMMITTEE: Senate Rule 28.8
SENATE FLOOR: 38-0, 5/21/18
AYES: Allen, Anderson, Atkins, Bates, Beall, Berryhill, Bradford, Cannella, De León, Dodd, Fuller, Gaines, Galgiani, Glazer, Hernandez, Hertzberg, Hill, Hueso, Jackson, Lara, Leyva, McGuire, Mitchell, Monning, Moorlach, Newman, Nguyen, Nielsen, Pan, Portantino, Roth, Skinner, Stern, Stone, Vidak, Wieckowski, Wiener, Wilk
NO VOTE RECORDED: Morrell
ASSEMBLY FLOOR: 80-0, 8/27/18 - See last page for vote
SUBJECT: California State Auditor: high-risk local government agency audit program
DIGEST:
This bill authorizes the California State Auditor (Auditor), after first notifying the Joint Legislative Audit Committee (JLAC), to conduct initial assessments when determining if an entity is high risk under the Auditor’s high risk local government agency audit program (program).
Assembly Amendments
require the Auditor to notify JLAC prior to beginning an initial assessment at a local government agency, and add chaptering out language to avoid potential conflicts with provisions of AB 2822 (Obernolte) of the current legislative session.
Existing law:
- Establishes the Auditor’s Office headed by the Auditor, with specified duties that include, among others, conducting financial and performance audits as directed by statute and other government audits as requested by JLAC.
- Authorizes the Auditor to establish a high-risk local government agency audit program for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, that the Auditor identifies as being at high-risk for the potential waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
- Provides that the Auditor’s Office shall be responsible for the state costs associated with the program, shall conduct the program as funds permit, and shall only conduct the program to the extent that it does not interfere with duties related to mandated audits and requests from JLAC.
- Requires the Auditor to notify JLAC whenever he or she identifies a local government as high-risk.
- Provides that if the Auditor determines that a local agency is at high risk, the Audit shall issue audit reports at least once every two years with recommendations for improvement in the local government so identified.
- Requires that audits conducted pursuant to those provisions be approved by JLAC.
This bill:
- Authorizes the Auditor to conduct an initial assessment at a local government agency prior to conducting an audit, during which he or she may gather publicly available information from a local government agency and any additional information, including interviews, that the local government agency is willing to provide, for the purpose of identifying whether or not it is a high-risk local government agency.
- Requires the Auditor to notify JLAC in writing which local government agency will be assessed prior to beginning an initial assessment at a local government agency.
- Extends from two to three years, the frequency that the Auditor must issue audit reports with recommendations for improvement to local governments determined to be at high risk.
Comments
Purpose of the bill. According to the author, “this bill seeks to further match the spirit and intent of AB 187 (Lara, Chapter 451, Statutes of 2011) by allowing the Auditor to examine local governments during the course of his or her Program to determine if there are any areas that are at risk of fraud, waste, or mismanagement.”
Further, the author argues that “in light of a recent Legislative Counsel opinion, where the intent of AB 187 left room for interpretation and provisions have been put into question, this bill further matches the intent and spirit of the law to authorize the Auditor to gather information from a local government agency. This bill avoids any room for additional interpretations of the statute, and continues to provide the Auditor with the previously granted authority to gather information from local governments as a part of the Program.”
High-risk local government agency audit program. Under current law, the Auditor is authorized to establish the program for the purpose of identifying, auditing, and issuing reports on any local government agency that the Auditor identifies as being at high-risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
In implementing the program, the Auditor established a five-step process prior to submitting an audit proposal to JLAC. That process includes identifying, from available information, a local agency as potentially high-risk, contacting the local agency with initial concerns, meeting with the local agency’s management to discuss risk factors, visiting the local agency and performing an initial assessment, and holding an initial assessment closeout meeting with local agency management.
Once the five-step process is completed, the Auditor will either cease their work if the Auditor believes the local agency is not at high-risk, or, the Auditor will submit an audit proposal to JLAC for consideration. While audits conducted under the program must be approved by JLAC, a recent opinion from Legislative Counsel has left room for interpretation whether current law authorizes the program to include on-site reviews such as those performed during the initial assessment.
The author points out that it was the original intent of AB 187 to allow the Auditor to examine local governments while conducting the program in order to accurately determine if there are any areas that are at risk of fraud, waste, or mismanagement.
This bill provides explicit direction that the Auditor may conduct an initial assessment at a local government agency prior to conducting an audit. Additionally, this bill clarifies that during the initial assessment, the Auditor may gather any publicly available information from a local government agency and any additional information, including any interviews, that the local government agency is willing to provide, for the purpose of identifying whether or not it is a high-risk local government agency.
Related/Prior Legislation
AB 2729 (Muratsuchi, 2018) sets approval requirements for audits under the Auditor’s high-risk local government agency audit program and allows the Auditor to limit or discontinue audit work. (Never heard in the Senate Appropriations Committee)
AB 2822 (Obernolte, 2018) authorizes the Auditor to use publicly available information when identifying local government agencies that are high-risk under the Auditor’s high-risk local government agency program. (Pending on the Senate Floor)
SB 187 (Lara, Chapter 451, Statutes of 2011) authorized the Auditor to establish a Program to identify, audit, and issue reports on any local government agency, including any city, county, or special district.
FISCAL EFFECT: Appropriation: Fiscal Com.: Local:
According to the Assembly Appropriations Committee, negligible cost to the Auditor.
Association of California Healthcare Districts
California Special Districts Association
League of California Cities
OPPOSITION: (Verified 8/27/18)
None received
ARGUMENTS IN SUPPORT: The supporters of this bill write that the “simple change sought by SB 1293 to grant the State Auditor the authority to implement the HRLGAAP (High-Risk Local Government Agency Audit Program) as it was originally designed, benefits the public and the local public agencies that serve them, while maintaining essential financial oversight.”
ASSEMBLY FLOOR: 80-0, 8/27/18
AYES: Acosta, Aguiar-Curry, Travis Allen, Arambula, Baker, Berman, Bigelow, Bloom, Bonta, Brough, Burke, Caballero, Calderon, Carrillo, Cervantes, Chau, Chávez, Chen, Chiu, Choi, Chu, Cooley, Cooper, Cunningham, Dahle, Daly, Eggman, Flora, Fong, Frazier, Friedman, Gabriel, Gallagher, Cristina Garcia, Eduardo Garcia, Gipson, Gloria, Gonzalez Fletcher, Gray, Grayson, Harper, Holden, Irwin, Jones-Sawyer, Kalra, Kamlager-Dove, Kiley, Lackey, Levine, Limón, Low, Maienschein, Mathis, Mayes, McCarty, Medina, Melendez, Mullin, Muratsuchi, Nazarian, Obernolte, O'Donnell, Patterson, Quirk, Quirk-Silva, Reyes, Rivas, Rodriguez, Rubio, Salas, Santiago, Steinorth, Mark Stone, Thurmond, Ting, Voepel, Waldron, Weber, Wood, Rendon
8/28/18 9:36:31
**** END ****
SENATE THIRD READING
STR Bill Id:SB 1293
Author:(Lara)
As Amended Ver:August 23, 2018
Majority vote
SENATE VOTE: 38-0
Committee | Votes | Ayes | Noes |
Accountability | 7-0 | Eggman, Patterson, Burke, Frazier, Lackey, Medina, Quirk-Silva |
|
Appropriations | 17-0 | Gonzalez Fletcher, Bigelow, Bloom, Bonta, Brough, Calderon, Carrillo, Chau, Eggman, Fong, Friedman, Gallagher, Eduardo Garcia, Nazarian, Obernolte, Quirk, Reyes |
|
SUMMARY: Allows, after first notifying the Joint Legislative Audit Committee (JLAC), the California State Auditor (Auditor) to conduct initial assessments when determining if an entity is high risk under the Auditor's high risk local government agency audit program (program).
EXISTING LAW:
- Allows the Auditor to establish a high-risk local audit program.
- Specifies the information to use when the Auditor assesses if an entity is high risk.
- Specifies that the Auditor is responsible for the state costs of conducting the high-risk local audit program.
- Requires the Auditor to notify JLAC when the Auditor identifies an entity as high risk.
- Requires JLAC approval prior to an audit of an entity.
FISCAL EFFECT: According to the Assembly Appropriations Committee, negligible cost to the State Auditor.
COMMENTS: This bill allows the Auditor to conduct initial assessments of local government entities under the program when evaluating if an entity should be classified as high risk. Prior to beginning the assessment, this bill requires the Auditor to notify JLAC in writing which government agency will be reviewed. Additionally, it specifies that the Auditor may gather, during the assessment, publicly available and other information that a local agency is willing to provide.
Current law specifies that, when determining risk of a local entity, the Auditor can use weaknesses identified in its audit and investigative reports, and through consultation with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency.
When implementing the high-risk program, the Auditor established a five step process prior to submitting an audit proposal to JLAC. That process includes identifying from available information a local agency as potentially high-risk; contacting it with initial concerns; meeting with its management to discuss risk factors and expected timeframes for the Auditor's analysis; visiting the agency and performing an initial assessment, in which the audit team spends approximately two to three weeks onsite; and holding an initial assessment closeout meeting with agency management.
After this process is complete, the Auditor either ceases its work if it does not determine that the agency is high risk or submits an audit proposal to JLAC for its consideration. JLAC, which reviews and takes action on audit requests, is a legislative committee composed of members of both the Assembly and Senate. If JLAC approves the audit, the Auditor returns to the agency to conduct it.
While audits conducted under the high-risk program must be approved by JLAC, current law does not authorize or include references to on-site reviews like those done during initial assessments.
A recent opinion from the Legislative Counsel of California (Counsel), the nonpartisan public agency that drafts legislative proposals and prepares legal opinions for the Legislature, found concerns related to the authority in the program. Counsel states "we think that a court would find, based upon the plain language of [Government Code] section 8546.10, that the Auditor has neither explicit nor implicit authority to gather information from a local government agency for the sole purpose of identifying it as a high-risk local government agency."
This bill would provide the Auditor the authority to conduct initial assessments, as specified.
Recent amendments resolve a potential chaptering out issue with AB 2822 (Obernolte) of the current legislative session, a bill also related to the program, by adding information about how the bills become operative.
RELATED LEGISLATION:
AB 2822 (Obernolte) of the current legislative session, which is pending in the Senate, allows the Auditor to use publicly available information when determining if a local government is considered high risk under the program.
Analysis Prepared by: Scott Herbstman / A. & A.R. / (916) 319-3600 FN: 0004383
SENATE THIRD READING
STR Bill Id:SB 1293
Author:(Lara)
As Amended Ver:July 5, 2018
Majority vote
SENATE VOTE: 38-0
Committee | Votes | Ayes | Noes |
Accountability | 7-0 | Eggman, Patterson, Burke, Frazier, Lackey, Medina, Quirk-Silva | |
Appropriations | 17-0 | Gonzalez Fletcher, Bigelow, Bloom, Bonta, Brough, Calderon, Carrillo, Chau, Eggman, Fong, Friedman, Gallagher, Eduardo Garcia, Nazarian, Obernolte, Quirk, Reyes |
SUMMARY: Allows, after first notifying the Joint Legislative Audit Committee (JLAC), the California State Auditor (Auditor) to conduct initial assessments when determining if an entity is high risk under the Auditor's high risk local government agency audit program (program).
EXISTING LAW:
- Allows the Auditor to establish a high-risk local audit program.
- Specifies the information to use when the Auditor assesses if an entity is high risk.
- Specifies that the Auditor is responsible for the state costs of conducting the high-risk local audit program.
- Requires the Auditor to notify JLAC when the Auditor identifies an entity as high risk.
- Requires JLAC approval prior to an audit of an entity.
FISCAL EFFECT: According to the Assembly Appropriations Committee, negligible cost to the State Auditor.
COMMENTS: This bill allows the Auditor to conduct initial assessments of local government entities under the program when evaluating if an entity should be classified as high risk. Prior to beginning the assessment, this bill requires the Auditor to notify JLAC in writing which government agency will be reviewed. Additionally, it specifies that the Auditor may gather, during the assessment, publicly available and other information that a local agency is willing to provide.
Current law specifies that, when determining risk of a local entity, the Auditor can use weaknesses identified in its audit and investigative reports, and through consultation with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency.
When implementing the high-risk program, the Auditor established a five step process prior to submitting an audit proposal to JLAC. That process includes identifying from available information a local agency as potentially high-risk; contacting it with initial concerns; meeting with its management to discuss risk factors and expected timeframes for the Auditor's analysis; visiting the agency and performing an initial assessment, in which the audit team spends approximately two to three weeks onsite; and holding an initial assessment closeout meeting with agency management.
After this process is complete, the Auditor either ceases its work if it does not determine that the agency is high risk or submits an audit proposal to JLAC for its consideration. JLAC, which reviews and takes action on audit requests, is a legislative committee composed of members of both the Assembly and Senate. If JLAC approves the audit, the Auditor returns to the agency to conduct it.
While audits conducted under the high-risk program must be approved by JLAC, current law does not authorize or include references to on-site reviews like those done during initial assessments.
A recent opinion from the Legislative Counsel of California (Counsel), the nonpartisan public agency that drafts legislative proposals and prepares legal opinions for the Legislature, found concerns related to the authority in the program. Counsel states "we think that a court would find, based upon the plain language of [Government Code] Section 8546.10, that the Auditor has neither explicit nor implicit authority to gather information from a local government agency for the sole purpose of identifying it as a high-risk local government agency."
This bill would provide the Auditor the authority to conduct initial assessments, as specified.
RELATED LEGISLATION:
AB 2822 (Obernolte) of the current legislative session, which is pending in the Senate, allows the Auditor to use publicly available information when determining if a local government is considered high risk under the program.
Analysis Prepared by: Scott Herbstman / A. & A.R. / (916) 319-3600 FN: 0004201
Date of Hearing: August 8, 2018
ASSEMBLY COMMITTEE ON APPROPRIATIONS
Lorena Gonzalez Fletcher, Chair
SBPCA Bill Id:SB 1293
Author:(Lara) – As Amended Ver:July 5, 2018
Policy Committee: | Accountability and Administrative Review | Vote: | 7 - 0 |
|
| ||
|
|
Urgency: No State Mandated Local Program: No Reimbursable: No
SUMMARY:
This bill authorizes the California State Auditor (Auditor) to conduct an initial assessment at a local government agency prior to conducting an audit, for the purpose of determining whether the agency is a high-risk local agency. The bill requires the Auditor, prior to beginning the assessment, to notify the Joint Legislative Audit Committee (JLAC, in writing, which agency will be assessed. The bill specifies the Auditor may gather publically available information from the agency as well as any additional information the agency is willing to provide.
The bill further specifies that the Auditor may issue an audit report on a high-risk agency at least once every three years, instead of once every two years.
FISCAL EFFECT:
Negligible cost to the State Auditor.
COMMENTS:
- Purpose. This bill seeks to clarify the authority of the Auditor to conduct initial assessments under its high-risk program in response to a recent Legislative Counsel opinion questioning the authority of the Auditor to do so.
- Background. AB 187 (Lara), Chapter 451, Statutes of 2011, authorized the Auditor to establish the high-risk local government agency audit program to identify, audit, and issue reports on any local government agency the Auditor identifies as being at high risk for potential waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
In implementing the program, the Auditor established a 10-step process through program regulations. The initial steps of that process includes assessing publicly available information, establishing formal contact with the local agency, holding an entrance conference to discuss risk factors, visiting the local agency, and holding an initial assessment closeout meeting.
Once the initial five steps are completed, the Auditor either ceases work or submits an audit proposal to JLAC for the committee’s consideration. While audits conducted under the high-risk local government agency audit program must be approved by JLAC, a recent opinion from Legislative Counsel questions whether current law authorizes the initial assessment portion of the process to include on-site reviews.
This bill provides the Auditor authority to conduct initial assessments prior to JLAC approval, however, adds the requirement that the Auditor first notify JLAC of which agency will be assessed. This clarification allows the program to continue operating essentially as it does now.
Existing law specifies the Auditor, when determining risk of a local entity, may use weaknesses identified in its audit and investigative reports and consult with the controller, attorney general, and other state agencies that have oversight responsibilities over any local government agency. This bill further specifies the Auditor may use any publically available information from the agency and any additional information the agency is willing to provide.
- Related Legislation. Earlier this session, this committee approved AB 2729 (Muratsuchi), a competing bill that required JLAC approval prior to the Auditor conducting an initial assessment. That bill was amended in June to be nearly identical to this bill. It is staff’s understanding that the Auditor and both authors have agreed to the language in SB 1293 (this bill) and that AB 2729, set for August 6, 2018, in the Senate Appropriations Committee, will no longer address the Auditor’s authority to conduct initial assessments.
AB 2822 (Obernolte) of the current legislative session, similar to provisions of this bill, allows the Auditor to use publicly available information when determining if a local government is considered high risk under the program. That bill is set for August 6, 2018, in the Senate Appropriations Committee.
Analysis Prepared by: Jennifer Swenson / APPR. / (916) 319-2081
Date of Hearing: June 27, 2018
ASSEMBLY COMMITTEE ON ACCOUNTABILITY AND ADMINISTRATIVE REVIEW
Susan Talamantes Eggman, Chair
SBPCA Bill Id:SB 1293
Author:(Lara) – As Amended Ver:April 16, 2018
SENATE VOTE: 38-0
SUBJECT: California State Auditor: high-risk local government agency audit program
SUMMARY: Allows the California State Auditor (Auditor) to conduct initial assessments when determining if an entity is high risk under the Auditor's high risk local government agency audit program (program).
EXISTING LAW:
- Allows the Auditor to establish a high-risk local audit program.
- Specifies the information to use when the Auditor assesses if an entity is high risk.
- Specifies that the Auditor is responsible for the state costs of conducting the high-risk local audit program.
- Requires the Auditor to notify the Joint Legislative Audit Committee (JLAC) when the Auditor identifies an entity as high risk.
- Requires JLAC approval prior to an audit of an entity.
FISCAL EFFECT: According to the Senate Appropriations Committee, pursuant to Senate Rule 28.8, negligible state costs.
COMMENTS: This bill allows the Auditor to conduct initial assessments of local government entities under the program when evaluating if an entity should be classified as high risk.
Current law specifies that, when determining risk of a local entity, the Auditor can use weaknesses identified in its audit and investigative reports, and through consultation with the Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency.
When implementing the high-risk program, the Auditor established a five step process prior to submitting an audit proposal to JLAC. That process includes identifying from available information a local agency as potentially high-risk; contacting it with initial concerns; meeting with its management to discuss risk factors and expected timeframes for the Auditor's analysis; visiting the agency and performing an initial assessment, in which the audit team spends approximately two to three weeks onsite; and holding an initial assessment closeout meeting with agency management.
After this process is complete, the Auditor either ceases its work if it does not determine that the agency is high risk or submits an audit proposal to JLAC for its consideration. JLAC, which reviews and takes action on audit requests, is a legislative committee composed of members of both the Assembly and Senate. If JLAC approves the audit, the Auditor returns to the agency to conduct it.
While audits conducted under the high-risk program must be approved by JLAC, current law does not authorize or include references to on-site reviews like those done during initial assessments.
A recent opinion from the Legislative Counsel of California (Counsel), the nonpartisan public agency that drafts legislative proposals and prepares legal opinions for the Legislature, found concerns related to the authority in the program. Counsel states "we think that a court would find, based upon the plain language of [Government Code] section 8546.10, that the Auditor has neither explicit nor implicit authority to gather information from a local government agency for the sole purpose of identifying it as a high-risk local government agency."
This bill would provide the Auditor the authority to conduct initial assessments prior to JLAC approval, which would allow the program to continue operating as it does now.
The author of this bill states that it is needed in light of the legal opinion to meet the intent of the program, which was created by one of his bills, AB 187 (Lara), Chapter 451, Statutes of 2011.
This bill "seeks to further match the spirit and intent of AB 187 (Lara, 2011) by allowing the State Auditor to examine local governments during the course of his/her high-risk audit program to determine if there are any areas at risk of fraud, waste, or mismanagement," the author states. "Since the creation of this program, many local governments have benefited from the State Auditor’s corrective guidance program, avoiding past mistakes and ensure the effective and efficient management of public funds."
Supporters of this bill, which include groups that represent local entities, contend that the program has been working effectively. They state that allowing the Auditor to conduct initial assessments prior to JLAC approval "prevents the unnecessary erosion of public trust in the local agencies that serve them by ensuring that the State Auditor does not prematurely request a full-audit in a statewide setting that is unneeded and unwarranted."
RELATED LEGISLATION:
- AB 2729 (Muratsuchi) of the current legislative session, which is set to be heard June 26, 2018, in the Senate Governmental Organization Committee, allows the Auditor to conduct initial assessments after first notifying JLAC.
- AB 2822 (Obernolte) of the current legislative session, which is set to be heard June 26, 2018, in the Senate Governmental Organization Committee, allows the Auditor to use publicly available information when determining if a local government is considered high risk under the program.
REGISTERED SUPPORT / OPPOSITION:
Support
Association of California Healthcare Districts
California Special Districts Association
League of California Cities
Opposition
None on file
Analysis Prepared by: Scott Herbstman / A. & A.R. / (916) 319-3600
Office of Senate Floor Analyses (916) 651-1520 Fax: (916) 327-4478 | SB |
THIRD READING
Bill No: SB 1293
:
SENATE GOVERNMENTAL ORG. COMMITTEE: 12-0, 4/24/18
AYES: Dodd, Wilk, Bradford, Cannella, Gaines, Galgiani, Glazer, Hill, Hueso, Lara, Portantino, Vidak
SENATE APPROPRIATIONS COMMITTEE: Senate Rule 28.8
DIGEST:
This bill authorizes the California State Auditor (Auditor) to gather information from a local government agency as part of conducting an initial assessment in identifying a high-risk local government agency, prior to receiving approval from the Joint Legislative Audit Committee (JLAC).
Existing law:
- Establishes the Auditor’s Office headed by the Auditor, with specified duties that include, among others, conducting financial and performance audits as directed by statute and other government audits as requested by JLAC.
- Authorizes the Auditor to establish a high-risk local government agency audit program (Program) for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, that the Auditor identifies as being at high-risk for the potential waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
- Authorizes the Auditor to consult with the State Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high-risk.
- Provides that the Auditor’s Office shall be responsible for the state costs associated with the Program, shall conduct the Program as funds permit, and shall only conduct the Program to the extent that it does not interfere with duties related to mandated audits and requests from JLAC.
- Provides that if a local government agency has taken significant corrective measures for deficiencies identified by the Auditor, that agency shall be removed from the Program.
- Requires the Auditor to notify JLAC whenever he or she identifies a local government as high-risk.
- Requires that audits conducted pursuant to those provisions be approved by JLAC.
This bill authorizes the Auditor to gather information from a local government agency as part of conducting an initial assessment in identifying a high-risk local government agency, prior to receiving approval from JLAC.
Comments
Purpose of the bill. According to the author, “this bill seeks to further match the spirit and intent of AB 187 (Lara, Chapter 451, Statutes of 2011) by allowing the Auditor to examine local governments during the course of his or her Program to determine if there are any areas that are at risk of fraud, waste, or mismanagement.”
Further, the author argues that “in light of a recent Legislative Counsel opinion, where the intent of AB 187 left room for interpretation and provisions have been put into question, this bill further matches the intent and spirit of the law to authorize the Auditor to gather information from a local government agency. This bill avoids any room for additional interpretations of the statute, and continues to provide the Auditor with the previously granted authority to gather information from local governments as a part of the Program.”
High-risk local government agency audit program. Under current law, the Auditor is authorized to establish the Program for the purpose of identifying, auditing, and issuing reports on any local government agency that the Auditor identifies as being at high-risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
In implementing the Program, the Auditor established a five-step process prior to submitting an audit proposal to JLAC. That process includes identifying, from available information, a local agency as potentially high-risk, contacting the local agency with initial concerns, meeting with the local agency’s management to discuss risk factors, visiting the local agency and performing an initial assessment, and holding an initial assessment closeout meeting with local agency management.
Once the five-step process is completed, the Auditor will either cease their work if the Auditor believes the local agency is not at high-risk, or, the Auditor will submit an audit proposal to JLAC for consideration. While audits conducted under the Program must be approved by JLAC, a recent opinion from Legislative Counsel has left room for interpretation whether current law authorizes the Program to include on-site reviews such as those performed during the initial assessment.
The author points out that it was the original intent of AB 187 to allow the Auditor to examine local governments while conducting the Program in order to accurately determine if there are any areas that are at risk of fraud, waste, or mismanagement.
This bill provides explicit direction that the Auditor may gather information from a local government agency during an initial assessment, as a way to avoid any room for additional interpretations of the statute.
Related/Prior Legislation
AB 2729 (Muratsuchi, 2018) sets approval requirements for audits under the Auditor’s high-risk local government agency audit program and allows the Auditor to limit or discontinue audit work. (Pending in the Assembly Appropriations Committee)
AB 2822 (Obernolte, 2018) authorizes the Auditor to use publicly available information when identifying local government agencies that are high-risk under the Auditor’s high-risk local government agency program. (Pending in the Senate Rules Committee)
AB 32 (Rodriguez, Chapter 606, Statutes of 2017) set a recruitment process for Auditor candidates by requiring JLAC to conduct a comprehensive search before it selects three qualified individuals for the position to be forwarded to the Governor to appoint one of the three as the Auditor.
SB 187 (Lara, Chapter 451, Statutes of 2011) authorized the Auditor to establish a Program to identify, audit, and issue reports on any local government agency, including any city, county, or special district.
SB 1437 (Speier, Chapter 251, Statutes of 2004) authorized the Auditor to establish a high-risk government agency audit program for the purpose of identifying, auditing, and issuing reports on any state agency that the Auditor identified as high-risk for the potential of waste, fraud, abuse, and mismanagement, or that has major challenges associated with its economy, efficiency, or effectiveness.
SB 37 (Maddy, Chapter 251, Statutes of 1993) created the Bureau of State Audits under the direction of the Little Hoover Commission, and moved many of the duties and powers of the Officer of Auditor General to the Bureau of State Audits.
FISCAL EFFECT: Appropriation: Fiscal Com.: Local:
Association of California Healthcare Districts
California Special Districts Association
League of California Cities
OPPOSITION: (Verified 5/15/18)
None received
5/16/18 10:33:22
**** END ****
SENATE COMMITTEE ON GOVERNMENTAL ORGANIZATION
Senator Bill Dodd
Chair
2017 - 2018 Regular
Bill No: SB Hearing Date: 4/24/2018
Author: | Lara | ||
Version: | Amended | ||
Urgency: | Fiscal: | ||
Consultant: | |||
SUBJECT:
DIGEST: This bill authorizes the California State Auditor (Auditor) to gather information from a local government agency as part of conducting an initial assessment in identifying a high-risk local government agency, prior to receiving approval from the Joint Legislative Audit Committee (JLAC).
ANALYSIS:
Existing law:
- Establishes the Auditor’s Office headed by the Auditor, with specified duties that include, among others, conducting financial and performance audits as directed by statute and other government audits as requested by JLAC.
- Authorizes the Auditor to establish a high-risk local government agency audit program (Program) for the purpose of identifying, auditing, and issuing reports on any local government agency, including, but not limited to, any city, county, special district, or any publicly created entity, that the Auditor identifies as being at high-risk for the potential waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
- Authorizes the Auditor to consult with the State Controller, Attorney General, and other state agencies that have oversight responsibilities over any local government agency, in identifying local governments that are at high-risk.
- Provides that the Auditor’s office shall be responsible for the state costs associated with the Program, shall conduct the Program as funds permit, and shall only conduct the Program to the extent that it does not interfere with duties related to mandated audits and requests from JLAC.
- Provides that if a local government agency has taken significant corrective measures for deficiencies identified by the Auditor, that agency shall be removed from the Program.
- Requires the Auditor to notify JLAC whenever he or she identifies a local government as high-risk.
- Requires that audits conducted pursuant to those provisions be approved by JLAC.
This bill authorizes the Auditor to gather information from a local government agency as part of conducting an initial assessment in identifying a high-risk local government agency, prior to receiving approval from JLAC.
Background
Purpose of the bill. According to the author, “this bill seeks to further match the spirit and intent of AB 187 (Lara, Chapter 451, Statutes of 2011) by allowing the Auditor to examine local governments during the course of his or her Program to determine if there are any areas that are at risk of fraud, waste, or mismanagement.”
Further, the author argues that “in light of a recent Legislative Counsel opinion, where the intent of AB 187 left room for interpretation and provisions have been put into question, this bill further matches the intent and spirit of the law to authorize the Auditor to gather information from a local government agency. This bill avoids any room for additional interpretations of the statute, and continues to provide the Auditor with the previously granted authority to gather information from local governments as a part of the Program.”
High-risk local government agency audit program. Under current law, the Auditor is authorized to establish the Program for the purpose of identifying, auditing, and issuing reports on any local government agency that the Auditor identifies as being at high-risk for the potential of waste, fraud, abuse, or mismanagement or that has major challenges associated with its economy, efficiency, or effectiveness.
In implementing the Program, the Auditor established a five-step process prior to submitting an audit proposal to JLAC. That process includes identifying, from available information, a local agency as potentially high-risk, contacting the local agency with initial concerns, meeting with the local agency’s management to discuss risk factors, visiting the local agency and performing an initial assessment, and holding an initial assessment closeout meeting with local agency management.
Once the five-step process is completed, the Auditor will either cease their work if the Auditor believes the local agency is not at high-risk, or, the Auditor will submit an audit proposal to JLAC for consideration. While audits conducted under the Program must be approved by JLAC, a recent opinion from Legislative Counsel has left room for interpretation whether current law authorizes the Program to include on-site reviews such as those performed during the initial assessment.
The author points out that it was the original intent of AB 187 to allow the Auditor to examine local governments while conducting the Program in order to accurately determine if there are any areas that are at risk of fraud, waste, or mismanagement.
This bill provides explicit direction that the Auditor may gather information from a local government agency during an initial assessment, as a way to avoid any room for additional interpretations of the statute.
Prior/Related Legislation
AB 2729 (Muratsuchi, 2018) sets approval requirements for audits under the Auditor’s high-risk local government agency audit program and allows the Auditor to limit or discontinue audit work. (Pending in the Assembly Accountability and Administrative Review Committee)
AB 2822 (Obernolte, 2018) authorizes the Auditor to use publicly available information when identifying local government agencies that are high-risk under the Auditor’s high-risk local government agency program. (Pending on the Assembly Floor)
AB 32 (Rodriguez, Chapter 606, Statutes of 2017) set a recruitment process for Auditor candidates by requiring JLAC to conduct a comprehensive search before it selects three qualified individuals for the position to be forwarded to the Governor to appoint one of the three as the Auditor.
SB 187 (Lara, Chapter 451, Statutes of 2011) authorized the Auditor to establish a Program to identify, audit, and issue reports on any local government agency, including any city, county, or special district.
SB 1437 (Speier, Chapter 251, Statutes of 2004) authorized the Auditor to establish a high-risk government agency audit program for the purpose of identifying, auditing, and issuing reports on any state agency that the Auditor identified as high-risk for the potential of waste, fraud, abuse, and mismanagement, or that has major challenges associated with its economy, efficiency, or effectiveness.
SB 37 (Maddy, Chapter 251, Statutes of 1993) created the Bureau of State Audits under the direction of the Little Hoover Commission, and moved many of the duties and powers of the Officer of Auditor General to the Bureau of State Audits.
FISCAL EFFECT: Appropriation: No Fiscal Com.: Yes Local: No
SUPPORT:
None received
OPPOSITION:
None received
Bill Co-Author(s):